
 Gaming Mouse Market | 2026-2036
Gaming Mouse Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Mouse Market Analysis
Buyer concentration among e-sports organizations and professional gaming houses is recalibrating procurement volumes toward bulk sensor calibration and uniform fleet deployments. Logitech sustains technology leadership through proprietary LIGHTSPEED wireless protocols and precision sensor ecosystems. Razer dominates enthusiast-grade peripheral ecosystems with deep software-hardware integration. SteelSeries competes through audio-visual peripheral bundling and tournament sponsorship density.
A gaming mouse is a human interface device engineered with sub-micron tracking resolution, typically between 100 and 30,000 dots per inch, utilizing optical or laser illumination paired with CMOS image correlation sensors to translate physical displacement into digital cursor positioning for competitive and recreational interactive software. Wireless connectivity segments are capturing margin pools as battery density and latency compression technologies mature, while wired configurations retain cost-sensitive casual gamer volume. E-sports player end-user demand concentrates in adjustable DPI and weight tuning feature sets where tournament regulations mandate hardware standardization.
FCC electromagnetic interference certification governs wireless transmission protocols in the United States, while China's GB standards enforce electromagnetic compatibility thresholds for peripheral electronics sold domestically. REACH substance restrictions in Europe constrain polymer and coating chemistries used in shell manufacturing and surface treatments. Stakeholders must monitor regulatory divergence between low-latency wireless frequency allocations and material compliance deadlines to preserve cross-border product continuity.
Market Dynamics
E-sports procurement consolidation is compressing vendor margins while demanding fleet-standardized sensor calibration protocols across professional gaming houses.
Growth Catalysts
- LIGHTSPEED wireless protocol maturation:Sub-millisecond latency compression is displacing wired configurations in tournament environments. Battery density improvements enable multi-day competitive use without recharge cycles.
- REACH substance compliance evolution:European coating chemistry restrictions are accelerating shell material innovation toward bio-based polymers. Manufacturers retooling production lines capture premium positioning in sustainability-conscious segments.
- Seoul-Incheon hardware cluster concentration:South Korea's integrated peripheral ecosystem reduces sensor-to-assembly logistics costs. Proximity to professional league headquarters enables rapid prototype-to-tournament feedback loops.
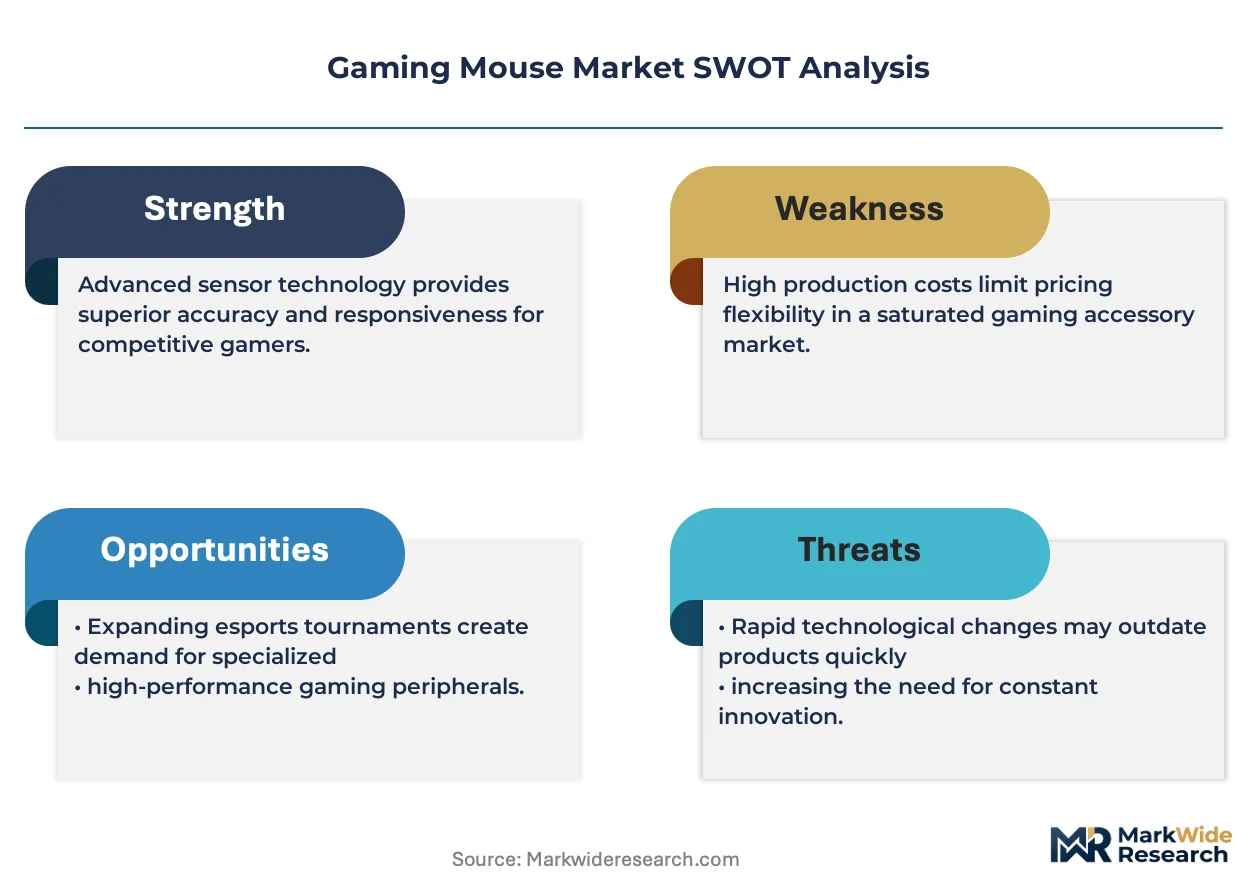
Market Restraints
- CMOS sensor supply concentration:Three Asian foundries control high-precision image correlation chip fabrication. Geographic concentration creates vulnerability to foundry allocation disruptions.
- FCC electromagnetic interference certification costs:Wireless protocol testing protocols require six-figure validation cycles per frequency variant. Small manufacturers face barrier-to-entry pressure from compliance overhead.
- Optical tracking substitution threat:Camera-based hand-tracking systems in VR headsets reduce dependency on physical peripherals. Early-stage displacement visible in immersive simulation segments.
Strategic Opportunities
- India's emerging e-sports infrastructure:Untapped professional league formation creates first-mover advantage for localized peripheral distribution. BIS certification pathways remain underutilized by incumbent brands.
- AI-driven predictive click analytics:Convergence of onboard edge computing and machine learning enables real-time performance coaching features. Tournament-legal implementations differentiate enthusiast-grade offerings.
- Direct-to-team subscription models:Hardware-as-a-service contracts with professional gaming houses replace transactional procurement. Recurring revenue streams stabilize manufacturer cash flow visibility.
Industry Challenges
- Firmware security certification complexity:Tournament anti-cheat integration requires continuous validation against evolving cheat detection protocols. Engineering resources divert from feature development to compliance maintenance.
- Cross-platform driver standardization delays:Console manufacturer SDK fragmentation forces redundant development cycles. Unified peripheral control layers remain unrealized despite industry consortium efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Mouse Market |
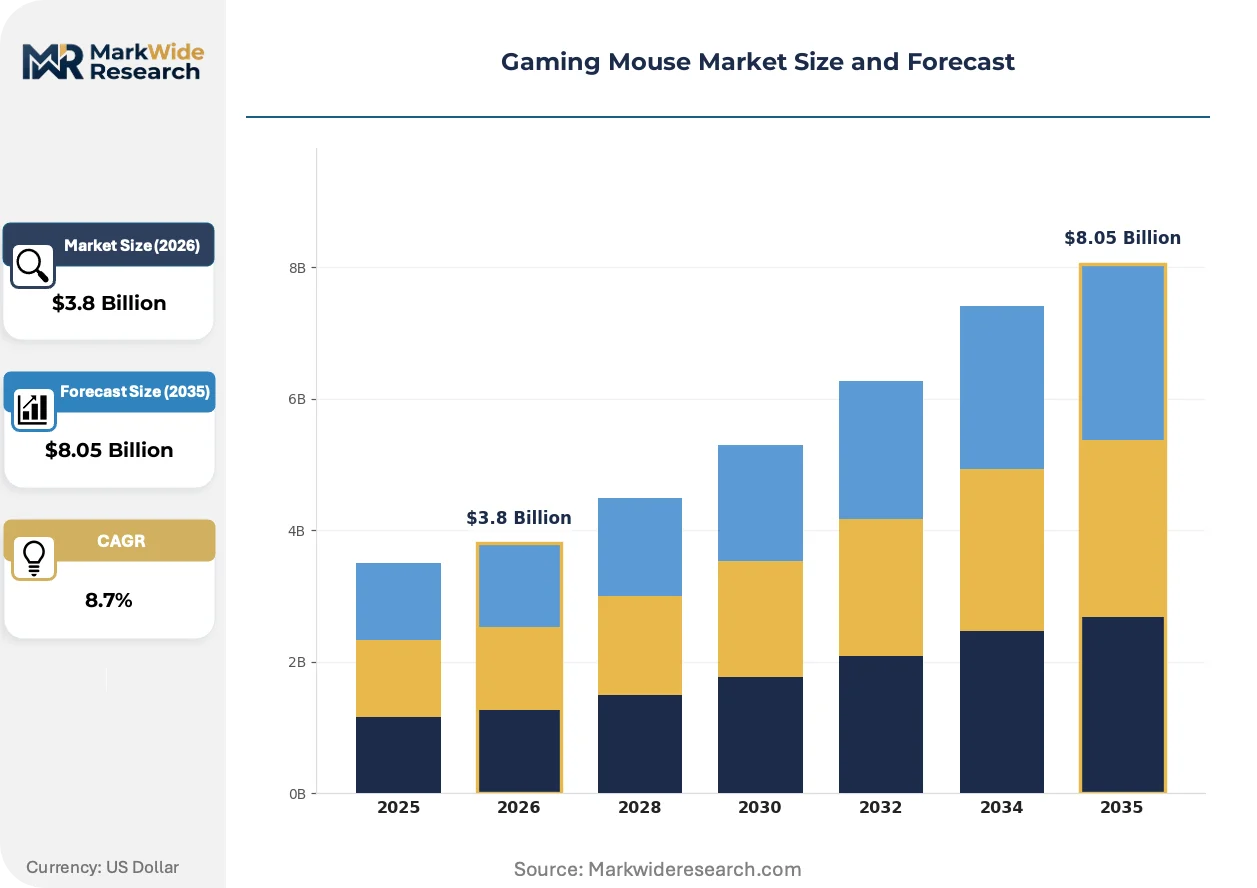
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Ergonomic, Ambidextrous Technology: Optical, Laser, Hybrid, Gaming Sensors End User: Casual Gamers, Professional Gamers, Streamers, E-Sports Players Feature: Customizable RGB Lighting, Programmable Buttons, Adjustable DPI, Weight Tuning |
| Companies Covered | SteelSeries, ASUS, Logitech, Lamzu, Finalmouse, Razer, Zowie, Pulsar, Corsair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Mouse Market Emerging Trajectories
Sensor architecture, wireless transmission standards, and procurement contracting models are simultaneously evolving, creating discontinuities in established competitive positioning.
Optical sensor assemblies with swappable lens configurations are modularizing across enthusiast product lines. Professional gaming houses now specify base sensor modules with interchangeable DPI ceiling variants for different game genre requirements. This architecture compresses inventory carrying costs while enabling rapid tournament regulation compliance adjustments.
China's GB electromagnetic compatibility standards are tightening shielding requirements for wireless peripherals sold domestically. Manufacturers face retooling investments for ferrite core integration and PCB layout modifications. Products failing pre-certification testing face six-month market entry delays, disadvantaging brands without Shanghai or Shenzhen validation laboratory partnerships.
Team procurement officers now negotiate multi-year fleet replacement contracts with embedded sensor calibration services. Traditional retail channel volumes fragment as direct manufacturer relationships capture professional and semi-professional segments. This concentration is most visible in Denmark and Sweden, where organized e-sports club structures dominate hardware acquisition decisions.
Gaming Mouse Market Segmentation
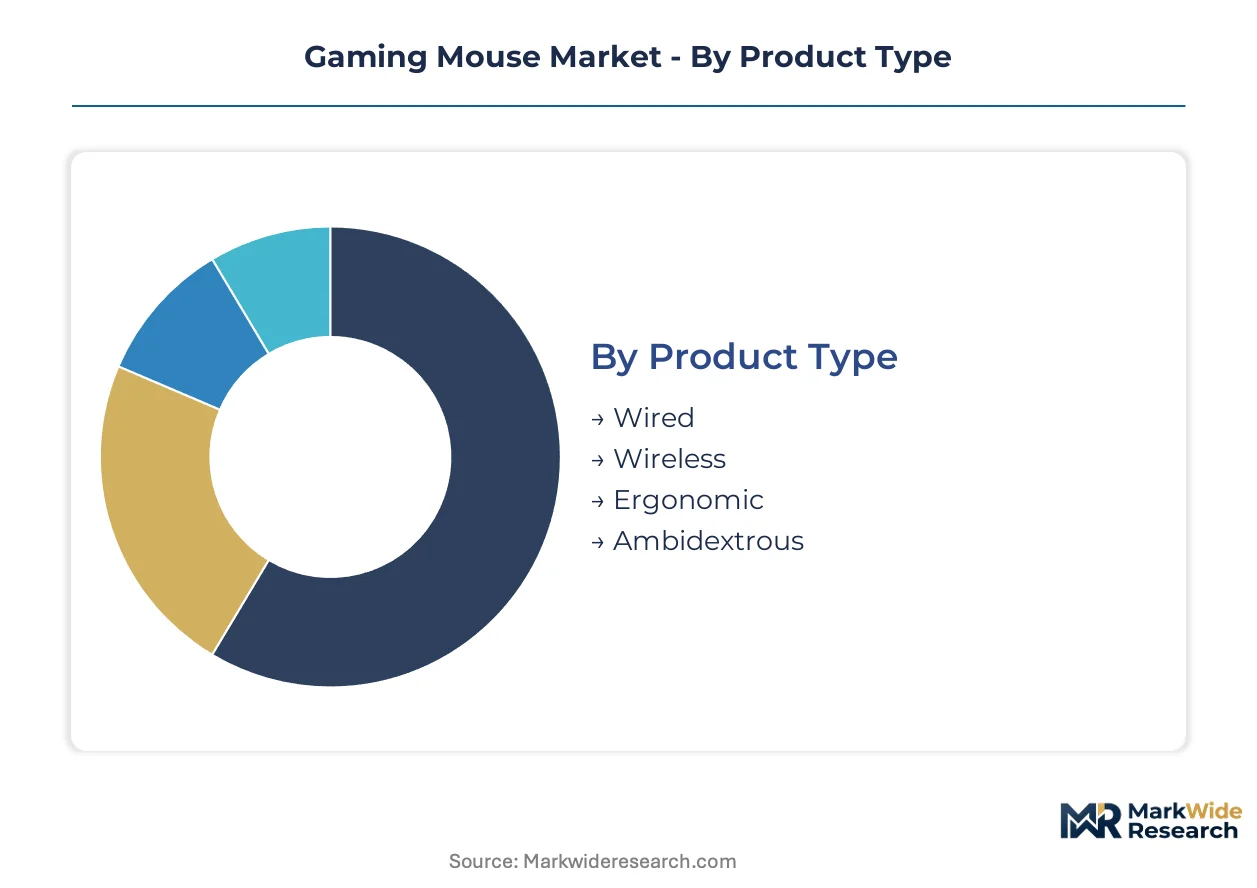
Gaming mouse segmentation reflects divergent performance requirements across competitive intensity levels. Procurement patterns split between standardized fleet deployments and individualized enthusiast configurations.
Product Type:
Form factor and connectivity architecture define baseline performance envelopes and use-case suitability.
- Wireless:LIGHTSPEED and comparable low-latency protocols achieve sub-millisecond transmission benchmarks. Tournament regulations in South Korea and Denmark now permit certified wireless configurations, displacing wired dominance in professional environments where cable drag affects micro-adjustment precision.
- Wired:USB-C and braided cable constructions retain cost-sensitive casual gamer volume. USB polling rate standardization at 1000Hz maintains baseline responsiveness without wireless certification overhead.
- Ergonomic:Right-handed sculpted shells with thumb rests reduce fatigue during extended sessions. Palm-grip and claw-grip variants target hand-size demographics.
- Ambidextrous:Symmetrical shell geometry accommodates left-handed users and fingertip-grip styles. Mirror-button layouts enable true ambidextrous mapping without software workarounds.
Wireless leads on scale; ergonomic leads on momentum as hand-health awareness penetrates enthusiast segments.
Technology:
Illumination and image correlation methods determine tracking fidelity across surface materials.
- Optical:LED-illuminated CMOS sensors dominate through surface adaptability and power efficiency. PixArt and comparable sensor vendors supply 16,000+ DPI variants to mainstream manufacturers.
- Gaming Sensors:Proprietary co-developed architectures such as Logitech's HERO and Razer's Focus Pro enable custom power-performance curves. Tournament-grade calibration protocols require factory-line variance below one percent.
- Laser:Infrared illumination penetrates glossy surfaces where optical tracking fails. Higher power draw limits wireless implementation.
- Hybrid:Dual-mode switching between optical and laser illumination adapts to surface transitions. Niche positioning in multi-environment professional use.
Optical dominates volume deployment; gaming sensors command premium positioning through calibration exclusivity.
End User:
Skill level and revenue model determine feature prioritization and procurement channel.
- E-Sports Players:Hardware standardization mandates from league operators drive fleet procurement. Organizations in Sweden and Denmark negotiate direct manufacturer contracts with embedded sensor calibration services.
- Professional Gamers:Individual sponsorship arrangements provide early access to prototype hardware. Streaming visibility requirements prioritize aesthetic customization alongside performance.
- Streamers:RGB synchronization with broadcast overlays creates content-creation differentiation. OBS Studio integration and lighting effect programmability outweigh pure tracking specifications.
- Casual Gamers:Retail channel price sensitivity favors feature-bundled SKUs. Adjustable DPI and basic programmable buttons satisfy mainstream interactive software demands.
E-Sports Players concentrate procurement volume; Streamers expand most quickly as content creation professionalizes.
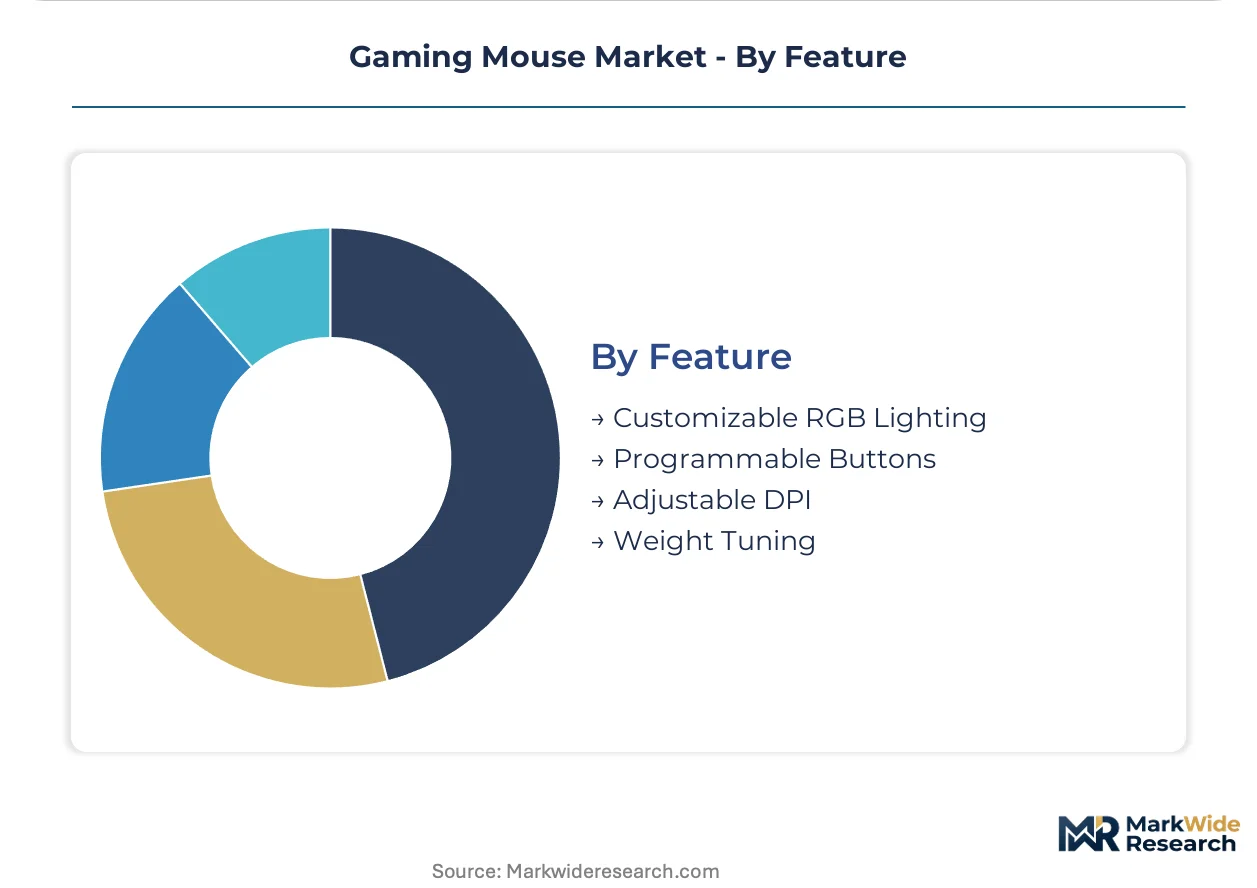
Feature:
Customizability depth separates enthusiast-grade positioning from mass-market commoditization.
- Adjustable DPI:On-the-fly sensitivity switching enables genre-appropriate configuration. Tournament regulations cap maximum DPI to prevent sensor interpolation artifacts.
- Programmable Buttons:Onboard memory stores macro configurations independent of driver software. MOBA and MMO genres demand 12+ button arrays.
- Weight Tuning:Modular gram-scale adjustment systems accommodate flick-shot versus tracking preferences. Professional gaming houses specify fleet-standardized weight configurations.
- Customizable RGB Lighting:16.8 million color addressability and effect synchronization across peripheral ecosystems. Manufacturer-specific software platforms create switching costs.
Adjustable DPI leads on scale; Weight Tuning gains share fastest as tournament standardization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's peripheral manufacturing base dwarfs South Korea's specialized e-sports hardware cluster in unit volume, yet Seoul-Incheon commands premium pricing through tournament-proximity calibration services.
China
Domestic e-sports league expansion and live-streaming platform monetization drive hardware refresh cycles. GB standards from the State Administration for Market Regulation enforce electromagnetic compatibility thresholds for wireless peripherals. Shenzhen and Dongguan host integrated PCB-to-assembly operations serving global OEM contracts.
South Korea
Professional league standardization mandates and team house procurement consolidation concentrate demand. The Ministry of Trade, Industry and Energy oversees radio frequency allocations for low-latency wireless protocols. Seoul-Incheon corridor manufacturers maintain validation laboratory partnerships for rapid tournament certification.
United States
Content creator economy professionalization and Twitch-integrated peripheral ecosystems sustain replacement demand. FCC electromagnetic interference certification governs wireless transmission protocol approvals. Los Angeles and Austin clusters anchor influencer marketing and esports franchise headquarters procurement.
Denmark
Organized club structures and team house network density create fleet-standardized procurement pools. REACH substance restrictions from the European Chemicals Agency constrain coating chemistry formulations. Copenhagen-Aarhus corridor hosts concentrated professional gaming organization headquarters negotiating direct manufacturer contracts.
Sweden
Tournament infrastructure investment and player union formation institutionalize hardware standardization requirements. CE marking directives enforce electrical safety and electromagnetic compatibility for peripheral imports. Stockholm anchors Nordic esports federation procurement coordination and sensor calibration service contracts.
Gaming Mouse Market Vendor Landscape
Chinese producers anchor the scale-driven tier; Danish and American specialists hold enthusiast-grade positioning through software-hardware integration. The vendor base stratifies across three functional tiers: integrated peripheral ecosystem providers, precision sensor technology licensors, and tournament-focused calibration service operators. Consolidation pressure concentrates among mid-scale fabricators lacking proprietary wireless protocol stacks or direct team procurement relationships. Dominant competitive moves include sensor architecture licensing partnerships and direct-to-team subscription contract expansion.
Within the integrated ecosystem tier, Logitech and Razer exemplify divergent strategic positioning. Logitech anchors premium wireless protocol development through proprietary transmission technology. Razer occupies enthusiast-grade positioning through deep software-hardware integration and RGB synchronization platforms. SteelSeries represents tournament-focused calibration service bundling alongside audio-visual peripheral packaging.
| Leading Market Players |
|---|
| SteelSeries |
| ASUS |
| Logitech |
| Lamzu |
| Finalmouse |
| Razer |
| Zowie |
| Pulsar |
| Corsair |
| Others |
Supply Flow & Price Mechanics
Fleet-standardized procurement from Denmark's professional gaming houses is compressing vendor margins while demanding embedded sensor calibration services, forcing manufacturers to absorb certification costs or cede volume to direct-contract competitors with Shenzhen laboratory partnerships.
Pricing Analysis
Capacity additions in Dongguan and Shenzhen are reshaping price floors for wired peripheral SKUs serving casual gamer segments. Three-tier pricing structure across enthusiast, professional, and entry levels separates tournament-grade calibration bundles from retail-channel commodity units. Cost compression in entry-tier wireless SKUs is intensifying because GB electromagnetic compatibility retooling investments must be recovered across thinner volume bases. Casual gamers exhibit highest price sensitivity, while e-sports organizations prioritize total-cost-of-ownership including fleet maintenance and calibration.
Supply Chain Analysis
Refurbishment flows for tournament-returned peripherals create secondary supply channels in Seoul-Incheon and Copenhagen-Aarhus corridors. Component sourcing draws from Taiwan and South Korea for CMOS sensors, China for PCB assemblies, and Vietnam for cable and shell molding. Single-source vulnerability concentrates in high-precision image correlation chip fabrication. Distribution runs through direct manufacturer contracts with professional gaming houses, bypassing traditional retail for fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on battery density improvements reducing wireless BOM costs and enthusiast-tier willingness to pay for AI-driven predictive analytics features.
For Market Incumbents: Cement proprietary wireless protocol advantages through expanded Seoul-Incheon validation laboratory partnerships before China's GB electromagnetic compatibility deadlines close. Defend against optical tracking substitution in VR-adjacent segments by accelerating onboard edge computing feature roadmaps. Deepen backward integration into sensor module calibration to preserve margin on fleet-standardized contracts.
For New Entrants and Emerging Players: Begin with India's underutilized BIS certification pathways and emerging professional league infrastructure where incumbent direct-contract relationships remain unformed. Target streamer segments requiring OBS Studio-integrated RGB ecosystems rather than tournament-grade tracking specifications. Pursue hardware-as-a-service subscription models with nascent team houses seeking to convert capital expenditure to operational expenditure.
For Investors and Strategic Acquirers: Asymmetric upside sits with calibration service operators and sensor architecture licensors lacking captive peripheral brands. Long-term viability across the projection horizon favors asset-light technology licensors over capital-intensive assembly operations. Watch FCC electromagnetic interference certification backlog duration as inflection indicator for wireless peripheral market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Team Subscription Model | Recurring revenue stabilizes cash flow visibility against retail channel fragmentation. |
| Sensor Architecture Licensing Partnership | Technology licensors capture margin without Shenzhen assembly capital intensity. |
| GB Electromagnetic Compatibility Pre-Certification | Shanghai laboratory partnerships compress six-month market entry delays. |
| AI-Driven Predictive Click Analytics Integration | Onboard edge computing differentiates enthusiast-grade from commodity positioning. |
| Reverse Logistics Refurbishment Program | Tournament-returned peripheral flows extend asset life in secondary markets. |
Methodological Framework
Multiple input streams — executive interviews, procurement officer surveys, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork encompassed peripheral OEM product managers, professional gaming house procurement leads, e-sports league operations directors, and sensor foundry technical sales engineers. Secondary validation drew from FCC equipment authorization databases, China's SAMR GB standard disclosure filings, REACH substance restriction updates from ECHA, and customs trade flow records. Bottom-up SKU volume aggregation and top-down category spend analysis were cross-referenced for triangulation.
Historical shipment trajectories were cross-referenced against panel-based forward estimates across the analysis window. Segmentation dimensions modeled include connectivity architecture, illumination technology, end-user skill tier, and regional regulatory cluster. CAGRs were derived from slope-consistent growth trajectory fitting rather than endpoint anchoring. Forecast inputs incorporated battery energy density improvement curves and tournament regulation adoption timelines for wireless protocol permissibility.
Several conditions sit outside the modeled scope, including unforeseen electromagnetic spectrum reallocation decisions, abrupt REACH substance restriction expansions, and VR hand-tracking technology performance breakthroughs. Forecasts reflect documented assumptions regarding professional league formation rates and team house procurement consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Gaming Phone Market
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Ereader Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Headphones Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
True Wireless Stereo Earbuds Market