
 Europe Soundbar Market | 2026-2036
Europe Soundbar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Soundbar Market Intelligence
European consumer electronics manufacturing is pivoting toward higher-margin audio products as flat-panel TV margins compress. Samsung Electronics leverages its semiconductor foundry relationships to captive-source DSP chipsets for its soundbar lineup. LG Electronics anchors its position through vertical integration into display-audio bundles sold through major European retail chains. Yamaha Corporation differentiates via acoustic engineering heritage and dedicated AV receiver compatibility.
A soundbar is a loudspeaker enclosure containing multiple drivers in a single elongated cabinet, typically integrating amplifiers, signal processing, and wireless connectivity within a form factor designed for placement beneath or near a television display. Units range from compact 2.1 channel configurations with dedicated wireless subwoofers to immersive soundbar systems incorporating upward-firing height channels for object-based audio rendering. Wireless soundbar systems lead European volume shipments by eliminating cabling complexity in rental apartments and renovated urban dwellings. Dolby Atmos-enabled immersive soundbar models command disproportionate margin contribution as consumers upgrade from basic 2.1 channel systems. HDMI ARC connectivity has become a baseline expectation, with eARC extension gaining traction among audio professionals and home theater enthusiasts seeking uncompressed multichannel bitstream passthrough.
The EU Ecodesign Directive and CE marking requirements enforce standby power consumption ceilings and electromagnetic compatibility standards that shape product development roadmaps for brands serving the European Economic Area. REACH compliance constrains material selection for enclosures, adhesives, and flame-retardant components used in soundbar construction. Germany's national regulator, the Federal Network Agency, coordinates spectrum allocation for wireless audio transmission protocols including Bluetooth and Wi-Fi. Stakeholders must monitor evolving EU right-to-repair legislation and digital product passport requirements that will reshape supply chain documentation obligations and aftermarket service economics.
Market Dynamics
The EU Ecodesign Directive's tightening standby power limits are forcing manufacturers to redesign power management circuits across their entire European product portfolios, compressing margins while accelerating R&D cycles for compliant architectures.
Growth Catalysts
- Dolby Atmos Immersion:Object-based audio rendering is pulling consumers away from basic 2.1 channel systems toward height-enabled soundbars. Living-room entertainment upgrades in Germany's premium retail corridor concentrate this demand.
- REACH Compliance:Material constraints on enclosures and flame-retardant components are filtering out non-compliant imports, creating protected market space for certified manufacturers serving the European Economic Area.
- Wireless Connectivity:Bluetooth and Wi-Fi transmission protocols eliminate cabling complexity in rental apartments and renovated urban dwellings across France and the United Kingdom.
Market Restraints
- Semiconductor Supply Concentration:DSP chipset sourcing depends on captive foundry relationships controlled by integrated electronics conglomerates, limiting independent audio specialists' procurement flexibility.
- Substrate Cost Volatility:Enclosure materials face price pressure from REACH-constrained adhesive and flame-retardant supply chains, squeezing bill-of-materials predictability.
- HDMI Standard Fragmentation:The gap between baseline ARC and uncompressed eARC passthrough creates consumer confusion and inventory complexity for retailers stocking mixed connectivity tiers.
Strategic Opportunities
- Right-to-Repair Legislation:Evolving EU digital product passport requirements will reshape aftermarket service economics, creating documentation and spare-parts revenue streams for prepared manufacturers.
- Display-Audio Convergence:Bundling soundbars with flat-panel televisions through major retail chains captures margin that standalone audio sales cannot access.
- Poland and Eastern Europe:Underpenetrated premium audio markets present white-space expansion potential as disposable income growth outpaces saturated Western European corridors.
Industry Challenges
- Acoustic Engineering Talent Scarcity:The intersection of DSP programming and physical driver tuning requires specialized skill sets concentrated in legacy audio manufacturing regions.
- CE Marking Timeline Compression:Electromagnetic compatibility certification cycles must accelerate to match seasonal retail stocking windows, straining testing laboratory capacity.
- Legacy AV Receiver Integration:Dedicated compatibility requirements for existing home theater infrastructure complicate firmware development and support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Soundbar Market |
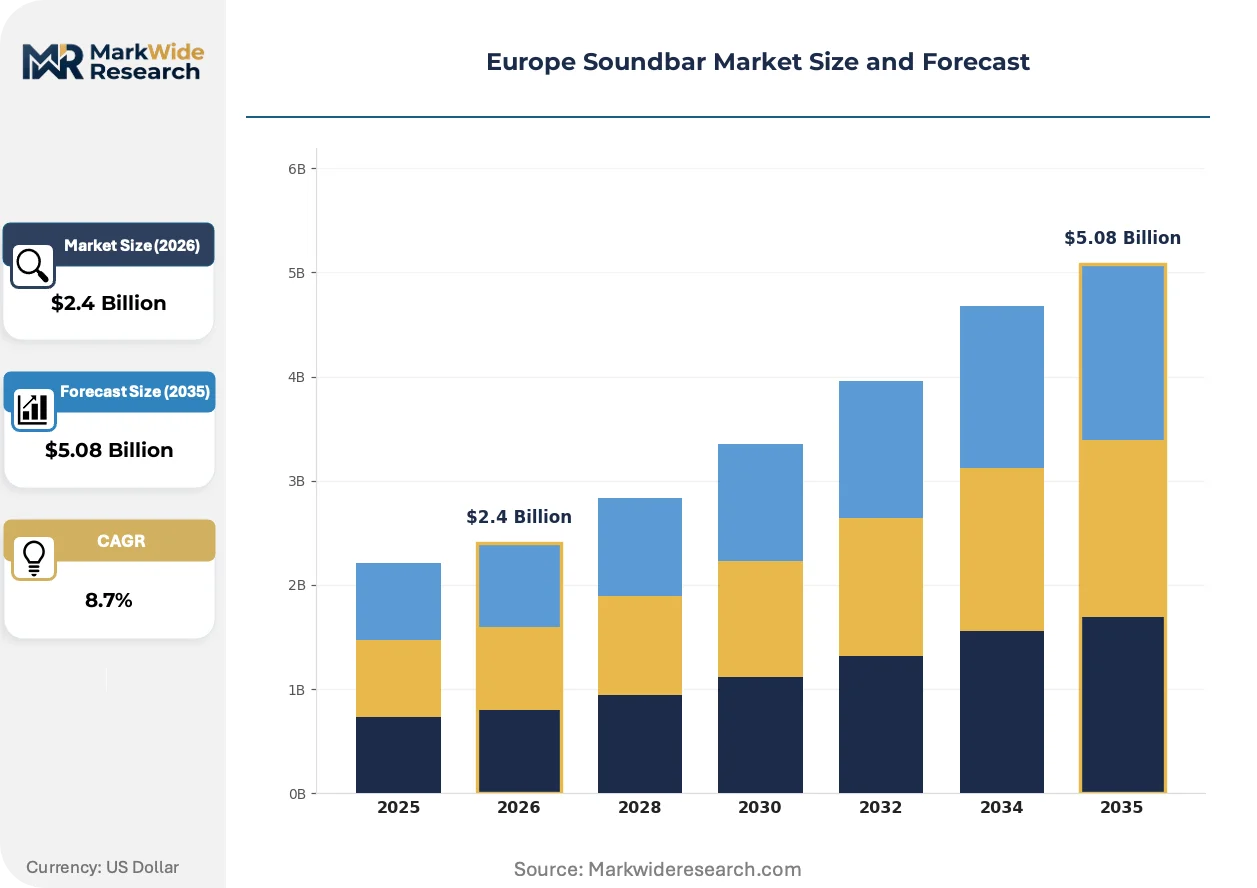
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2.1 Channel, 3.1 Channel, 5.1 Channel, Immersive Soundbar, Wireless Soundbar Technology: Dolby Atmos, DTS:X, Bluetooth, Wi-Fi, HDMI ARC, USB Connectivity Application: Home Theater, Gaming Setup, Streaming Services, Corporate Audio, Educational Use, Personal Entertainment Customer Type: Retail Consumers, Audio Professionals, Hospitality Providers, Educational Institutions, Event Organizers |
| Companies Covered | LG Electronics, Yamaha Corporation, Samsung Electronics, Xiaomi Corporation, Panasonic Holdings Corporation, Sony Corporation, Koninklijke Philips, Intex Technologies, Bose Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Soundbar Market Strategic Shifts & Innovations
Audio rendering architectures and connectivity standards are converging to reshape how European consumers configure living-room entertainment systems, with implications for manufacturing roadmaps and retail assortment planning.
Upward-firing height channel drivers are overtaking traditional horizontal-only soundbar configurations as the default architecture for mid-tier and premium segments. Home theater enthusiasts in Germany and the United Kingdom are specifying these units for object-based audio reproduction. This shift is compressing demand for basic 2.1 channel systems while expanding addressable margin pools for immersive-capable manufacturers.
CE marking requirements under the EU Ecodesign Directive are enforcing standby power consumption ceilings that reshape product development roadmaps. Electromagnetic compatibility testing obligations now consume larger portions of pre-launch timelines. Audio specialists serving France and the Benelux markets are responding by consolidating power management circuit designs across multiple SKU tiers.
Rental apartment dwellers are prioritizing wireless subwoofer configurations that eliminate floor-cable runs in renovated urban dwellings. Specialist audio retailers in Paris and Berlin report stronger attachment rates for fully wireless systems versus wired alternatives. This consumption-pattern shift is most visible in metropolitan France and Western Germany where housing stock renovation rates exceed Southern European benchmarks.
Europe Soundbar Market Segmentation
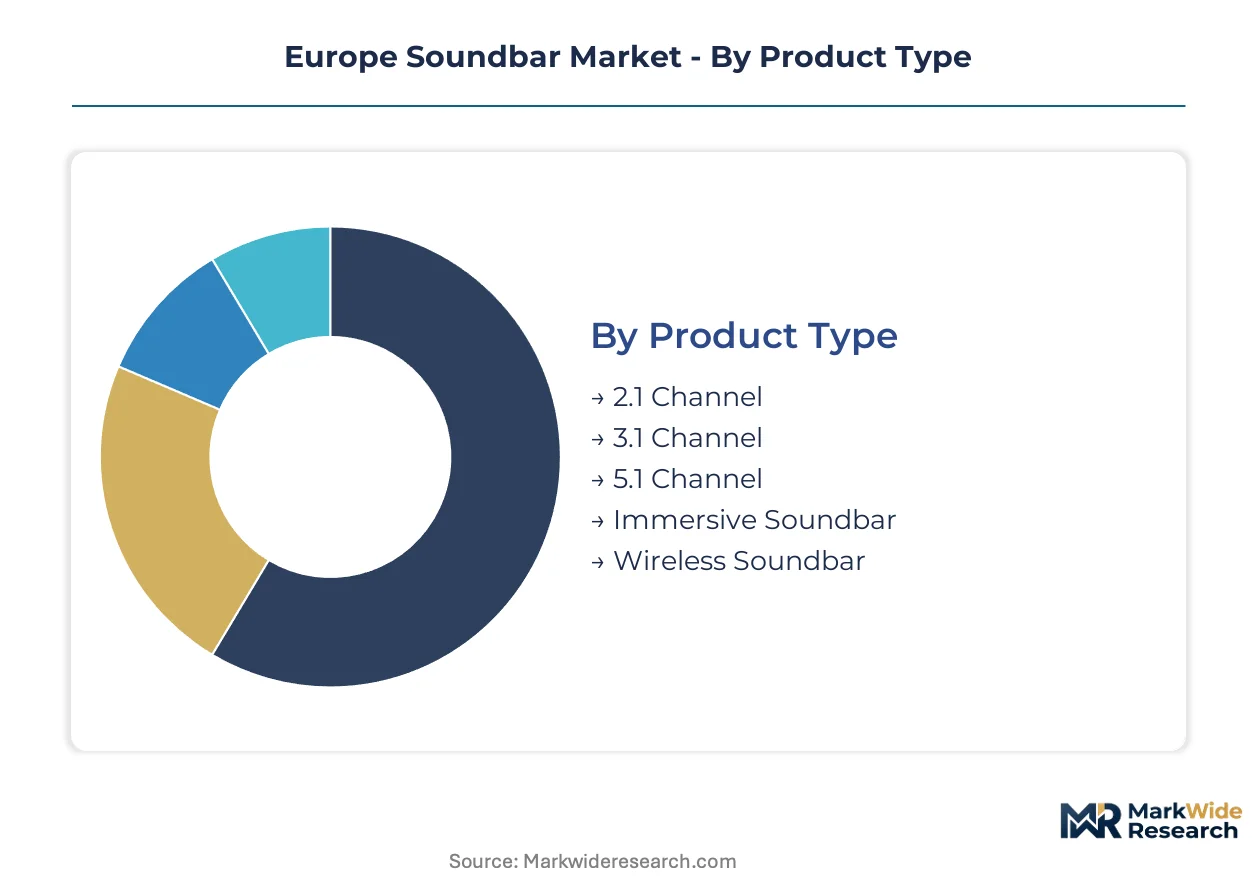
Soundbar manufacturers must align product architectures with distinct usage contexts across European living spaces. Channel configurations, audio codecs, and connectivity suites each command different margin profiles and certification burdens under EU Ecodesign Directive compliance frameworks.
Product Type:
Standardization dominates entry-level tiers while premium segments demand acoustic customization for room-specific immersion.
- Immersive Soundbar:Upward-firing height channels enable object-based audio rendering through Dolby Atmos and DTS:X decoding. German premium retail corridors concentrate demand as consumers upgrade flat-panel television installations with three-dimensional sound fields.
- Wireless Soundbar:Elimination of cabling between main enclosure and subwoofer modules suits rental apartments and renovated urban dwellings across France and the United Kingdom. Bluetooth and Wi-Fi transmission protocols reduce installation friction for non-technical users.
- 2.1 Channel:Compact configurations with dedicated low-frequency drivers serve budget-conscious consumers in Poland and Eastern European markets.
- 3.1 Channel:Center-channel dialogue clarity targets streaming service viewers prioritizing vocal intelligibility over surround immersion.
- 5.1 Channel:Discrete rear satellite compatibility appeals to home theater enthusiasts maintaining legacy speaker investments.
Leading the category by volume: Wireless Soundbar. Expanding most quickly: Immersive Soundbar.
Technology:
Codec licensing costs and connectivity standard adoption curves segment the supply base by R&D investment capacity.
- Dolby Atmos:Object-based metadata rendering requires DSP chipsets with height-channel virtualization capabilities. Samsung Electronics and LG Electronics leverage captive semiconductor sourcing to absorb licensing overhead that constrains independent audio specialists.
- HDMI ARC:Audio Return Channel connectivity has displaced optical TOSLINK as the baseline expectation for television integration. Retailers in the United Kingdom report inventory complexity from mixed ARC and eARC capability tiers.
- DTS:X:Alternative immersive codec provides competitive differentiation for Yamaha Corporation's AV receiver-compatible soundbar lineup.
- Bluetooth:Short-range wireless protocol dominates mobile device pairing scenarios for personal entertainment use.
- Wi-Fi:Whole-home audio synchronization and high-resolution streaming support command premium positioning.
- USB Connectivity:Firmware update pathways and local media playback satisfy enthusiast segments requiring physical interface assurance.
Dolby Atmos captures margin leadership. HDMI ARC anchors volume penetration.
Application:
Residential installation types concentrate demand while commercial verticals impose divergent durability and service requirements.
- Home Theater:Living-room entertainment system upgrades drive premium soundbar attachment to flat-panel television sales through major European retail chains. Germany's consumer electronics retail corridor concentrates this demand with Dolby Atmos-enabled bundle configurations.
- Gaming Setup:Low-latency audio processing and spatial positioning accuracy attract console and PC gaming enthusiasts. HDMI eARC passthrough requirements complicate inventory planning for specialty retailers serving this segment.
- Streaming Services:Dialogue enhancement and night-mode compression algorithms target apartment dwellers consuming subscription video content.
- Corporate Audio:Conference room installations prioritize microphone array integration and unified communications platform certification.
- Educational Use:Classroom durability requirements and institutional procurement cycles favor standardized 2.1 channel configurations.
- Personal Entertainment:Desktop and bedroom secondary television setups drive compact form factor demand.
Home Theater dominates revenue contribution. Gaming Setup shows steepest expansion trajectory.
Customer Type:
Procurement sophistication varies sharply between mass-market retail and professional specification channels.
- Retail Consumers:Mass-market purchasers rely on in-store demonstration and bundle pricing through major European electronics retail chains. CE marking visibility and energy efficiency labeling influence selection criteria under EU Ecodesign Directive awareness campaigns.
- Audio Professionals:Post-production studios and broadcast facilities demand calibrated frequency response and reference-grade connectivity. Yamaha Corporation's acoustic engineering heritage anchors specification in this segment.
- Hospitality Providers:Hotel and restaurant installations prioritize discrete form factors and centralized control system integration.
- Educational Institutions:Public procurement frameworks in France and Germany impose documentation and warranty requirements that filter supplier eligibility.
- Event Organizers:Temporary installation portability and rapid deployment compatibility drive rental market specifications.
Retail Consumers generate unit volume leadership. Audio Professionals command pricing premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Dresden and Leuven anchors European DSP chipset sourcing for soundbar manufacturers serving the regional market. Premium audio retail corridors concentrate demand in Germany, France, and the United Kingdom. Regulatory pressure from the EU Ecodesign Directive shapes product development timelines across all member states.
Germany
Dolby Atmos-enabled immersive soundbars drive living-room entertainment upgrades in Berlin and Munich's premium retail corridors. The Federal Network Agency coordinates spectrum allocation for Bluetooth and Wi-Fi transmission protocols. Bavaria's consumer electronics manufacturing cluster houses acoustic engineering facilities tuning driver arrays for height-channel configurations.
France
Wireless soundbar systems dominate Parisian rental apartment installations where cabling complexity deters renovation. ANSM and CNIL oversight extends to electromagnetic compatibility certification under CE marking requirements. The Île-de-France region concentrates specialist audio retailers reporting stronger attachment rates for fully wireless subwoofer configurations.
United Kingdom
HDMI eARC passthrough demand from home theater enthusiasts complicates inventory planning for London-based specialty retailers. Ofcom spectrum management intersects with EU Ecodesign Directive standby power limits. The Southeast England logistics corridor distributes bundled display-audio configurations through major retail chains.
Poland
Budget-conscious consumers in Warsaw and Kraków drive 2.1 channel soundbar volume for secondary television setups. The country's national regulator enforces REACH compliance on imported electronics, filtering non-certified manufacturers. Silesia's emerging consumer electronics assembly footprint serves underpenetrated Eastern European premium audio demand.
Netherlands
Rotterdam's port logistics hub channels REACH-compliant component imports for Benelux distribution networks. The Dutch national regulator implements EU right-to-repair legislation previewing documentation obligations. Randstad metropolitan consumers prioritize compact form factors for renovated urban dwellings with space constraints.
Europe Soundbar Market Key Industry Players
Global majors compete with regional champions across semiconductor sourcing and acoustic engineering capabilities. Samsung Electronics and LG Electronics leverage captive foundry relationships to control DSP chipset procurement, while Yamaha Corporation and Bose Corporation anchor premium positioning through heritage audio engineering. The vendor base separates into three strategic archetypes: integrated electronics conglomerates, dedicated audio specialists, and value-oriented consumer electronics assemblers. Competitive moves concentrate on display-audio bundle partnerships with major retail chains and backward integration into amplifier module production.
Within the integrated conglomerate tier, Samsung Electronics and LG Electronics exemplify scale-driven positioning through in-house semiconductor production and vertical control over display panel supply chains. Yamaha Corporation occupies a specialist position representing acoustic engineering heritage and dedicated AV receiver compatibility. These three anchors illustrate how procurement flexibility and brand positioning separate competitive outcomes in a market where REACH compliance and CE marking requirements filter supplier eligibility.
| Leading Market Players |
|---|
| LG Electronics |
| Yamaha Corporation |
| Samsung Electronics |
| Xiaomi Corporation |
| Panasonic Holdings Corporation |
| Sony Corporation |
| Koninklijke Philips |
| Intex Technologies |
| Bose Corporation |
| Others |
Cost & Logistics Intelligence
Acoustic engineering talent concentration in Bavaria and the Randstad region feeds labor-cost differentials that widen pricing-tier spreads between premium immersive soundbars and economy 2.1 channel units. Manufacturers absorb REACH compliance certification overhead into premium-tier pricing while compressing margins on entry-level SKUs destined for Eastern European markets.
Pricing Analysis
Warranty and service bundling separates premium-tier immersive soundbars from unbundled economy configurations sold through mass retail. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by Dolby Atmos certification grade and after-sales service inclusion. Price erosion runs through entry-level tiers as Chinese assemblers flood Poland and Romania with non-certified imports. Budget-conscious retail consumers in Eastern Europe exhibit highest price sensitivity, while audio professionals in Germany's post-production corridor demonstrate lowest sensitivity to sticker premiums.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing remain underdeveloped across European soundbar distribution, limiting circular economy participation. Semiconductor sourcing draws from Taiwan, South Korea, and Germany's Dresden foundry cluster for DSP chipset fabrication. Enclosure production rests on ABS polymer and flame-retardant adhesive supply chains constrained by REACH substance restrictions. Single-source vulnerability in height-channel driver arrays sourced from Japanese acoustic component specialists threatens premium-tier production continuity. Distribution runs through Rotterdam's port hub into Benelux consolidation centers serving major retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity allocation for automotive and AI applications constrains DSP chipset availability, propping pricing power for manufacturers with captive semiconductor relationships.
For Market Incumbents: To counter margin compression from REACH compliance overhead, Samsung Electronics and LG Electronics should deepen backward integration into amplifier module production and consolidate power management circuit designs across multiple SKU tiers to amortize certification costs. Channel control through exclusive display-audio bundle partnerships with major European retail chains anchors volume retention against emerging entrants. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer lower customer acquisition costs than retail slotting fees for unbranded assemblers targeting Poland and Romania's underpenetrated premium audio segments. White-space expansion should concentrate on wireless immersive soundbars for renovated urban dwellings in Warsaw and Kraków, leveraging e-commerce platforms to bypass established retail gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with acoustic engineering specialists possessing dedicated AV receiver compatibility and heritage tuning capabilities, given Dolby Atmos codec licensing as catalyst for margin expansion. Long-term viability across a decade horizon favors targets with established CE marking documentation and spare-parts infrastructure aligned with EU right-to-repair trajectories. Practitioners should monitor Federal Network Agency spectrum reallocation proceedings for wireless audio transmission protocols as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amplifier Production | Captive supply of power management modules insulates margins from REACH-constrained component volatility. |
| Dolby Atmos Certification Investment | Codec licensing unlocks premium positioning in Germany's immersive audio retail corridor. |
| Direct-to-Consumer Digital Launch | E-commerce routes bypass slotting fees for entrants targeting Poland's underpenetrated segments. |
| Display-Audio Bundle Partnership | Retail chain exclusivity captures margin unattainable through standalone audio sales. |
| Right-to-Repair Infrastructure Buildout | Digital product passport readiness positions aftermarket service revenue streams under evolving EU legislation. |
Research Approach
Document review covered customs trade databases, EU Ecodesign Directive regulatory filings, and REACH substance restriction updates, complemented by interviews with acoustic engineering directors at Bavarian manufacturing facilities, procurement leads at major Benelux retail chains, and DSP chipset sourcing managers at integrated electronics conglomerates. Secondary validation drew from Federal Network Agency spectrum allocation records, CE marking certification databases, and flat-panel television shipment statistics. Bottom-up unit demand modeling triangulated against top-down consumer electronics spending forecasts.
Cross-referencing historical channel shipment patterns against panel input from audio retailer category managers anchored volume projections across the analysis window. Segmentation dimensions modeled encompassed channel configuration tiers, codec technology adoption curves, and residential versus commercial installation contexts. CAGRs derived from logistic diffusion curves fitted to immersive audio upgrade cycles, with explicit incorporation of EU Ecodesign Directive standby power limit phase-in schedules and REACH compliance timeline constraints.
The model holds under stable semiconductor foundry allocation and REACH substance restriction continuity; deviation in height-channel driver supply disruptions or right-to-repair legislative acceleration would shift volume trajectories. Forecasts reflect documented assumptions regarding codec licensing cost absorption and wireless protocol spectrum availability. Practitioners should monitor ECHA substance restriction proposals and Federal Network Agency Bluetooth spectrum proceedings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Personal Computer Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
Camera Case Market
Consumer Electronics
Keycap Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Wrist Dive Computer Market