
 Industrial Hearables Market | 2026-2036
Industrial Hearables Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hearables Market Intelligence
The EU Green Deal and its embedded industrial sustainability mandates is broadening the addressable market for energy-efficient communication headsets in European factories. Honeywell International Inc. leverages its integrated safety portfolio to cross-sell hearables alongside gas detection and respiratory equipment. 3M anchors the high-volume disposable segment through deep distribution into construction supply chains. Sensear Pty Ltd differentiates via proprietary SENS technology that isolates speech while suppressing hazardous ambient noise in mining environments.
Industrial hearables are wearable audio devices engineered to deliver hearing protection above 85 dB while enabling two-way voice communication, typically incorporating noise-canceling microphones, Bluetooth 5.0+ connectivity, and lithium-polymer batteries rated for full-shift operation. Their primary purpose is preventing occupational noise-induced hearing loss without isolating workers from situational awareness or coordination. Bone conduction variants command premium positioning in heavy manufacturing where traditional seals fail under hard-hat pressure, while in-ear systems with smart features represent the fastest-expanding margin pool as facilities integrate biometric monitoring and geolocation tracking into unified worker safety platforms.
OSHA enforces permissible exposure limits under 29 CFR 1910.95, compelling employers to implement hearing conservation programs that increasingly specify connected protection devices with data-logging capabilities. The EPA regulates environmental claims around noise reduction ratings, while FCC certification governs radio transmission protocols in multi-site industrial deployments. Buyers must evaluate whether vendor roadmaps align with emerging ISO standards for occupational wearable interoperability before committing to fleet-scale deployments.
Market Dynamics
Bluetooth-enabled active noise cancellation is displacing legacy wired PPE across manufacturing plants as OSHA intensifies enforcement of 29 CFR 1910.95 hearing conservation mandates, compressing replacement cycles and forcing suppliers to demonstrate real-time data-logging capabilities.
Growth Catalysts
- OSHA Compliance Pressure:Federal enforcement of permissible exposure limits under 29 CFR 1910.95 compels construction and oil & gas operators to upgrade to connected protection devices with automated exposure monitoring.
- EU Green Deal Mandates:Embedded industrial sustainability requirements broaden procurement criteria for energy-efficient communication headsets in European factories.
- Bone Conduction Engineering:Premium variants addressing seal failure under hard-hat pressure capture margin in heavy manufacturing where traditional in-ear systems fail.
Market Restraints
- Lithium-Polymer Supply Concentration:Battery chemistry dependence on East Asian cell manufacturers creates input cost volatility and qualification bottlenecks for full-shift operation ratings.
- FCC Certification Friction:Radio transmission protocol approvals for multi-site industrial deployments extend vendor lead times and freeze specification decisions.
- ISO Interoperability Delays:Emerging occupational wearable standards lack finalized test protocols, forcing buyers to defer fleet-scale commitments pending vendor roadmap alignment.
Strategic Opportunities
- Biometric Convergence:Integration of geolocation tracking and physiological monitoring into unified worker safety platforms opens premium-margin service contracts.
- German Manufacturing Modernization:Accelerating procurement of smart in-ear systems combining hearing protection with team communication creates concentrated demand for configurable enterprise solutions.
- Construction Supply Chain Penetration:Deep distribution partnerships with safety equipment wholesalers capture high-volume disposable segment replacement cycles.
Industry Challenges
- Acoustic Engineering Talent Scarcity:Specialized expertise in speech-isolation algorithms and hazardous noise suppression remains concentrated among mining-environment specialists.
- Legacy System Integration Complexity:Bluetooth 5.0+ connectivity requirements conflict with existing plant communication infrastructure, demanding costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hearables Market |
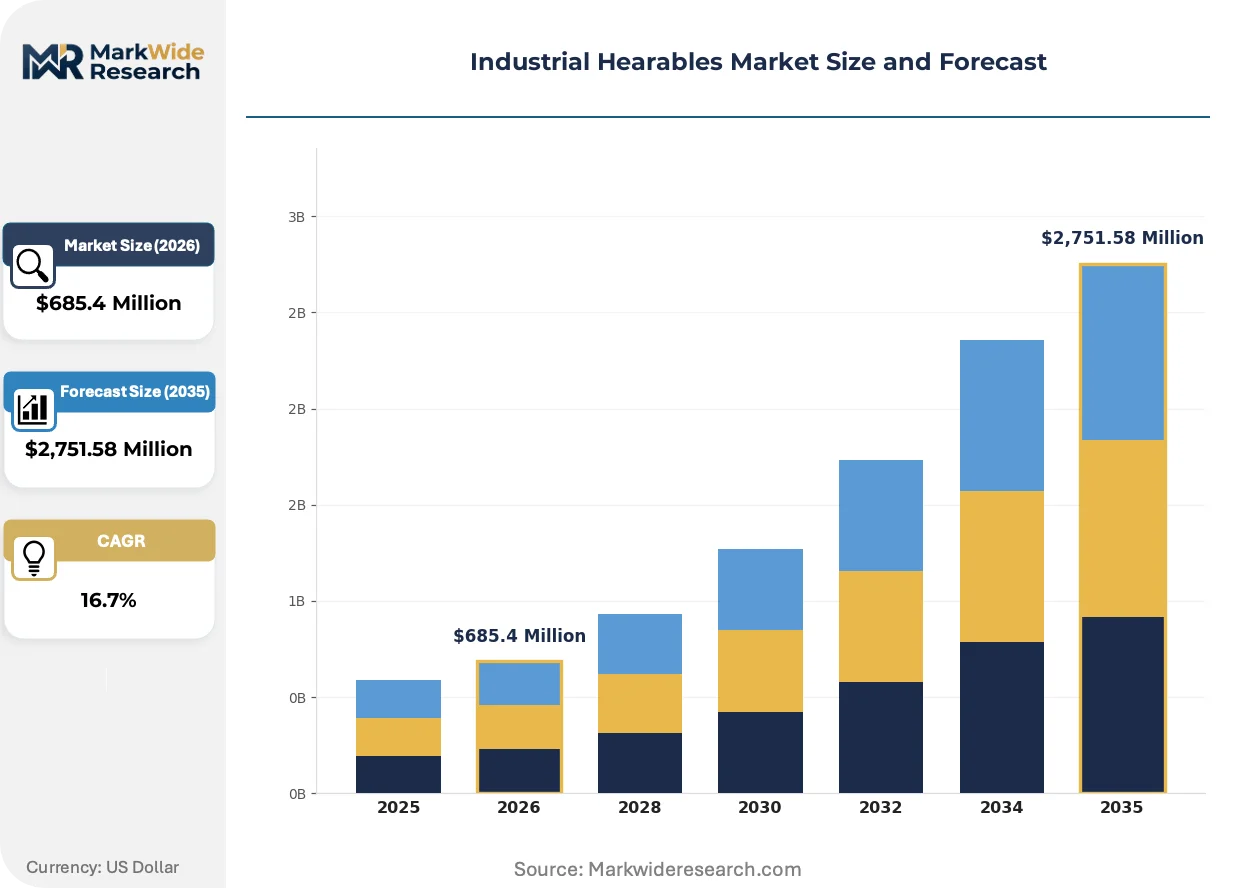
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,751.58 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-Ear, In-Ear, On-Ear, Bone Conduction Technology: Active Noise Cancellation, Bluetooth, Wired, Smart Features End User: Construction, Manufacturing, Oil & Gas, Mining Application: Communication, Hearing Protection, Monitoring, Industrial Training |
| Companies Covered | Sensear Pty Ltd, EERS Global Technologies Inc., Sonetics Corporation, Honeywell International Inc., 3M, QuietOn Ltd., Setcom Corporation, Pro Tech Technologies, Inc., Fujikon Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hearables Market Strategic Shifts & Innovations
Real-time situational awareness is reshaping product architecture as facilities reject isolation-based protection in favor of connected systems preserving environmental perception. Three developments are compressing competitive timelines.
Advanced noise-canceling microphone arrays is converging with bone conduction transducers to eliminate seal dependency in high-pressure PPE environments. Mining operators and heavy manufacturing facilities are accelerating qualification of hybrid designs that bypass traditional acoustic isolation. This convergence is compressing the addressable market for conventional passive attenuation devices.
REACH chemical safety protocols and embedded CSRD sustainability reporting requirements are tightening material disclosure obligations for European industrial procurement. Vendors must now document full substance inventories for lithium-polymer housings and ear-tip polymers to maintain approved supplier status. German automotive and chemical plants are driving the fastest specification updates to capture Green Deal-linked capital allocation.
Specification authority is migrating from safety managers to enterprise IT departments as connected hearables integrate into unified worker safety platforms. Channel relationships with industrial distributors are weakening as direct vendor engagement with facility technology officers captures multi-year platform contracts. United States oil & gas and construction verticals exhibit the most pronounced buying committee restructuring.
Industrial Hearables Market Segmentation
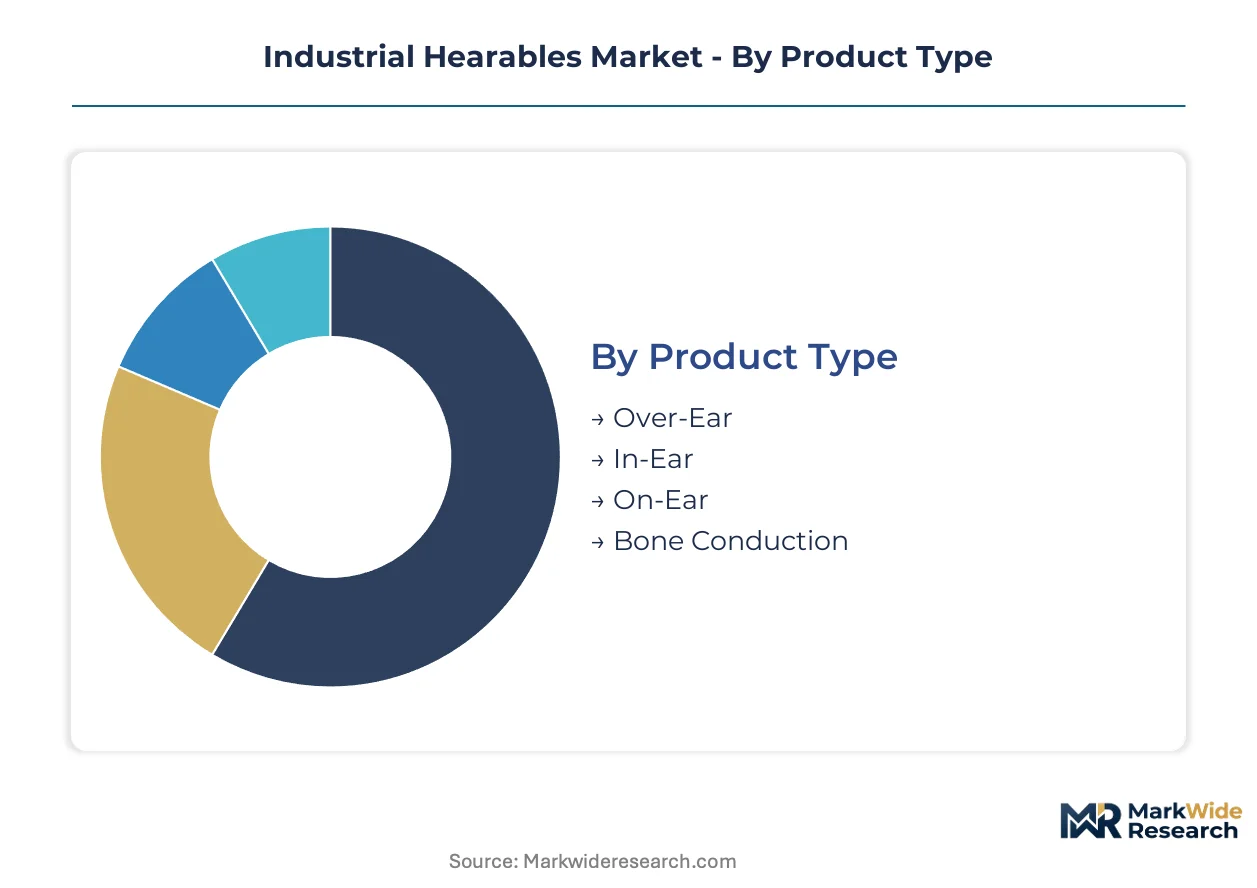
Industrial hearables segmentation reflects divergent engineering requirements across hazardous work environments. Product architecture, connectivity protocols, and end-use specifications determine procurement patterns as facilities balance OSHA compliance with operational integration.
Product Type:
Physical form factor dictates seal integrity, comfort duration, and compatibility with existing PPE ensembles.
- In-Ear:Silicone and foam-tipped designs insert directly into the ear canal, achieving noise reduction ratings above 25 dB through passive attenuation combined with active electronic processing. German automotive plants and chemical facilities are accelerating procurement of smart in-ear systems that embed biometric sensors and geolocation tracking, driven by EU Green Deal capital allocation for connected worker safety platforms.
- Bone Conduction:Transducers bypass the eardrum entirely, transmitting vibration through the temporal bone to preserve situational awareness in environments above 100 dB. Premium positioning in heavy manufacturing and mining addresses seal failure under hard-hat pressure, with hybrid designs converging noise-canceling microphone arrays to eliminate acoustic isolation dependency.
- Over-Ear:Circumaural cups enclosing the entire ear deliver maximum passive attenuation for sustained high-noise exposure.
- On-Ear:Supra-aural pads rest against the outer ear, trading attenuation depth for reduced bulk and improved compatibility with safety helmets.
In-Ear leads on scale; Bone Conduction leads on momentum.
Technology:
Connectivity and signal processing architecture separates legacy compliance equipment from next-generation integrated safety systems.
- Bluetooth:Bluetooth 5.0+ protocols enable wireless team communication, real-time exposure data logging, and integration with unified worker safety platforms. FCC certification requirements for multi-site industrial deployments create vendor qualification bottlenecks, compressing specification decisions toward vendors with established radio transmission approvals.
- Smart Features:Embedded biometric monitoring, GPS tracking, and AI-driven speech isolation transform hearables into edge computing nodes. United States oil & gas operators and construction firms are restructuring buying committees to place enterprise IT departments at specification authority, capturing multi-year platform contracts with automated exposure monitoring capabilities.
- Active Noise Cancellation:Electronic circuitry generates anti-phase waveforms to cancel hazardous ambient frequencies while preserving speech-band clarity.
- Wired:Tethered connections persist in facilities with electromagnetic interference concerns or legacy communication infrastructure.
Bluetooth leads on scale; Smart Features leads on momentum.
End User:
Industry verticals impose distinct acoustic hazard profiles, shift patterns, and regulatory enforcement intensities.
- Manufacturing:Continuous noise environments from metal forming, assembly machinery, and process equipment drive full-shift battery requirements and durability specifications. German manufacturing modernization programs concentrate demand for configurable enterprise solutions combining hearing protection with real-time team coordination.
- Construction:Transient high-impact noise from pneumatic tools, demolition, and heavy equipment creates intermittent exposure patterns favoring rapid donning and doffing. Federal OSHA enforcement of permissible exposure limits under 29 CFR 1910.95 compels upgrade cycles toward connected protection devices with automated documentation.
- Oil & Gas:Explosive atmosphere classifications and remote site operations demand intrinsically safe designs with extended temperature tolerance.
- Mining:Underground communication dead zones and extreme reverberation environments prioritize proprietary speech-isolation algorithms and mesh networking protocols.
Manufacturing leads on scale; Construction leads on momentum.
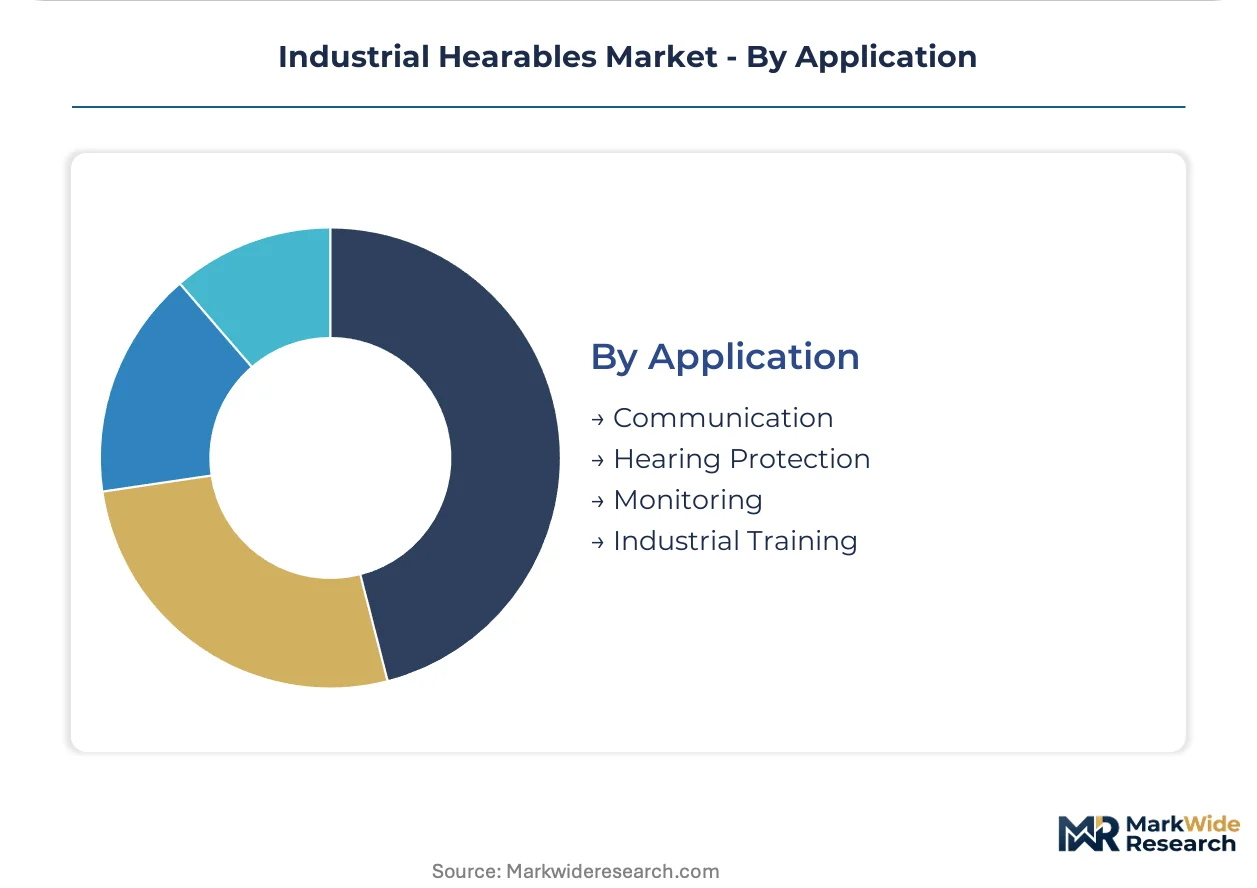
Application:
Functional deployment mode determines sensor payload, software architecture, and service contract structure.
- Hearing Protection:Core regulatory compliance function preventing occupational noise-induced hearing loss above 85 dB time-weighted average. EPA-regulated noise reduction ratings govern procurement specifications, with data-logging capabilities becoming mandatory under intensifying OSHA enforcement.
- Communication:Two-way voice coordination preserving team situational awareness in partitioned facilities or remote operations. Integration with plant communication infrastructure demands costly middleware development where Bluetooth 5.0+ conflicts with legacy systems.
- Monitoring:Continuous exposure tracking, physiological surveillance, and environmental sensing for predictive safety analytics.
- Industrial Training:Augmented audio instruction and skill transfer applications in high-turnover workforce environments.
Hearing Protection leads on scale; Communication leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial hearables emerged from Scandinavian mining safety engineering and German automotive acoustic research before scaling through North American oilfield digitization and East Asian electronics manufacturing.
United States
OSHA intensifies enforcement of 29 CFR 1910.95 permissible exposure limits across construction sites and Permian Basin oilfields. The EPA regulates noise reduction rating claims while FCC certification governs multi-site radio deployments. Houston-Gulf Coast petrochemical clusters and North Dakota shale operations drive fleet-scale procurement of connected protection devices with automated exposure logging.
Germany
EU Green Deal capital allocation accelerates modernization of Bavarian automotive plants and North Rhine-Westphalia chemical facilities. REACH chemical safety protocols and embedded CSRD sustainability reporting tighten material disclosure obligations for lithium-polymer housings. Stuttgart automotive engineering clusters and Ludwigshafen chemical complexes specify smart in-ear systems combining hearing protection with biometric monitoring.
China
GB standards for occupational noise exposure tighten enforcement across Yangtze River Delta manufacturing zones. MIIT certification requirements for radio transmission equipment create vendor qualification bottlenecks for Bluetooth-enabled industrial deployments. Shenzhen electronics assembly corridors and Shanghai Pudong heavy machinery plants integrate bone conduction variants where traditional seals fail under hard-hat pressure.
Australia
Underground communication dead zones in Western Australian iron ore and Queensland coal operations prioritize mesh networking protocols and proprietary speech-isolation algorithms. The country's national occupational safety regulator enforces exposure limits that increasingly specify data-logging capabilities. Pilbara mining camps and Bowen Basin extraction sites accelerate qualification of hybrid bone conduction designs.
Canada
Health Canada and provincial occupational health agencies align hearing conservation requirements with EPA-equivalent noise reduction rating standards. Alberta oil sands operations and Ontario automotive assembly plants face compressed replacement cycles as legacy wired PPE phases out. Fort McMurray extraction sites and Windsor-Essex manufacturing corridors specify full-shift battery ratings for continuous noise environments.
Industrial Hearables Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the industrial hearables sector. The vendor base clusters around three strategic archetypes: diversified safety conglomerates cross-selling through integrated PPE portfolios, specialized acoustic engineering firms with proprietary noise suppression algorithms, and electronics contract manufacturers supplying private-label Bluetooth modules. Dominant competitive moves include backward integration into lithium-polymer battery supply and strategic partnerships with industrial distributors to bypass weakening channel relationships.
Within the diversified safety conglomerate tier, Honeywell International Inc. and 3M occupy positions anchored by deep distribution into construction supply chains and cross-selling alongside respiratory and gas detection equipment. Sensear Pty Ltd exemplifies the specialized acoustic engineering archetype, with its proprietary SENS technology representing the mining-environment speech-isolation capability that remains concentrated among hazardous noise suppression specialists.
| Leading Market Players |
|---|
| Sensear Pty Ltd |
| EERS Global Technologies Inc. |
| Sonetics Corporation |
| Honeywell International Inc. |
| 3M |
| QuietOn Ltd. |
| Setcom Corporation |
| Pro Tech Technologies, Inc. |
| Fujikon Industrial Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Bluetooth 5.0+ module miniaturization and lithium-polymer cell densification are compressing unit economics while concentrating procurement leverage among East Asian contract manufacturers. German automotive plants and United States oilfield operators now face divergent landed cost structures as FCC certification timelines and EU Green Deal material disclosure obligations layer compliance premiums onto base hardware.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the industrial hearables sector, with differentiation driven by OSHA data-logging certification grade and volume procurement scale. Premium bone conduction variants command widest margins where hard-hat compatibility failures eliminate in-ear competition, while economy-tier wired replacements face steepest cost compression from Bluetooth-enabled active noise cancellation displacement. Construction supply chains exhibit highest price sensitivity due to high-volume disposable replacement cycles, whereas mining operators prioritize speech-isolation performance over unit cost.
Supply Chain Analysis
Freight cost volatility from East Asian lithium-polymer cell manufacturers to North American and European assembly plants is reshaping vendor qualification strategies as buyers seek regional buffer inventory. Battery chemistry feeds from South Korea and Japan, Bluetooth module fabrication concentrates in China and Taiwan, and final acoustic calibration anchors in Germany and the United States. Single-source vulnerability in noise-canceling microphone MEMS sensors threatens production continuity, while distribution runs through industrial safety equipment wholesalers and direct enterprise IT procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial hearables procurement functions as a geographic-arbitrage play where German facilities absorb EU CSRD sustainability reporting premiums while United States buyers capture faster OSHA compliance depreciation schedules.
For Market Incumbents: Anticipate margin compression from private-label electronics contract manufacturers entering through Bluetooth module standardization. Backward integration into lithium-polymer cell supply secures full-shift battery rating credibility, while accelerated FCC pre-certification investments freeze specification decisions before multi-site deployments. For New Entrants and Emerging Players: Begin with construction supply chain penetration where disposable replacement cycles and fragmented buying committees resist incumbent platform bundling. White-space opportunity concentrates in mid-tier configurable enterprise solutions for German manufacturing modernization programs, with go-to-market leverage through safety equipment distributor partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized acoustic engineering firms with proprietary speech-isolation algorithms and mining-environment regulatory track records. Long-term viability hinges on biometric convergence service contract attach rates, with inflection signal tracking OSHA enforcement intensity in Permian Basin oilfields and federal construction stimulus allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive lithium-polymer cell production secures full-shift operation ratings against East Asian supply volatility. |
| FCC Pre-Certification Investment | Accelerated radio transmission approvals compress vendor lead times for multi-site industrial deployments. |
| Biometric Platform Integration | Geolocation and physiological monitoring embedding transforms hardware margins into recurring service contracts. |
| German Manufacturing Direct Engagement | Bypass weakening distributor channels to capture EU Green Deal capital allocation for connected worker safety. |
| Hybrid Bone Conduction R&D | Noise-canceling microphone convergence eliminates seal dependency in heavy manufacturing and mining environments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant safety managers, enterprise IT procurement officers, industrial distributor category heads, and acoustic engineering R&D directors with secondary validation against OSHA enforcement databases, FCC equipment authorization filings, EU CSRD sustainability disclosure registries, and customs trade data for lithium-polymer cell imports. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated against vendor revenue disclosures and facility procurement records.
Comparable-period anchoring linked forward projections to historical replacement cycle data across manufacturing, construction, and oilfield verticals, with segmentation modeling spanning product architecture, connectivity protocol, end-use industry, and functional application dimensions. CAGR derivation weighted Bluetooth adoption curves against OSHA compliance mandate timelines, incorporating lithium-polymer battery energy density improvement trajectories and FCC certification backlog durations as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to ISO occupational wearable interoperability standards and geopolitical disruptions to East Asian electronics component flows. Forecasts reflect documented assumptions about enforcement continuity and technology transition rates; stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Europe Soundbar Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Consumer Electronics Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Global Digital Watch Market