
 Mechanical Keyboard Market | 2026-2036
Mechanical Keyboard Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Keyboard Market Analysis
Software-defined lighting and macro programming layers is rebalancing how vendors monetize mechanical keyboards beyond hardware shipments. Cherry AG leverages captive switch production to sustain margin control across OEM and retail channels. Razer Inc. competes through ecosystem lock-in spanning keyboards, mice, and cloud-stored profiles. Logitech International SA anchors enterprise positioning with wireless mechanical variants targeting hybrid work deployments.
A mechanical keyboard employs individual spring-actuated switches beneath each keycap, typically rated for fifty-million-plus keystrokes with tactile, linear, or clicky feedback profiles. These devices serve precision input requirements across competitive gaming, software development, and content creation workflows where input latency and actuation consistency carry operational weight. Gaming keyboards occupy the dominant revenue pool given peripheral spending intensity among esports participants and streamers. Optical switch technology is gaining fastest traction due to contactless actuation eliminating debounce delay and extending operational lifespan. Compact keyboards command premium positioning among mobile professionals prioritizing desk portability without sacrificing switch quality.
FCC electromagnetic emissions standards govern wireless keyboard certification for US market entry, while EU REACH and RoHS frameworks restrict lead content and hazardous substances in switch solder points and PCB substrates. China's GB standards through SAMR mandate electrical safety testing for domestically sold peripherals, creating compliance cost layering for import brands. Stakeholders must monitor whether optical switch architectures trigger refreshed regulatory classification as electronic rather than electromechanical devices, potentially altering certification pathways and testing burdens across major markets.
Market Dynamics
Optical switch architectures are compressing actuation latency benchmarks while forcing PCB redesigns and recertification cycles across switch vendors and keyboard OEMs. This technology transition is redistributing competitive advantage away from traditional electromechanical expertise toward optical sensor integration capabilities.
Growth Catalysts
- EU RoHS hazardous substance restrictions:Lead-free solder mandates are accelerating PCB substrate innovation and opening market share for compliant Asian component suppliers.
- Esports tournament infrastructure:Professional gaming leagues are standardizing peripheral specifications, creating pull-through demand at the consumer tier.
- Shenzhen manufacturing corridor concentration:Vertical integration of switch housing, spring fabrication, and keycap molding within a fifty-kilometer radius compresses lead times and prototyping costs.
Market Restraints
- Copper and rare earth magnet volatility:Switch spring alloys and Hall-effect sensor inputs face commodity price swings that OEMs struggle to pass through in retail pricing.
- Single-region switch supply:Premium mechanical switch production concentrates in southern China, exposing brands to logistics disruption and tariff exposure.
- Debounce delay physics:Traditional metal-contact switches cannot eliminate signal noise without firmware compensation, capping performance claims against optical alternatives.
Strategic Opportunities
- India BIS certification pathway:Domestic electrical safety mandates for imported electronics create first-mover advantage for brands establishing local testing partnerships.
- Cloud-stored macro profile ecosystems:Software-defined keyboard functionality is unbundling hardware replacement cycles and enabling recurring revenue attachment.
- Hybrid work enterprise procurement:IT departments are refreshing peripheral standards for distributed teams, opening bulk contract opportunities beyond gaming demographics.
Industry Challenges
- FCC Part 15 wireless certification timelines:Bluetooth and 2.4 GHz keyboard variants face six-to-nine month approval windows that compress product launch windows against unlicensed competitors.
- Optical switch patent thickets:Infrared actuation mechanisms carry overlapping IP claims across Japanese, Chinese, and US filings, complicating clean-room engineering efforts.
- Legacy USB-HID firmware integration:Enterprise security software and kiosk systems often block unrecognized device IDs, requiring per-customer compatibility validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Keyboard Market |
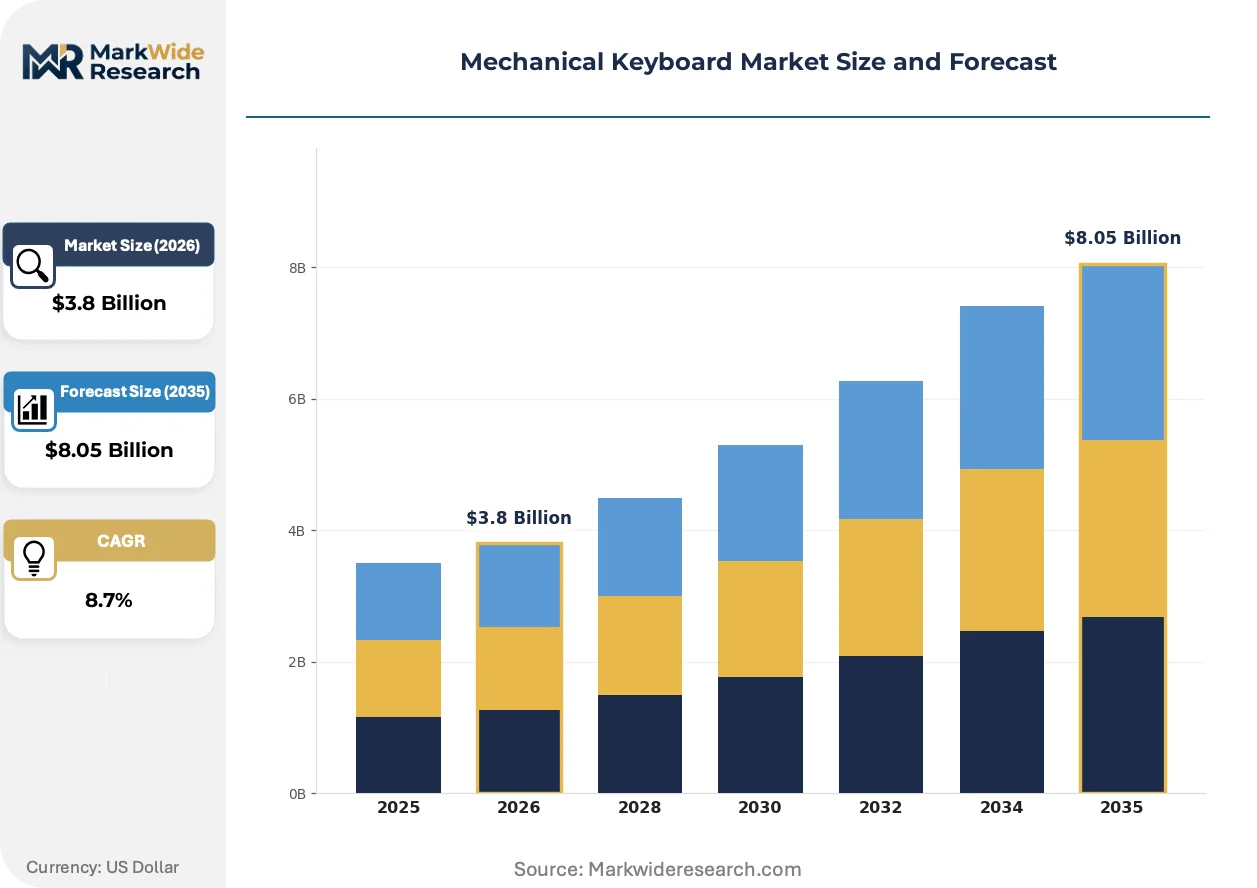
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gaming Keyboards, Office Keyboards, Compact Keyboards, Ergonomic Keyboards Technology: Mechanical, Optical, Hybrid, Bluetooth End User: Gamers, Professionals, Creatives, Students Switch Type: Cherry MX, Razer, Kailh, Gateron |
| Companies Covered | Logitech International SA, Corsair Gaming, Razer Inc., SteelSeries ApS, Cherry AG, DuckyChannel International Co., Ltd., Shenzhen Rapoo Technology Co., Ltd., Cooler Master Technology Inc., Keychron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Keyboard Market Emerging Trajectories
Switch technology, regulatory frameworks, and procurement patterns are converging to redefine how mechanical keyboards are engineered, certified, and sold. Vendors must now coordinate optical sensor development with electromagnetic compliance and enterprise sales cycles simultaneously.
Hot-swappable PCB architectures are unifying enthusiast customization with retail durability expectations. Gamers and developers are adopting socketed switch platforms at accelerating rates, enabling field replacement without soldering equipment. This unifying capability is compressing the traditional segmentation between DIY kit buyers and pre-built keyboard consumers.
REACH substance candidate list expansion is tightening scrutiny on flame retardants in keyboard plastics and stabilizer lubricants. ECHA evaluations are forcing reformulation of ABS and PBT keycap compounds ahead of sunset date uncertainties. German electronics distributors are demanding full material disclosure documentation from Asian OEMs to preempt downstream liability.
Enterprise IT departments are consolidating peripheral procurement around wireless mechanical standards with centralized fleet management. Gaming-focused brands are losing share in commercial RFPs to vendors offering MDM-compatible firmware and standardized warranty terms. This rotation is most visible in United States hybrid work deployments where security audit requirements override consumer feature preferences.
Mechanical Keyboard Market Segmentation
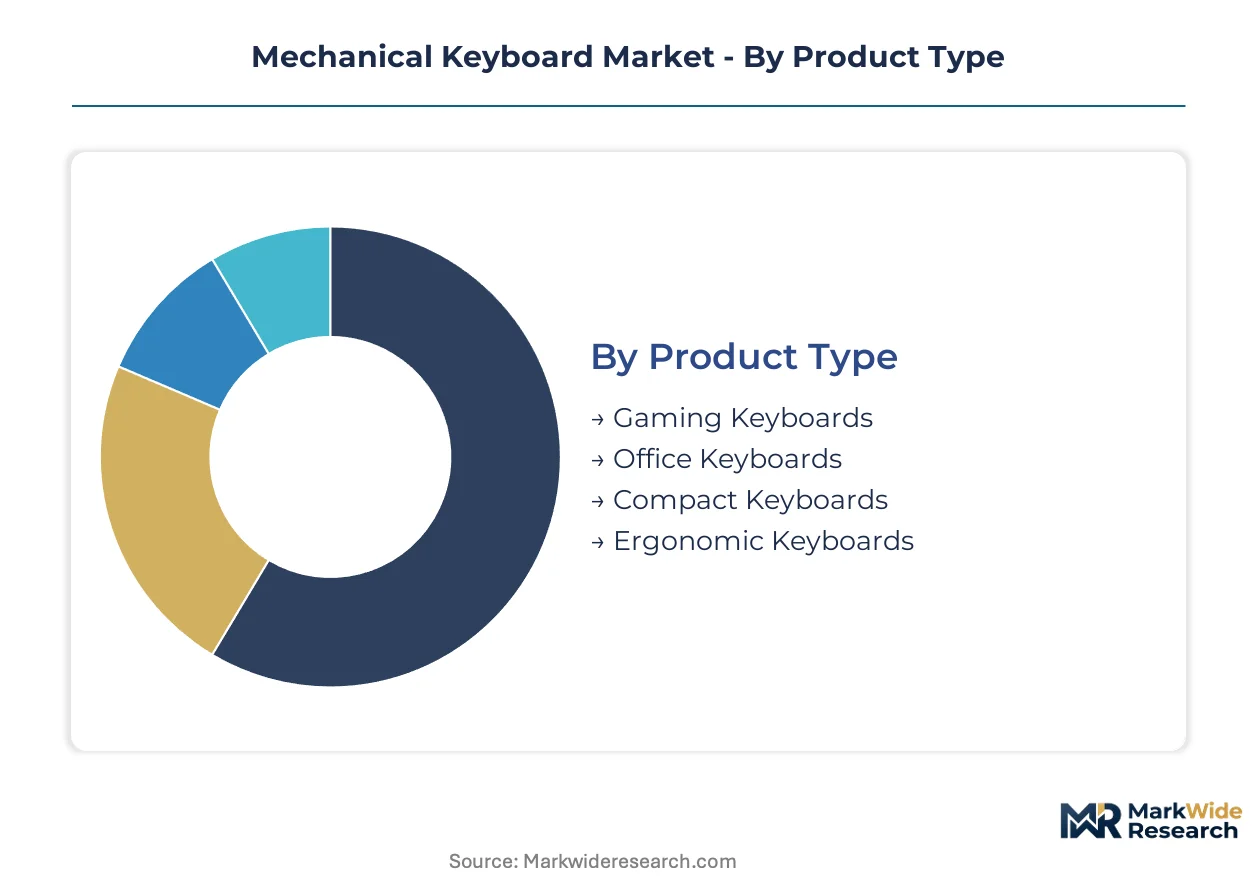
Mechanical keyboard segmentation reveals how capital deployment, regulatory exposure, and end-user specialization fragment manufacturing priorities. Switch technology investments and certification pathways vary dramatically across these divides, forcing vendors to choose concentration over breadth.
Product Type:
Capital intensity peaks where actuation precision requirements intersect with volume scale, driving divergent factory equipment and testing infrastructure needs.
- Gaming Keyboards:Full-size and tenkeyless layouts with per-key RGB controllers, dedicated macro columns, and aluminum top plates dominate BOM costs. Demand concentrates among esports tournament organizers in Germany and the United States, where input latency benchmarking drives procurement specifications and sponsorship obligations.
- Compact Keyboards:60% and 75% form factors with layered function rows and detachable USB-C cables command premium positioning. Mobile professionals in China's Shenzhen corridor and surrounding tech hubs prioritize desk portability without sacrificing Cherry MX or optical switch quality, compressing traditional segmentation between enthusiast kits and retail pre-builts.
- Office Keyboards:Wireless mechanical variants with muted tactile switches and enterprise firmware compatibility address IT standardization requirements.
- Ergonomic Keyboards:Split chassis designs with adjustable tenting angles and palm rests target repetitive strain injury prevention in software development workflows.
Most installed capacity flows through Gaming Keyboards. Expansion is steepest in Compact Keyboards.
Technology:
Switch actuation mechanisms determine PCB layer complexity, sensor integration requirements, and recertification burdens across FCC and REACH frameworks.
- Optical:Infrared beam interruption eliminates metal-contact debounce delay and extends operational lifespan beyond fifty million actuations. China's Shenzhen manufacturing corridor is retooling fastest here, with Hall-effect sensor suppliers co-locating near switch housing fabricators to compress prototyping cycles.
- Mechanical:Spring-actuated metal contacts with gold alloy plating remain the volume standard despite firmware-dependent debounce compensation. German electronics distributors demand full material disclosure documentation from Asian OEMs to preempt downstream REACH liability on solder alloys and stabilizer lubricants.
- Hybrid:Dual-mode wired and wireless architectures with battery management ICs and 2.4 GHz transceivers balance latency and mobility.
- Bluetooth:Low-energy protocol stacks enable multi-device pairing for tablet and smartphone workflows.
Revenue concentration sits with Mechanical. Optical is gaining share fastest through latency-sensitive gaming applications.
End User:
Procurement authority and replacement frequency create divergent margin structures across consumer, enterprise, and institutional channels.
- Gamers:Peripheral spending intensity among esports participants and streamers sustains premium pricing for tournament-grade specifications. United States retailers allocate expanding shelf space to RGB-equipped mechanical variants with cloud-stored macro profiles.
- Professionals:Enterprise IT departments are consolidating procurement around wireless mechanical standards with MDM-compatible firmware and centralized fleet management, rotating share away from gaming-focused brands in commercial RFPs.
- Creatives:Video editors and 3D modelers prioritize macro programmability and dial encoders for timeline scrubbing.
- Students:Price-sensitive entry-level mechanical adoption concentrates in China's domestic education technology procurement.
Bulk contract volume flows through Professionals. Gamer segment spending per unit remains highest.
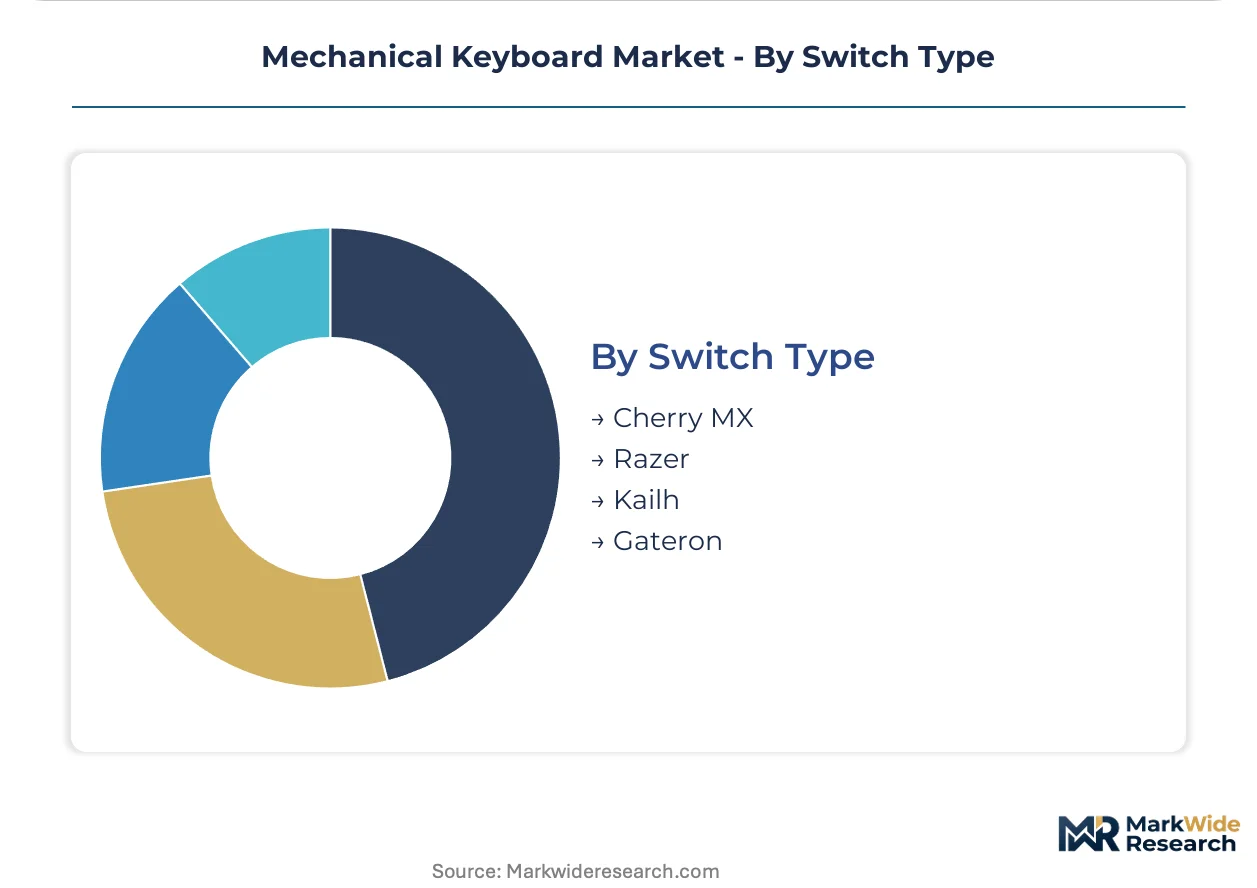
Switch Type:
Intellectual property licensing and captive production capabilities determine margin capture for switch vendors versus keyboard OEMs.
- Cherry MX:German-engineered crosspoint contact mechanisms with standardized stem geometries anchor aftermarket keycap compatibility. Cherry AG leverages captive switch production in Auerbach to sustain margin control across OEM and retail channels while enforcing trademark protection against clone manufacturers.
- Kailh:Chinese-developed BOX architecture with dust and moisture sealing targets IP-rated industrial applications. Vertical integration of spring fabrication and housing molding within Guangdong province compresses lead times for keyboard brands seeking RoHS-compliant alternatives.
- Razer:Proprietary opto-mechanical and analog designs lock into ecosystem-controlled peripheral suites.
- Gateron:Smooth linear actuation variants with factory lubrication appeal to enthusiast customization markets.
Volume leadership rests with Cherry MX. Kailh is expanding production capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shenzhen corridor concentrates switch manufacturing capacity while Germany enforces REACH material disclosure standards that reshape Asian OEM compliance obligations. The United States drives wireless mechanical adoption through enterprise hybrid work procurement. India and Japan represent divergent growth vectors through certification pathways and optical sensor development.
United States
Enterprise IT departments are consolidating peripheral procurement around wireless mechanical standards with MDM-compatible firmware. FCC Part 15 certification governs Bluetooth and 2.4 GHz keyboard variants for market entry. Austin and Seattle tech corridors anchor distributed team deployments where security audit requirements override consumer feature preferences.
Germany
Electronics distributors demand full material disclosure documentation from Asian OEMs to preempt downstream REACH liability. Cherry AG leverages captive switch production in Auerbach to sustain margin control across OEM and retail channels. Berlin and Hamburg gaming communities drive tournament-grade specification adoption among esports participants.
China
Shenzhen's manufacturing corridor hosts vertical integration of switch housing, spring fabrication, and keycap molding within a fifty-kilometer radius. SAMR GB standards mandate electrical safety testing for domestically sold peripherals. Guangdong province fabricators are retooling fastest toward optical switch architectures with Hall-effect sensor suppliers co-locating nearby.
India
Domestic electrical safety mandates for imported electronics create first-mover advantage for brands establishing BIS certification partnerships. Bengaluru and Hyderabad tech hubs concentrate mobile professionals prioritizing compact keyboard portability. Mumbai electronics distributors are expanding shelf space for gaming peripherals targeting price-sensitive entry-level adoption.
Japan
METI standards frameworks influence optical switch patent development and infrared actuation mechanism engineering. Tokyo and Osaka metropolitan areas anchor enthusiast customization markets demanding smooth linear actuation variants. Japanese sensor component suppliers are co-developing contactless actuation technologies with keyboard OEMs.
Mechanical Keyboard Market Vendor Landscape
Top-tier vendors anchor premium gaming and enterprise segments, while mid-tier specialists compete on switch customization and regional price positioning. The vendor base stratifies across captive switch producers, ecosystem-locked peripheral brands, and wireless-first enterprise suppliers. Three archetypes dominate: German-engineered switch licensors, Chinese vertically integrated fabricators, and cloud-profile ecosystem operators. Competitive moves center on optical sensor patent licensing and hot-swappable PCB platform standardization.
Within the captive production archetype, Cherry AG exemplifies margin control through in-house switch manufacturing and trademark enforcement. Among ecosystem-locked operators, Razer Inc. and Logitech International SA occupy positions where cloud-stored macro profiles and multi-device compatibility create switching costs. Shenzhen Rapoo Technology Co., Ltd. represents the scale-driven Chinese fabrication tier competing on lead time compression and RoHS compliance integration.
| Leading Market Players |
|---|
| Logitech International SA |
| Corsair Gaming |
| Razer Inc. |
| SteelSeries ApS |
| Cherry AG |
| DuckyChannel International Co., Ltd. |
| Shenzhen Rapoo Technology Co., Ltd. |
| Cooler Master Technology Inc. |
| Keychron |
| Others |
Supply Flow & Price Mechanics
Enterprise IT procurement consolidation around wireless mechanical standards with MDM-compatible firmware is forcing OEMs to absorb certification and firmware development costs, compressing margins on standard-tier products while premium gaming SKUs retain pricing power through ecosystem lock-in.
Pricing Analysis
Capacity additions in China's Guangdong province are reshaping price floors for RoHS-compliant mechanical switches. Three-tier pricing structure across premium, standard, and economy levels separates tournament-grade optical variants from entry-level metal-contact designs. Price differentiation rests on certification grade and volume scale. Cost compression in the standard tier is intensifying because OEMs struggle to pass through copper alloy volatility. Students represent the most price-sensitive buyer archetype; esports tournament organizers show the least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from enterprise IT departments, while gaming-focused brands rely on distributor networks through German electronics retailers and United States consumer channels. Manufacturing concentrates in China, with component sourcing from Japan for Hall-effect sensors and Germany for Cherry MX crosspoint mechanisms. Raw material dependencies include copper spring alloys, rare earth magnets for optical sensors, and ABS/PBT keycap compounds. Single-region switch supply in southern China creates tariff exposure and logistics disruption risk. Distribution runs through Shenzhen-based fabricators to global OEM assembly points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical keyboard production arbitrage favors establishing switch fabrication in India to exploit BIS certification first-mover advantages against REACH compliance costs burdening European competitors.
For Market Incumbents: To counter optical switch patent thickets from Japanese and Chinese filings, Cherry AG and Logitech International SA should deepen in-house production of contactless actuation mechanisms and accelerate hot-swappable PCB platform standardization to lock in aftermarket keycap compatibility revenue. For New Entrants and Emerging Players: Enter via India's BIS certification pathway for wireless mechanical variants targeting Bengaluru and Hyderabad tech hubs, exploiting underpenetrated enterprise procurement channels with MDM-compatible firmware offerings priced below gaming-brand alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated Chinese fabricators retooling toward optical architectures, given Shenzhen's co-location advantages with Hall-effect sensor suppliers. Long-term viability hinges on optical switch IP clearance and enterprise channel penetration. Watch for FCC Part 15 certification timeline compression as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Switch Patent Licensing | Clears IP barriers for contactless actuation architectures across Japanese, Chinese, and US filings. |
| Hot-Swappable PCB Platform Standardization | Unifies enthusiast customization with retail durability expectations, compressing DIY and pre-built segmentation. |
| BIS Certification Partnership Establishment | Creates first-mover advantage in India's domestic electrical safety mandate for imported electronics. |
| Cloud-Stored Macro Profile Ecosystem Development | Enables recurring revenue attachment and unbundles hardware replacement cycles for gaming demographics. |
| REACH-Compliant Material Reformulation | Preempts downstream liability from ECHA flame retardant scrutiny on ABS and PBT keycap compounds. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each. The analysis combines interviews with switch OEM procurement directors, enterprise IT fleet managers, gaming peripheral category buyers, Hall-effect sensor R&D leads, and Shenzhen manufacturing operators with secondary validation from FCC equipment authorization databases, ECHA REACH candidate list updates, SAMR GB standard filings, and SEC 10-K peripheral segment disclosures. Bottom-up switch shipment modeling and top-down gaming hardware revenue triangulation anchor volume and value estimates.
Granularity-level framing applies country-specific regulatory cluster modeling for certification pathway analysis, with switch technology, end-user segment, and form factor dimensions projected across the analysis window. CAGRs derive from trend-line extrapolation against esports tournament infrastructure buildout rates and enterprise hybrid work peripheral refresh cycles. Forecast inputs incorporate optical switch adoption curves and copper alloy price volatility assumptions.
Inputs from FCC, ECHA, and SAMR regulatory filings were available through the study window; gaps in real-time OEM inventory positioning and patent litigation status introduce uncertainty bands around capacity expansion timing. Forecasts reflect documented assumptions on optical switch cost parity achievement and enterprise MDM compatibility standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Android TV Box Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
Global Beauty Camera Apps Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Airport Retailing Consumer Electronics Market