
 Dog Box Market | 2026-2036
Dog Box Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Box Market Analytics
Certified pet product designers is bifurcating the competitive landscape as artisanal craftsmanship competes with mass manufacturing efficiency. BarkBox leverages its subscription logistics network to sustain recurring kit assembly capacity. The Farmer's Dog anchors premium positioning through veterinary-formulated product curation. Bullymake specializes in durable chew-resistant construction for aggressive breeds, occupying a defensible niche against commodity rivals.
A dog box is an enclosed container engineered from plastic, metal, wood, or fabric composites with specified ventilation apertures and structural load ratings, designed to house, transport, or train canines in residential, commercial, or veterinary environments. Indoor box configurations dominate household penetration due to space constraints in urban dwellings, while travel crate demand accelerates among airline-compliant pet transport services. Metal fabrication commands margin premiums for kennel operators requiring sanitization cycles, whereas fabric segments compete on collapsibility and weight reduction for portable applications.
USDA Animal Welfare Act standards govern interstate transport container dimensions and ventilation, while FDA oversight applies to grooming boxes contacting topical treatments. State-level DOT regulations in Texas and Florida mandate crash-tested anchoring for vehicle-mounted travel crates, shaping product development roadmaps. Stakeholders must monitor evolving municipal breed-specific housing ordinances that could restrict box sizing requirements in multi-unit residential zones.
Market Dynamics
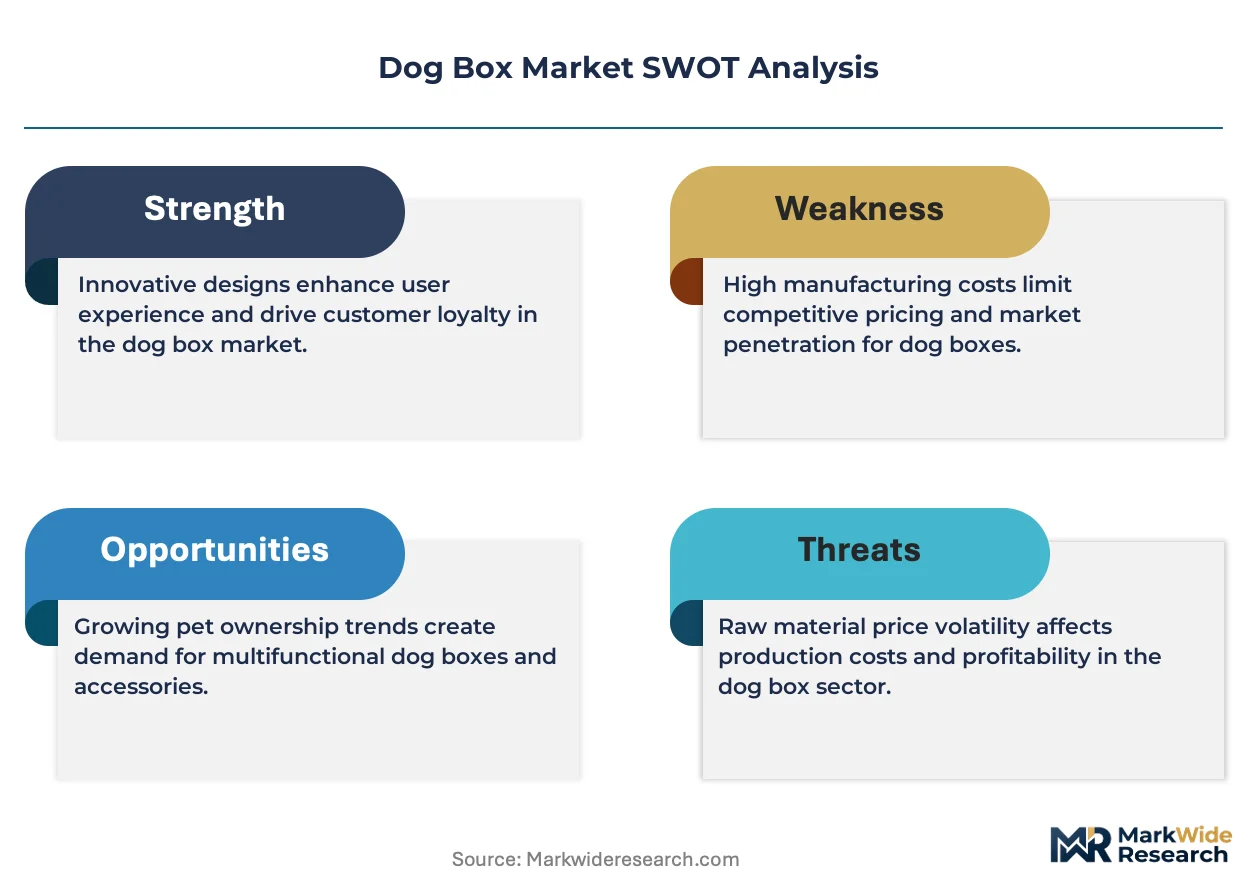
USDA ventilation mandates and state-level DOT crash-test requirements are compressing product development cycles while fragmenting supplier compliance costs across fabrication tiers.
Growth Catalysts
- USDA Animal Welfare Act standards:Interstate transport container specifications are forcing kennel operators and breeders to upgrade to compliant ventilation systems, sustaining replacement demand cycles.
- Texas and Florida DOT anchoring mandates:Vehicle-mounted travel crate crash-testing requirements are accelerating procurement of certified metal fabrication among commercial transport services.
- Professional dog training specialization:Certified behaviorists are expanding dedicated facility builds, driving institutional-grade box procurement with sanitization and modular configuration specifications.
Market Restraints
- Aluminum and steel input volatility:Sanitization-grade metal fabrication faces margin compression from commodity price swings, pressuring kennel operator procurement budgets.
- China-dominated polymer supply:Virgin and recycled plastic resin concentration in East Asian manufacturing clusters creates tariff exposure and logistics fragility for North American blow-molding operations.
- Fabric durability ceiling:Collapsible soft-sided boxes face chew-resistance limitations with aggressive breeds, constraining penetration in working dog and security training verticals.
Strategic Opportunities
- India companion animal expansion:Urban pet ownership growth in Mumbai and Bangalore corridors presents underpenetrated demand for airline-compliant travel crates as veterinary infrastructure professionalizes.
- Smart sensor integration:Temperature and humidity monitoring hardware convergence with crate manufacturing is enabling premium tier differentiation for pharmaceutical and breeding transport applications.
- Veterinary subscription bundling:Telehealth platforms are piloting equipment-inclusive wellness plans, creating direct-to-consumer channel bypass of traditional retail and distributor markups.
Industry Challenges
- Certified pet product designer scarcity:Artisanal craftsmanship capability gaps are throttling boutique brand scaling and forcing reliance on mass manufacturing with compromised differentiation.
- Multi-jurisdiction compliance stacking:Simultaneous USDA, FDA, and municipal breed-specific housing ordinances are extending product validation timelines and inflating SKU proliferation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Box Market |
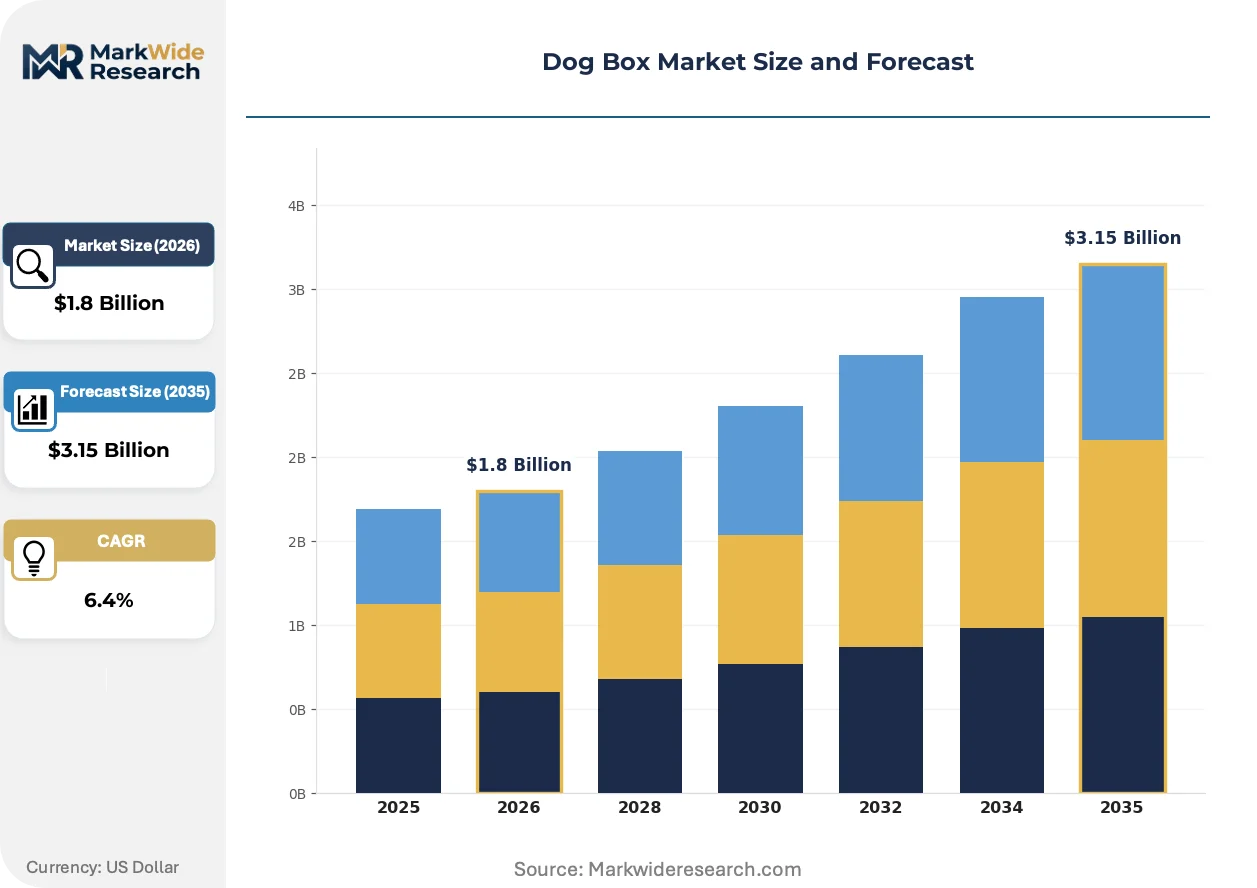
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Box, Travel Crate, Training Box, Grooming Box Material: Plastic, Metal, Wood, Fabric Size: Small, Medium, Large, Extra Large End User: Pet Owners, Dog Trainers, Kennel Operators, Pet Shops |
| Companies Covered | BarkBox, PupBox, Pet Treater, Loot Pets, DoggieLawn, HempMy Pet, The Farmer's Dog, Bullymake, Fetch Box, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Box Market Evolving Landscape
Material science advances and regulatory digitization are compressing traditional fabrication cycles while enabling real-time compliance verification across distributed supply chains.
Carbon fiber-reinforced polymer composites are penetrating high-performance veterinary transport applications where weight reduction intersects with structural load ratings. Equine and exotic animal transporters are piloting these materials for multi-species fleet standardization. This substitution trajectory is miniaturizing the addressable premium segment and forcing aluminum fabricators to defend margin position through sanitization automation.
EU F-Gas Regulation phase-down schedules are pressuring foam insulation suppliers serving temperature-controlled pet transport containers. Blow-molding operations in Germany and the Netherlands are reformulating polyurethane cores to maintain thermal performance envelopes. Veterinary pharmaceutical distributors are absorbing compliance costs through fleet refresh cycles, while budget airline pet services are deferring upgrades and accepting narrower operational temperature bands.
Breed-specific housing ordinances in Texas and Florida multi-unit residential zones are fragmenting box sizing standardization. Property management procurement is shifting toward modular, reconfigurable interior dimensions that accommodate municipal variation without inventory duplication. This specification divergence is most visible in Houston and Miami metro corridors, where pit bull and rottweiler restrictions create patchwork compliance requirements.
Dog Box Market Segmentation
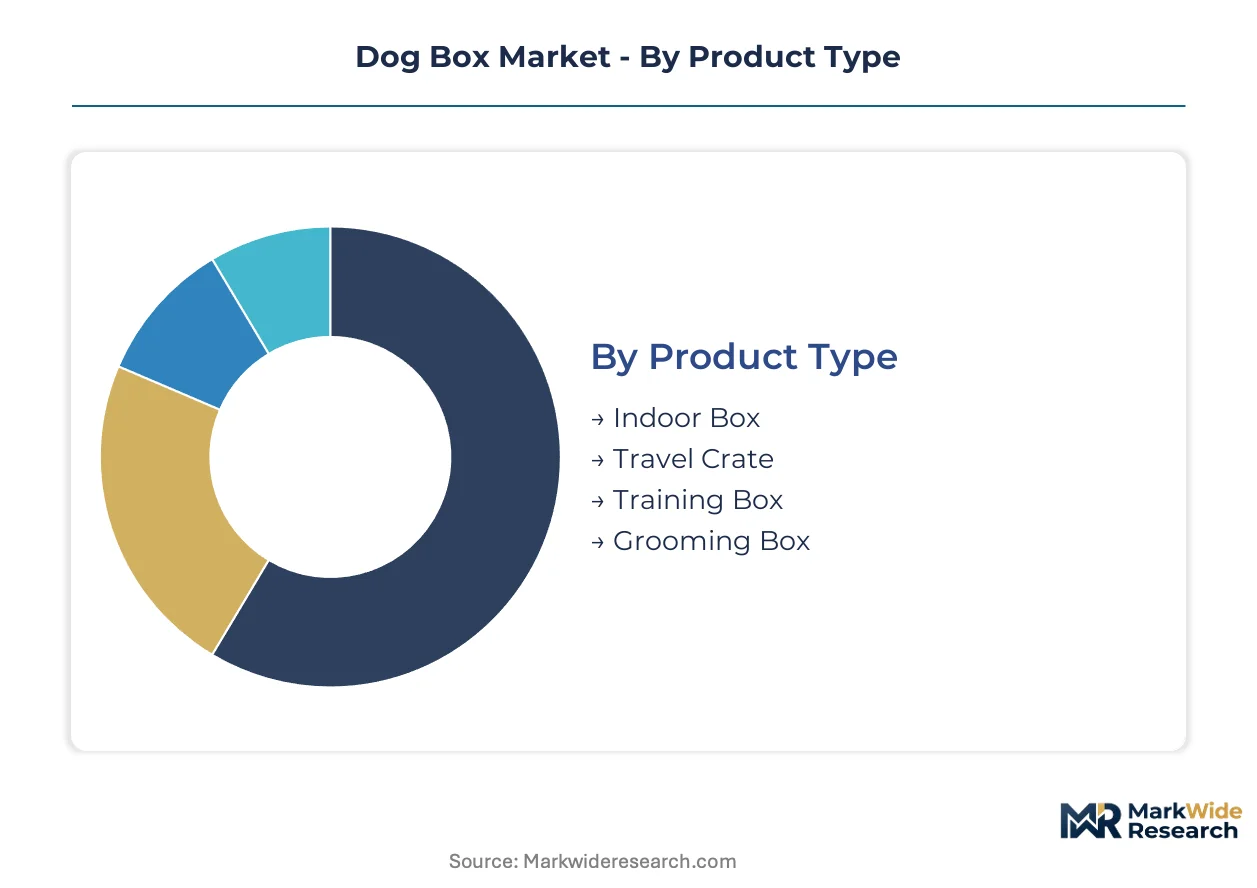
Dog box procurement patterns diverge sharply across use cases, with channel strategy determining which configurations achieve household penetration versus institutional adoption. Material selection and sizing specifications further fragment addressable demand across veterinary, airline, and residential compliance frameworks.
Product Type:
Channel distribution concentrates indoor boxes through mass retail and e-commerce direct, while travel crates and training boxes flow through specialty veterinary and professional supply channels with certification requirements.
- Indoor Box:Enclosed residential configurations prioritize space efficiency for urban dwellings with modular interior dimensions. Demand clusters in Texas and Florida metro corridors where municipal breed-specific housing ordinances drive sizing fragmentation.
- Travel Crate:Airline-compliant and vehicle-anchored designs integrate USDA ventilation mandates and DOT crash-test specifications. Commercial transport services in the United States are accelerating procurement of certified metal fabrication for interstate operations.
- Training Box:Specialized institutional-grade units feature sanitization surfaces and modular reconfigurability for certified behaviorist facilities.
- Grooming Box:FDA-regulated configurations contacting topical treatments serve veterinary and professional grooming operations with material safety documentation.
Indoor boxes dominate installed base. Travel crates are where expansion concentrates.
Material:
Cost tier stratification separates premium metal fabrication from commodity polymer and collapsible fabric alternatives, with margin compression most acute in mid-tier blow-molding operations.
- Plastic:Blow-molded polymer dominates volume production through weight reduction and cost scalability, though virgin and recycled resin concentration in East Asian manufacturing clusters exposes North American operations to tariff exposure.
- Metal:Aluminum and steel fabrication commands premium positioning for kennel operators requiring repeated sanitization cycles. USDA-compliant ventilation integration and DOT crash-test certification sustain replacement demand among commercial transport services.
- Wood:Artisanal craftsmanship serves boutique residential positioning with aesthetic differentiation, constrained by moisture resistance limitations in veterinary environments.
- Fabric:Collapsible soft-sided construction competes on portability and weight reduction, though chew-resistance limitations constrain penetration in working dog and security training verticals.
Plastic captures volume leadership. Metal fabrication is climbing the fastest on certification premiums.
Size:
Application requirements and municipal housing ordinances fragment standardization, with property management procurement shifting toward reconfigurable interior dimensions that accommodate patchwork compliance without inventory duplication.
- Small:Compact configurations serve toy breeds and airline cabin transport with strict dimensional limits. Urban pet ownership in United States metro corridors sustains baseline demand.
- Medium:Mid-range specifications balance residential space constraints with breed accommodation, representing the most contested tier between mass retail and specialty channels.
- Large:Working dog and security training applications require reinforced structural load ratings. Kennel operators in Texas and Florida prioritize sanitization-grade fabrication at this scale.
- Extra Large:Specialized veterinary transport and exotic animal applications absorb premium pricing for carbon fiber-reinforced composites where weight reduction intersects with structural requirements.
Medium sizes anchor household penetration. Large configurations are gaining share fastest on institutional procurement.
End User:
Customer type determines compliance burden and channel access, with professional segments absorbing certification costs while pet owners prioritize collapsibility and retail availability.
- Pet Owners:Residential purchasers prioritize space efficiency, aesthetic integration, and municipal breed ordinance compliance. E-commerce direct channels and mass retail dominate procurement.
- Dog Trainers:Certified behaviorists require institutional-grade specifications with modular reconfiguration and sanitization surfaces. Professional supply channels with documentation support dominate this segment.
- Kennel Operators:Commercial breeding and boarding facilities face USDA Animal Welfare Act compliance mandates for interstate transport containers. Metal fabrication with ventilation certification sustains replacement cycles.
- Pet Shops:Retail intermediaries stock inventory breadth across price tiers, with private label expansion compressing branded margin capture in standard polymer configurations.
Pet owners represent volume concentration. Dog trainers are where specification premiums expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for dog boxes diverge sharply by geography, with North American procurement driven by regulatory compliance and institutional certification while Asian markets prioritize collapsible portability for urban apartment living.
United States
USDA Animal Welfare Act ventilation mandates and Texas DOT crash-test requirements sustain replacement cycles among commercial kennel operators. FDA oversight applies to grooming boxes contacting topical treatments. Houston and Dallas metro corridors concentrate demand for large-format metal fabrication serving working dog training facilities.
Germany
EU F-Gas Regulation phase-down schedules pressure foam insulation suppliers serving temperature-controlled veterinary transport containers. ECHA REACH compliance documentation requirements inflate SKU validation timelines for polymer fabricators. Blow-molding operations in the Netherlands and western Germany reformulate polyurethane cores to maintain thermal performance envelopes.
China
Domestic pet ownership growth in Shanghai and Beijing metro areas accelerates demand for airline-compliant travel crates as veterinary infrastructure professionalizes. MIIT GB standards govern product safety labeling for polymer fabrication. Manufacturing clusters in Guangdong and Zhejiang provinces dominate virgin and recycled resin supply for North American blow-molding operations.
India
Urban companion animal expansion in Mumbai and Bangalore corridors presents underpenetrated demand for collapsible fabric configurations suited to apartment living. BIS certification requirements for imported pet products create compliance barriers for foreign manufacturers. Maharashtra state veterinary infrastructure investments support institutional-grade procurement from certified behaviorist facilities.
United Kingdom
Post-Brexit divergence from EU veterinary certification frameworks fragments product validation requirements for cross-channel transport services. DEFRA animal welfare transport guidelines tighten ventilation specifications for commercial breeding operations. London and Southeast England concentrate premium-tier demand for artisanal wood craftsmanship serving boutique residential positioning.
Dog Box Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with subscription logistics operators and veterinary-formulated curators commanding premium positioning against commodity polymer fabricators. The competitive terrain stratifies across three archetypes: subscription kit assemblers leveraging recurring revenue infrastructure, durability specialists occupying chew-resistant niches, and mass-manufacturing volume players competing on cost scalability. Dominant competitive moves include backward integration into captive resin supply and strategic partnerships with telehealth platforms for equipment-inclusive wellness bundling.
Among subscription-centric operators, BarkBox and The Farmer's Dog exemplify divergent premium positioning strategies, with the former leveraging logistics network density and the latter anchoring veterinary-formulated curation. Bullymake occupies a defensible specialist position within the durability-focused tier, representing the chew-resistant construction archetype against commodity rivals. These three companies illustrate how channel strategy and material specialization fragment competitive advantage across household penetration versus institutional procurement vectors.
| Leading Market Players |
|---|
| BarkBox |
| PupBox |
| Pet Treater |
| Loot Pets |
| DoggieLawn |
| HempMy Pet |
| The Farmer's Dog |
| Bullymake |
| Fetch Box |
| Others |
Value Network & Pricing Analysis
USDA Animal Welfare Act ventilation mandates and Texas DOT crash-test certifications gate both supplier qualification and price differentiation simultaneously, compressing margin tiers between certified metal fabricators and uncertified polymer producers while fragmenting procurement budgets across compliance tiers.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement from kennel operators and commercial transport services, while spot purchasing persists in residential channels. Pricing stratifies across DOT-certified metal fabrication, FDA-documented grooming configurations, and uncertified polymer alternatives. Cost compression in blow-molded segments is intensifying because resin tariff exposure and logistics fragility erode margin buffers. Pet shops and mass retail intermediaries exhibit highest price sensitivity, whereas certified behaviorist facilities absorb premium positioning for sanitization-grade specifications.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for North American blow-molding operations dependent on Guangdong and Zhejiang resin clusters. Virgin and recycled polymer supply draws from East Asian manufacturing concentration, while aluminum and steel fabrication rests on domestic North American metalworking capacity. Single-source vulnerability in China-dominated resin supply creates tariff exposure and logistics fragility. Distribution runs through veterinary supply wholesalers, mass retail big-box channels, and direct-to-consumer e-commerce platforms with divergent margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with USDA and DOT certification requirements creating switching costs that institutional buyers cannot easily circumvent.
For Market Incumbents: Compound certification depth through backward integration into captive resin formulation and DOT testing laboratory partnerships. Metal fabricators should automate sanitization surface finishing to defend margin position against carbon fiber-reinforced polymer substitution. Kennel operator consolidation threatens volume concentration leverage against suppliers.
For New Entrants and Emerging Players: Telehealth platform equipment bundling represents a service-layer gap where incumbents under-serve direct-to-consumer channels. Veterinary subscription wellness plans offer the most penetrable entry vector. Fabric durability specialists can target working dog training verticals with chew-resistant composite formulations bypassing commodity polymer limitations.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward foam insulation reformulation capabilities and thermal performance engineering. Long-term viability favors vertically integrated specialists with captive resin supply and multi-jurisdiction compliance documentation. Watch USDA ventilation mandate expansion into previously exempt intrastate transport categories as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Integration | Temperature monitoring hardware convergence enables premium tier differentiation for pharmaceutical transport applications. |
| Backward Integration into Resin Supply | Captive polymer formulation mitigates tariff exposure from China-dominated virgin and recycled resin clusters. |
| Veterinary Subscription Bundling | Telehealth platform partnerships create direct-to-consumer channel bypass of traditional retail markups. |
| DOT Crash-Test Certification Investment | Texas and Florida anchoring mandates accelerate procurement of certified metal fabrication among commercial services. |
| Modular Reconfigurable Sizing | Patchwork municipal breed ordinances in Houston and Miami corridors drive property management procurement toward flexible inventory. |
Research Methodology
Desk research of regulatory filing databases, trade customs records, and veterinary industry association publications preceded structured interviews with kennel operations managers, pet product procurement leads at mass retail chains, certified dog behaviorists, DOT compliance officers, and polymer fabrication plant engineers. Primary fieldwork combined with secondary validation across USDA Animal Welfare Act enforcement data, state DOT regulatory updates, and resin import manifests. Bottom-up unit economics and top-down category sizing were triangulated to reconcile demand estimates.
Variance decomposition across product type, material grade, size tier, and end-user segment anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro pet ownership trends and regulatory compliance cycle timing. Modeled inputs included USDA ventilation mandate enforcement intensity, Texas and Florida DOT rulemaking trajectories, and carbon fiber composite cost curves for premium veterinary transport applications.
Material uncertainties — commodity aluminum and steel price volatility, tariff regime shifts affecting East Asian resin supply, and municipal breed ordinance proliferation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and institutional procurement budget stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Italy Pet Food Market
Pet Care Products
Pet Food Bowl Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Dog Vest Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Interactive Dog Toys Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Pet Sitting Market
Pet Care Products
South Korea Organic and Natural Pet Food Market