
 Portable Showers Market | 2026-2036
Portable Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Showers Market Insights
The EU Green Deal is realigning portable shower demand toward low-flow, energy-efficient designs across European distribution channels. Kohler leverages its plumbing heritage to anchor premium electric shower positioning in North American specialty retail. RinseKit competes through patented pressurized systems that eliminate pump dependency for off-grid users. Geyser Systems specializes in thermal efficiency, sustaining margin pools in cold-climate camping segments.
Portable showers are self-contained, pressurized washing units engineered with food-grade reservoirs, 12V or solar thermal heating elements, and flow rates typically between 1.5 and 2.5 gallons per minute for hygiene maintenance where fixed plumbing is absent. Electric showers dominate unit volume through instant heating convenience, while solar showers capture margin expansion among sustainability-weighted outdoor enthusiasts in Western Europe. Manual showers retain cost-sensitive demand in emerging outdoor markets, though inflatable variants are accelerating fastest among ultralight backpacking sub-segments.
The EPA WaterSense program and REACH compliance frameworks are tightening material safety and flow-rate thresholds, forcing redesign cycles among manufacturers serving transatlantic distribution. FDA oversight of antimicrobial reservoir coatings adds testing burden for products marketed to military and rescue end users. Stakeholders must monitor how California's Title 20 appliance efficiency standards propagate to other state-level adoptions, reshaping product development roadmaps and channel eligibility criteria.
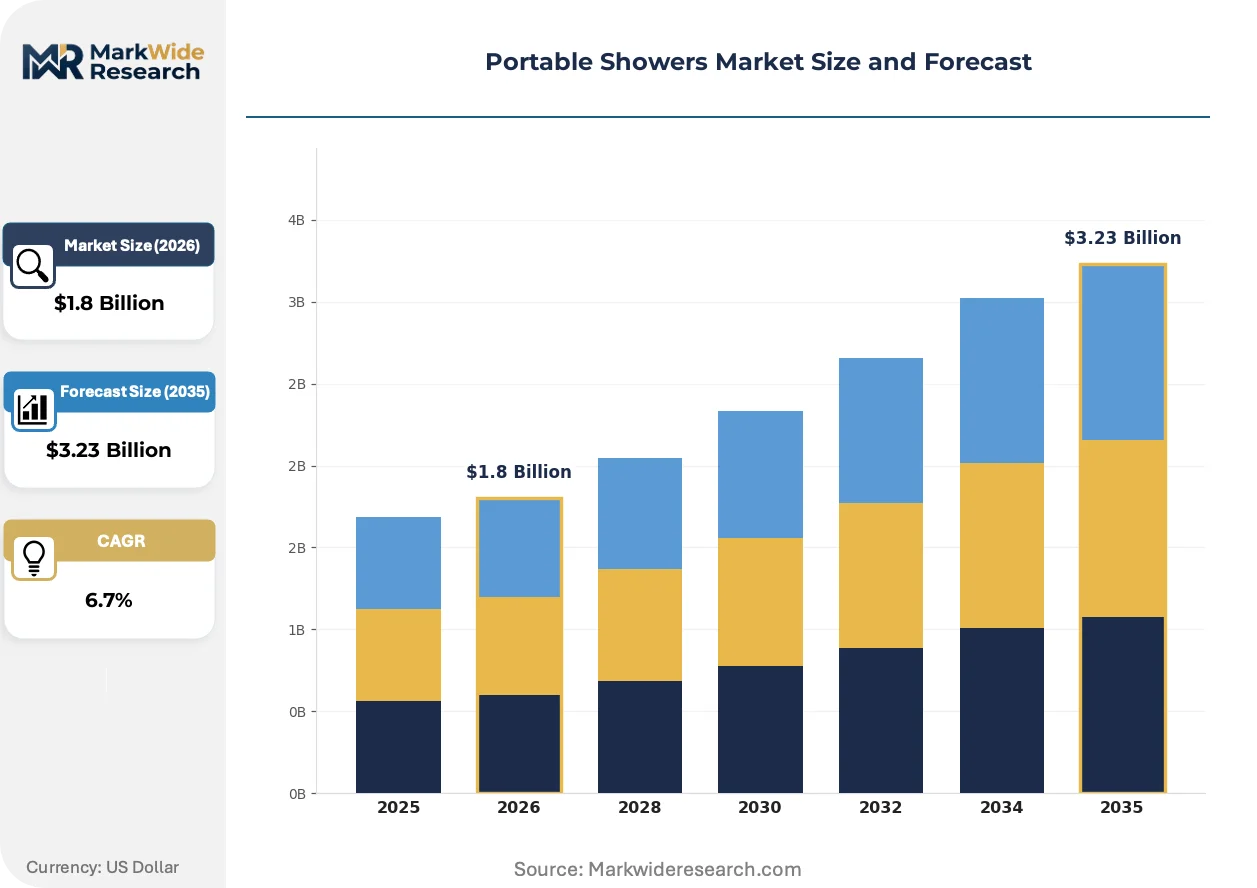
Market Dynamics
The EU Green Deal's product efficiency directives are compressing design cycles across portable shower manufacturing, forcing rapid thermal efficiency upgrades and water-use recertification before 2027 compliance deadlines.
Growth Catalysts
- Outdoor recreation spending:Camping enthusiasts across the United States and Canada are expanding equipment budgets for off-grid hygiene solutions, pulling unit volume through specialty retail channels.
- REACH compliance frameworks:Material safety standards for antimicrobial reservoir coatings are creating certified product premiums in transatlantic distribution, rewarding early compliance investments.
- Solar thermal convergence:Photovoltaic heating elements are capturing sustainability-weighted demand in Western European outdoor markets, displacing propane-dependent alternatives.
Market Restraints
- Food-grade polymer supply concentration:Reservoir material sourcing clusters in Southeast Asian petrochemical corridors, exposing margin volatility to feedstock price swings.
- 12V battery technical limitations:Energy density constraints in lithium-ion cells cap heating duration for electric showers below 15 minutes in sub-zero conditions.
- California Title 20 propagation:Appliance efficiency standards adopted by California are creating fragmented state-level eligibility criteria, complicating national distribution planning.
Strategic Opportunities
- Germany's outdoor equipment retail corridor:Demand concentration in Bavarian and Baden-Württemberg specialty chains offers channel partnership leverage for low-flow certification holders.
- Military and rescue procurement:FDA antimicrobial coating requirements for institutional buyers create defensible margin pools through testing investment amortization.
- Ultralight backpacking channel innovation:Direct-to-consumer inflatable variants are bypassing traditional outdoor retail markups through alpine sports subscription platforms.
Industry Challenges
- Thermal engineering talent scarcity:Cross-disciplinary expertise combining fluid dynamics and photovoltaic integration sits concentrated in German and Japanese research institutes, constraining R&D velocity.
- EPA WaterSense recertification timelines:Flow-rate threshold revisions demand 18-month testing cycles, freezing product launches during regulatory transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Showers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Showers, Solar Showers, Manual Showers, Inflatable Showers Application: Camping, Athletics, Emergency Rescue, Disaster Relief End User: Outdoor Enthusiasts, Event Organizers, Military Personnel, Rescuers Distribution Channel: Online Stores, Retail Outlets, Wholesale Distributors, Specialty Shops |
| Companies Covered | Zodi, RinseKit, Kohler, Dometic, Nemo Equipment, Moen, Geyser Systems, Yakima, Camplux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Showers Market Trends and Innovations
Pressurized system architectures and thermal management protocols are undergoing rapid revision as off-grid power availability and water scarcity reshape functional requirements across camping, emergency response, and mobile hygiene applications.
Phase-change material thermal storage is integrating into portable shower reservoirs to extend heating duration without battery weight penalties. Alpine expedition outfitters in Switzerland and Austria are piloting these systems for multi-day basecamp deployments. The technology is integrating high-altitude performance specifications into premium product roadmaps, compressing development cycles for conventional resistive heating models.
REACH substance restrictions on bisphenol-A alternatives are forcing reservoir polymer reformulation across European manufacturing. Industrial consequence includes 12-month material qualification timelines and supplier audit expansion. Cold-climate camping segments in Scandinavia are responding fastest, accelerating Tritan copolyester adoption ahead of 2026 enforcement windows.
Subscription-based equipment access is displacing ownership models among urban outdoor enthusiasts in France and the Netherlands. Specialty retail channels are unbundling after-sales service into monthly maintenance packages. This pattern is most visible in Paris and Amsterdam metropolitan clusters, where storage constraints and intermittent usage patterns favor rental economics over capital purchase.
Portable Showers Market Segmentation
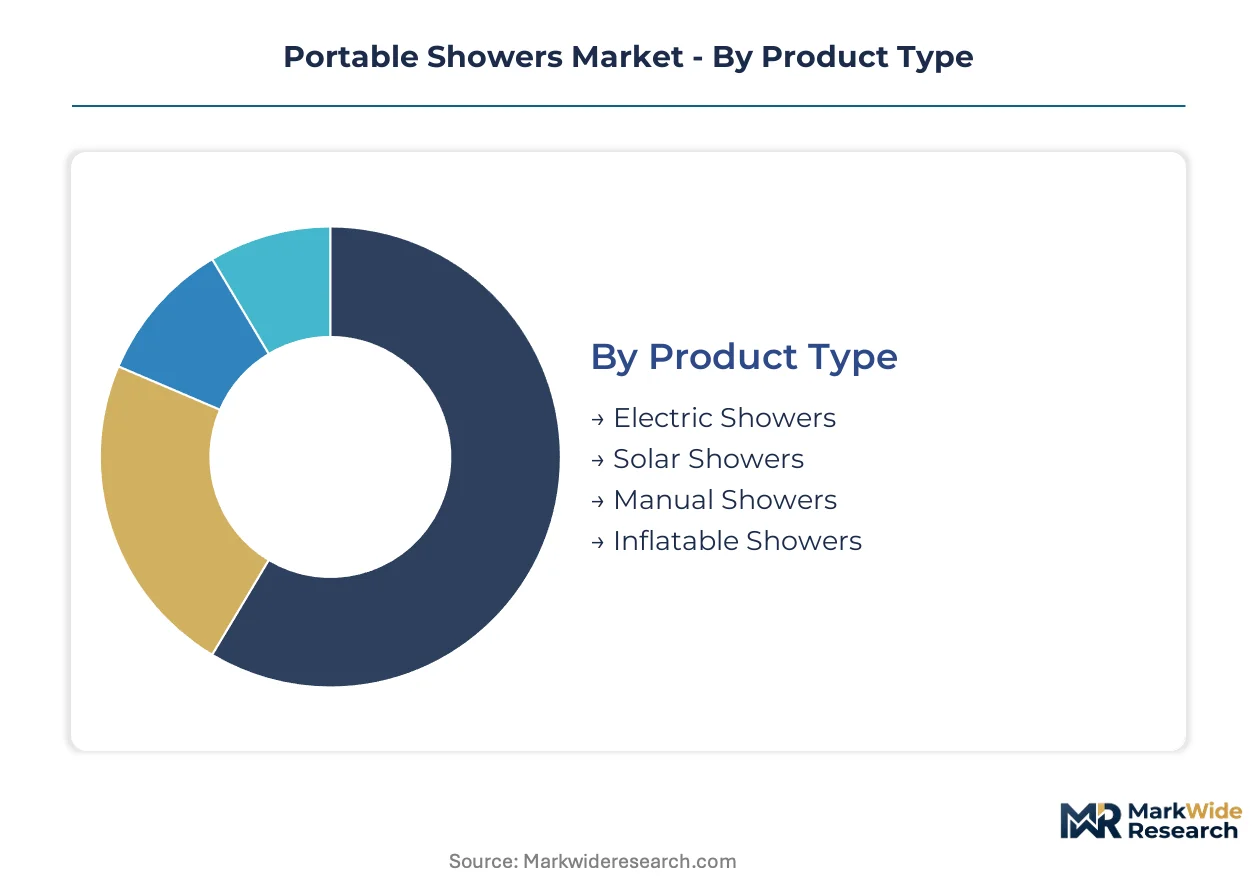
Portable shower manufacturers configure product architectures around thermal source, deployment scenario, and procurement authority. Segment boundaries are hardening as EPA WaterSense flow-rate thresholds and EU Green Deal efficiency mandates force divergent design investments across channels.
Product Type:
Supply concentration clusters around electric heating element sourcing and photovoltaic cell integration capabilities.
- Electric Showers:Instantaneous heating via 12V lithium-ion cells delivers 1.5-2.5 GPM flow rates without solar dependency. Demand concentrates in North American specialty retail where camping enthusiasts prioritize heating reliability over weight penalties.
- Solar Showers:Black polymer reservoirs with photovoltaic-thermal hybrid elements capture sustainability-weighted demand in Western Europe. German outdoor equipment retail corridors favor these units for EU Green Deal compliance positioning.
- Manual Showers:Foot-pump or gravity-fed systems eliminate power requirements entirely. Cost-sensitive emerging markets and ultralight backpacking sub-segments drive residual volume.
- Inflatable Showers:TPU bladder construction with integrated heating coils collapses to sub-liter pack volumes. Alpine sports subscription platforms in France and the Netherlands are accelerating direct-to-consumer adoption.
Today's leader: Electric Showers. Tomorrow's challenger: Inflatable Showers.
Application:
Margin structure varies sharply between recreational discretionary spend and institutional procurement cycles.
- Camping:Recreational vehicle and backcountry tent deployments dominate unit economics. Bavarian and Baden-Württemberg specialty chains in Germany concentrate demand for low-flow certified units.
- Athletics:Post-event hygiene for marathon and triathlon circuits requires rapid deployment. Event organizers in Paris and Amsterdam metropolitan clusters favor rental economics over capital purchase.
- Emergency Rescue:FDA antimicrobial reservoir coating requirements create testing burden and certified product premiums. Military procurement amortizes these investments across multi-year contracts.
- Disaster Relief:NGO and government stockpiling demands ruggedized field deployment specifications. REACH compliance frameworks govern transatlantic distribution eligibility for reservoir materials.
Camping commands volume. Emergency Rescue commands margin.
End User:
Procurement authority determines specification stringency and channel access requirements.
- Outdoor Enthusiasts:Individual consumers purchasing through online stores and specialty shops. California Title 20 appliance efficiency standards constrain product eligibility for this segment.
- Event Organizers:Rental and subscription-based equipment access models displace ownership among urban users. Monthly maintenance packages unbundle after-sales service in French and Dutch metropolitan clusters.
- Military Personnel:Institutional buyers requiring FDA oversight of antimicrobial reservoir coatings. Defensible margin pools emerge through testing investment amortization across multi-year procurement cycles.
- Rescuers:Search-and-rescue and first responder units demand sub-zero operational reliability. Energy density constraints in lithium-ion cells cap heating duration below 15 minutes in extreme cold.
Military Personnel anchor premium tier pricing. Outdoor Enthusiasts drive volume scale.
Distribution Channel:
Channel configuration determines margin capture and regulatory compliance burden allocation.
- Online Stores:Direct-to-consumer platforms bypass traditional retail markups. Subscription-based equipment access models concentrate in French and Dutch urban markets.
- Retail Outlets:Big-box outdoor and sporting goods chains require national distribution planning. Fragmented state-level eligibility criteria complicate inventory management.
- Wholesale Distributors:Bulk procurement for institutional and NGO buyers. REACH and EPA WaterSense recertification timelines freeze product launches during regulatory transition windows.
- Specialty Shops:Bavarian and Baden-Württemberg outdoor equipment retail corridors in Germany offer partnership leverage for low-flow certification holders.
Specialty Shops concentrate premium positioning. Online Stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portable showers emerged from post-war American camping culture before migrating to European outdoor equipment manufacturing. German engineering refined pressurized thermal systems during the 1970s. Today's demand clusters in three continental nodes with divergent regulatory and recreational profiles.
United States
Camping enthusiasts in the Pacific Northwest and Mountain West drive specialty retail volume for electric and propane-heated units. EPA WaterSense flow-rate thresholds constrain product eligibility for national distribution, forcing 18-month recertification cycles. California's Title 20 appliance efficiency standards propagate eligibility fragmentation that complicates inventory planning for big-box outdoor chains.
Germany
Bavarian and Baden-Württemberg outdoor equipment retail corridors concentrate demand for low-flow certified portable showers aligned with EU Green Deal efficiency mandates. REACH substance restrictions on reservoir polymers force 12-month material qualification timelines ahead of 2026 enforcement windows. Stuttgart-based thermal engineering institutes supply scarce cross-disciplinary talent combining fluid dynamics with photovoltaic integration.
France
Paris and Amsterdam metropolitan clusters accelerate subscription-based equipment access models that displace ownership among urban outdoor enthusiasts. The country's national environmental regulator enforces EU Green Deal product efficiency directives through tightened water-use standards. Alpine expedition outfitters in Chamonix pilot phase-change material thermal storage systems for multi-day basecamp deployments.
United Kingdom
Post-event hygiene demand from marathon and triathlon circuits in London and Southeast England favors rapid-deployment rental economics over capital purchase. The Medicines and Healthcare products Regulatory Agency maintains oversight of antimicrobial reservoir coatings for institutional procurement. Scottish Highlands camping segments sustain manual shower volume for cost-sensitive backcountry users.
Japan
Chubu and Kansai industrial regions host concentrated thermal engineering expertise for portable shower R&D partnerships. The Ministry of Economy, Trade and Industry oversees JIS standards compliance for electrical safety in battery-powered heating elements. Tokyo metropolitan outdoor retailers emphasize ultralight inflatable variants for domestic alpine sports subscription platforms.
Portable Showers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and thermal engineering sophistication. The vendor base organizes into three strata: plumbing heritage multinationals with institutional distribution, outdoor equipment specialists with patented pressurized architectures, and regional fabricators serving cost-sensitive emerging markets. Consolidation pressure concentrates among mid-scale players lacking REACH compliance infrastructure or FDA antimicrobial coating certification. Dominant competitive moves include strategic partnerships with alpine sports subscription platforms and backward integration into food-grade polymer reservoir manufacturing.
Within the plumbing heritage tier, Kohler Co. and Moen Incorporated anchor premium electric shower positioning through institutional channel access and thermal engineering scale. Among outdoor equipment specialists, RinseKit and Nemo Equipment exemplify patented pressurized system differentiation that eliminates pump dependency for off-grid users. Geyser Systems occupies a position within thermal efficiency specialization, while Zodi and Camplux represent regional fabrication archetypes with cost-optimized manual and propane-heated portfolios. Dometic and Yakima sit within automotive and cargo systems integration, leveraging vehicle-mounted distribution channels.
| Leading Market Players |
|---|
| Zodi |
| RinseKit |
| Kohler |
| Dometic |
| Nemo Equipment |
| Moen |
| Geyser Systems |
| Yakima |
| Camplux |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal efficiency mandates are forcing rapid thermal engineering redesigns across portable shower manufacturing, compelling suppliers to absorb certification costs or pass them downstream while buyers consolidate around low-flow certified vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified antimicrobial units from REACH-compliant European models from basic manual systems. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Southeast Asian fabricators are flooding emerging markets with non-compliant manual variants. Event organizers and subscription platforms show least price sensitivity due to rental economics, while individual outdoor enthusiasts in cost-sensitive segments drive hard bargaining.
Supply Chain Analysis
Thermal engineering talent shortages in Stuttgart and Nagoya constrain R&D velocity for manufacturers dependent on cross-disciplinary expertise. Food-grade polymer reservoir production clusters in Thailand and Vietnam, while photovoltaic cell integration capabilities concentrate in China and South Korea. Supply chain risk centers on single-source vulnerability for Tritan copolyester alternatives ahead of REACH bisphenol-A enforcement. Distribution runs through Bavarian specialty retail corridors for premium positioning and direct-to-consumer platforms for inflatable variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as institutional procurement shifts toward FDA-certified antimicrobial specifications that amortize testing investments across multi-year contracts.
For Market Incumbents: Acquire thermal engineering talent pools in German research institutes before photovoltaic-thermal hybrid designs commoditize. Lock in backward integration into food-grade polymer reservoir manufacturing to defend margin pools against feedstock volatility. Counter RinseKit's patented pressurized architecture by embedding phase-change material thermal storage into premium product roadmaps. For New Entrants and Emerging Players: Alpine sports subscription platforms in France and the Netherlands offer the most penetrable route for inflatable TPU bladder variants bypassing traditional retail markouts. Target ultralight backpacking sub-segments through direct-to-consumer channels with sub-liter pack volume positioning. Exploit REACH compliance gaps among mid-scale European fabricators unable to absorb 12-month material qualification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with outdoor equipment specialists holding FDA antimicrobial coating certification and institutional military procurement relationships. Five-to-ten year viability favors players with defensible testing investment amortization rather than commodity manual shower fabricators. Watch EPA WaterSense recertification timeline delays as inflection indicator for product launch freezes that concentrate share among compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reservoir Manufacturing | Captive supply of Tritan copolyester insulates margins from REACH-driven polymer reformulation costs. |
| Phase-Change Material Thermal Storage Integration | Extends heating duration without battery weight penalties for Alpine basecamp deployments in Switzerland. |
| FDA Antimicrobial Coating Certification | Creates defensible margin pools through testing investment amortization across military procurement cycles. |
| Direct-to-Consumer Subscription Launch | Bypasses Bavarian retail markups while capturing urban outdoor enthusiasts in Paris and Amsterdam clusters. |
| Photovoltaic-Thermal Hybrid R&D Partnership | Leverages Stuttgart engineering institutes to accelerate EU Green Deal compliance ahead of 2027 deadlines. |
Research Methodology
Coverage spans North America, Western Europe, and East Asia, with primary inputs from each region combining interviews with outdoor equipment procurement managers, thermal engineering directors, specialty retail buyers, and military contract officers alongside secondary validation from EPA WaterSense filings, ECHA REACH substance restriction updates, EU Green Deal directive texts, and customs trade data for food-grade polymer imports. Bottom-up segment sizing triangulates against top-down macroeconomic outdoor recreation spending indicators.
Granularity-level modeling disaggregates volume and value across thermal source type, deployment scenario, procurement authority tier, and regional regulatory cluster throughout the forecast period. CAGRs derive from installed base replacement cycles, efficiency standard adoption curves, and channel shift elasticity parameters. Industry-specific inputs include lithium-ion cell energy density improvement trajectories and alpine sports subscription platform penetration rates.
The model assumes a particular technology adoption path; alternative pathways for solid-state thermal storage would alter the outlook if phase-change materials fail to achieve cost parity with resistive heating. Forecasts reflect assumptions around REACH enforcement timing and EPA recertification cycle duration. Material deviation in California Title 20 propagation patterns or EU Green Deal compliance deadline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Mirror Holder Market
Household Items
Water Purifier Bottle Market
Household Items
Water Purifier Market
Household Items
Thermos Drinkware Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Collapsible Water Bottle Market
Household Items
Drinkware Accessories Market
Household Items
Washing Capsules Market
Household Items
Toilet Care Wipes Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Candle Air Fresheners Market
Household Items
Europe Hand Dryers Market
Household Items
Command Hooks Market
Household Items
North America Car Air Freshener Market
Household Items
Household Sewing Machines Market
Household Items
Beach Towel Market