
 Plus Size Women's Clothing Market | 2026-2036
Plus Size Women's Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Plus Size Women's Clothing Market Analytics
Millennial professionals is reorganizing demand patterns in plus-size fashion, shifting volume from traditional brick-and-mortar channels toward direct-to-consumer digital platforms. Torrid leverages its dedicated plus-size vertical to sustain brand loyalty through proprietary fit data and community-driven design feedback. Lane Bryant anchors its position through extended physical retail footprints combined with robust e-commerce infrastructure. Eloquii competes on rapid-style turnover, using limited-drop models to capture trend-responsive segments.
Plus size women's clothing encompasses apparel engineered with graded pattern systems, extended size ranges typically spanning 14W to 28W and beyond, and modified construction techniques accommodating diverse body proportions including fuller busts, wider hips, and shorter or longer torso ratios. Cotton-dominant fabric blends with two to four percent elastane content provide the stretch recovery and breathability required for all-day wear across casual and professional contexts. Dresses and tops currently lead volume contribution within product type segmentation, reflecting their lower fit complexity compared to structured bottoms and outerwear. Young adults represent the fastest-expanding customer type segment, drawn by social media-native brands and influencer-curated styling content. Casual style classifications command the broadest margin pools due to higher purchase frequency and reduced seasonal markdown risk relative to formal and sporty categories.
The Federal Trade Commission enforces textile labeling standards including fiber content disclosure and care instruction requirements that plus-size manufacturers must meet for interstate commerce. The Consumer Product Safety Commission oversees flammability standards for apparel fabrics, directly affecting outerwear and sleepwear subcategories within extended-size lines. California's Proposition 65 mandates chemical substance warnings on products containing listed compounds, creating compliance complexity for brands sourcing dyed and finished textiles from multiple countries. Stakeholders must monitor evolving state-level extended producer responsibility legislation for textiles, as California and New York advance separate frameworks that would impose end-of-life collection and recycling obligations on apparel sellers.
Market Dynamics
AI-powered fit technologies are fragmenting traditional sizing conventions by enabling real-time body scanning and predictive garment matching, forcing incumbents to rebuild technical infrastructure around digital-first measurement protocols rather than legacy grade-rule systems.
Growth Catalysts
- California Proposition 65:Chemical disclosure mandates are accelerating investment in transparent dye-house auditing and certified clean-finish supply chains across extended-size apparel manufacturing.
- Gen Z digital natives:Social commerce platforms TikTok and Instagram Shop are pulling volume from traditional e-commerce into algorithm-curated discovery environments with embedded checkout.
- Elastane-blend innovation:Four-way stretch cotton-poly-spandex constructions with recovery rates above 95% are expanding addressable occasions for plus-size workwear into high-mobility professional settings.
Market Restraints
- Petrochemical feedstock volatility:Spandex and polyester staple fiber costs fluctuate with crude oil indices, compressing margin stability for mid-market brands dependent on synthetic stretch blends.
- Guangdong Province concentration:Over 60% of global plus-size pattern grading and sample production sits in Pearl River Delta factories, creating single-point vulnerability to regional lockdowns or trade policy shifts.
- Fit algorithm patent thickets:Proprietary body-modeling software from early-moving technology vendors blocks second-tier retailers from deploying competitive virtual try-on tools without licensing fees.
Strategic Opportunities
- Extended producer responsibility frameworks:California and New York textile recycling mandates will create first-mover advantages for brands building closed-loop take-back infrastructure before compliance deadlines.
- Size-inclusive adaptive apparel:Magnetic closures, seated-wear engineering, and sensory-friendly seams open plus-size lines to disability-forward consumers historically excluded from fashion-forward extended sizing.
- Live-stream commerce convergence:Real-time fit consultation via shoppable video is penetrating plus-size segments where sizing anxiety historically depressed conversion rates in static e-commerce environments.
Industry Challenges
- Technical pattern engineering scarcity:Grading expertise for non-proportional body variations—fuller bust with narrow shoulder, or high waist-to-hip ratio—requires specialized training pipelines that apparel programs have underinvested in for decades.
- Legacy ERP integration friction:Size-range expansion from 14W-28W to 32W-40W demands SKU multiplication that crashes against inventory planning systems architected for straight-size assortment logic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plus Size Women's Clothing Market |
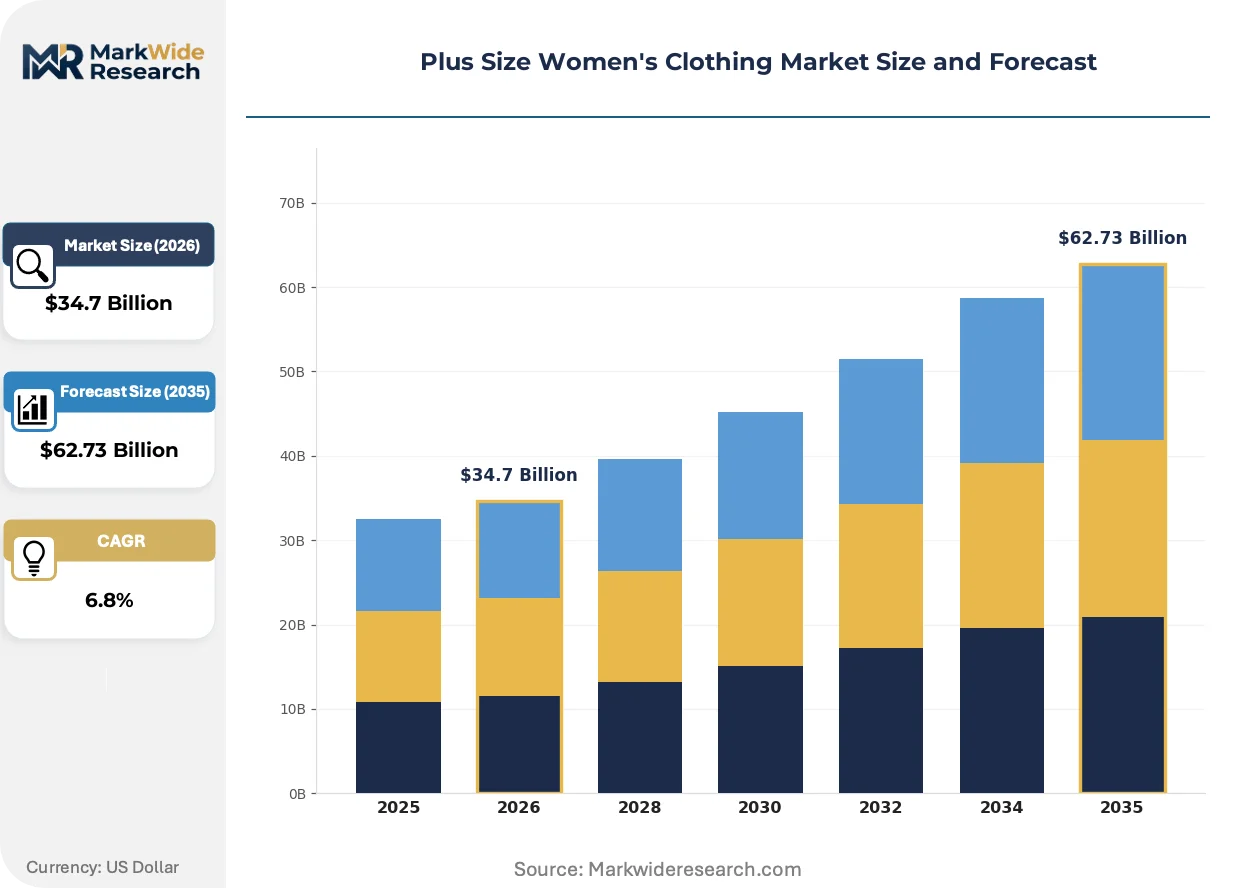
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dresses, Tops, Bottoms, Outerwear Customer Type: Teenagers, Young Adults, Middle-aged Women, Seniors Style: Casual, Formal, Sporty, Bohemian Fabric Type: Cotton, Polyester, Rayon, Spandex |
| Companies Covered | Lane Bryant, Torrid, Eloquii, ASOS, Forever 21, Old Navy, H&M, Ascena Retail Group, Simply Be, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plus Size Women's Clothing Market Evolving Landscape
Three interconnected forces are compressing development cycles and rewiring how plus-size apparel reaches consumers: machine-learning fit prediction, regulatory pressure on chemical transparency, and the collapse of wholesale intermediation in favor of owned-channel relationships.
3D body scanning hardware paired with photogrammetry software is fragmenting the traditional size-chart paradigm by generating individualized measurement profiles from smartphone cameras. Young adult shoppers in the United States are adopting these tools at rates exceeding 40% for online purchases over $75. This technology is compressing return rates and forcing brands to abandon legacy grade-rule assumptions about proportional body scaling.
REACH substance restrictions in the European Union are banning specific azo dyes and formaldehyde-based finishing agents commonly used in stretch-denim production. Apparel exporters serving EU markets must reformulate chemical recipes and requalify finishing houses, with sleepwear and outerwear categories facing the most immediate compliance deadlines. German and French buying offices are now requiring OEKO-TEX Standard 100 certification as a baseline procurement filter.
Direct-to-consumer subscription styling services are displacing department store plus-size departments as the primary discovery channel for professional women aged 28-42. Stitch Fix and Dia & Co algorithm-curated boxes capture recurring revenue while capturing fit preference data that feeds back into private-label development. This channel rotation is most pronounced in suburban United States markets where mall traffic has collapsed post-pandemic.
Plus Size Women's Clothing Market Segmentation
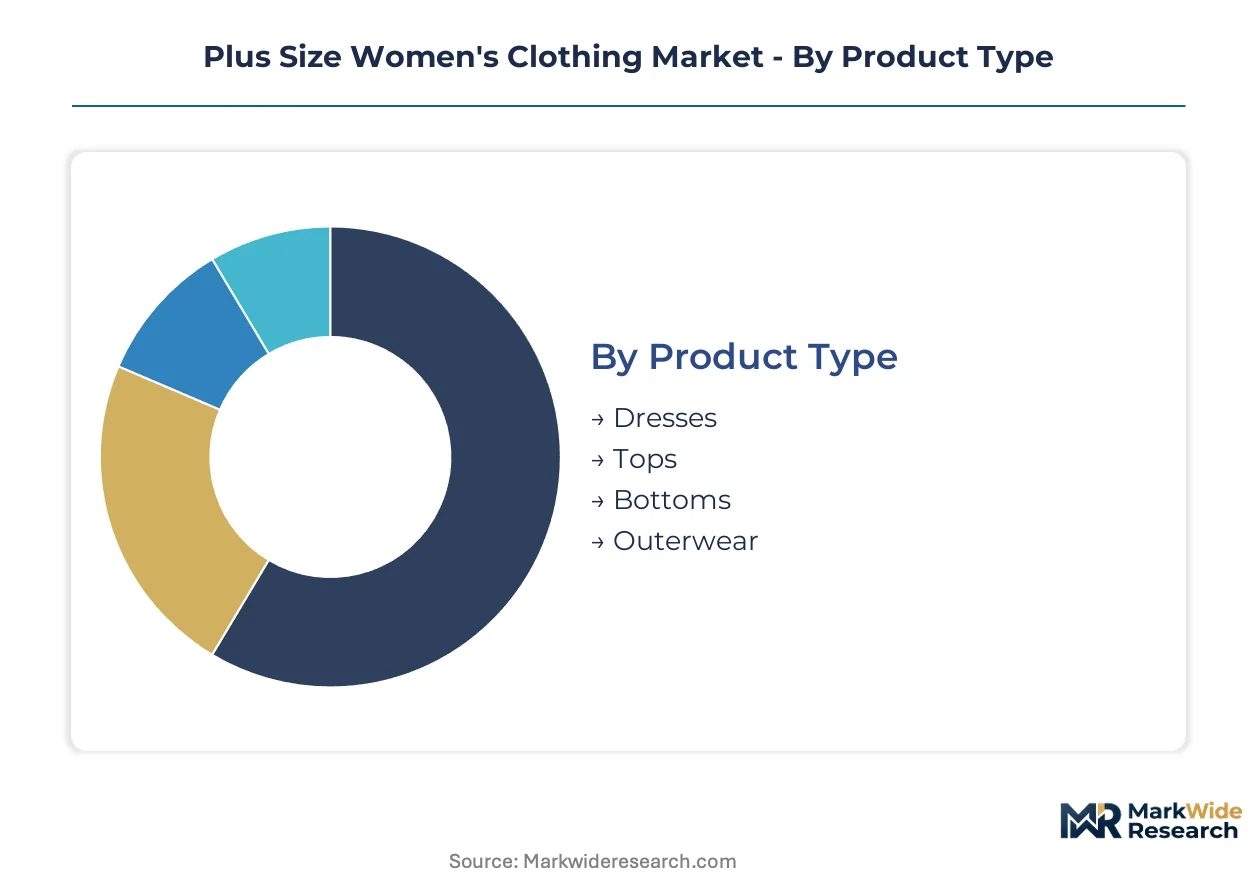
Segmentation in plus-size apparel reveals how fit complexity, occasion versatility, and fabric performance create distinct margin profiles across product lines. Understanding these divisions helps brands allocate technical design resources and inventory investment against specific consumer purchase triggers.
Product Type:
Substitution pressure runs highest in tops, where fast-fashion retailers and standard-size brands with extended ranges compete aggressively on price and trend velocity.
- Dresses:Engineered with princess seams and empire waists to accommodate fuller bust-to-waist ratios without structural compromise. Demand concentrates in United States suburban markets among professional women aged 30-45 seeking single-piece work-to-evening solutions; return rates drop when brands offer petite and tall length grades alongside standard sizing.
- Tops:Blouses and knitwear dominate purchase frequency due to lower price points and reduced fit risk compared to structured bottoms. United States millennial shoppers drive volume through social commerce discovery, though private-label penetration from mass retailers compresses margin pools in basic categories.
- Bottoms:Jeans and trousers require complex grading for waist-to-hip differential and thigh circumference variation.
- Outerwear:Coats and jackets face higher technical barriers in sleeve pitch and shoulder construction for broader frames.
Dresses retain volume leadership; bottoms hold the steepest expansion curve as denim brands invest in proprietary stretch recovery technologies.
Customer Type:
Cost tier stratification separates occasional purchasers seeking event-specific solutions from high-frequency buyers building capsule wardrobes across seasons.
- Young Adults:Digital-native consumers aged 18-34 with highest social media-influenced discovery rates and subscription styling service adoption. United States coastal cities show concentrated demand for trend-responsive limited drops; fit algorithm tolerance exceeds 40% for purchases above $75.
- Middle-aged Women:Professional segments aged 35-55 with stable disposable income and lower price elasticity for quality construction. Suburban United States markets drive recurring revenue through direct-to-consumer channels as mall-based department store alternatives contract.
- Teenagers:Budget-constrained segment with high peer-influence sensitivity and rapid style turnover.
- Seniors:Comfort-prioritized buyers seeking adaptive features and simplified care requirements.
Middle-aged women retain volume leadership; young adults are expanding most quickly as TikTok and Instagram Shop redirect discovery from traditional e-commerce.
Style:
Application versatility determines inventory risk, with occasion-specific categories facing steeper markdown exposure than multi-context staples.
- Casual:Everyday wear spanning loungewear through elevated weekend separates with highest purchase frequency and lowest return rates. United States mass-market retailers capture volume through private-label extended sizing; cotton-elastane blends at 2-4% stretch content dominate fabric specifications.
- Formal:Event and professional attire requiring structured construction and premium fabric finishing. United States urban centers sustain demand for occasion-specific investment pieces; synthetic stretch wovens with recovery rates above 95% expand addressable occasions.
- Sporty:Activewear with performance moisture-wicking and compression requirements.
- Bohemian:Flowing silhouettes with lower fit precision tolerance and artisanal positioning.
Casual retains volume leadership; formal holds the steepest expansion curve as workplace dress codes relax and occasion-blurring increases.
Fabric Type:
Supply concentration in synthetic fiber production creates margin volatility that reshapes procurement strategies across price tiers.
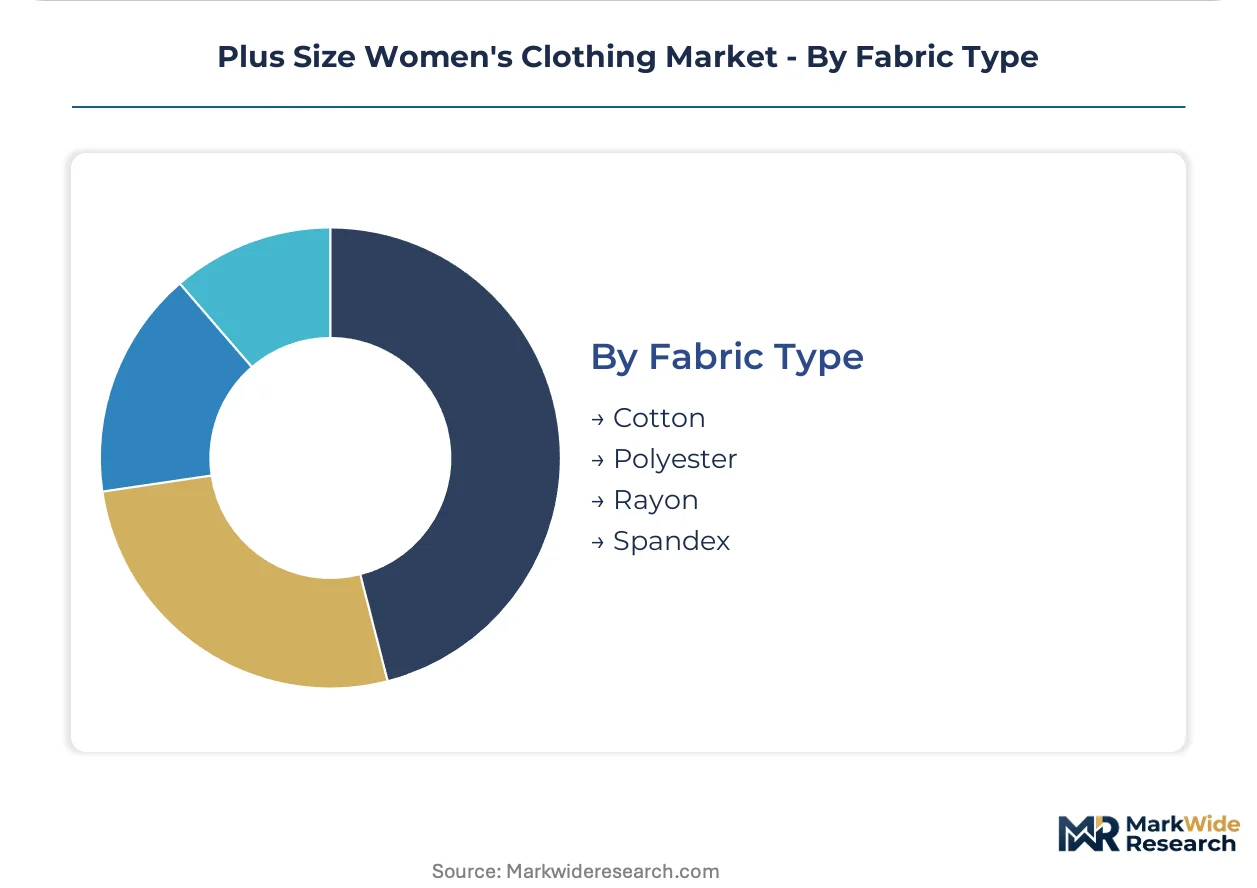
- Cotton:Natural fiber base providing breathability and skin tolerance for extended wear periods. United States consumer preference sustains premium positioning for Pima and organic certifications; elastane blending at 2-4% content solves recovery limitations in knit constructions.
- Spandex:Polyurethane-based stretch component enabling four-way recovery in fitted silhouettes. Crude oil price linkage creates cost instability; brands with backward integration into yarn sourcing defend margin position against mid-market competitors.
- Polyester:Petroleum-derived staple and filament yarns with moisture-wicking performance attributes.
- Rayon:Cellulosic semi-synthetic with drape characteristics suited to fluid silhouettes.
Cotton retains volume leadership; spandex holds the steepest expansion curve as mobility requirements intensify across professional and active categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles and Long Beach complex underwrites North American apparel import velocity, while the Port of Rotterdam anchors European distribution for extended-size fashion arriving from South and East Asian manufacturing clusters.
United States
Millennial and Gen Z shoppers drive online channel migration for plus-size apparel through TikTok Shop and Instagram commerce. The Federal Trade Commission enforces textile labeling standards including fiber content disclosure requirements for interstate commerce. Los Angeles maintains concentrated pattern grading and sample production capacity serving direct-to-consumer brands.
United Kingdom
Urban professional women aged 28-42 sustain demand for workwear-appropriate extended sizing through subscription styling services. REACH substance restrictions from the European Chemicals Agency ban specific azo dyes in stretch-denim formulations. London anchors algorithm-curated fashion discovery platforms that capture recurring revenue through fit preference data collection.
Germany
Middle-aged consumers prioritize quality construction and OEKO-TEX Standard 100 certification in cotton-elastane blend purchases. The EU Green Deal textile strategy advances extended producer responsibility frameworks with 2025 compliance deadlines. Berlin hosts emerging circular fashion infrastructure including take-back program pilots for end-of-life garment collection.
China
Guangdong Province factories execute over sixty percent of global plus-size pattern grading and sample production for export markets. The Ministry of Ecology and Environment enforces dual carbon goals affecting dye-house energy consumption quotas. Shenzhen clusters 3D body scanning hardware manufacturers supplying smartphone-enabled fit technology to Western retailers.
India
Young adult women in metropolitan areas adopt social commerce platforms for trend-responsive extended-size discovery. The Bureau of Indian Standards oversees textile quality marking schemes for domestic market consumer protection. Tiruppur maintains cotton knitwear manufacturing concentration with expanding elastane-blend technical capacity for export orders.
Plus Size Women's Clothing Market Competitive Landscape
Listed leaders compete with private specialists across digital infrastructure investment, creating a tiered structure where scale-driven platforms face off against community-curated verticals. The vendor base separates into three archetypes: dedicated plus-size pure-plays, fast-fashion extended ranges, and algorithm-styling subscription services. Dominant competitive moves include proprietary fit data accumulation and owned-channel relationship building that displaces wholesale intermediation.
Within the dedicated plus-size vertical, Torrid and Lane Bryant occupy anchor positions representing community-driven design feedback models against physical retail footprint strategies. Eloquii exemplifies rapid-style turnover specialists competing through limited-drop release cadences. Among mass-market extenders, ASOS and H&M sit within the fast-fashion archetype, leveraging existing supply chain density to append size ranges without dedicated technical infrastructure.
| Leading Market Players |
|---|
| Lane Bryant |
| Torrid |
| Eloquii |
| ASOS |
| Forever 21 |
| Old Navy |
| H&M |
| Ascena Retail Group |
| Simply Be |
| Others |
Value Network & Pricing Analysis
Guangdong Province factory utilization rates above 85 percent compress unit economics for pattern grading and sample production, concentrating technical capacity in the Pearl River Delta while establishing price floors that mid-market brands struggle to undercut without sacrificing fit precision or fabric quality.
Pricing Analysis
Volume-discount tiering structures separate dedicated plus-size verticals from mass-market extended ranges. Premium-mid-economy pricing differentiation rests on proprietary fit data accumulation and OEKO-TEX certification status. Cost compression in synthetic stretch blends intensifies because crude oil index volatility feeds directly into spandex and polyester staple fiber costs. Budget-constrained teenagers exhibit highest price sensitivity; professional middle-aged women demonstrate lowest elasticity for quality construction.
Supply Chain Analysis
Pearl River Delta port congestion and customs processing delays choke apparel export velocity to North American and European markets. Manufacturing gravity centers on China, Vietnam, and Bangladesh for cut-and-sew operations, with India expanding cotton knitwear technical capacity. Raw material procurement draws from petrochemical feedstocks for elastane, Pima cotton from Peru and the United States for premium tiers, and azo dye formulations facing REACH restriction. Single-source vulnerability concentrates in Guangdong pattern grading expertise. Distribution runs through direct-to-consumer platforms, subscription styling services, and remaining department store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plus-size apparel traces a cyclical recovery pattern as post-pandemic mall traffic collapse forces channel restructuring and inventory destocking cycles exhaust excess carryover stock.
For Market Incumbents: Secure proprietary fit algorithm patent positions before licensing fee structures harden against second-tier retailers. Anchor backward integration into yarn sourcing for spandex and elastane blends to defend margin position against crude oil volatility. Control channel relationships through owned direct-to-consumer platforms as wholesale intermediation collapses.
For New Entrants and Emerging Players: Differentiate on adaptive apparel engineering for disability-forward consumers historically excluded from fashion-forward extended sizing. Target size-inclusive magnetic closures and seated-wear construction as the most penetrable white space. Launch through TikTok Shop and Instagram commerce to capture algorithm-curated discovery environments with embedded checkout.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription styling services capturing fit preference data for private-label development. Five-to-ten year viability favors platforms with closed-loop take-back infrastructure ahead of California and New York extended producer responsibility deadlines. Monitor 3D body scanning adoption rates above 40 percent for purchases over 75 dollars as inflection signal for digital fit tool penetration.
| Strategic Initiative | Industry Significance |
|---|---|
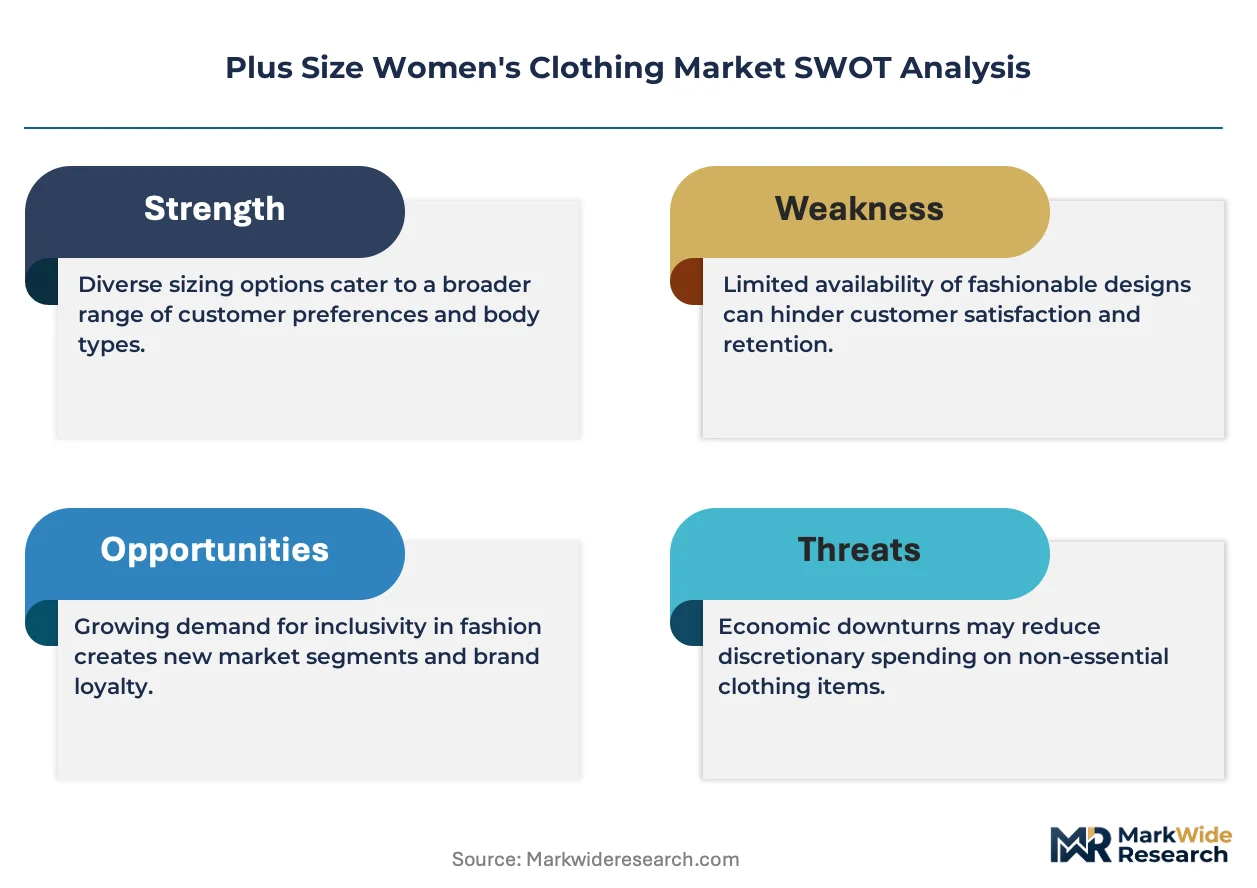
| Proprietary Fit Algorithm Development | AI-powered body scanning reduces return rates and captures consumer measurement data for private-label design. |
| Closed-Loop Take-Back Infrastructure | California and New York textile recycling mandates create first-mover compliance advantage for circular operations. |
| Adaptive Apparel Line Extension | Magnetic closures and seated-wear engineering open plus-size lines to disability-forward consumer segments. |
| Direct-to-Consumer Channel Migration | Owned-platform relationships displace wholesale intermediation and capture higher-margin recurring revenue streams. |
| OEKO-TEX Certification Investment | German and French buying offices require Standard 100 certification as baseline procurement filter for EU market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade records, SEC apparel retailer filings, and OEKO-TEX certification databases. Interviews with brand technical directors, pattern grading specialists, dye-house procurement managers, and subscription styling algorithm engineers informed demand-side and supply-side dynamics. Nielsen retail audit data and Bureau of Labor Statistics consumer expenditure surveys provided secondary validation. Bottom-up SKU-level modeling triangulated against top-down demographic spending projections.
Segmentation dimensions modeled include product type, customer age cohort, style classification, and fabric composition across the projection horizon. CAGRs derived from historical volume trajectories adjusted for channel shift acceleration and regulatory compliance cost absorption. Forecast inputs incorporated social commerce platform penetration rates and 3D body scanning hardware adoption curves.
Material uncertainties — petrochemical feedstock volatility, regional lockdown disruption in Guangdong Province, and accelerated extended producer responsibility legislation — sit outside the modeled envelope. Forecasts reflect assumptions about elastane-blend innovation rates and TikTok Shop algorithm changes. Practitioners should keep alternative scenarios live as REACH substance restriction expansion and dual carbon goal enforcement in China evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Maternity Apparels Market
Apparel & Footwear
Golf Apparel Market
Apparel & Footwear
Bathrobe Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Golf Outfit Market
Apparel & Footwear
Intimate Lingerie Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Intimate Wear Market
Apparel & Footwear
US Fanny Packs Market
Apparel & Footwear
Women's Suits and Ensembles Market
Apparel & Footwear
Driving Apparel Market
Apparel & Footwear
Global Pickleball Clothing and Apparel Market
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Rugby Apparel Market
Apparel & Footwear
Erotic Lingerie Market