
 Cloud Service Assurance Market | 2026-2036
Cloud Service Assurance Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Service Assurance Market Outlook
Enterprise-grade SLA compliance is rotating from reactive uptime guarantees toward predictive availability engineering with sub-second fault detection. IBM Cloud leverages its Red Hat integration to sustain hybrid orchestration capabilities across regulated industries. Microsoft Azure anchors government cloud certifications in North America and Europe. Broadcom differentiates through network performance telemetry that extends visibility into 5G core-to-cloud pathways.
Cloud service assurance encompasses the systematic monitoring, management, and optimization of distributed computing resources to guarantee contractual performance thresholds, typically measured through mean time to detection, mean time to resolution, and availability percentages exceeding 99.99%. The discipline integrates automated remediation, synthetic transaction testing, and cross-domain correlation to prevent revenue-impacting outages in digital service delivery. Hybrid Cloud deployments occupy the highest-margin segment as enterprises retain sensitive workloads on-premises while bursting transactional loads to public infrastructure. Security services within the Service Type dimension are expanding fastest as zero-trust architectures and encryption-in-transit mandates proliferate across regulated verticals.
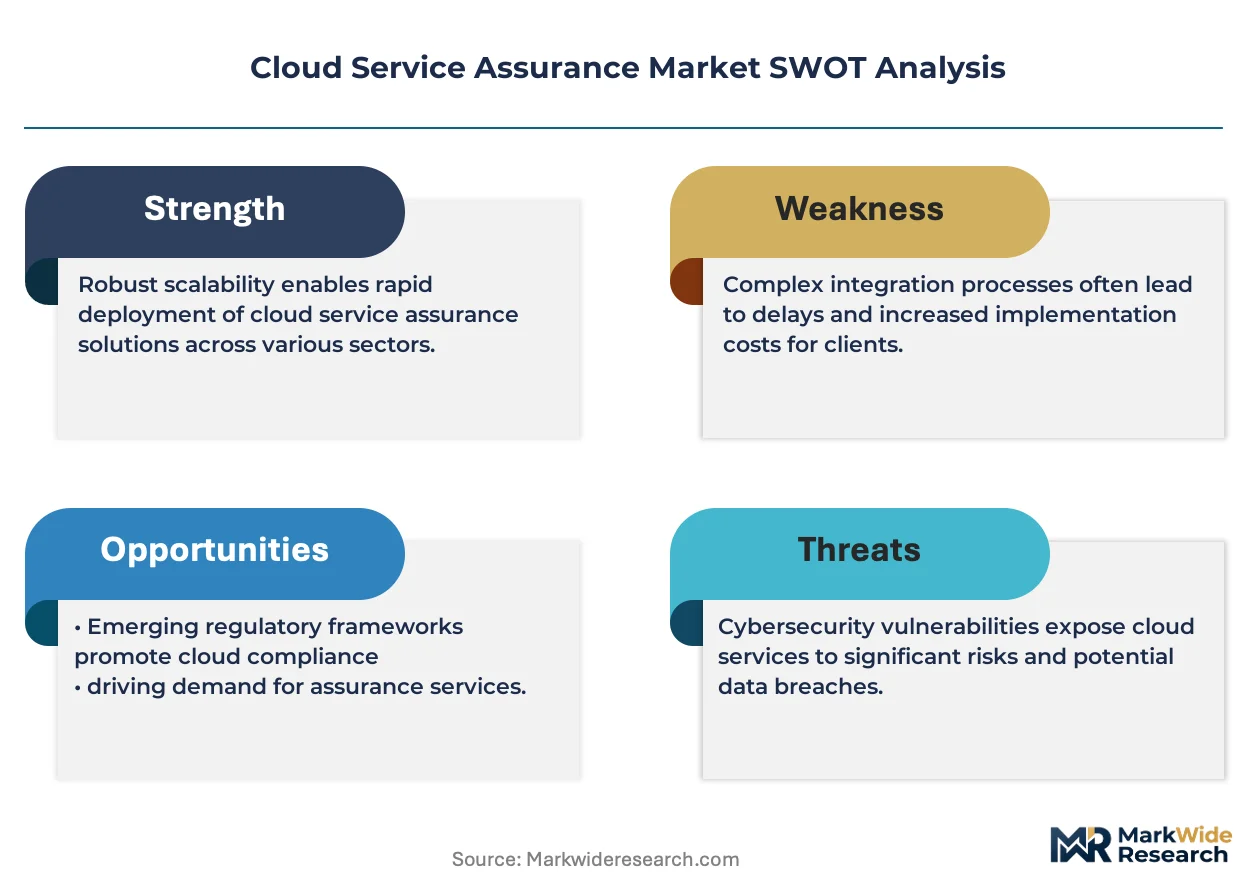
FCC guidelines on communications infrastructure reliability, EU NIS2 requirements for critical ICT service providers, and ISO 27017 cloud security standards collectively elevate baseline compliance costs while disqualifying under-invested vendors from enterprise procurement cycles. The EU AI Act introduces additional algorithmic transparency obligations for AI-infused assurance tools processing personal data in European jurisdictions. Stakeholders must weigh sovereign cloud mandates against the operational complexity of fragmented regulatory compliance across deployment footprints.
Market Dynamics
Enterprise migration to sovereign cloud architectures is fragmenting traditional assurance frameworks as regulators in Germany, France, and Singapore impose data residency mandates that conflict with centralized monitoring models.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident reporting timelines for critical ICT providers are forcing financial institutions and healthcare operators to upgrade observability stacks, creating replacement demand across European member states.
- 5G Standalone Core Deployments:Telecommunications operators rolling out network slicing capabilities require end-to-end latency monitoring that extends from radio access to cloud-native network functions.
- Industrial Cloud Clusters:Germany's Gaia-X initiative and similar sovereign infrastructure programs in France are mandating assurance tooling that operates entirely within jurisdictional boundaries.
Market Restraints
- Specialized Engineering Talent Scarcity:Expertise in OpenTelemetry instrumentation and eBPF kernel programming concentrates in Silicon Valley and Bangalore, inflating implementation costs for enterprises elsewhere.
- Observability Data Storage Costs:Petabyte-scale telemetry retention requirements for compliance with SEC and FCA audit trails consume 30-40% of assurance program budgets.
- Fragmented API Standards:Each hyperscaler maintains proprietary metrics formats, forcing middleware translation layers that degrade real-time correlation accuracy.
Strategic Opportunities
- Edge-to-Cloud Continuum Assurance:Manufacturing and autonomous vehicle deployments in Japan and South Korea require monitoring that spans factory floor PLCs through regional cloud zones.
- AI-Infused Anomaly Detection:Convergence of large language models with time-series databases enables natural language querying of system telemetry, lowering analyst training barriers.
- Federal Cloud Certification Pathways:FedRAMP High and IL6 authorization processes in the United States create multi-year competitive moats for vendors achieving authorization.
Industry Challenges
- Certification Timeline Compression:ISO 27017 and SOC 2 Type II audit cycles now overlap with quarterly product releases, straining engineering resources at mid-tier vendors.
- Mainframe Integration Complexity:Financial services institutions running COBOL-based core banking systems struggle to extract telemetry compatible with cloud-native observability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Service Assurance Market |
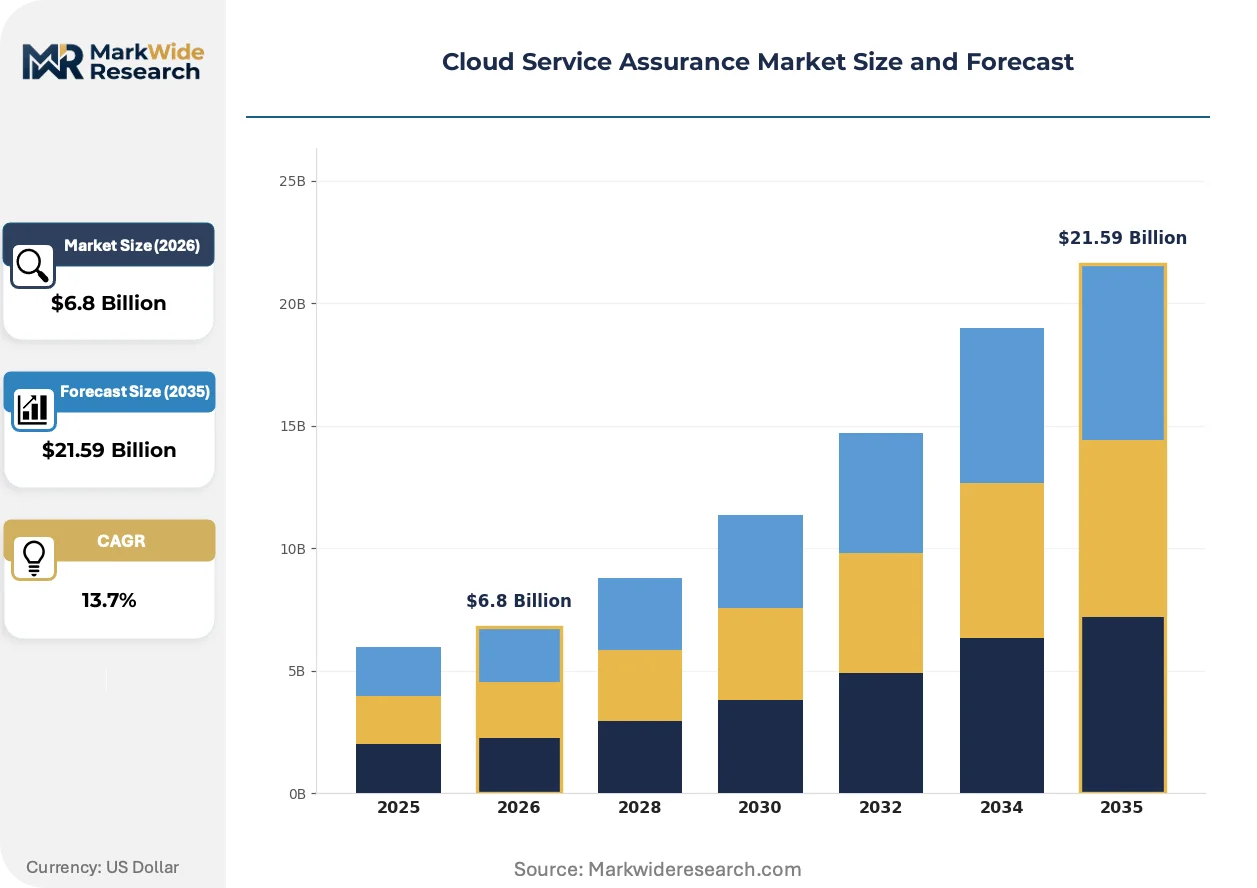
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Monitoring, Management, Security, Compliance End User: Small Enterprises, Medium Enterprises, Large Corporations, Government Agencies Solution: Automation Tools, Analytics Platforms, Incident Management, Performance Optimization |
| Companies Covered | IBM Cloud, Infovista, Amazon Web Services, Accenture, Broadcom, Microsoft Azure, Oracle Cloud Infrastructure, Ericsson, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Service Assurance Market Strategic Shifts
OpenTelemetry is fragmenting proprietary agent ecosystems as standardization efforts gain traction across vendor communities. This shift is compressing differentiation strategies and forcing incumbents to compete on data platform performance rather than capture mechanisms.
eBPF-based kernel instrumentation is fragmenting traditional agent-based monitoring approaches. Cloud-native enterprises in fintech and gaming verticals are adopting these capabilities for zero-overhead telemetry extraction. The technology is fragmenting the APM market by collapsing the distinction between infrastructure and application monitoring layers.
The EU AI Act's risk classification framework for automated decision systems is mandating algorithmic audit trails for assurance tools processing personal data. Financial services operators in Frankfurt and Paris must now document how anomaly detection models arrive at incident classifications. Vendors are responding by embedding explainability modules that surface feature importance scores alongside alerts.
Consumption-based pricing for observability platforms is displacing per-seat licensing models that dominated the 2015-2022 period. Enterprise buyers in retail and logistics verticals now negotiate contracts indexed to data volume rather than user count. This pattern is most pronounced in North American and Australian markets where FinOps practices have matured.
Cloud Service Assurance Market Segmentation
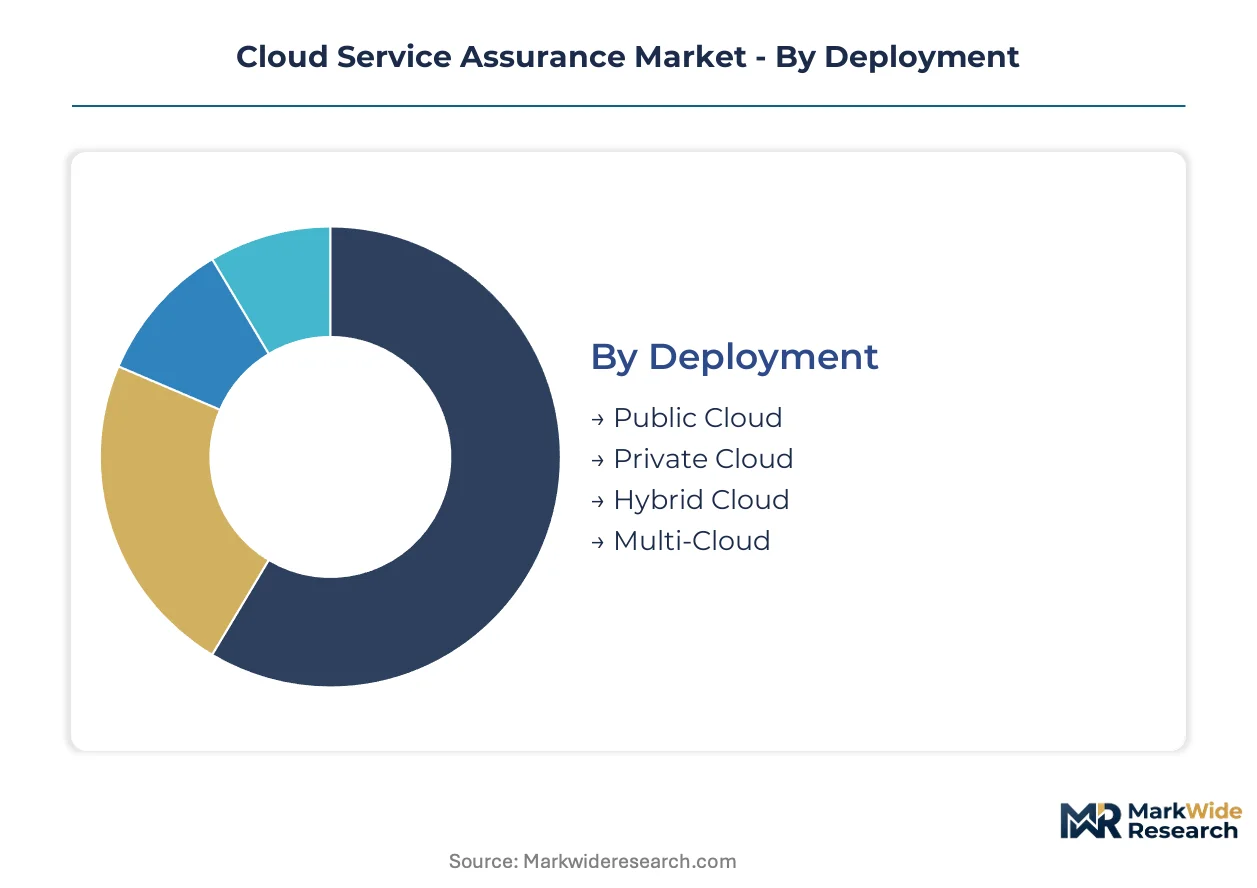
Cloud service assurance vendors must align product architectures with distinct operational constraints across deployment modes, regulatory exposure levels, and enterprise scale tiers. Segmentation reveals where margin concentration diverges from volume opportunity.
Deployment:
Geographic spread varies sharply: hybrid and private cloud deployments concentrate in Germany, France, and Singapore due to data sovereignty mandates, while public cloud assurance scales across export-led North American and Australian markets.
- Public Cloud:Shared infrastructure monitoring relies on standardized APIs and cross-tenant isolation verification. Demand concentrates among retail and media enterprises in the United States and Australia seeking elastic capacity without capital expenditure. FinOps maturity drives consumption-based pricing acceptance.
- Private Cloud:Dedicated infrastructure assurance requires bespoke instrumentation for single-tenant environments. German automotive manufacturers and French defense contractors anchor demand, compelled by Gaia-X sovereignty requirements and ANSM data localization rules.
- Hybrid Cloud:Orchestration across on-premises and public resources demands unified telemetry pipelines. Financial services institutions in Frankfurt and London prioritize this mode for core banking retention with transactional bursting.
- Multi-Cloud:Cross-hyperscaler visibility necessitates middleware translation layers. Singaporean government agencies and Canadian healthcare operators adopt this to avoid vendor lock-in while meeting jurisdictional redundancy requirements.
Hybrid Cloud holds the largest share; momentum sits with Multi-Cloud as sovereign fragmentation accelerates.
Service Type:
Cost tier stratification separates commodity monitoring from premium security and compliance bundles requiring specialized engineering talent.
- Monitoring:Real-time telemetry collection spans infrastructure metrics, application traces, and synthetic transaction testing. Baseline capability commoditizes quickly; differentiation shifts toward sub-second anomaly detection in 5G network slicing deployments.
- Management:Automated remediation and capacity orchestration reduce mean time to resolution. Japanese manufacturing enterprises and South Korean telecommunications operators drive adoption for edge-to-cloud continuum control.
- Security:Zero-trust architecture enforcement and encryption-in-transit verification command premium pricing. EU NIS2 Directive compliance deadlines propel replacement demand across European financial institutions and healthcare operators.
- Compliance:Audit trail generation and regulatory reporting automation address SEC, FCA, and GDPR documentation requirements. Petabyte-scale telemetry retention consumes substantial assurance budgets.
Security commands the highest margins; Compliance is expanding most quickly as algorithmic audit mandates proliferate.
End User:
Customer type determines procurement complexity, with government agencies imposing multi-year certification cycles and large corporations negotiating enterprise-wide volume discounts.
- Small Enterprises:Managed service consumption dominates as internal observability expertise remains scarce. Standardized SaaS dashboards suffice for sub-thousand-node environments.
- Medium Enterprises:Hybrid tool adoption accelerates as workload diversification outpaces single-platform coverage. Regional cloud providers in India and Brazil capture this tier through localized support.
- Large Corporations:Custom integration requirements span COBOL mainframe telemetry extraction and cloud-native Kubernetes instrumentation. Multi-year contracts index to data volume rather than seat count.
- Government Agencies:FedRAMP High, IL6, and comparable national authorization frameworks create competitive moats. Authorization timelines extend 18-36 months, disqualifying under-invested vendors.
Large Corporations contribute the greatest revenue concentration; Government Agencies are gaining share fastest as sovereign cloud procurement accelerates.
Solution:
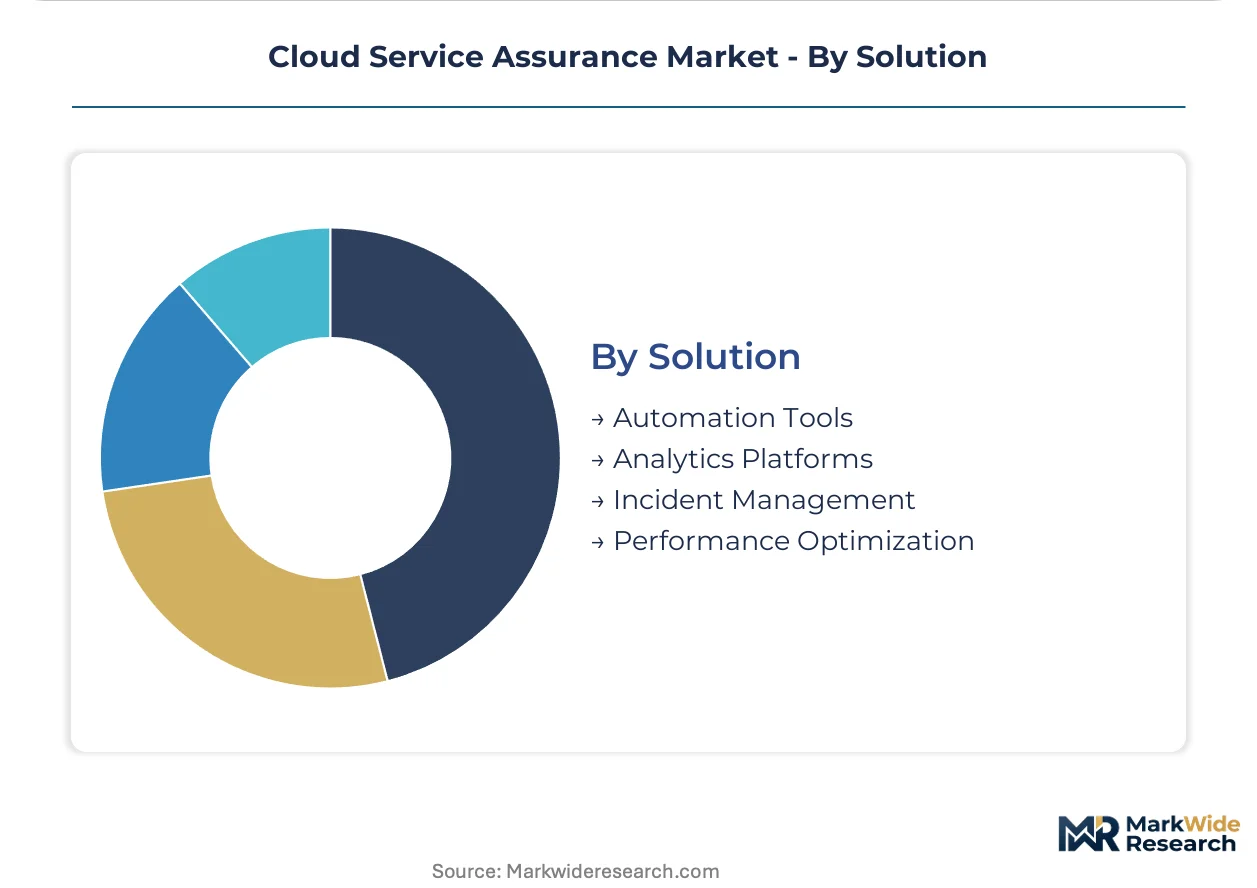
Application maturity separates established automation and incident management categories from emerging analytics platforms embedding AI-infused anomaly detection.
- Automation Tools:Self-healing scripts and policy-driven remediation reduce manual intervention. Telecommunications operators deploying 5G standalone cores require automated network function lifecycle management.
- Analytics Platforms:Time-series databases converging with large language models enable natural language telemetry querying. Financial services operators in Paris and Frankfurt must embed explainability modules for EU AI Act algorithmic transparency compliance.
- Incident Management:Workflow orchestration and root cause analysis capabilities integrate with enterprise IT service management suites. Mandatory NIS2 reporting timelines compress escalation procedures.
- Performance Optimization:Latency reduction and resource right-sizing recommendations target cloud cost containment. Retail and logistics verticals in North America prioritize this capability within FinOps programs.
Incident Management holds the largest installed base; Analytics Platforms show the steepest expansion trajectory as AI-augmented observability matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud service assurance capability concentrates in the United States, Germany, Japan, Singapore, and the United Kingdom, where hyperscaler density, sovereign mandates, and 5G infrastructure investments create divergent procurement requirements. Each jurisdiction imposes distinct regulatory frameworks that reshape vendor qualification criteria and deployment architectures.
United States
FedRAMP High and IL6 authorization requirements dominate federal procurement, creating multi-year competitive barriers for assurance vendors. The SEC mandates petabyte-scale telemetry retention for financial audit trails, consuming substantial observability budgets. San Francisco Bay Area hyperscaler clusters anchor demand for sub-second anomaly detection in fintech and gaming verticals.
Germany
Gaia-X sovereign infrastructure mandates require assurance tooling that operates entirely within jurisdictional boundaries, disqualifying centralized monitoring models. The EU NIS2 Directive compresses incident reporting timelines for Frankfurt-based financial institutions. Bavarian industrial cloud clusters drive edge-to-cloud continuum assurance requirements for automotive manufacturers.
Japan
METI industrial cloud initiatives mandate telemetry pipelines spanning factory floor PLCs through regional cloud zones. The country's national cybersecurity framework imposes strict data localization for critical infrastructure operators. Tokyo-Osaka metropolitan corridors concentrate demand for 5G standalone core monitoring with network slicing capabilities.
Singapore
Government agencies adopt multi-cloud architectures to satisfy vendor redundancy requirements while meeting data residency obligations. The Monetary Authority of Singapore tightens operational resilience standards for cloud-dependent financial services. Smart nation infrastructure investments drive edge computing assurance across island-wide deployment footprints.
United Kingdom
FCA audit trail requirements for cloud service providers elevate baseline compliance costs and telemetry retention obligations. The National Cyber Security Centre certifies assurance platforms for critical national infrastructure protection. London financial services clusters prioritize hybrid cloud orchestration for core banking retention with transactional bursting.
Cloud Service Assurance Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the cloud service assurance market. Hyperscaler-native platforms dominate scale economics while specialized vendors capture premium pricing through vertical-specific compliance modules. Three archetypes define competitive positioning: infrastructure-integrated hyperscalers, telecommunications-embedded network specialists, and independent observability platforms. Consolidation pressure intensifies through strategic partnerships between legacy systems integrators and cloud-native tooling vendors, alongside vertical integration into sovereign cloud infrastructure deployments.
Within the hyperscaler tier, Amazon Web Services, Microsoft Azure, and Google Cloud Platform anchor infrastructure-integrated assurance portfolios. IBM Cloud exemplifies the hybrid orchestration specialist archetype through Red Hat integration capabilities. Broadcom occupies a position within telecommunications-embedded network performance telemetry, extending visibility into 5G core-to-cloud pathways. These three company structures represent distinct competitive vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| IBM Cloud |
| Infovista |
| Amazon Web Services |
| Accenture |
| Broadcom |
| Microsoft Azure |
| Oracle Cloud Infrastructure |
| Ericsson |
| Google Cloud Platform |
| Others |
Value Chain & Pricing Dynamics
Ninety-day implementation timelines for FedRAMP High authorization compress vendor qualification windows and amplify pricing power for pre-certified incumbents while disqualifying undercapitalized challengers from government procurement cycles. This lead-time constraint concentrates supply-side leverage among established players who have already absorbed certification costs, creating tiered access patterns across public sector and regulated commercial segments.
Pricing Analysis
The EU NIS2 Directive dictates the pricing tier structure for incident response and audit trail capabilities across European financial services. Consumption-based models indexed to telemetry volume displace per-seat licensing, with FinOps-mature buyers in North America negotiating data-scale contracts. Price differentiation hinges on certification grade—FedRAMP High versus Moderate—and vertical-specific compliance module depth. Cost compression in baseline monitoring tiers intensifies as OpenTelemetry standardization erodes proprietary agent lock-in, while security and compliance bundles retain premium positioning. Small enterprises exhibit highest price sensitivity, defaulting to managed service consumption; government agencies accept elevated pricing for pre-authorized platforms.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-native tooling deployment, though strategic stockpiling of engineering talent concentrates in Silicon Valley and Bangalore. Software development and technical support capacity clusters in the United States, India, and Ireland, with localization engineering for sovereign cloud mandates expanding in Germany and Singapore. The supply chain draws from specialized labor pools for eBPF kernel programming and OpenTelemetry instrumentation expertise. Single-source vulnerability in hyperscaler API dependencies creates middleware translation risks. Distribution runs through direct enterprise sales for large contracts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs durable defensive moats in this market, as authorization timelines spanning 18-36 months disqualify rapid competitive entry and cement incumbent positioning in government and critical infrastructure verticals.
For Market Incumbents: Compound certification advantages by accelerating FedRAMP High and IL6 pathway investments before authorization backlogs lengthen. Defend against OpenTelemetry-driven commoditization in baseline monitoring by embedding vertical-specific compliance modules for EU NIS2 and AI Act algorithmic transparency requirements. Prioritize backward integration into sovereign cloud infrastructure partnerships in Germany and Singapore where data residency mandates reshape procurement criteria. For New Entrants and Emerging Players: Differentiate on edge-to-cloud continuum assurance for manufacturing and autonomous vehicle deployments in Japan and South Korea, where METI industrial cloud initiatives create whitespace outside hyperscaler-dominated core markets. Target medium enterprises in India and Brazil through regional cloud provider partnerships that offer localized support without global certification overhead. Lead with AI-infused natural language querying capabilities that lower analyst training barriers against established platform complexity. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because authorization moats deepen with each compliance cycle and sovereign fragmentation multiplies addressable market segmentation. Acquisition candidates with existing FedRAMP High or comparable national certifications command strategic premiums. Watch for inflection when EU AI Act enforcement actions against non-compliant anomaly detection systems trigger replacement demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telemetry pipelines across hybrid and multi-cloud footprints for financial services operators in Frankfurt. |
| Acquisition of Specialist Firm | Captures eBPF instrumentation expertise concentrated in Silicon Valley and Bangalore engineering clusters. |
| Strategic Partnership | Secures Gaia-X sovereign infrastructure alignment for German automotive and defense contractor procurement eligibility. |
| Geographic Expansion | Establishes edge-to-cloud assurance presence for METI-mandated industrial cloud deployments across Japan. |
| Product Launch | Introduces explainability modules that surface feature importance scores for EU AI Act algorithmic audit compliance. |
Study Parameters
Cross-validation between primary interviews with cloud architects, IT procurement officers, platform engineers, and compliance directors and secondary validation through SEC filings, hyperscaler capex disclosures, and regulatory submission databases anchors the qualitative findings. Bottom-up telemetry platform deployment assessments triangulate against top-down market sizing from enterprise IT spending surveys. Stakeholder conversations spanned North American financial services, European critical infrastructure operators, and Asia-Pacific manufacturing enterprises to capture regional variance in sovereign cloud mandates and certification requirements.
Sensitivity analysis around regulatory enforcement intensity and hyperscaler pricing power shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment mode, service type, organization scale tier, solution maturity, and regional regulatory cluster. CAGRs derive from installed base growth, replacement demand cycles tied to NIS2 compliance deadlines, and expansion in AI-augmented analytics platform adoption. Industry-specific inputs encompass OpenTelemetry standardization velocity, FedRAMP authorization pipeline backlogs, and sovereign cloud procurement acceleration patterns.
Forecasts assume regulatory continuity in EU NIS2 and AI Act implementation, FCC infrastructure reliability guidelines, and FedRAMP authorization standards; material policy shifts would require re-modeling. Telemetry retention cost inflation, hyperscaler API fragmentation, and specialized engineering talent scarcity constitute primary revision triggers. Revision becomes warranted when sovereign cloud mandate adoption crosses threshold penetration in additional European member states beyond Germany and France.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Recruitment Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Revenue Management Software Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Product Information Management Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Global Product Lifecycle Management Market