
 Anti-Snoring Treatment Market | 2026-2036
Anti-Snoring Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Snoring Treatment Market Analysis
Subscription-based leasing for CPAP machines and remote monitoring bundles is tilting competitive dynamics toward asset-light entrants. ResMed leverages its cloud-connected device ecosystem to sustain recurring revenue streams. SomnoMed anchors its position through specialized mandibular advancement devices tailored to dental sleep medicine. Fisher & Paykel Healthcare competes on humidification technology integrated into flow generators.
Anti-snoring treatment encompasses mechanical, electronic, and surgical interventions designed to maintain upper airway patency during sleep, with mandibular advancement devices typically fabricated from biocompatible dental acrylics with titration mechanisms adjustable in millimeter increments. The primary commercial purpose centers on reducing pharyngeal collapse and improving nocturnal oxygen saturation for patients with obstructive sleep-disordered breathing. Oral appliances command durable margin pools due to custom dental fitting requirements, while positional therapy devices represent the fastest-growing technology segment driven by wearable form factors and smartphone integration. Nasal strips occupy a mature, price-sensitive tier with limited clinical differentiation.
FDA 510(k) clearance and EU MDR Class IIa designation shape product development timelines and clinical evidence requirements for mandibular devices and CPAP systems. The EPA regulates volatile organic compound emissions from dental appliance manufacturing processes in the United States. Japan's PMDA enforces stringent electrical safety standards for home-use positive airway pressure equipment. Stakeholders must monitor evolving reimbursement coding for remote patient monitoring alongside dental-medical integration models.
Market Dynamics
Remote patient monitoring integration is compressing the traditional device-sales model toward recurring-revenue architectures, forcing incumbents to rebuild around cloud-connected hardware ecosystems rather than transactional unit economics.
Growth Catalysts
- EU MDR Class IIa designation:Harmonized clinical evidence requirements for mandibular advancement devices are accelerating cross-border market access for certified manufacturers.
- Aging demographics in Japan:METI-supported sleep disorder screening programs are expanding reimbursement eligibility for home-use positive airway pressure equipment.
- Biocompatible dental acrylics:Advances in CAD/CAM milling precision are reducing custom oral appliance production cycles from weeks to days.
Market Restraints
- Specialized dental laboratory concentration:Custom fitting requirements for mandibular devices create supply bottlenecks in Germany and the United States where certified technicians remain scarce.
- FDA 510(k) clinical evidence thresholds:Comparative effectiveness studies against predicate devices extend clearance timelines and elevate development costs for novel mechanical interventions.
- Positional therapy substitution:Wearable sleep trainers with smartphone integration are capturing price-sensitive segments that oral appliances previously dominated.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives could localize production of nasal dilators and basic oral appliances for South Asian markets.
- Tele-dentistry integration:Remote intraoral scanning and digital impression workflows are opening direct-to-patient channels bypassing traditional sleep clinic gatekeepers.
- AI-actuated titration:Machine learning algorithms embedded in mandibular advancement devices enable real-time positional adjustment without clinical visits.
Industry Challenges
- Dental-medical credentialing complexity:Cross-licensing requirements between sleep physicians and dental sleep medicine practitioners fragment referral pathways.
- ISO 13485 quality management implementation:Small device manufacturers struggle with documentation burdens for EU MDR technical file preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Snoring Treatment Market |
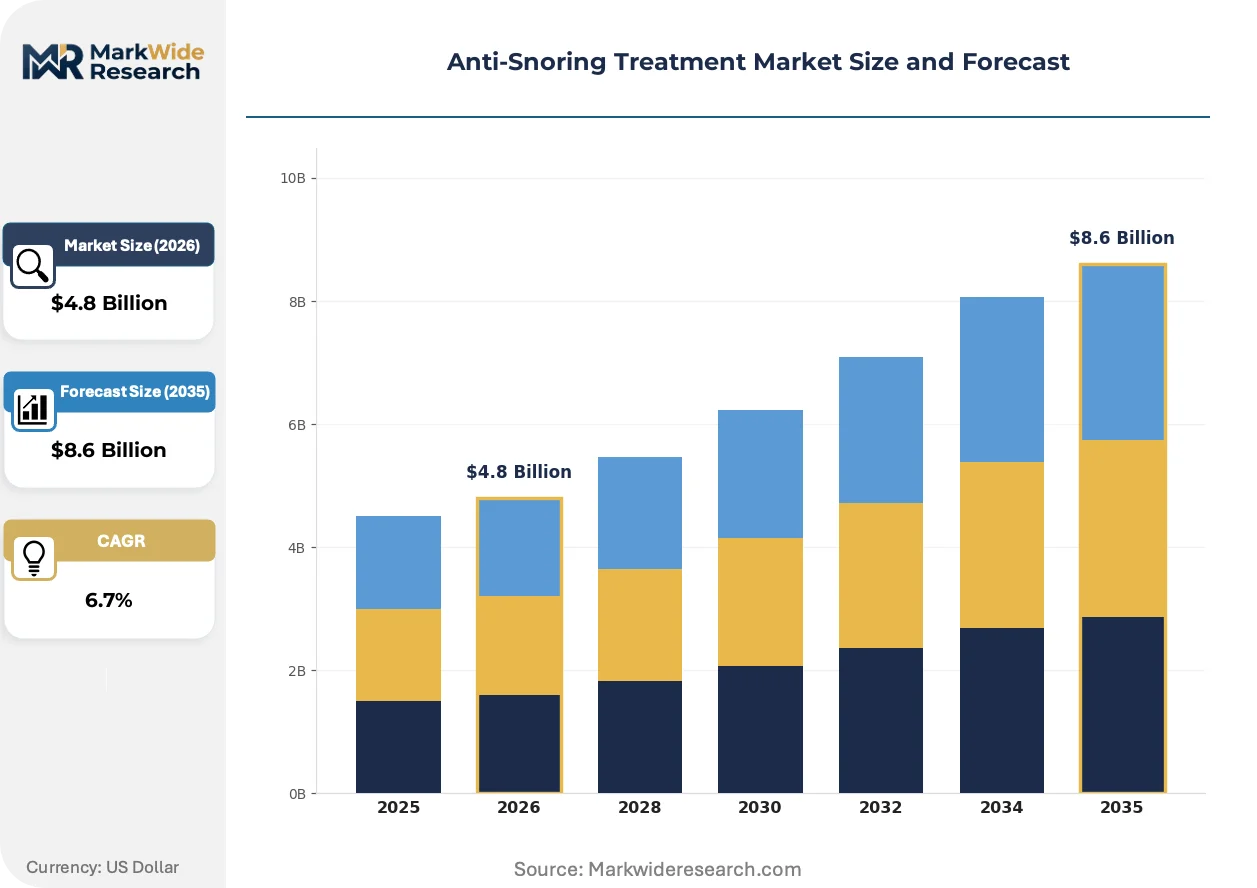
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mandibular Devices, Nasal Strips, CPAP Machines, Oral Appliances Technology: Laser Therapy, Positional Therapy, Surgical Solutions, Somnoplasty End User: Individuals, Hospitals, Sleep Clinics, Home Care Providers Application: Sleep Apnea, Chronic Snoring, Hypopnea, Restless Sleep |
| Companies Covered | ResMed, SomnoMed, Fisher & Paykel Healthcare, Koninklijke Philips, ProSomnus Sleep Technologies, Apnea Sciences, Airway Management, Tomed GmbH, Glidewell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Snoring Treatment Market Emerging Trajectories
Sensor miniaturization and edge computing are embedding diagnostic capability directly into treatment devices, blurring the boundary between therapy delivery and sleep architecture monitoring.
Photoplethysmography arrays integrated into mandibular advancement devices enable continuous blood oxygen and heart rate variability tracking without separate pulse oximetry equipment. Sleep clinics in the United States are piloting these dual-function appliances for patients requiring both intervention and longitudinal monitoring. This convergence is digitizing patient management workflows by collapsing diagnosis, treatment, and follow-up into a single hardware footprint.
Japan's PMDA revised electrical safety standards for home-use positive airway pressure equipment in 2023, mandating enhanced electromagnetic compatibility testing and software validation protocols. Domestic manufacturers have absorbed compliance costs through redesigned power supply architectures, while importers face extended conformity assessment periods. The regulation most heavily affects compact travel CPAP systems where space constraints complicate shielding requirements.
Subscription leasing for CPAP machines and remote monitoring bundles is displacing outright purchase models among US home care providers seeking to reduce capital deployment and obsolescence risk. Equipment financiers are entering direct partnerships with device manufacturers to underwrite asset pools. This shift concentrates most visibly in Medicare Advantage networks where per-member-per-month reimbursement structures favor operational expenditure over capital expenditure accounting.
Anti-Snoring Treatment Market Segmentation
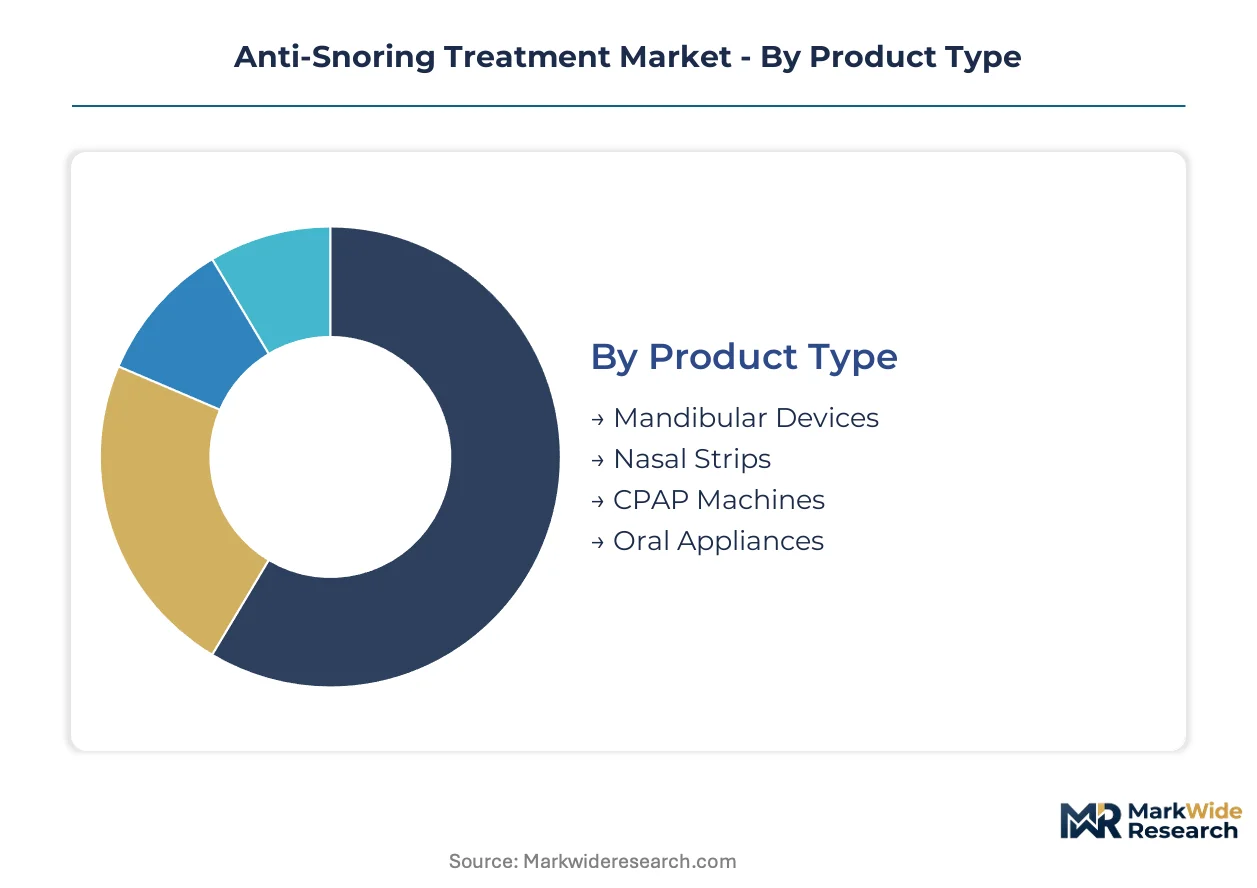
Segmentation in the Anti-Snoring Treatment Market reveals divergent service intensity requirements across product categories. Custom-fitted mandibular devices demand ongoing dental adjustment protocols, while disposable nasal strips operate through transactional retail channels with minimal after-sales engagement.
Product Type:
After-sales-service intensity varies dramatically across this category, with custom-fitted solutions requiring multi-visit clinical protocols versus off-the-shelf alternatives needing no technical support.
- Mandibular Devices:Fabricated from biocompatible dental acrylics with millimeter-precision titration mechanisms. Sleep clinics in the United States and Germany concentrate procurement for these devices, constrained by certified dental technician scarcity that extends production cycles.
- Oral Appliances:CAD/CAM milling advances have compressed custom fabrication from weeks to days. Home care providers in Japan are expanding leasing arrangements for these devices, driven by METI-supported reimbursement expansion for sleep disorder interventions.
- CPAP Machines:Cloud-connected flow generators with integrated humidification systems.
- Nasal Strips:Elastic adhesive bands with spring-like dilation mechanics.
Oral appliances hold the largest share; momentum sits with mandibular devices as dental-medicine integration deepens.
Technology:
Cost tier stratification separates capital-intensive surgical interventions from consumer-grade wearable alternatives, with reimbursement eligibility determining accessible price points across patient populations.
- Positional Therapy:Wearable form factors with smartphone-integrated sleep trainers that vibrate when supine positioning is detected. Individuals in price-sensitive segments favor these devices, drawn by direct-to-consumer availability and absence of clinical fitting requirements.
- Somnoplasty:Radiofrequency ablation of soft palate tissue performed in outpatient settings. Sleep clinics in the United States perform these procedures under local anesthesia, constrained by limited insurance coverage for non-apneic snoring cases.
- Laser Therapy:Palatal stiffening through targeted thermal injury.
- Surgical Solutions:Uvulopalatopharyngoplasty and genioglossus advancement procedures.
Positional therapy holds the largest share; surgical solutions are climbing the fastest as ambulatory surgical center networks expand.
End User:
Volume concentration diverges between institutional procurement with negotiated device leasing terms and individual purchasers navigating direct-to-consumer channels without clinical gatekeeping.
- Sleep Clinics:Specialized diagnostic and treatment facilities with polysomnography capabilities. These institutions in Germany face supply bottlenecks for custom mandibular devices, limited by EU MDR Class IIa certification requirements for dental laboratory partners.
- Home Care Providers:Durable medical equipment suppliers managing subscription-based CPAP leasing. Medicare Advantage networks in the United States favor these providers, driven by per-member-per-month reimbursement structures that reward operational expenditure accounting.
- Hospitals:Acute care facilities with sleep medicine departments.
- Individuals:Direct purchasers through retail and e-commerce channels.
Sleep clinics hold the largest share; home care providers are gaining share fastest as remote patient monitoring integration accelerates.
Application:
Margin structure correlates with diagnostic coding complexity, with reimbursed sleep apnea interventions commanding premium pricing versus self-pay chronic snoring treatments.
- Sleep Apnea:Obstructive and central sleep-disordered breathing with validated diagnostic criteria. Hospitals in Japan prioritize positive airway pressure equipment for these patients, constrained by PMDA electrical safety standards that extend conformity assessment for imported compact travel systems.
- Chronic Snoring:Primary snoring without oxygen desaturation or arousal indices. Individuals in the United States access nasal dilators and over-the-counter solutions for this indication, limited by exclusion from most insurance formularies.
- Hypopnea:Partial airway obstruction with reduced airflow.
- Restless Sleep:Sleep fragmentation without definitive respiratory etiology.
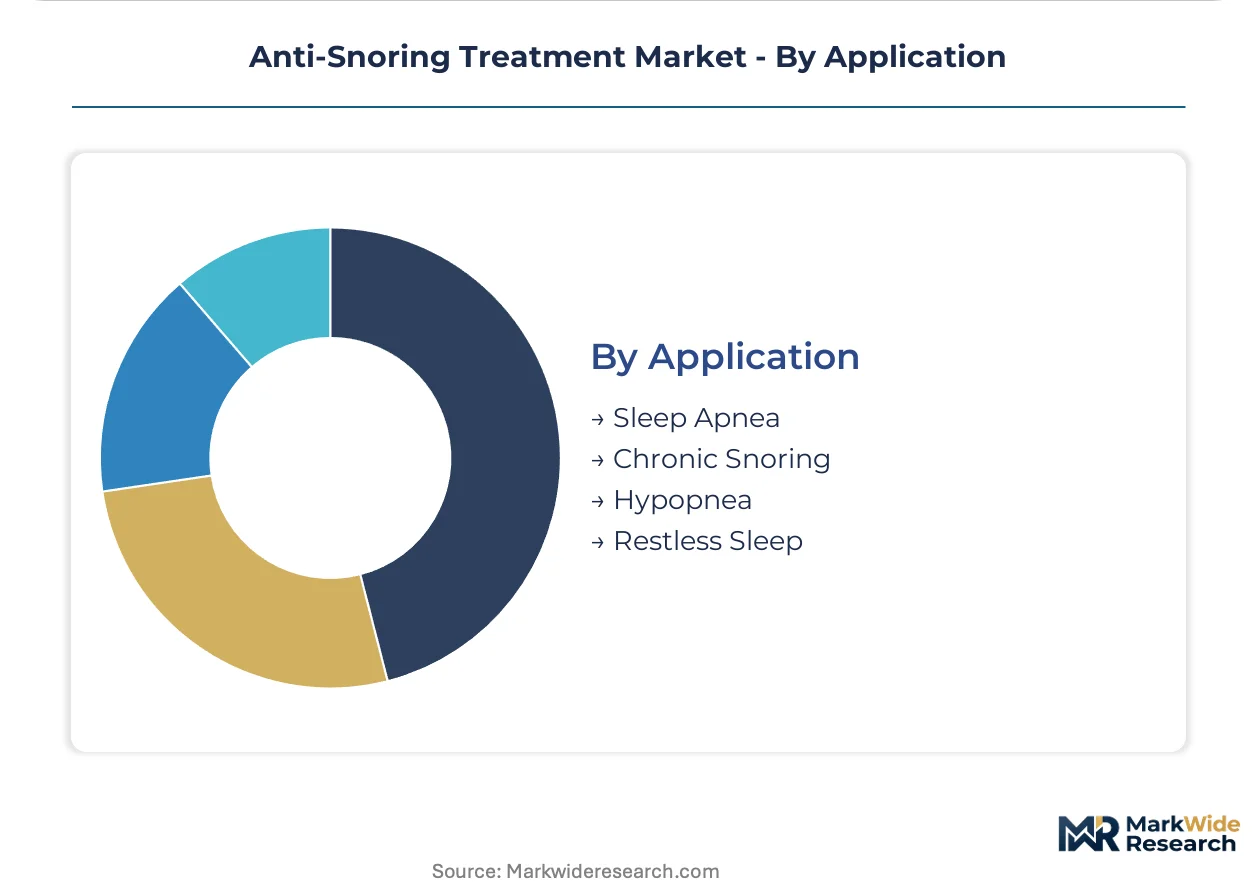
Sleep apnea holds the largest share; chronic snoring shows steepest expansion trajectory as wearable diagnostics expand addressable detection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy shifts and aging demographics are concentrating commercial activity in developed healthcare systems with established sleep medicine infrastructure and regulatory clarity for device certification pathways.
United States
Medicare Advantage networks are accelerating subscription-based CPAP leasing models that favor operational expenditure accounting over capital deployment. The FDA maintains 510(k) clearance pathways for mandibular advancement devices with predicate-based clinical evidence requirements. Sleep clinics in the American Southeast face supply bottlenecks for custom-fitted oral appliances due to certified dental technician scarcity.
Germany
EU MDR Class IIa designation for mandibular devices has harmonized cross-border certification standards while extending technical file documentation burdens. The country's national medical device regulator enforces stringent quality management system audits for dental laboratory partners. Manufacturing clusters in Bavaria and Baden-Württemberg specialize in precision-milled biocompatible dental acrylics with compressed production cycles.
Japan
METI-supported sleep disorder screening programs are expanding reimbursement eligibility for home-use positive airway pressure equipment among aging populations. PMDA electrical safety standards mandate enhanced electromagnetic compatibility testing that extends conformity assessment periods for imported compact travel systems. Tokyo-based sleep clinics are piloting dual-function mandibular devices with integrated photoplethysmography arrays.
India
The PLI scheme for medical devices is creating domestic manufacturing incentives for nasal dilators and basic oral appliances targeting South Asian price-sensitive segments. The country's national pharmaceutical and medical device regulator oversees import licensing for positive airway pressure equipment with escalating local content requirements. Production facilities in Maharashtra and Gujarat are scaling injection-molded nasal dilator capacity for regional distribution.
United Kingdom
NHS England commissioning frameworks are consolidating sleep apnea diagnostic pathways toward centralized polysomnography hubs with preferred device supplier arrangements. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for mandibular device market access. London and Southeast England concentrate private dental sleep medicine practices offering premium custom appliance services.
Anti-Snoring Treatment Market Vendor Landscape
On the supply side, the industry is tiered between capital-intensive flow generator manufacturers with cloud-connected ecosystems and specialized dental device fabricators with custom-fitting capabilities. Consolidation pressures concentrate among CPAP system providers where recurring revenue architectures favor scale, while fragmentation persists in oral appliance segments constrained by dental technician scarcity. Two strategic archetypes dominate: integrated respiratory device platforms with remote monitoring bundles, and precision dental laboratories with CAD/CAM milling specialization. Competitive moves center on tele-dentistry partnerships bypassing sleep clinic gatekeepers and AI-actuated titration technology licensing.
Within the integrated device platform tier, ResMed and Koninklijke Philips occupy positions exemplifying cloud-connected hardware ecosystems with subscription-based revenue models. SomnoMed represents the specialized dental fabrication archetype, anchoring mandibular advancement device expertise through dental sleep medicine channel relationships. These three companies illustrate the structural divergence between scale-driven respiratory platforms and precision-focused oral appliance specialists competing for overlapping patient populations with distinct service intensity requirements.
| Leading Market Players |
|---|
| ResMed |
| SomnoMed |
| Fisher & Paykel Healthcare |
| Koninklijke Philips |
| ProSomnus Sleep Technologies |
| Apnea Sciences |
| Airway Management |
| Tomed GmbH |
| Glidewell |
| Others |
Supply Flow & Price Mechanics
EU MDR Class IIa certification bottlenecks for mandibular advancement devices determine both margin stratification and geographic sourcing patterns across the anti-snoring treatment landscape. Dental laboratory capacity scarcity in Germany and the United States compresses production throughput while elevating pricing premiums for certified custom-fitted appliances.
Pricing Analysis
Certification level creates the primary spread between premium custom-milled mandibular devices and economy-grade nasal dilators. Three-tier pricing structure across premium ISO 13485-certified, standard CE-marked, and economy retail tiers reflects after-sales service bundling and clinical validation depth. Cost compression in the economy tier intensifies because direct-to-consumer positional therapy substitutes erode oral appliance dominance. Home care providers exhibit lowest price sensitivity due to Medicare Advantage per-member-per-month structures, while individual retail purchasers navigate price-sensitive over-the-counter channels.
Supply Chain Analysis
Biocompatible dental acrylic feedstock concentrates manufacturing gravity in Bavaria and Baden-Württemberg, Germany, with secondary milling clusters in the United States and Japan. Precision CAD/CAM equipment, certified dental technicians, and biocompatible polymer resins constitute critical input dependencies. Single-source vulnerability sits with specialized dental laboratory networks where EU MDR technical file documentation burdens constrain expansion. Distribution runs through sleep clinic procurement committees, durable medical equipment leasing platforms, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified dental technician scarcity fragments competitive control across custom-fitted device segments, concentrating margin capture with laboratories that have secured EU MDR Class IIa partnerships.
For Market Incumbents: Harden cloud-connected hardware ecosystems against asset-light entrants by deepening remote patient monitoring integration and expanding subscription-based leasing arrangements. Secure captive dental laboratory capacity through exclusive partnerships or in-house technician training programs to defend against supply bottlenecks. Prioritize AI-actuated titration R&D to reduce clinical visit dependency and compress competitor response windows. For New Entrants and Emerging Players: Build out tele-dentistry-enabled direct-to-patient channels bypassing traditional sleep clinic gatekeepers, leveraging remote intraoral scanning workflows to capture price-sensitive chronic snoring segments. Target India's PLI scheme-supported manufacturing zones for nasal dilator and basic oral appliance localization. Pursue white-label partnerships with existing dental laboratories rather than building certified fabrication capacity from inception. For Investors and Strategic Acquirers: EU MDR transition completion reshapes the acquisition landscape by eliminating subscale competitors unable to absorb technical file documentation burdens. Favor precision dental laboratories with established CAD/CAM milling specialization and existing sleep physician referral networks over capital-intensive CPAP platform plays. Monitor PMDA electrical safety standard evolution for Japanese home-use equipment as signal for import conformity assessment timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Class IIa technical file preparation compresses market access timelines for mandibular device manufacturers. |
| Tele-Dentistry Platform Development | Remote intraoral scanning integration opens direct-to-patient channels bypassing sleep clinic procurement committees. |
| AI-Actuated Titration Licensing | Machine learning-enabled positional adjustment reduces clinical visit frequency and deepens device switching costs. |
| Dental Laboratory Partnership Expansion | Exclusive certified technician access secures production throughput against EU MDR-constrained supply bottlenecks. |
| Reimbursement Strategy Optimization | Medicare Advantage per-member-per-month structuring favors operational expenditure accounting for home care providers. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Sleep clinic directors, dental sleep medicine practitioners, biomedical engineers at home care providers, and GPO contracts managers contributed operational perspective. FDA 510(k) clearance databases, EU MDR technical file registries, CMS Medicare reimbursement schedules, and PMDA electrical safety standards provided secondary validation. Bottom-up demand modeling across product type, technology, end user, and application segments was reconciled with top-down market sizing.
Calibration against historical reimbursement policy shifts and regulatory transition timelines informed projection reliability across the modeling period. Segmentation dimensions include product type, technology platform, end user channel, application indication, and geographic regulatory cluster. CAGRs were derived from fitted trend analysis incorporating aging demographic trajectories, reimbursement expansion patterns, and substitution elasticity between device categories. Forecast inputs incorporate dental technician training pipeline constraints and cloud-connected device adoption curves.
Stress conditions across EU MDR certification timeline delays, PMDA conformity assessment extensions, and positional therapy substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement coding stability and dental-medical integration velocity. Cross-checking against hospital procurement database benchmarks and GPO contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Hypoventilation Management Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Insomnia Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Home Sleep Apnea Testing Market