
 Asia-Pacific Arachidonic Acid Market | 2026-2036
Asia-Pacific Arachidonic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Arachidonic Acid Market Outlook
Plant-derived arachidonic acid from microbial fermentation is restructuring cost economics across the Asia-Pacific supply base. Cabio Biotech (Wuhan) Co., Ltd leverages its Wuhan fermentation complex to anchor regional production capacity for pharmaceutical-grade material. Kingdomway Nutrition sustains downstream dominance through captive powder formulation lines serving infant formula clients. Guangdong Runke Bioengineering differentiates via lipid emulsion technology tailored to cosmetic applications.
Arachidonic acid is a long-chain polyunsaturated omega-6 fatty acid with the molecular formula C20H32O2, typically manufactured through fungal fermentation using Mortierella alpina or extracted from animal tissues, functioning as a critical structural component of cell membranes and precursor to eicosanoid signaling molecules in pharmaceutical and nutritional applications. Powder formulations occupy the dominant share of volume throughput due to stability advantages in bulk ingredient handling and extended shelf life under tropical storage conditions. Infant formula applications command premium positioning within the application matrix, while nutritional supplements segment growth reflects expanding direct-to-consumer channels across Southeast Asian markets. Liquid and emulsion formats serve specialized pharmaceutical injection and cosmetic serum formulations where bioavailability requirements exceed standard powder performance.
China's NMPA enforces GB standards for food-grade fatty acid purity, while India's FSSAI mandates contaminant thresholds for nutritional additive imports, and both frameworks directly determine market access for cross-border suppliers. Japan's METI oversees pharmaceutical-grade arachidonic acid through PMDA-aligned quality certifications that constrain supplier eligibility for clinical nutrition products. Stakeholders must monitor divergence between national purity standards and emerging sustainability disclosure requirements as procurement criteria evolve across the region.
Market Dynamics
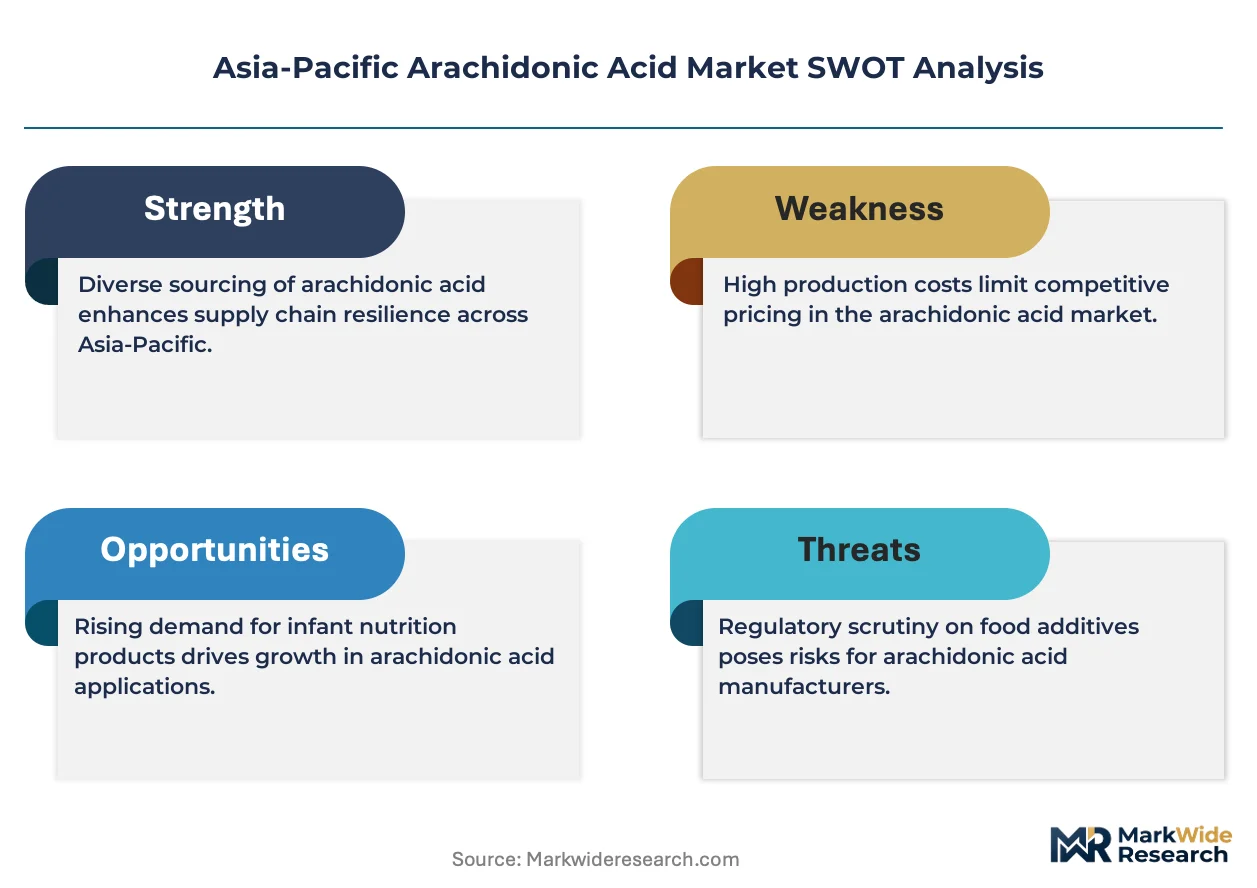
Microbial fermentation technology is restructuring cost economics across Asia-Pacific arachidonic acid production, enabling plant-derived alternatives to displace traditional animal-tissue extraction methods and compressing input cost structures for downstream formulators.
Growth Catalysts
- Infant formula fortification mandates:China's NMPA and India's FSSAI have expanded permissible arachidonic acid inclusion levels in pediatric nutrition products, directly expanding addressable demand from formula manufacturers in both markets.
- Pharmaceutical-grade certification pathways:Japan's PMDA-aligned METI oversight for clinical nutrition applications creates premium pricing tiers that incentivize quality upgrades across regional suppliers.
- Cosmetic serum bioavailability requirements:Lipid emulsion technologies tailored to topical applications are opening formulation flexibility for Korean and Japanese skincare manufacturers seeking omega-6 fatty acid incorporation.
Market Restraints
- Fungal strain input concentration:Mortierella alpina cultivation capacity concentrates in a limited number of fermentation complexes, creating supply vulnerability during equipment maintenance cycles.
- Cross-border purity friction:Divergent GB standards and FSSAI contaminant thresholds force dual-certification investments for suppliers serving both Chinese and Indian markets simultaneously.
- Omega-3 substitution pressure:DHA and EPA fortification programs in competing nutritional segments divert R&D budgets and consumer attention from omega-6 positioning.
Strategic Opportunities
- Southeast Asian direct-to-consumer channels:Vietnam, Indonesia, and Thailand exhibit underdeveloped nutritional supplement penetration, creating first-mover positioning for e-commerce-enabled arachidonic acid brands.
- Dual carbon policy alignment:China's MEE sustainability disclosure requirements favor fermentation-based production methods with lower carbon intensity profiles versus animal-derived alternatives.
- Pharmaceutical injection formulation expansion:Parenteral nutrition applications in Japan and South Korea demand liquid emulsion formats with bioavailability specifications exceeding standard powder performance.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology expertise for large-volume Mortierella alpina cultivation remains concentrated in a limited pool of technical specialists across the region.
- Multi-jurisdiction certification timelines:Synchronous NMPA, FSSAI, and PMDA approval processes extend product launch cycles by eighteen to thirty-six months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Arachidonic Acid Market |
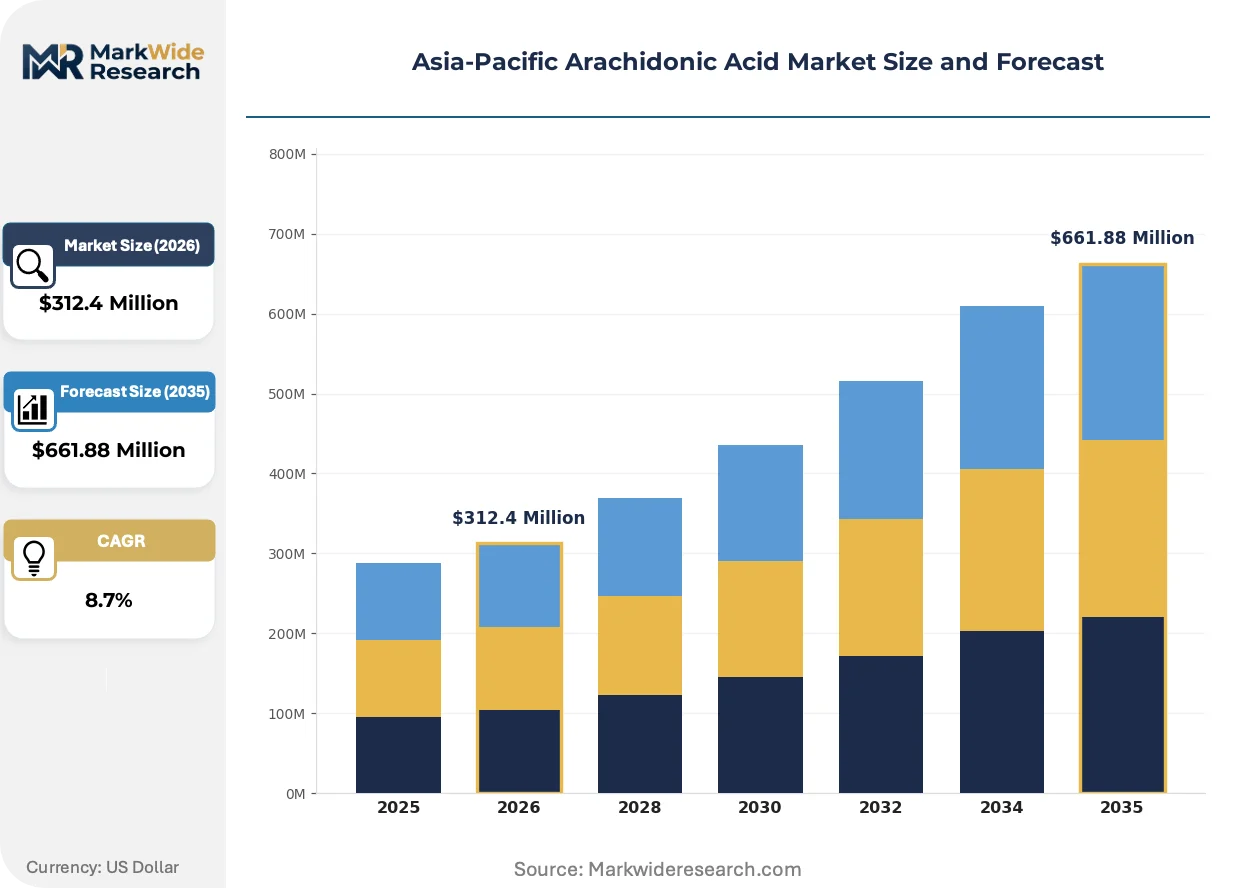
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Emulsion, Capsules Application: Nutritional Supplements, Pharmaceuticals, Infant Formula, Cosmetics End User: Healthcare Providers, Nutritional Product Manufacturers, Cosmetic Companies, Research Institutions Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Food Stores |
| Companies Covered | Guangdong Runke Bioengineering, A & Z Food Additives Co., Ltd, Cargill, BASF, Zhejiang Weiss, Cabio Biotech (Wuhan) Co., Ltd, Royal DSM, Kingdomway Nutrition, Cayman Chemicals, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Arachidonic Acid Market Strategic Shifts
Continuous fermentation systems are displacing batch processing as the dominant production architecture, while regulatory disclosure requirements and procurement model evolution reshape how value flows through the Asia-Pacific arachidonic acid supply chain.
Single-use bioreactor technology is absorbing capital investment from regional fermentation operators seeking to reduce cross-contamination risk between pharmaceutical-grade and food-grade production campaigns. Infant formula manufacturers in China's eastern coastal clusters are qualifying these systems for powder formulation lines. The technology is absorbing validation timelines that previously constrained multi-product facility flexibility.
China's GB standards for food-grade fatty acid purity are tightening contaminant thresholds for heavy metals and oxidation byproducts, forcing suppliers to upgrade filtration and stabilization protocols. India's FSSAI has mirrored this trajectory for imported nutritional additives. Pharmaceutical-grade material destined for Japan's PMDA-aligned METI certification faces the most stringent enforcement, compressing eligibility for clinical nutrition suppliers.
Ingredient sourcing decisions now prioritize documented chain-of-custody from fermentation through final formulation, displacing spot-market procurement for infant formula applications. Powder stability under tropical storage conditions has become a contractual specification rather than a negotiable attribute. This behavioral shift is most visible in procurement contracts from Chinese and Indian nutritional supplement hubs where shelf-life guarantees now extend to thirty-six months.
Asia-Pacific Arachidonic Acid Market Segmentation
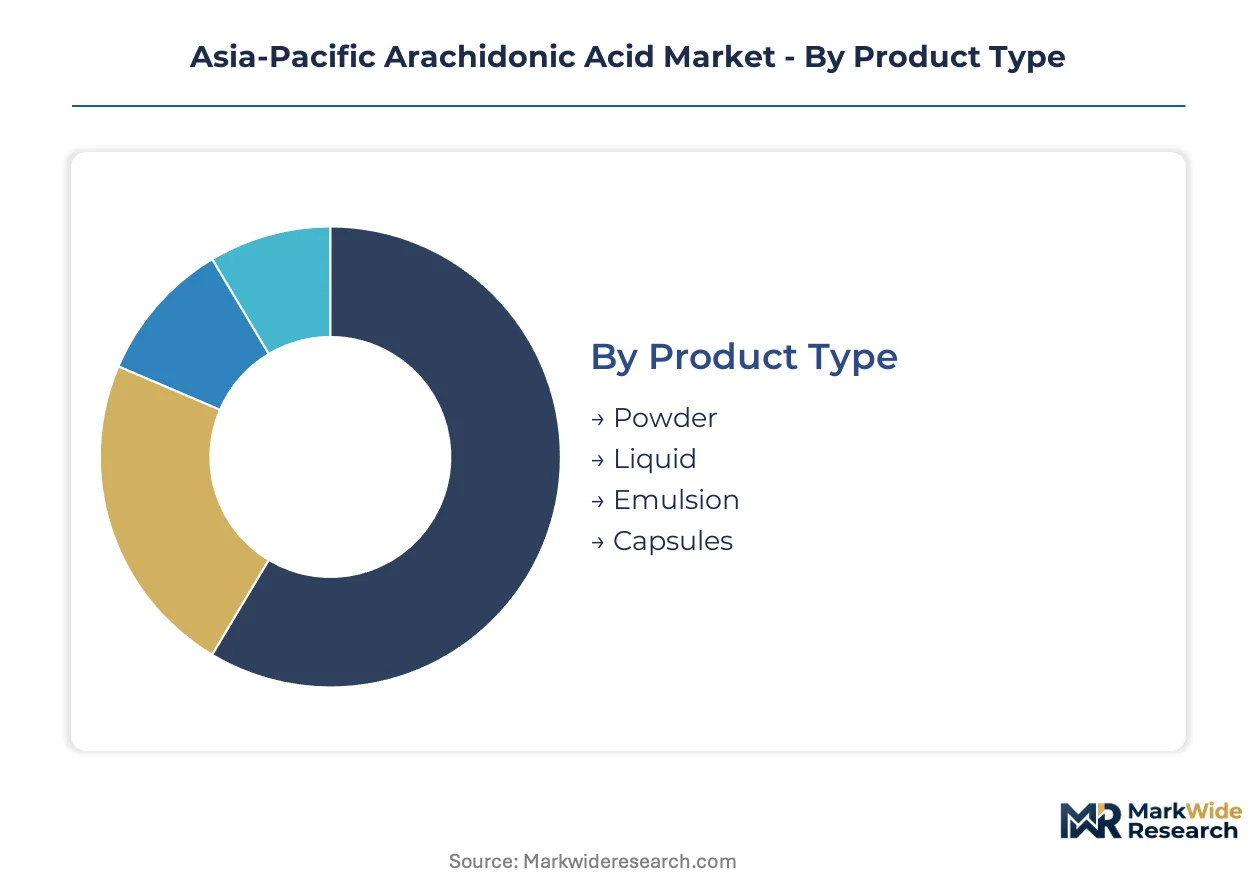
Arachidonic acid segmentation in Asia-Pacific tracks how formulation specifications, regulatory pathways, and procurement channels create distinct value tiers. Each dimension reveals where margin concentrates and where volume flows through the supply chain.
Product Type:
Formulation stability and bioavailability specifications determine manufacturing investment and shelf-life performance across tropical distribution networks.
- Powder:Spray-dried crystalline formulations with enhanced oxidative stability dominate bulk ingredient handling. China's eastern coastal manufacturing clusters and India's nutritional supplement hubs absorb the majority of volume for infant formula fortification programs requiring thirty-six-month shelf-life guarantees under ambient storage conditions.
- Liquid:Oil-based concentrates with standardized potency levels serve pharmaceutical injection and parenteral nutrition applications. Demand concentrates in Japan's clinical nutrition sector and South Korean hospital supply chains where METI-aligned PMDA certifications mandate documented chain-of-custody from fermentation through final formulation.
- Emulsion:Lipid-based delivery systems with particle size optimization for dermal penetration address Korean and Japanese skincare manufacturer requirements for omega-6 fatty acid incorporation into serum formulations.
- Capsules:Pre-measured unit-dose formats with enteric coating options target direct-to-consumer nutritional supplement channels across Vietnam, Indonesia, and Thailand.
Mature deployment sits with Powder. Newer deployment is concentrated in Emulsion.
Application:
Regulatory classification tiers create divergent certification burdens and pricing structures for end-use categories.
- Infant Formula:Pediatric nutrition fortification commands premium positioning through NMPA and FSSAI inclusion level expansions. Procurement contracts from Chinese and Indian manufacturers now specify powder stability under tropical conditions as a non-negotiable attribute rather than a negotiable specification.
- Pharmaceuticals:Clinical nutrition and parenteral applications face Japan's most stringent PMDA-aligned METI enforcement, compressing supplier eligibility and creating quality-upgrade incentives across regional production bases.
- Nutritional Supplements:Direct-to-consumer expansion across Southeast Asian e-commerce channels drives volume growth, with first-mover positioning available in underpenetrated Vietnamese, Indonesian, and Thai markets.
- Cosmetics:Topical serum formulations leverage lipid emulsion technologies for bioavailability requirements exceeding standard powder performance, particularly among Korean skincare manufacturers.
Revenue concentration aligns with Infant Formula. Volume expansion is climbing the fastest in Nutritional Supplements.
End User:
Procurement sophistication and quality documentation requirements separate institutional buyers from commercial formulators.
- Nutritional Product Manufacturers:Infant formula producers in China and India drive powder formulation demand with captive qualification protocols for fermentation-derived material. These buyers prioritize documented carbon intensity profiles under China's MEE sustainability disclosure requirements.
- Healthcare Providers:Hospital systems and clinical nutrition departments in Japan and South Korea specify liquid emulsion formats for parenteral applications, with procurement decisions contingent on PMDA-aligned certification status.
- Cosmetic Companies:Korean and Japanese skincare manufacturers seek lipid emulsion technologies with particle size specifications tailored to dermal penetration requirements.
- Research Institutions:Academic and clinical research centers require pharmaceutical-grade material with batch-level traceability for eicosanoid signaling studies.
Contractual volume sits with Nutritional Product Manufacturers. Specification complexity is expanding most quickly among Healthcare Providers.
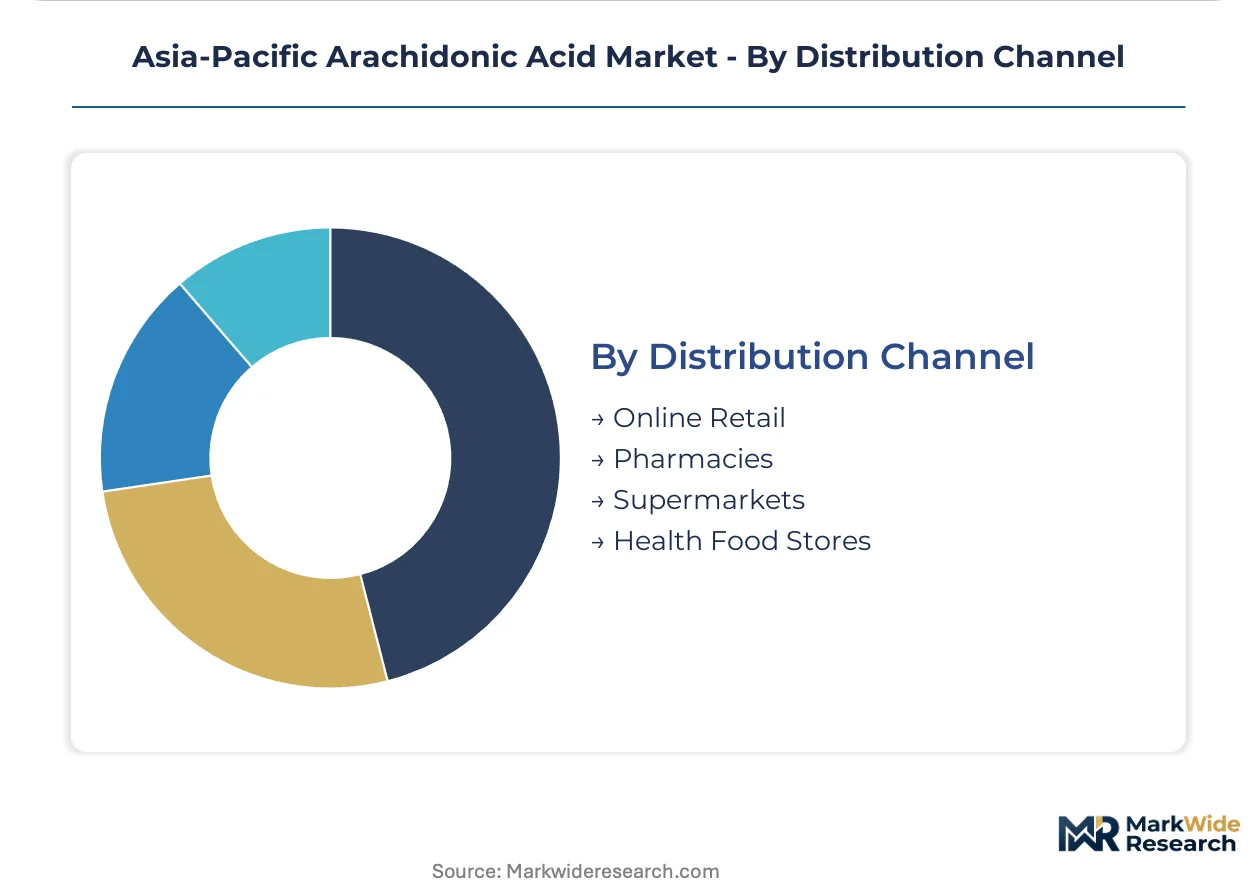
Distribution Channel:
Channel selection reflects end-user procurement sophistication and regulatory documentation requirements.
- Pharmacies:Licensed retail channels dominate pharmaceutical-grade and infant formula-grade distribution in China, Japan, and South Korea, with inventory management systems tracking lot-level certification documentation.
- Online Retail:E-commerce platforms enable direct-to-consumer nutritional supplement penetration across Southeast Asian markets, bypassing traditional import distribution layers for capsule and powder formats.
- Health Food Stores:Specialized retail channels serve premium positioning for nutritional supplements in urban centers across India and China's tier-one cities.
- Supermarkets:Mass retail channels carry limited nutritional supplement SKUs with lower potency specifications and reduced certification documentation requirements.
Regulatory compliance burden concentrates in Pharmacies. Geographic reach is expanding fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for arachidonic acid concentrates in China's eastern coastal manufacturing clusters and India's nutritional supplement hubs, with procurement patterns diverging sharply between infant formula fortification and pharmaceutical-grade applications.
China
Infant formula manufacturers in Jiangsu and Zhejiang provinces drive powder formulation demand with thirty-six-month shelf-life specifications. NMPA enforces GB standards for food-grade fatty acid purity that tighten contaminant thresholds annually. Cabio Biotech anchors production capacity at its Wuhan fermentation complex, supplying pharmaceutical-grade material to domestic formulators.
India
Nutritional supplement expansion across Maharashtra and Gujarat creates volume growth for direct-to-consumer capsule formats. FSSAI mandates contaminant thresholds for imported omega fatty acid additives that force dual-certification investments. Mumbai-based distributors now specify documented chain-of-custody from fermentation through final formulation.
Japan
Clinical nutrition and parenteral applications in Tokyo and Osaka demand liquid emulsion formats with bioavailability specifications exceeding standard powder performance. METI oversees pharmaceutical-grade material through PMDA-aligned quality certifications that compress supplier eligibility. Kanto-region hospital systems require batch-level traceability for eicosanoid signaling studies.
South Korea
Skincare manufacturers in Seoul and Busan seek lipid emulsion technologies for omega-6 fatty acid incorporation into serum formulations. MFDS pharmaceutical regulations create premium pricing tiers for clinical nutrition suppliers. Daegu-Gyeongbuk pharmaceutical clusters absorb liquid formats for parenteral nutrition applications.
Vietnam
Underdeveloped nutritional supplement penetration creates first-mover positioning for e-commerce-enabled arachidonic acid brands. General food safety regulations govern additive imports without specialized omega fatty acid frameworks. Ho Chi Minh City distribution channels bypass traditional import layers for direct-to-consumer powder and capsule formats.
Asia-Pacific Arachidonic Acid Market Competitive Environment
Capacity expansion dominates the current landscape as fermentation operators absorb capital investment in single-use bioreactor technology. The vendor base organizes around three strategic archetypes: integrated fermentation-to-formulation specialists, pure-play biotech suppliers, and diversified chemical conglomerates with nutritional additive portfolios. Geographic expansion and technology licensing represent the dominant competitive moves, with cross-border certification investments creating tiered market access.
Among China-based fermentation specialists, Cabio Biotech (Wuhan) Co., Ltd and Guangdong Runke Bioengineering occupy positions representing the integrated and application-differentiated archetypes respectively. Kingdomway Nutrition exemplifies downstream formulation dominance through captive powder production lines. Zhejiang Weiss represents the regional specialist tier serving domestic infant formula manufacturers with stability-optimized formulations.
| Leading Market Players |
|---|
| Guangdong Runke Bioengineering |
| A & Z Food Additives Co., Ltd |
| Cargill |
| BASF |
| Zhejiang Weiss |
| Cabio Biotech (Wuhan) Co., Ltd |
| Royal DSM |
| Kingdomway Nutrition |
| Cayman Chemicals |
| Others |
Value Chain & Pricing Dynamics
Fungal strain cultivation costs for Mortierella alpina propagate through three distinct pricing tiers as fermentation-derived powder moves from Wuhan production complexes to infant formula manufacturers in Jiangsu and Zhejiang provinces, with pharmaceutical-grade liquid emulsions commanding premium positioning for Japan's PMDA-aligned clinical nutrition sector.
Pricing Analysis
Volume concentrates in powder formulations for China's infant formula sector while margins accrue to pharmaceutical-grade liquid emulsions for Japan's clinical nutrition applications. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified pharmaceutical material from food-grade powder and generic supplement-grade capsules. Cost compression in standard-grade powder is intensifying because NMPA's annual GB standard tightening forces filtration and stabilization protocol upgrades. Nutritional supplement distributors across Vietnam and Indonesia exhibit the highest price sensitivity, while Japanese hospital procurement committees demonstrate the lowest.
Supply Chain Analysis
Cold-chain logistics costs for liquid emulsion formats absorb margin disproportionately as temperature-controlled transport from Wuhan fermentation complexes to Osaka and Seoul clinical nutrition facilities runs through specialized pharmaceutical distributors with documented chain-of-custody requirements. Geographic supply concentration centers on China, India, and Japan, with raw material dependencies on fungal strain banks, fermentation nutrient media, and pharmaceutical-grade stabilizer chemicals. Single-source vulnerability concentrates in Mortierella alpina strain cultivation capacity, where equipment maintenance cycles at limited fermentation complexes create supply interruption risk. Distribution runs through dual-track structures: licensed pharmacies for pharmaceutical and infant formula grades, e-commerce platforms for direct-to-consumer supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory certification burden is accelerating consolidation as dual NMPA-FSSAI approval timelines and PMDA-aligned quality upgrades force capital-constrained regional suppliers toward acquisition or exit.
For Market Incumbents: Acquire fermentation capacity with existing multi-jurisdiction certification status to compress eighteen-to-thirty-six-month approval timelines for new entrants. Kingdomway Nutrition's captive powder formulation lines demonstrate how backward integration into downstream processing defends margin position against pure-play biotech suppliers. Cabio Biotech's Wuhan complex anchors regional pharmaceutical-grade production; replication of this asset base in India's Maharashtra corridor addresses FSSAI import substitution pressure. For New Entrants and Emerging Players: E-commerce platform partnerships in Vietnam, Indonesia, and Thailand offer first-mover positioning where nutritional supplement penetration remains underdeveloped and general food safety regulations lack specialized omega fatty acid frameworks. Capsule formats for direct-to-consumer channels bypass pharmacy licensing requirements that constrain established competitors. Target Ho Chi Minh City distribution nodes with powder and capsule SKUs before incumbent brands establish local fulfillment infrastructure. For Investors and Strategic Acquirers: PMDA-aligned METI enforcement tightening is the leading indicator that pharmaceutical-grade certification scarcity will concentrate value in qualified suppliers. The five-to-ten-year viability window favors acquisition of integrated fermentation-to-formulation specialists with existing multi-jurisdiction approvals over pure-play upstream biotech operators. Watch for NMPA GB standard revision announcements as signals of forced consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Cabio Biotech's Wuhan complex demonstrates how captive production secures pharmaceutical-grade supply for PMDA-aligned buyers. |
| Dual-Certification Investment for NMPA and FSSAI | Simultaneous approval pathways compress market access timelines for suppliers serving both Chinese and Indian infant formula manufacturers. |
| Single-Use Bioreactor Technology Adoption | Validation timeline absorption enables multi-product facility flexibility between pharmaceutical-grade and food-grade production campaigns. |
| E-Commerce Channel Expansion in Southeast Asia | Direct-to-consumer penetration in Vietnam and Indonesia bypasses traditional import distribution layers for capsule formats. |
| Lipid Emulsion Technology Development | Particle size optimization for Korean skincare manufacturers opens formulation flexibility beyond standard powder performance. |
Study Parameters
Trade databases, regulatory filing repositories, and industry association publications formed the secondary backbone, supplemented by primary interviews with fermentation plant managers, infant formula procurement leads, pharmaceutical regulatory affairs directors, and nutritional supplement distribution channel partners. Bottom-up volume modeling from production capacity disclosures triangulated against top-down demand estimates from end-use consumption patterns.
Historical trendline analysis across production volume, import-export flows, and pricing trajectories established baseline growth parameters. Segmentation dimensions modeled include formulation type, application category, end-user procurement sophistication, and distribution channel regulatory burden. CAGRs were derived from fitted trend projections incorporating capacity expansion announcements, certification timeline changes, and substitution elasticity between omega-6 and omega-3 fortification programs.
Caveats apply where NMPA GB standard revisions, FSSAI contaminant threshold adjustments, or PMDA enforcement tightening could materially shift the outlook for supplier eligibility and pricing tier compression. Forecasts reflect assumptions about fermentation scale-up talent availability and sustained infant formula fortification mandate expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Global Digestive Enzymes Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
Psyllium-Based Supplement Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Wellness Supplements Market