
 Digital Turbidity Meter Market | 2026-2036
Digital Turbidity Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Turbidity Meter Market Insights
Skilled optical engineering talent is unwinding supply constraints for high-precision nephelometric instruments. Hach Company leverages its vertical integration in light-source manufacturing to dominate North American utility procurement. Thermo Fisher Scientific sustains R&D intensity across laser-based detection platforms. Endress+Hauser Group anchors European demand through channel control in German-speaking industrial clusters.
A digital turbidity meter measures suspended particle concentration in liquids by detecting light scattering at angles, typically employing a tungsten-filament or LED source with silicon photodiode detectors sensitive to 0.01 nephelometric turbidity units. Its primary purpose spans regulatory compliance in potable water distribution, process control in beverage manufacturing, and effluent monitoring at wastewater discharge points. Laboratory-grade instruments command premium positioning due to calibration traceability requirements, while online systems are displacing manual sampling in municipal networks. Portable handheld units occupy niche environmental fieldwork where EPA methods dictate rapid deployment.
The EPA enforces turbidity limits under the Surface Water Treatment Rule, compelling utilities to maintain continuous monitoring records and validated calibration protocols. ISO 7027 standardizes nephelometric measurement geometry, creating technical barriers for non-compliant entrants in European procurement. FDA water-quality guidelines for pharmaceutical manufacturing extend demand into hygienic process instrumentation. Stakeholders must weigh captive sensor production against modular supplier ecosystems as wavelength-tunable laser sources redefine detection thresholds.
Market Dynamics
Continuous optical monitoring is displacing manual grab-sampling protocols across municipal water networks, compressing calibration cycles and forcing sensor architecture redesigns around 24/7 telemetry integration.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Tightened turbidity reporting thresholds compel utilities to deploy validated continuous monitoring systems with automated data logging.
- Beverage manufacturing quality protocols:Process control mandates in carbonated drink production drive nephelometric sensor installation at filtration checkpoints.
- German utility infrastructure retrofitting:Aging treatment plants in Bavaria and North Rhine-Westphalia are procuring laser-based detection platforms for real-time suspended particle tracking.
Market Restraints
- Optical component supply concentration:High-precision silicon photodiode fabrication concentrates in East Asian foundries, exposing lead times to geopolitical friction.
- ISO 7027 compliance costs:Nephelometric geometry standardization creates technical barriers for modular entrants lacking in-house optical engineering.
- UV-Vis spectrophotometry substitution:Multi-parameter analyzers offering turbidity-plus-absorbance measurement capture budget-constrained laboratory procurement.
Strategic Opportunities
- Indian municipal water expansion:Smart city initiatives in Maharashtra and Gujarat prioritize online turbidity monitoring for distribution network digitization.
- Laser-LED hybrid architectures:Wavelength-tunable sources combined with solid-state emitters enable single-instrument multi-range detection spanning 0.001 to 4000 NTU.
- Outcome-based service contracting:Performance-guaranteed calibration and sensor replacement subscriptions penetrate North American utility procurement.
Industry Challenges
- Photonics engineering talent scarcity:Skilled optical designers capable of scattering-angle optimization command premium compensation, constraining R&D expansion.
- Legacy SCADA integration complexity:Retrofitting continuous sensors into 1990s-era control systems demands custom protocol gateways and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Turbidity Meter Market |
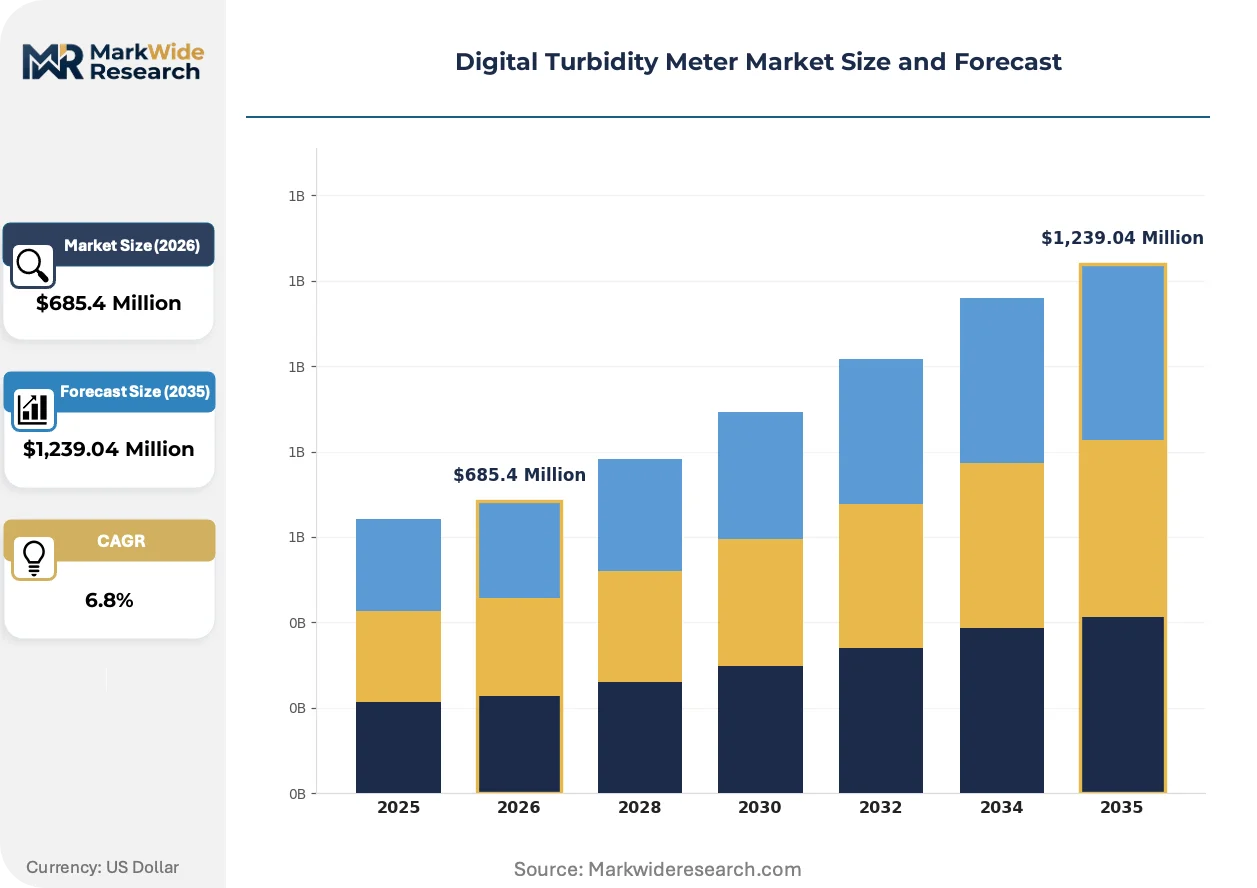
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Laboratory, Online, Handheld Technology: Optical, Nephelometric, Infrared, Laser Application: Water Quality Testing, Wastewater Treatment, Environmental Monitoring, Industrial Processes End User: Municipalities, Industries, Research Institutions, Environmental Agencies |
| Companies Covered | Hach Company, Thermo Fisher Scientific, Xylem Inc., Emerson Electric Co., Hanna Instruments, Endress+Hauser Group, METTLER TOLEDO, LaMotte Company, Horiba Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Turbidity Meter Market Trends and Innovations
Optical sensing architectures are bifurcating between laboratory-grade traceability systems and ruggedized field-deployable platforms, with digital signal processing becoming the primary differentiation axis.
MEMS-based microfluidic nephelometry is supplanting traditional cuvette-based sampling in pharmaceutical quality control laboratories. Pfizer and Roche manufacturing sites are adopting chip-scale turbidity sensors for in-line bioprocess monitoring. This miniaturization is compressing instrument footprints from benchtop to handheld while maintaining 0.01 NTU resolution.
REACH restrictions on mercury-containing lamps are accelerating LED source standardization across European laboratory equipment procurement. The F-Gas Regulation's phase-down of cooling-dependent detectors is pushing manufacturers toward thermoelectrically stabilized photodiodes. German and Swiss instrumentation vendors are redesigning optical benches around solid-state emitters to preempt compliance-driven obsolescence.
Buyers are unbundling calibration services from hardware procurement, creating standalone metrology service contracts. Municipal utilities in California and Texas now source third-party ISO 17025-accredited validation rather than factory-direct recalibration. This service fragmentation is most pronounced in regions with decentralized water district governance structures.
Digital Turbidity Meter Market Segmentation
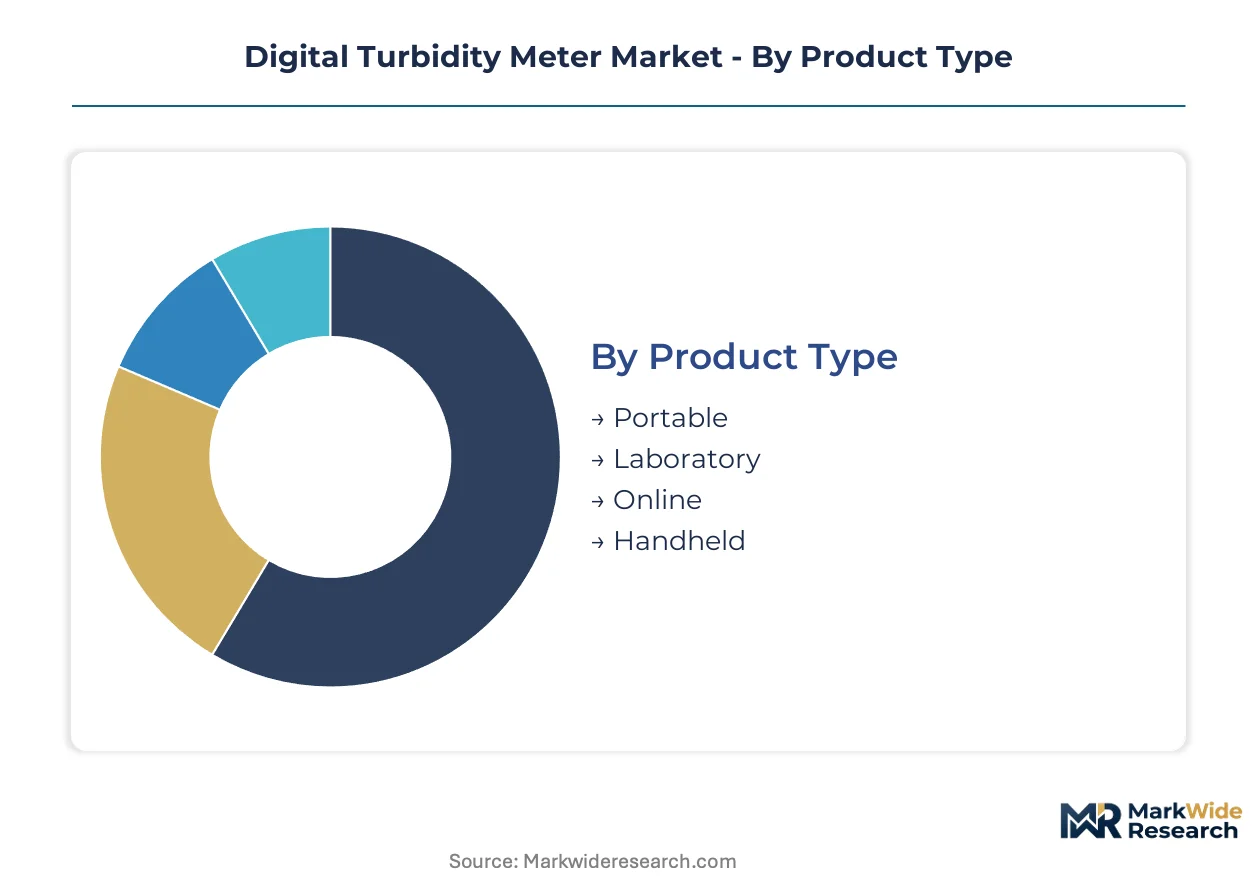
Segmentation in the Digital Turbidity Meter Market reveals distinct procurement patterns across instrumentation tiers, with substitution pressures varying sharply between laboratory-grade precision systems and ruggedized field units. Understanding these fault lines illuminates where multi-parameter analyzers threaten displacement versus where dedicated nephelometric instruments maintain defensible positioning.
Product Type:
Portable and handheld instruments face acute substitution pressure from smartphone-integrated colorimetric apps and dipstick-based rapid tests, while laboratory and online systems defend their installed base through regulatory calibration traceability requirements.
- Portable:Battery-powered units with 0.1 NTU resolution serve environmental field crews conducting EPA Method 180.1 compliance checks at remote surface water sites. Demand concentrates in California's Central Valley water districts where agricultural runoff monitoring mandates frequent site visits, though budget compression is pushing some districts toward rental models over ownership.
- Laboratory:Benchtop systems with 0.01 NTU resolution and ISO 7027-compliant 90-degree detection geometry command premium positioning through NIST-traceable calibration certificates. German pharmaceutical manufacturers in Baden-Württemberg sustain procurement intensity for validated batch-release testing, insulating this segment from price-based competition.
- Online:Continuous monitoring systems with 4-20mA output and automated cleaning mechanisms integrate directly into SCADA-controlled treatment trains. Municipal utilities in Bavaria deploy these for real-time coagulation dosing optimization.
- Handheld:Single-operator devices with simplified one-button operation target rapid-response scenarios such as flood event assessment and emergency distribution system checks.
Online systems anchor the volume base while portable units gain share at the steepest rate through rental-service model expansion.
Technology:
Cost tier stratification separates legacy tungsten-filament optical platforms from solid-state laser architectures, with infrared and LED-based systems occupying intermediate price-performance positions.
- Optical:Broadband white-light sources with silicon photodiode detectors dominate legacy installed bases across North American municipal utilities, though mercury lamp phase-outs under ECHA restrictions are forcing upgrade cycles.
- Nephelometric:90-degree scattered light detection per ISO 7027 geometry remains the regulatory gold standard for potable water compliance reporting in Germany, Switzerland, and Austria. This standardization creates technical moats against non-compliant entrants.
- Infrared:860nm wavelength sources minimize interference from dissolved color compounds in high-organic surface waters. Scandinavian pulp and paper mills favor this technology for effluent monitoring where lignin content disturbs visible-light measurements.
- Laser:Collimated monochromatic sources enable detection thresholds below 0.001 NTU for pharmaceutical-grade water validation. Swiss biologics manufacturers in Basel cluster drive premium procurement.
Nephelometric platforms anchor the volume base while laser architectures expand most quickly in hygienic process applications.
Application:
Customer type concentration varies by application maturity, with water quality testing showing the deepest municipal penetration and industrial processes presenting the most fragmented procurement landscape.
- Water Quality Testing:Potable water distribution monitoring under EPA Safe Drinking Water Act mandates sustains replacement demand across US municipal networks, with Texas and Florida utilities prioritizing telemetry-enabled continuous systems over manual sampling.
- Wastewater Treatment:Secondary clarifier effluent monitoring for suspended solids correlation drives nephelometric sensor deployment. German Ruhrgebiet utilities retrofit aging plants with laser-based platforms for real-time solids loading feedback.
- Environmental Monitoring:Surface water and groundwater surveillance programs in Maharashtra and Gujarat smart city initiatives prioritize online turbidity as a proxy for sediment loading and stormwater intrusion.
- Industrial Processes:Beverage filtration checkpoint control and chemical crystallization monitoring create diverse specification requirements across carbonated drink manufacturers and specialty chemical producers.
Water quality testing anchors the volume base while environmental monitoring climbs the fastest on smart city infrastructure investment.
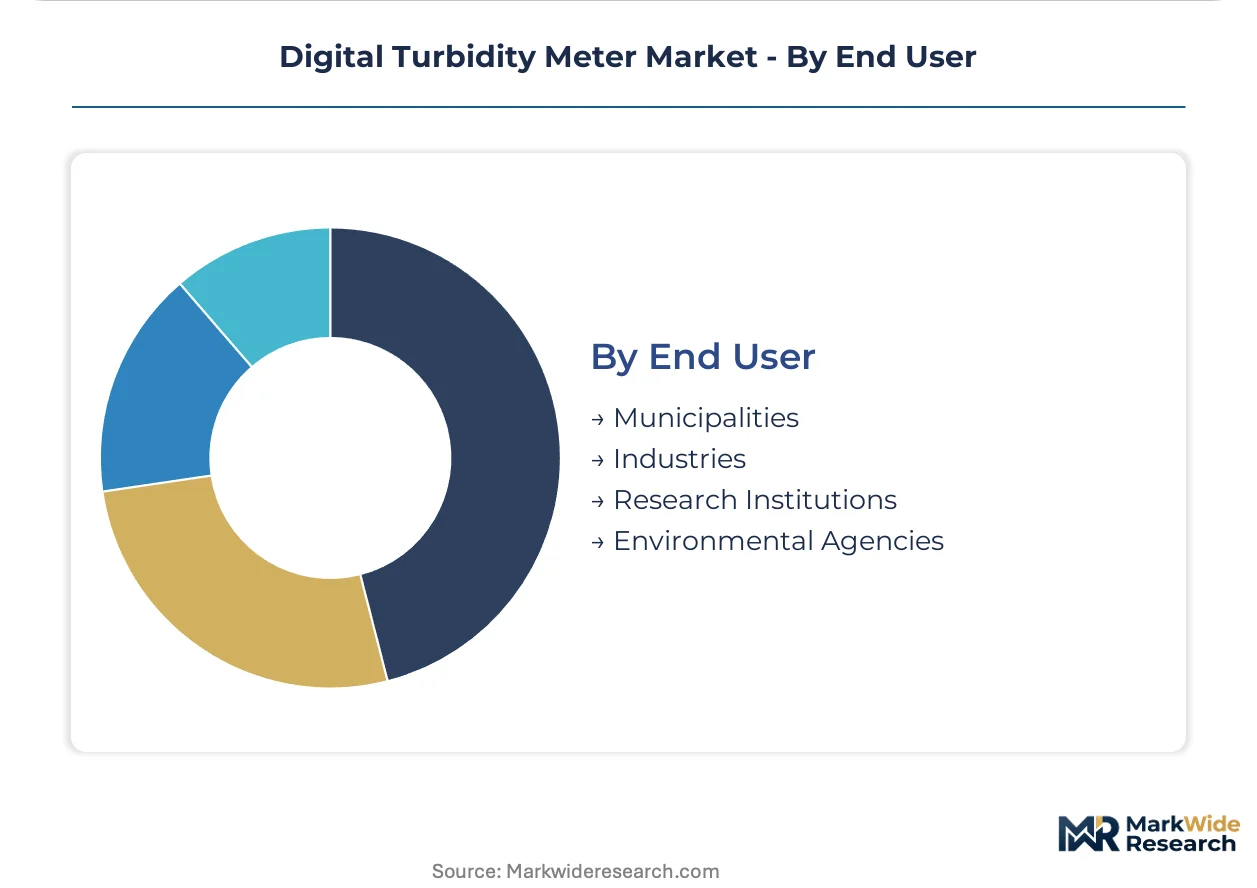
End User:
Procurement sophistication separates municipalities with centralized technical standards from industrial buyers with decentralized plant-level decision authority.
- Municipalities:Centralized procurement departments in Germany's North Rhine-Westphalia specify ISO 7027 compliance and multi-year calibration service contracts as mandatory bid criteria, compressing vendor margins through competitive tendering.
- Industries:Beverage manufacturers and chemical processors balance regulatory compliance against process optimization, with larger groups standardizing on single-vendor platforms to simplify metrology training.
- Research Institutions:University environmental science departments and government laboratories prioritize modularity and open data formats for method development flexibility.
- Environmental Agencies:Federal and state-level regulators in the US and EU deploy reference-grade instrumentation for audit and enforcement activities requiring defendable measurement uncertainty budgets.
Municipalities anchor the volume base while environmental agencies gain procurement share through expanded surface water surveillance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities deploy continuous nephelometric monitoring for real-time coagulation control, while Indian municipalities favor portable units for smart city field deployment. This consumption-mix differential reflects infrastructure maturity gaps and regulatory enforcement variance.
United States
Texas and Florida utilities prioritize telemetry-enabled online systems for EPA Safe Drinking Water Act compliance. The EPA mandates continuous monitoring records with validated calibration protocols. California's Central Valley water districts concentrate portable unit procurement for agricultural runoff surveillance.
Germany
Bavarian and North Rhine-Westphalian treatment plants retrofit aging infrastructure with laser-based detection platforms. The country's implementation of ISO 7027 geometry standards creates technical procurement barriers. Baden-Württemberg pharmaceutical manufacturers sustain premium laboratory-grade instrument demand for batch-release validation.
India
Maharashtra and Gujarat smart city initiatives prioritize online turbidity monitoring for distribution network digitization. The Central Electricity Authority guidelines encourage instrumentation standardization. Mumbai and Ahmedabad municipal corporations deploy portable units for rapid-response field assessment.
China
Yangtze River Delta municipalities expand procurement of multi-parameter water quality stations. The Ministry of Ecology and Environment tightens surface water discharge monitoring requirements. Shanghai treatment facilities integrate nephelometric sensors into SCADA-controlled coagulation dosing systems.
Switzerland
Basel biologics manufacturers drive premium laser-based instrument procurement for pharmaceutical-grade water validation. The F-Gas Regulation accelerates LED source standardization across laboratory equipment. Zurich and Geneva utilities deploy continuous monitoring for alpine source water turbidity tracking.
Digital Turbidity Meter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around optical engineering capability and calibration service networks. The upper tier commands utility procurement through captive light-source manufacturing and multi-year service contracting. Mid-scale specialists compete on modular platform flexibility and rapid commissioning timelines. Dominant competitive moves include backward integration into photonics component supply and geographic expansion through metrology service partnerships.
Among North American integrated instrumentation groups, Hach Company and Thermo Fisher Scientific exemplify the premium-tier archetype through vertical control over manufacturing inputs. Endress+Hauser Group anchors European demand positioning within German-speaking industrial clusters. These three entities represent contrasting strategic postures: captive production depth, diversified R&D portfolios, and channel-controlled regional market penetration.
| Leading Market Players |
|---|
| Hach Company |
| Thermo Fisher Scientific |
| Xylem Inc. |
| Emerson Electric Co. |
| Hanna Instruments |
| Endress+Hauser Group |
| METTLER TOLEDO |
| LaMotte Company |
| Horiba Ltd. |
| Others |
Pricing and Supply Chain Analysis
ISO 7027 compliance requirements gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb optical engineering costs that laboratory-grade buyers willingly premiumize while municipal tenders compress margins on standard-tier instruments.
Pricing Analysis
Long-term service contracts dominate municipal procurement, with German utilities locking in multi-year calibration subscriptions that bundle hardware replacement and telemetry integration. Price differentiation separates NIST-traceable laboratory systems from field-deployable portable units, with certification grade and after-sales service bundling as primary tiering mechanisms. Cost compression in the portable segment intensifies as smartphone-integrated colorimetric alternatives capture environmental fieldwork budgets. Municipal procurement departments exhibit highest price sensitivity, while pharmaceutical manufacturers in Basel and Baden-Württemberg prioritize measurement uncertainty budgets over unit cost.
Supply Chain Analysis
Extended lead times for high-precision silicon photodiodes now stretch procurement cycles, with inventory buffers thinning across German and Swiss instrument manufacturers. Optical component fabrication concentrates in Taiwan, South Korea, and Japan, with specialized LED emitter production anchored in East Asian foundries. Raw material dependencies include silicon wafers, rare-earth phosphors for wavelength stabilization, and thermoelectric cooling modules. Single-source vulnerability for 860nm infrared emitters exposes European vendors to export control friction. Distribution runs through authorized metrology service partners who maintain regional calibration laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from multi-parameter UV-Vis analyzers that bundle turbidity with absorbance measurement, requiring defensive positioning around regulatory traceability and continuous monitoring integration.
For Market Incumbents: Secure captive supply of wavelength-tunable laser sources through backward integration or exclusive offtake agreements with photonics foundries. Deepen calibration service network density in North Rhine-Westphalia and Bavaria to preempt third-party metrology entrants from unbundling hardware procurement.
For New Entrants and Emerging Players: Anchor in Maharashtra and Gujarat smart city initiatives where procurement standardization remains nascent and price competition from established European brands is weakest. Target portable unit rental models for California Central Valley water districts, leveraging outcome-based contracting to bypass capital budget constraints.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed environmental instrumentation platforms that consolidated water quality testing portfolios. Evaluate targets on their installed base telemetry penetration and recurring calibration revenue mix. Watch for EPA Safe Drinking Water Act amendment enforcement intensity as inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photonics Component Supply | Hach Company's captive LED manufacturing secures margin control against East Asian foundry pricing volatility. |
| Calibration Service Network Expansion | Endress+Hauser's German-speaking channel density preempts third-party metrology unbundling in Bavarian utility tenders. |
| Laser-LED Hybrid Architecture Development | Thermo Fisher Scientific's multi-range detection platforms capture pharmaceutical-grade and municipal procurement simultaneously. |
| Smart City Partnership Formation | Penetration of Maharashtra and Gujarat initiatives establishes foothold before procurement standardization crystallizes. |
| Outcome-Based Service Contracting | Performance-guaranteed subscriptions in Texas and California utilities convert capital expenditure to operational budget capture. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with municipal water treatment plant engineers, optical instrumentation procurement managers, and pharmaceutical quality control directors; and secondary validation through EPA enforcement records, ISO certification registries, and customs trade data for photonics component flows. Triangulation across bottom-up unit economics and top-down sector expenditure estimates anchored volume and value projections.
Across the projection horizon, the analytical framework modeled segmentation dimensions including instrument grade tier, detection technology architecture, end-use application maturity, and regional regulatory enforcement intensity. CAGRs derived from fitted growth curves applied to disclosed utility capital expenditure plans and pharmaceutical manufacturing capacity expansion announcements. Forecast inputs incorporated REACH mercury lamp phase-out timelines and F-Gas Regulation compliance deadlines.
Decision-makers should treat outputs as directional under base assumptions of continued EPA Safe Drinking Water Act enforcement and stable East Asian photonics supply; material deviation in regulatory stringency or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Micro Balances Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Microanalysis Sample Preparation Systems Market
Analytical Instruments
High Purity Gas Flow Meter Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Digital Moisture Analyzer Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
XRF Analyzer Market