
 Short Range Air Defense Systems Market | 2026-2036
Short Range Air Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Short Range Air Defense Systems Market Analytics
Market Dynamics
Missile defense engineering talent scarcity across NATO defense industrial bases is reorganizing contractor hiring pipelines and joint development agreements. Lockheed Martin Corporation leverages its directed energy research campuses to sustain laser-based close-in weapon prototyping. RTX Corporation anchors layered defense architectures through radar and kinetic interceptor integration. Thales Group competes in European mobility-focused programs with vehicle-mounted rapid-deployment systems.
Technical Landscape
Short range air defense systems encompass kinetic interceptors, directed energy weapons, and command-and-control nodes designed to defeat rotary-wing aircraft, unmanned aerial systems, and precision munitions at ranges below ten kilometers and altitudes under six thousand meters. These systems integrate radar cueing with electro-optical tracking to achieve engagement timelines measured in seconds against saturation threats. Vehicle-mounted platforms lead procurement volumes due to mechanized unit modernization cycles, while laser systems represent the fastest-expanding technology segment as solid-state power scaling matures. Military end users dominate budget allocation, though private security applications around critical infrastructure are emerging as a discrete margin pool.
Regulatory Environment
NATO Standardization Office frameworks govern interoperability requirements for member-state short range air defense acquisitions, while national regulators including the US Department of Defense and European defence procurement agencies enforce cybersecurity and supply chain security certifications. These standards shape product roadmaps by mandating open architecture interfaces and encrypted data links that restrict non-compliant vendors from program participation. Stakeholders must monitor directed energy weapon protocol developments at the Convention on Certain Conventional Weapons and corresponding national export control adjustments that could reclassify laser-based systems.
Market Dynamics
The Short Range Air Defense Systems Market is reconfiguring around directed energy maturation, as solid-state laser power scaling disrupts decades of kinetic interceptor dominance and forces contractors to retool manufacturing footprints.
Growth Catalysts
- NATO electronic warfare doctrine updates:Alliance-wide mandates for counter-UAS and low-altitude interception capabilities are accelerating vehicle-mounted platform procurement across mechanized units.
- Forward-deployed infrastructure expansion:Poland, Romania, and the Baltic states are driving urgent requirements for layered air defense architectures near contested borders.
- Critical infrastructure protection:Private security applications around energy facilities and transportation nodes are emerging as a discrete demand channel for man-portable systems.
Market Restraints
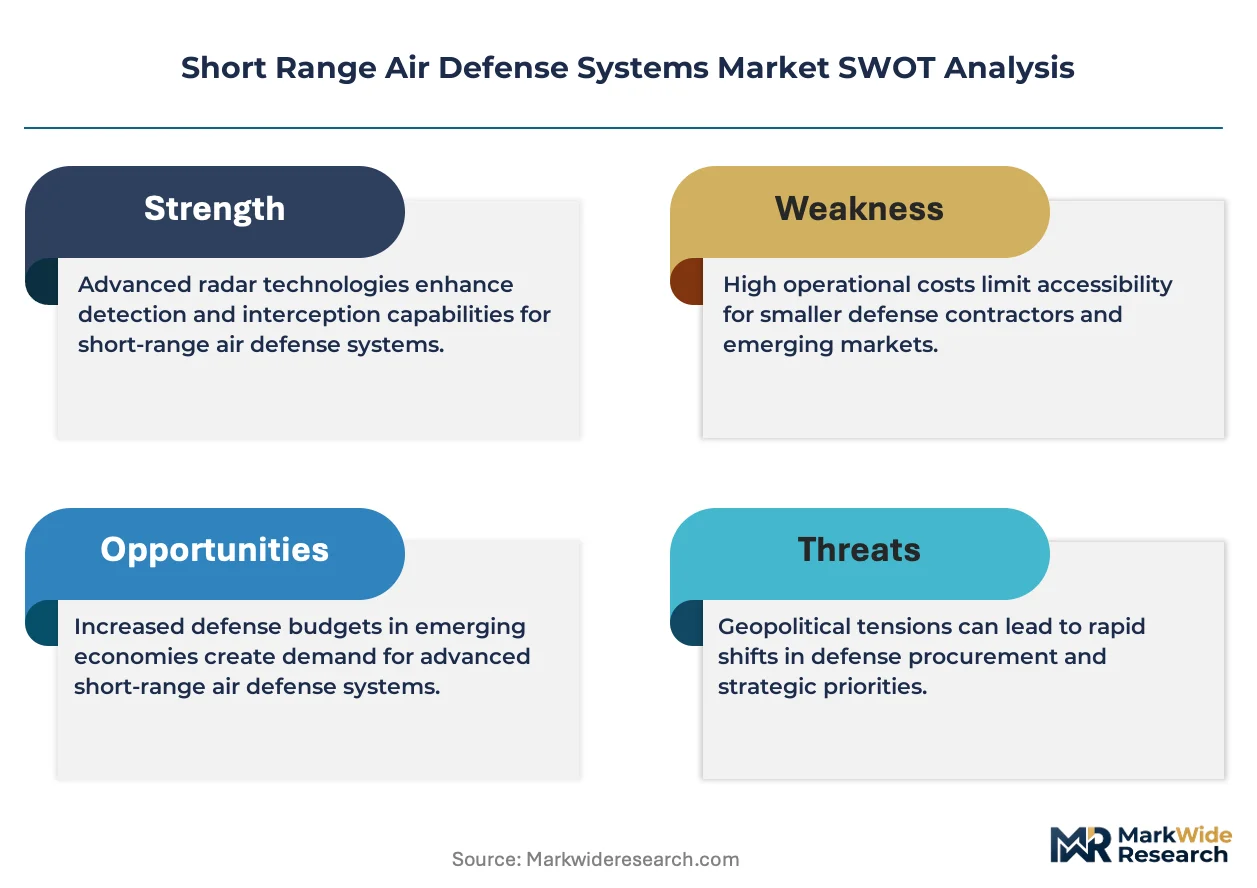
- Rare earth magnet supply concentration:Solid-state laser and advanced radar systems depend on neodymium and dysprosium inputs where processing capacity concentrates in single-source jurisdictions.
- Directed energy weapon protocol uncertainty:The Convention on Certain Conventional Weapons has not finalized classification frameworks, creating export control friction for laser-based platforms.
- Kinetic interceptor obsolescence risk:Stockpiled missile inventories face accelerated depreciation as engagement economics shift toward reusable energy weapons.
Strategic Opportunities
- Laser-kinetic convergence architectures:Hybrid systems combining solid-state directed energy with backup kinetic interceptors address saturation threat scenarios while hedging power reliability limitations.
- Urban air mobility corridor defense:Emerging commercial drone traffic in European and Middle Eastern cities creates demand for compact, civilian-certifiable detection and defeat systems.
- Open architecture mandate compliance:NATO Standardization Office interoperability requirements favor vendors with modular command-and-control software stacks over proprietary legacy platforms.
Industry Challenges
- Directed energy systems engineering talent scarcity:Optical physics and high-power electronics specializations are concentrated in a handful of defense research campuses, constraining workforce scaling.
- Legacy radar integration complexity:New electro-optical tracking layers must interface with decades-old command infrastructure without degrading millisecond engagement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short Range Air Defense Systems Market |
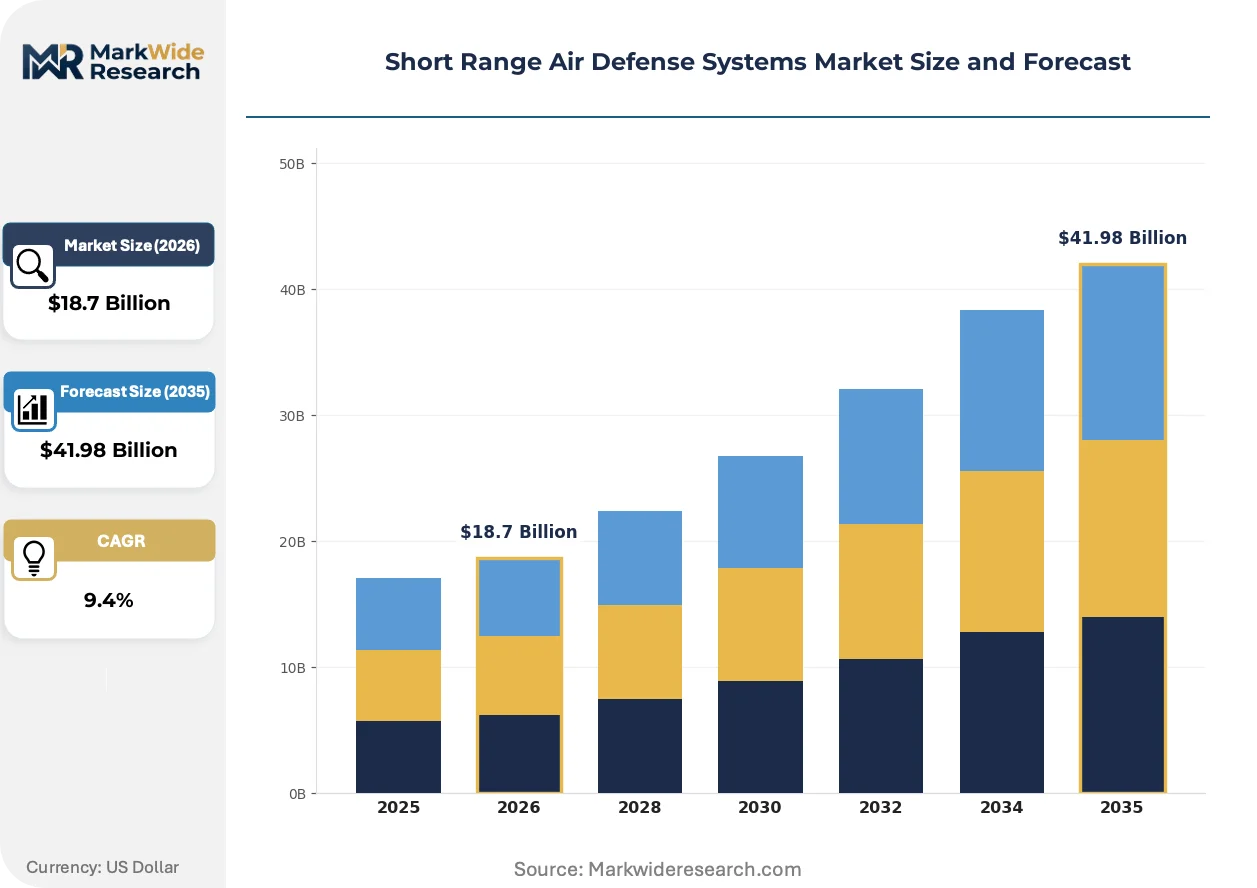
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Man-Portable, Vehicle-Mounted, Fixed Installations, Naval Systems Technology: Radar-Based, Laser Systems, Infrared Systems, Electro-Optical Systems End User: Military, Government Agencies, Private Security, Industrial Deployment Model: Onshore, Offshore, Mobile, Permanent |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Thales Group, BAE Systems plc, Saab AB, MBDA, Rheinmetall AG, Israel Aerospace Industries, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short Range Air Defense Systems Market Evolving Landscape
Solid-state laser technology is compressing the cost-per-engagement economics of close-in air defense, while procurement models shift toward performance-based contracting that penalizes missed intercepts rather than rewarding platform delivery.
Directed energy weapons are fragmenting the traditional kinetic interceptor market. Solid-state lasers achieving 50-100 kilowatt output levels provide unlimited magazine depth against drone swarms. Mechanized infantry units in NATO's eastern flank are field-testing these systems at unprecedented pace. The technology is fragmenting contractor revenue models away from recurring missile sales toward higher-margin depot-level maintenance contracts.
EU defense procurement agencies are tightening cybersecurity certification requirements under the European Defence Fund framework. Manufacturers must demonstrate encrypted data link resilience and supply chain provenance for all semiconductor components. Vehicle-mounted platform vendors are responding by pre-integrating NATO-standard communications protocols before national tender submission.
After-sales service unbundling is altering buyer-vendor relationships in military air defense. Defense ministries are separating platform acquisition from sustainment contracts, awarding multi-year performance agreements to third-party integrators. Poland and Romania have pioneered this model in recent mechanized unit modernization cycles, forcing original equipment manufacturers to compete separately for maintenance revenue pools.
Short Range Air Defense Systems Market Segmentation
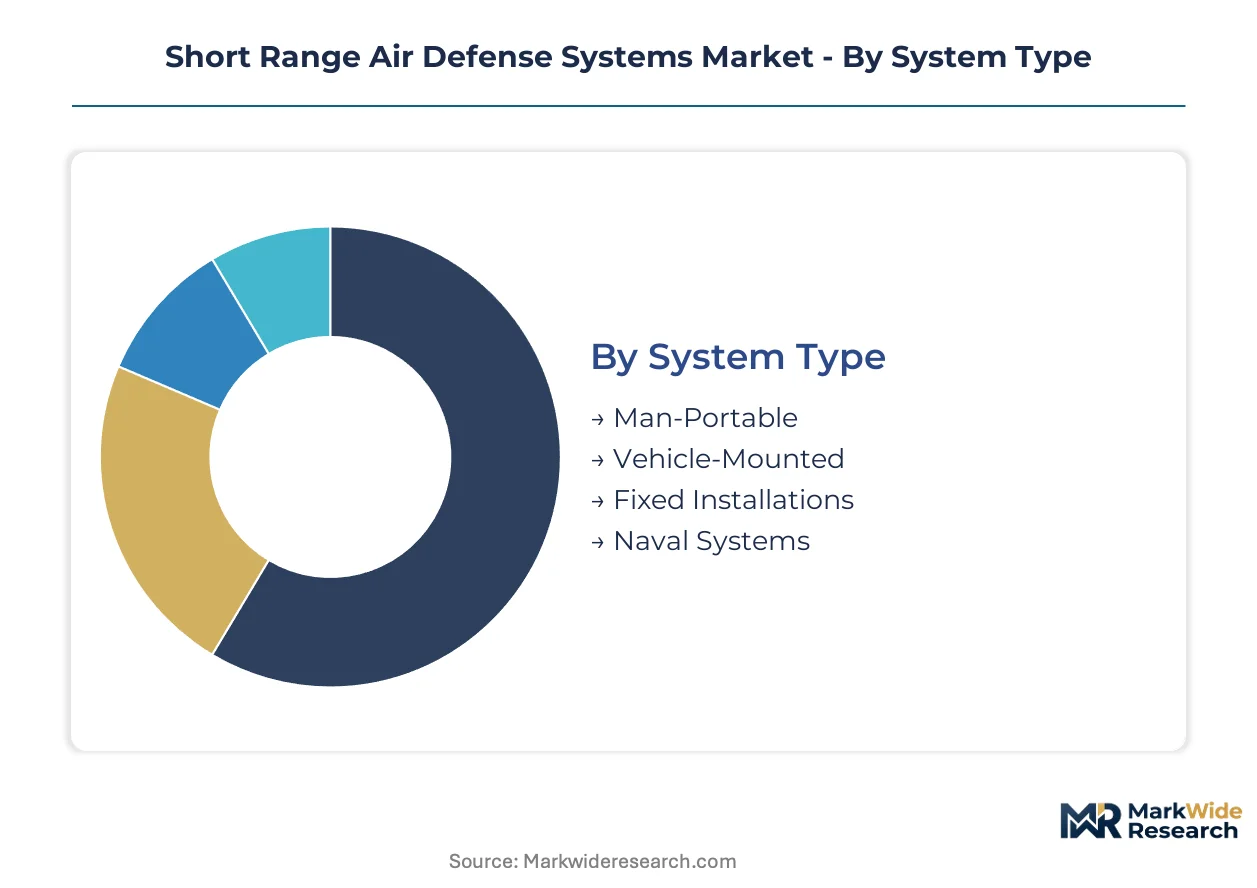
Segmentation in short range air defense systems reveals how procurement channels bifurcate between military program offices and emerging commercial security integrators. Each dimension exposes distinct margin structures, certification requirements, and technology readiness thresholds that reshape vendor go-to-market strategies.
System Type:
Vehicle-mounted platforms flow through defense ministry mechanized modernization budgets, while man-portable systems split between military special operations procurement and private security distributors.
- Man-Portable:Shoulder-launched interceptors and compact directed energy units weighing under 25 kilograms for dismounted infantry and facility security teams. Demand concentrates in Baltic states and Poland for border patrol units responding to low-altitude drone incursions, constrained by battery thermal management in extreme cold climates.
- Vehicle-Mounted:Turret-integrated systems on armored personnel carriers and light tactical vehicles combining radar, electro-optical sensors, and kinetic or laser effectors. NATO eastern flank mechanized brigades in Romania and Poland are driving procurement volumes as forward-deployed infrastructure expands.
- Fixed Installations:Permanent emplacements protecting critical infrastructure including airfields, command centers, and energy facilities with hardened command nodes.
- Naval Systems:Shipboard close-in weapon systems adapted for littoral operations and amphibious platforms with stabilized tracking against sea-skimming threats.
By volume, vehicle-mounted systems lead. By growth pace, man-portable configurations are expanding most quickly.
Technology:
Cost tiers separate mature radar-guided kinetic interceptors from developmental solid-state lasers demanding premium R&D recovery pricing.
- Radar-Based:Active electronically scanned array and pulse-Doppler radars providing all-weather detection and fire control cueing. Legacy NATO command infrastructure in Germany and the United Kingdom requires backward-compatible waveform protocols, slowing upgrade cycles.
- Laser Systems:Solid-state fiber and slab lasers achieving 50-100 kilowatt outputs for unlimited magazine depth against drone swarms. Polish and Romanian field trials are validating mobile platforms, though thermal management and atmospheric compensation constrain deployment latitude.
- Infrared Systems:Passive thermal imaging for covert detection and terminal guidance, prevalent in man-portable and fixed-site applications.
- Electro-Optical Systems:Day/night cameras with laser rangefinders and target trackers for visual identification and precision engagement.
Radar-based platforms retain the largest installed base. Laser systems are climbing the fastest as engagement economics shift from per-missile to per-shot costing.
End User:
Customer type determines certification intensity, with military programs demanding NATO Standardization Office interoperability and private security accepting civilian-grade detection thresholds.
- Military:Defense ministries procuring layered air defense for mechanized units, expeditionary forces, and fixed-site protection under national security classifications.
- Government Agencies:Border guards, coast guards, and national police acquiring counter-drone capabilities for territorial security without full military specification.
- Private Security:Critical infrastructure operators in energy and transportation sectors purchasing man-portable and fixed systems for facility defense, subject to national export control licensing.
- Industrial:Mining, construction, and logistics firms protecting remote sites from commercial drone surveillance or interference.
Military end users dominate absolute spending. Private security is gaining share fastest as regulatory frameworks for civilian counter-drone operations mature.
Deployment Model:
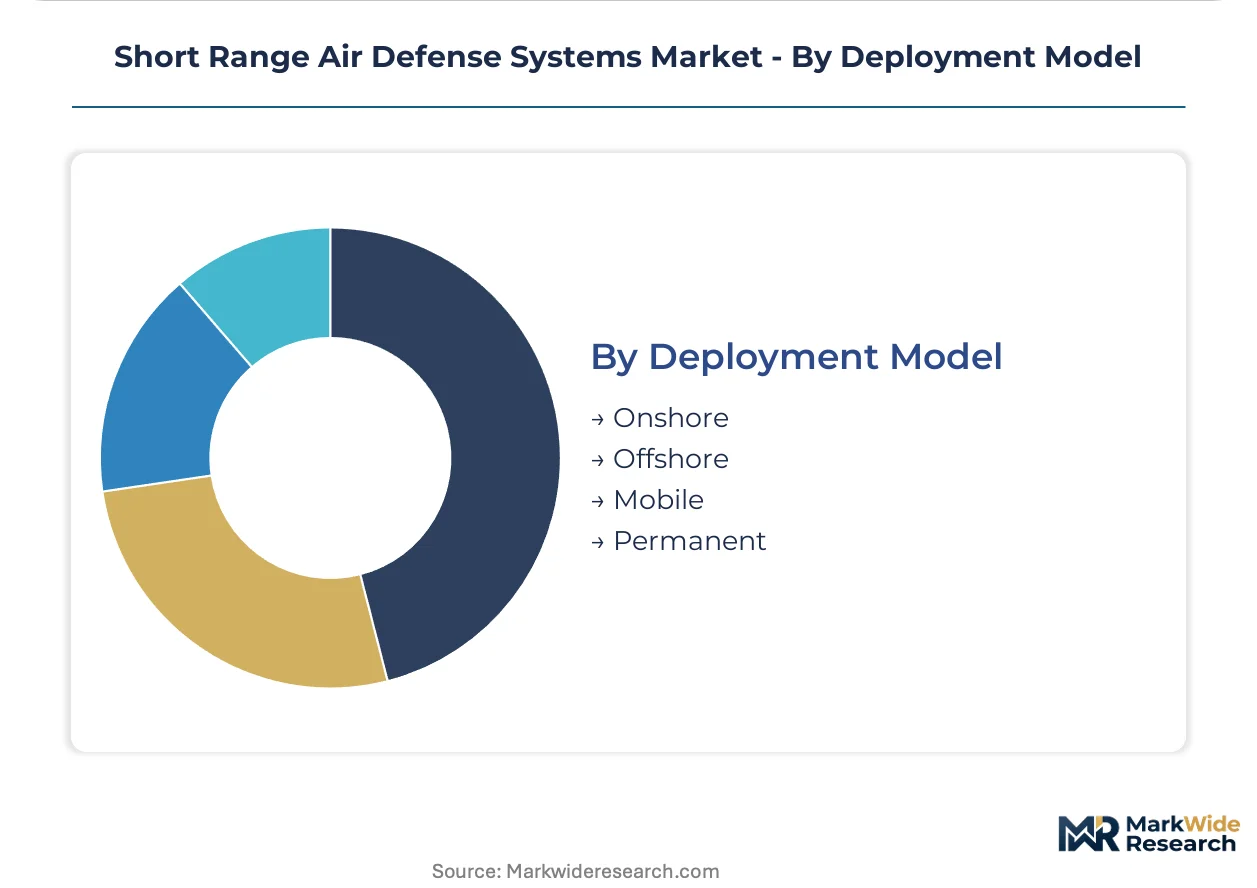
Application context dictates mobility requirements, with mobile platforms requiring rapid emplacement capability and permanent installations accepting longer integration timelines.
- Onshore:Land-based systems protecting territorial airspace, military installations, and critical infrastructure across contested border regions.
- Offshore:Platform and vessel defense for exclusive economic zone protection and littoral maritime operations.
- Mobile:Rapidly relocatable systems supporting maneuver warfare and expeditionary deployment with reduced logistics footprint.
- Permanent:Hardened, networked architectures for strategic site defense with dedicated power and communications infrastructure.
Mobile deployments lead procurement volumes. Permanent installations show steepest expansion trajectory as critical infrastructure hardening accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland deploys vehicle-mounted systems for mechanized brigade modernization, while Romania concentrates on layered border architectures and the Baltic states prioritize man-portable counter-drone units for territorial defense.
Poland
Forward-deployed NATO infrastructure drives urgent procurement of mobile air defense platforms for mechanized units operating near contested borders. The Ministry of National Defence accelerates tender processes under the Wisła and Narew layered defense programs. Industrial activity concentrates in Warsaw and the Łódź Voivodeship, where defense contractors integrate radar and electro-optical systems for rapid-deployment requirements.
Romania
Black Sea corridor security priorities shape investment in fixed installations protecting energy terminals and military airfields against low-altitude saturation threats. The Romanian Ministry of Defence aligns acquisitions with NATO Standardization Office interoperability mandates. Clusters in Bucharest and the Ploiești region host integration facilities for vehicle-mounted platforms supporting expeditionary deployment.
Germany
Legacy command infrastructure modernization constrains upgrade cycles for radar-based systems across Bundeswehr mechanized divisions. The Federal Ministry of Defence enforces cybersecurity certification under EU Defence Fund frameworks. Industrial concentration in Bavaria and Baden-Württemberg sustains precision manufacturing for turret-integrated defense architectures.
United States
Directed energy prototyping receives priority funding through Army Rapid Capabilities and Critical Technologies Office programs validating solid-state laser mobility. The Department of Defense mandates open architecture interfaces and encrypted data link resilience for all new acquisitions. Activity concentrates in Texas and Arizona, where directed energy research campuses field-test 50-100 kilowatt systems against drone swarm scenarios.
United Kingdom
Expeditionary force requirements drive demand for rapidly relocatable systems supporting littoral and amphibious operations. The Ministry of Defence integrates short range air defense into maritime strike group architectures under Joint Force 2025 planning. Industrial clusters in Scotland and the Southwest of England specialize in naval close-in weapon system adaptation for multi-domain employment.
Short Range Air Defense Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in platforms combining radar, electro-optical tracking, and kinetic or directed energy effectors. The structure rewards vendors with captive directed energy research pipelines and established NATO certification pathways. Two strategic archetypes dominate: full-stack integrators commanding mechanized modernization budgets, and technology specialists capturing laser-kinetic hybrid development contracts. Competitive intensity manifests through strategic partnerships securing rare earth magnet supply chains and joint ventures accelerating solid-state laser field testing.
Among US-based integrated defense contractors, Lockheed Martin Corporation and RTX Corporation exemplify full-stack archetypes spanning radar, kinetic interceptor, and directed energy portfolios. Thales Group represents the European mobility-focused tier, anchoring vehicle-mounted rapid-deployment programs. These three entities occupy positions that align with NATO electronic warfare doctrine updates and forward-deployed infrastructure expansion priorities across Poland, Romania, and the Baltic states.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Thales Group |
| BAE Systems plc |
| Saab AB |
| MBDA |
| Rheinmetall AG |
| Israel Aerospace Industries |
| Northrop Grumman Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at solid-state laser foundries in the United States and Germany shapes both supply concentration and price floors for directed energy weapon components, compressing margins for kinetic interceptor manufacturers while elevating premiums for rare earth magnet-dependent radar systems.
Pricing Analysis
Long-term performance-based offtake agreements dominate procurement between NATO defense ministries and prime contractors, with pricing stratifying across premium laser-kinetic hybrid tiers, standard radar-guided kinetic systems, and economy man-portable configurations. Price differentiation rests on NATO Standardization Office certification grade and after-sales service bundling, with Polish and Romanian tenders showing acute sensitivity to depot-level maintenance costs. Cost compression in standard kinetic tiers is intensifying because stockpiled missile inventories face accelerated depreciation against reusable energy weapons. Private security buyers exhibit highest price sensitivity, while military program offices prioritize interoperability premiums over unit economics.
Supply Chain Analysis
Strategic stockpiling of neodymium and dysprosium magnets supersedes just-in-time preferences across defense industrial bases, reflecting single-source jurisdiction concentration in China for rare earth processing. Solid-state laser systems draw from semiconductor fabrication capacity in the United States, Germany, and Taiwan, with advanced radar arrays sourcing gallium nitride substrates from Japan and South Korea. Single-source vulnerability in rare earth magnet supply creates structural exposure to export control friction. Distribution runs through national defense procurement agencies with encrypted data link certification requirements acting as gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent kinetic interceptor manufacturers face substitution defense imperatives as solid-state directed energy weapons displace missile-based engagement economics across NATO mechanized units.
For Market Incumbents: Consolidate directed energy research pipelines through captive optical physics talent acquisition in Texas and Arizona research campuses, while securing long-term rare earth magnet supply agreements to hedge against Chinese export control friction. Lockheed Martin Corporation and RTX Corporation demonstrate full-stack positioning that blends radar, kinetic, and laser portfolios to defend against pure-play directed energy specialists.
For New Entrants and Emerging Players: After-sales service unbundling in Polish and Romanian mechanized modernization cycles exposes white-space for third-party sustainment integrators unencumbered by legacy platform baggage. Target private security applications around European energy facilities with civilian-certifiable man-portable counter-drone systems, leveraging modular NATO-standard software stacks to bypass proprietary incumbent lock-in.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid laser-kinetic developers with validated field trials in NATO eastern flank deployments over pure directed energy plays facing atmospheric compensation constraints. Long-term viability hinges on open architecture compliance and encrypted data link certification pathways. Watch directed energy weapon protocol finalization at the Convention on Certain Conventional Weapons as the signal indicating export control clarity or prolonged licensing friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Kinetic Hybrid Development | Addresses saturation threat scenarios while hedging power reliability limitations in Polish field trials. |
| Rare Earth Magnet Supply Agreement | Secures neodymium and dysprosium inputs against Chinese export control concentration risk. |
| Open Architecture Certification | Enables NATO Standardization Office interoperability compliance for program participation eligibility. |
| After-Sales Service Unbundling | Captures multi-year performance agreements in Romanian mechanized unit modernization cycles. |
| Directed Energy Talent Acquisition | Consolidates scarce optical physics specializations concentrated in Arizona and Texas research campuses. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers at NATO member ministries, directed energy research directors at US Army Rapid Capabilities and Critical Technologies Office facilities, and aftermarket sustainment integrators in Poland and Romania, then refined through secondary validation against NATO Standardization Office interoperability frameworks, US Department of Defense acquisition databases, EU Defence Fund cybersecurity certification guidelines, and national tender documentation from Polish and Romanian defense ministries. Bottom-up platform deployment estimates triangulated with top-down defense budget allocation analysis.
Variance decomposition across system type, technology maturity, and end-user certification intensity structured the analytical framework over the projection horizon. Segmentation dimensions encompassed vehicle-mounted versus man-portable configurations, kinetic versus directed energy effector types, and military versus private security procurement channels. CAGRs derived from deployment timeline phasing in forward-deployed NATO infrastructure and mechanized brigade modernization cycles. Industry-specific inputs included solid-state laser power scaling curves and rare earth magnet supply elasticity assumptions.
Underlying assumptions cover directed energy weapon protocol resolution timelines and rare earth export control stability, with deviation risk concentrated in atmospheric compensation validation for mobile laser platforms and NATO electronic warfare doctrine update pacing. Revision becomes warranted when Convention on Certain Conventional Weapons classification frameworks cross thresholds triggering reclassification of laser-based systems under national export control regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
Air Defense System Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Global Missile Interceptor Market
Air Defense
Airborne Fire Control Radar Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Americas Air Defense Systems Market