
 Asia-Pacific Air Defense Systems Market | 2026-2036
Asia-Pacific Air Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Air Defense Systems Market Outlook
The Asia-Pacific air defense landscape is recalibrating around a widening gap between premium integrated multi-domain systems and commodity point-defense solutions. Lockheed Martin leverages its PAC-3 and THAAD integration expertise to anchor high-value contracts in Japan and Australia. Hanwha Systems competes through indigenous radar and command architecture tailored to South Korea's kill-chain doctrine. Almaz-Antey Corp dominates long-range surface-to-air missile supply to Vietnam and Myanmar through cost-competitive S-400 derivatives.
Asia-Pacific air defense systems encompass layered detection, tracking, and interception architectures designed to neutralize aerial threats from cruise missiles to hypersonic glide vehicles, typically operating at engagement ranges from 5 km to 400 km with reaction times under 30 seconds. These systems serve national sovereignty protection and force projection denial across contested airspaces. Missile systems capture the largest value pool as nations prioritize kinetic interceptors over passive surveillance, while radar systems represent the fastest-growing segment due to demand for low-probability-of-intercept AESA arrays and over-the-horizon backscatter installations. Command and control systems sit at the margin center, with network-centric warfare integration commanding premium pricing from militaries seeking sensor-to-shooter latency below 10 seconds.
Japan's Acquisition, Technology and Logistics Agency enforces stringent interoperability standards with U.S. joint force architectures, while India's DRDO certification mandates progressively exclude non-indigenous subsystems from domestic procurement. Australia's Defence Trade Controls Act restricts technology transfer pathways, compelling foreign OEMs to establish sovereign maintenance capabilities. Stakeholders must monitor how AUKUS Pillar Two technology sharing agreements reshape supplier qualification pathways across the region.
Market Dynamics
Integrated multi-domain command architectures are compressing sensor-to-shooter latency thresholds below 10 seconds across Southeast Asian procurement specifications, forcing legacy point-defense vendors to requalify for network-centric warfare contracts or exit tier-one supplier pools entirely.
Growth Catalysts
- India's PLI scheme for defense manufacturing:Domestic content mandates now require 60% indigenous value addition for missile subsystems, accelerating local radar and seeker production.
- Hypersonic threat proliferation:China's DF-17 deployments across the Taiwan Strait are compelling Japan and Australia to accelerate directed-energy and kinetic interceptor development programs.
- AUKUS Pillar Two technology sharing:Quantum sensing and AI-enabled target recognition protocols are being harmonized between Australian, UK, and US defense research establishments.
Market Restraints
- Gallium nitride substrate supply concentration:AESA radar production depends on Chinese-processed rare earth refining capacity, creating single-source vulnerability for low-probability-of-intercept arrays.
- DRDO certification timelines:India's indigenous subsystem validation protocols extend qualification cycles to 48-60 months, freezing foreign OEMs from fast-track integration.
- THAAD-PAC-3 interoperability lock-in:Japan's ATLA standards enforce US joint force architecture compliance, excluding European and Korean alternatives from layered defense contracts.
Strategic Opportunities
- Vietnam's S-300 modernization gap:Russian supply chain disruptions create replacement demand for non-sanctioned long-range SAM platforms with compatible radar interfaces.
- Over-the-horizon radar backscatter networks:Australia's Jindalee Operational Radar Network expansion offers anchor demand for ionospheric propagation technology transfer partnerships.
- Indonesia's Outer Islands air defense:Archipelago geography favors distributed short-range systems over centralized long-range batteries, opening point-defense specialization.
Industry Challenges
- Embedded software vulnerability certification:Cyber-physical kill-chain validation requires MIL-STD-882E compliance that few subsystem vendors can demonstrate at scale.
- Legacy analog radar integration:Soviet-era Vietnamese and Myanmar installations lack digital interface standards, forcing costly gateway development for network-centric upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Air Defense Systems Market |
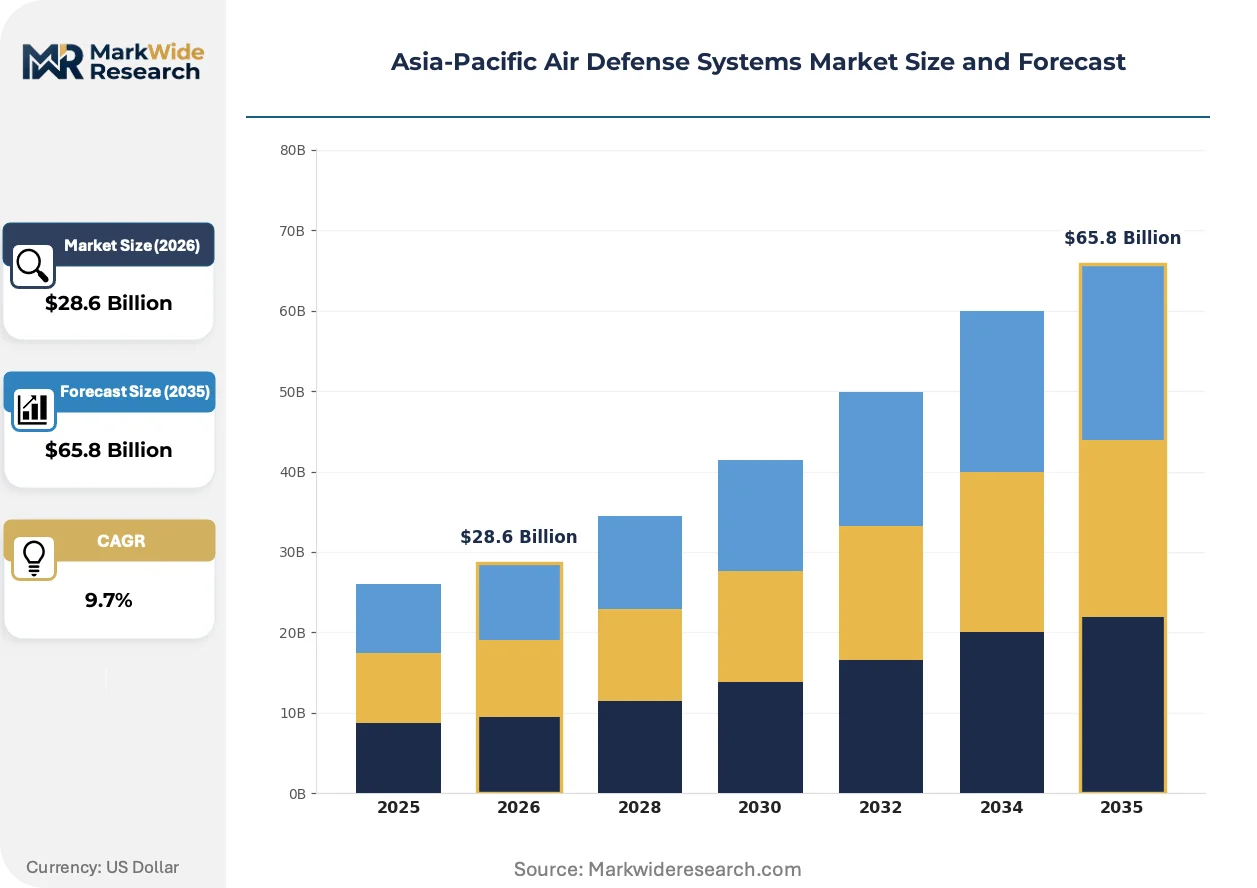
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Missile Systems, Radar Systems, Command & Control Systems, Portable Air Defense Systems Technology: Laser Systems, Electro-Optical Systems, Missile Launch Systems, Network-Centric Warfare End User: Government, Military, Defense Contractors, Homeland Security Application: Military Operations, National Security, Air Traffic Management, Emergency Response |
| Companies Covered | Lockheed Martin Corporation, IAI, Almaz-Antey Corp, Northrop Grumman Corporation, MBDA, RTX Corporation, Hanwha Systems, Defense Research and Development Organization, Leonardo S.p.A, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Air Defense Systems Market Strategic Shifts
Active electronically scanned arrays with gallium nitride transmit-receive modules are displacing conventional mechanically steered radars across detection and fire-control applications, compressing procurement cycles for legacy platform retrofits.
Distributed aperture sensing is decentralizing air defense architecture from centralized command nodes to edge-mounted passive infrared and RF sensors on mobile launchers. South Korea's kill-chain doctrine now mandates vehicle-integrated cueing that eliminates fixed radar dependency. This topology reduces signature exposure while complicating adversary targeting geometry.
Japan's Acquisition, Technology and Logistics Agency revised interoperability standards in 2024 to mandate open systems architecture for all new missile defense acquisitions. Foreign OEMs must now publish interface control documents to Japanese defense primes. European suppliers lacking US joint force certification are restructuring Australian and Japanese bids through Raytheon and Lockheed Martin partnership layers.
Defense ministries across Southeast Asia are unbundling long-term sustainment from initial platform procurement, creating separate competitive pools for 25-year service contracts. Malaysia and Thailand now run dual-track tenders where system integrators bid separately from in-country maintenance consortia. This bifurcation favors Korean and Turkish vendors with established regional logistics footprints over US primes dependent on foreign military financing structures.
Asia-Pacific Air Defense Systems Market Segmentation
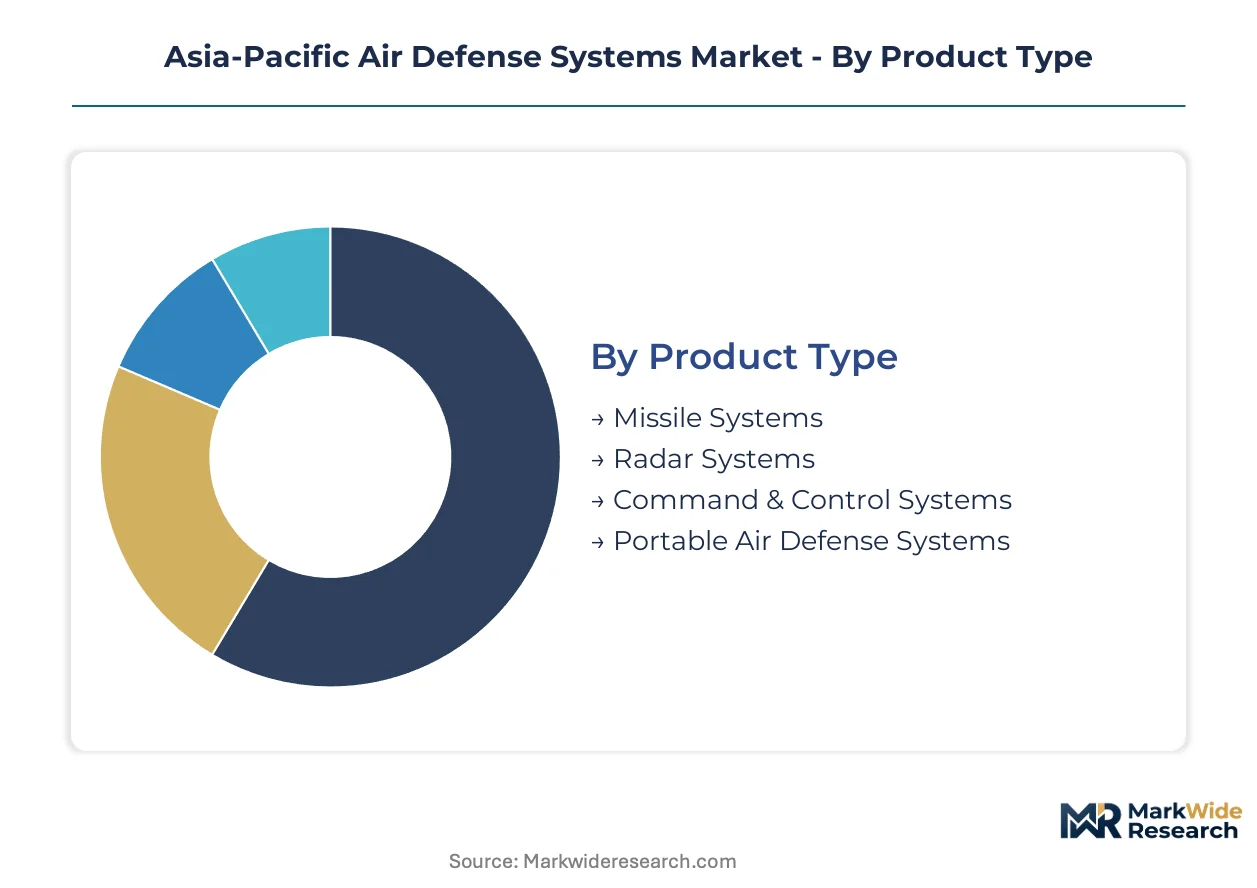
Air defense procurement in the Asia-Pacific bifurcates sharply between kinetic interceptors and enabling infrastructure, with certification requirements from Japan's Acquisition, Technology and Logistics Agency and India's DRDO creating divergent qualification pathways for foreign and indigenous suppliers.
Product Type:
DRDO certification mandates 60% indigenous value addition for missile subsystems entering Indian service, while Japan's ATLA interoperability standards enforce US joint force architecture compliance for layered defense contracts.
- Missile Systems:Kinetic interceptors ranging from short-range MANPADS to exo-atmospheric THAAD-class vehicles. India's layered missile defense program and Australia's northern radar modernization anchor regional procurement volumes, though gallium nitride seeker production bottlenecks constrain AESA-guided variants.
- Radar Systems:Active electronically scanned arrays with gallium nitride transmit-receive modules displacing mechanically steered architectures. Australia's Jindalee Operational Radar Network expansion and South Korea's distributed kill-chain doctrine drive demand for low-probability-of-intercept arrays and over-the-horizon backscatter installations.
- Command & Control Systems:Network-centric warfare integration compressing sensor-to-shooter latency below 10 seconds.
- Portable Air Defense Systems:Vehicle-mounted and dismounted short-range interceptors for archipelago and border defense.
Missile systems sit at the top of the volume ranking, with radar systems climbing the fastest.
Technology:
Cost tiers separate developmental directed-energy platforms from fielded kinetic solutions, with quantum sensing and AI-enabled target recognition protocols commanding premium pricing under AUKUS Pillar Two harmonization.
- Laser Systems:Directed-energy weapons for close-in defense against drone swarms and precision munitions. Japan and Australia accelerate development programs in response to China's DF-17 hypersonic deployments across the Taiwan Strait, though power density and atmospheric attenuation limit operational envelopes.
- Electro-Optical Systems:Passive infrared and visible-spectrum trackers for cueing and terminal guidance. South Korea's vehicle-integrated kill-chain doctrine eliminates fixed radar dependency, decentralizing detection to edge-mounted sensors on mobile launchers.
- Missile Launch Systems:Vertical and slant launchers with rapid reload architectures.
- Network-Centric Warfare:Open systems architecture mandating published interface control documents for Japanese defense primes.
Missile launch systems dominate current procurement value, with laser systems gaining share fastest on developmental funding infusions.
End User:
Military end users concentrate procurement authority through centralized defense ministries, while homeland security agencies operate under constrained budgets favoring point-defense specialization over integrated architectures.
- Government:National-level acquisition authorities setting interoperability standards and indigenization mandates. India's PLI scheme for defense manufacturing and Australia's Defence Trade Controls Act reshape supplier qualification pathways and technology transfer permissions.
- Military:Operational commands defining engagement range, reaction time, and multi-domain integration specifications. Southeast Asian militaries unbundle long-term sustainment from initial platform procurement, creating separate competitive pools for 25-year service contracts.
- Defense Contractors:System integrators and subsystem vendors bidding separately from in-country maintenance consortia.
- Homeland Security:Civil air defense and critical infrastructure protection with reduced latency requirements.
Military end users command the largest addressable budget pool, with defense contractors expanding most quickly on sustainment bifurcation trends.
Application:
Application maturity separates fielded military operations from emerging emergency response protocols, with air traffic management representing a crossover segment requiring dual-use certification.
- Military Operations:Force protection and area denial against manned aircraft, cruise missiles, and hypersonic glide vehicles. Vietnam's S-300 modernization gap and Indonesia's Outer Islands geography create replacement demand for distributed short-range systems over centralized long-range batteries.
- National Security:Sovereignty protection across contested airspaces with engagement ranges from 5 km to 400 km. Russian supply chain disruptions force Vietnamese and Myanmar installations toward non-sanctioned platforms with compatible radar interfaces.
- Air Traffic Management:Civil-military coordination for restricted airspace enforcement.
- Emergency Response:Rapid deployment for disaster-related airspace control and temporary corridor establishment.
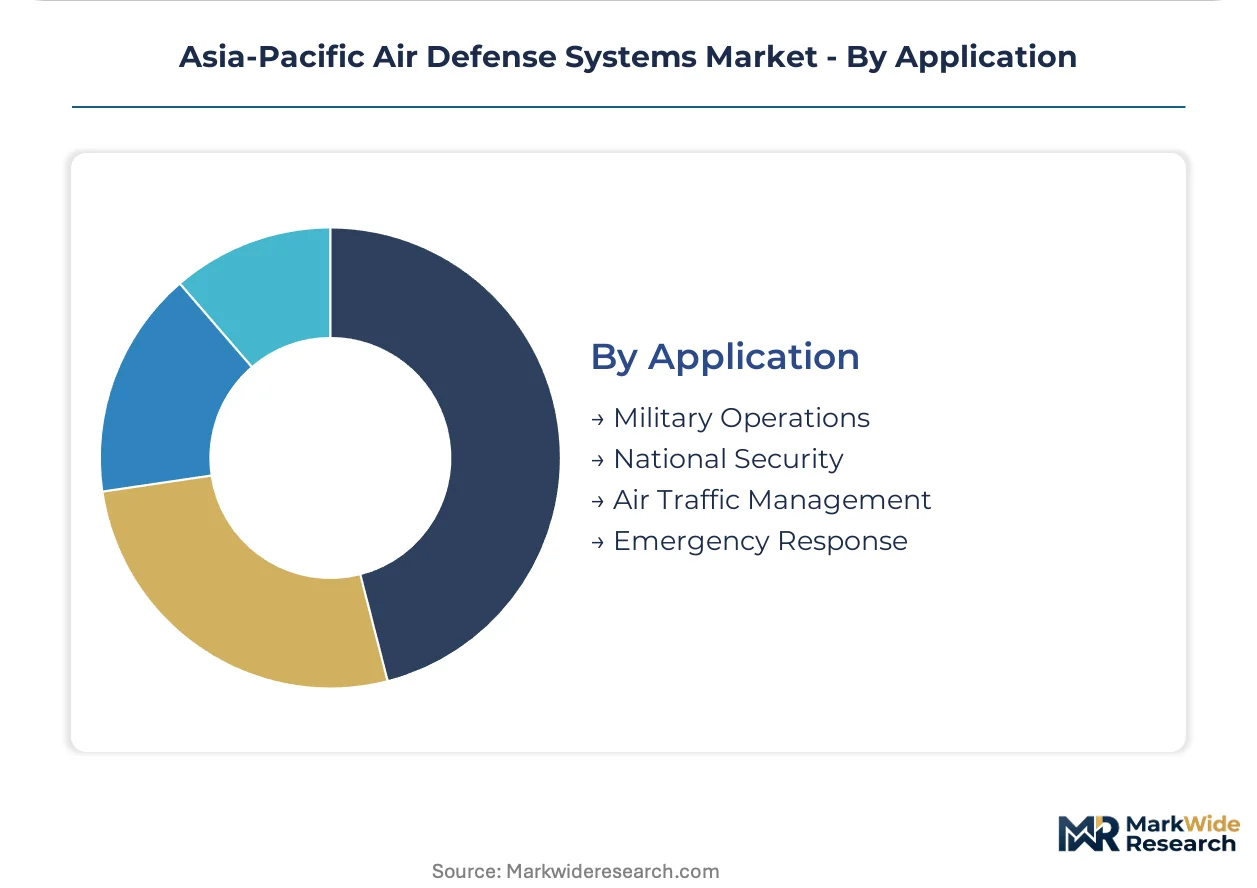
Military operations absorb the dominant share of procurement expenditure, with national security applications showing the steepest expansion trajectory on threat perception intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's layered missile defense program absorbs procurement volumes that dwarf Australia's northern radar modernization, yet both nations enforce incompatible supplier qualification pathways that fragment vendor strategies across the region.
India
The Defence Research and Development Organization drives indigenous radar and seeker production through 60% domestic content mandates for missile subsystems. India's PLI scheme for defense manufacturing accelerates local fabrication capacity, with Bangalore and Hyderabad anchoring gallium nitride AESA array development for low-probability-of-intercept applications.
Japan
China's DF-17 hypersonic deployments across the Taiwan Strait compel accelerated directed-energy interceptor programs. The Acquisition, Technology and Logistics Agency enforces open systems architecture standards mandating published interface control documents, with Tokyo and Nagoya clusters hosting US joint force-certified integration facilities for PAC-3 and THAAD-class systems.
Australia
AUKUS Pillar Two technology sharing harmonizes quantum sensing protocols between Australian, UK, and US defense research establishments. The Defence Trade Controls Act restricts technology transfer pathways, compelling foreign OEMs to establish sovereign maintenance capabilities concentrated in South Australia's defense precincts.
South Korea
Hanwha Systems anchors indigenous radar and command architecture tailored to the kill-chain doctrine eliminating fixed radar dependency. Seoul and Busan-Ulsan corridors host vehicle-integrated cueing development for distributed aperture sensing on mobile launchers, reducing signature exposure against adversary targeting geometry.
Vietnam
Russian supply chain disruptions create replacement demand for non-sanctioned long-range SAM platforms compatible with legacy S-300 radar interfaces. Hanoi directs procurement toward cost-competitive alternatives as Soviet-era installations lack digital interface standards for network-centric warfare integration.
Asia-Pacific Air Defense Systems Market Competitive Environment
Top-tier vendors anchor integrated multi-domain system contracts, while commodity point-defense specialists compete on distributed short-range bids. The vendor base stratifies across US joint force-certified primes, indigenous Asian system integrators, and Russian legacy suppliers facing sanction-constrained supply chains. Strategic archetypes include architecture licensors enforcing interoperability lock-in, indigenization champions leveraging domestic content mandates, and sustainment bundlers capturing 25-year service contracts. Competitive moves concentrate on sovereign maintenance capability establishment and open systems architecture certification restructuring.
Among US-based defense primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the architecture-licensor archetype through PAC-3 and THAAD integration expertise. Hanwha Systems occupies a position within the indigenous-integrator tier, representing Korean vendor strategies tailored to regional kill-chain doctrines. Almaz-Antey Corp anchors the legacy-supplier segment, exemplifying cost-competitive long-range SAM provision to Southeast Asian markets despite supply chain disruption headwinds.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| IAI |
| Almaz-Antey Corp |
| Northrop Grumman Corporation |
| MBDA |
| RTX Corporation |
| Hanwha Systems |
| Defense Research and Development Organization |
| Leonardo S.p.A |
| Others |
Value Chain & Pricing Dynamics
India's PLI scheme for defense manufacturing gates both qualified supply and premium-tier pricing access, mandating 60% indigenous value addition for missile subsystems and compressing margins for foreign OEMs unable to meet DRDO certification timelines while elevating pricing power for domestic gallium nitride AESA producers in Bangalore and Hyderabad.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for vehicle-integrated radar systems as Hanwha Systems scales indigenous production. Three-tier pricing structure across premium integrated multi-domain architectures, standard network-compliant systems, and economy point-defense solutions separates Lockheed Martin's PAC-3 contracts from Almaz-Antey's S-400 derivatives. Cost compression in commodity short-range interceptors is intensifying because Southeast Asian militaries unbundle sustainment from procurement. Homeland security agencies show highest price sensitivity; Japan's ATLA-certified primes command lowest sensitivity due to interoperability lock-in.
Supply Chain Analysis
Refurbishment flows for legacy Soviet-era Vietnamese and Myanmar radar installations create reverse-logistics demand for digital gateway development. Gallium nitride substrate supply concentrates in China, South Korea, and Japan, with Chinese-processed rare earth refining capacity anchoring AESA production. Raw material dependencies span gallium nitride wafers, high-purity aluminum for seeker housings, and specialized ceramics for radomes. Single-source vulnerability in Chinese rare earth processing threatens low-probability-of-intercept array availability. Distribution runs through sovereign maintenance consortia established under Australia's Defence Trade Controls Act and India's DRDO certification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific air defense systems market functions as a stable compounder, with hypersonic threat proliferation from China's DF-17 deployments driving sustained procurement across Japan, Australia, and South Korea regardless of budget cycle volatility.
For Market Incumbents: Extend interoperability certification depth to capture AUKUS Pillar Two technology sharing flows, particularly quantum sensing and AI-enabled target recognition protocols. Lockheed Martin and Northrop Grumman should deepen backward integration into gallium nitride seeker production to offset Chinese substrate supply concentration. DRDO certification timeline compression represents the critical margin defense lever against Korean indigenous challengers.
For New Entrants and Emerging Players: Capture Vietnam's S-300 modernization gap created by Russian supply chain disruptions, positioning cost-competitive long-range SAM platforms with compatible radar interfaces as the most penetrable white-space target. Indonesia's Outer Islands geography favors distributed short-range systems over centralized batteries, opening point-defense specialization for archipelago deployment expertise. Partner with established regional logistics footprints to bypass sustainment bifurcation barriers.
For Investors and Strategic Acquirers: Roll-up economics work for sovereign maintenance capability providers because Australia's Defence Trade Controls Act and India's PLI scheme fragment vendor pools and elevate in-country service premiums. Mid-cap specialists with DRDO or ATLA certification and established South Australian or Indian defense precinct presence offer 5-10 year visibility. Monitor AUKUS Pillar Two harmonization progress as the inflection signal for quantum sensing and directed-energy platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Systems Architecture Certification | Japan's ATLA mandates published interface control documents for PAC-3 and THAAD integration contracts. |
| Sovereign Maintenance Capability Establishment | Australia's Defence Trade Controls Act compels foreign OEMs to localize service operations in South Australian precincts. |
| Gallium Nitride Seeker Production Scale-Up | India's PLI scheme accelerates Bangalore and Hyderabad capacity for DRDO-certified AESA radar subsystems. |
| Directed-Energy Interceptor Development | Japan and Australia accelerate programs responding to China's DF-17 hypersonic deployments across the Taiwan Strait. |
| Network-Centric Warfare Integration | South Korea's kill-chain doctrine mandates sensor-to-shooter latency below 10 seconds for mobile launcher cueing. |
Study Parameters
Bottom-up military end-use modeling reconciled against top-down radar and missile system production tracking forms the analytical core. Primary interviews with defense ministry procurement officers, system integrator program managers, DRDO certification leads, and AESA subsystem engineers combined with secondary validation from customs filings, defense budget appropriations documents, and AUKUS Pillar Two technology sharing disclosures. Triangulation across these sources anchors volume estimates for India's layered missile defense program and Australia's Jindalee Operational Radar Network expansion.
Historical procurement trendlines for PAC-3, THAAD, and S-400-class systems establish baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user authority level, and application maturity. CAGRs derive from deployment schedule acceleration factors tied to hypersonic threat perception intensification and indigenization mandate enforcement. Forecast inputs incorporate gallium nitride substrate supply constraints and DRDO certification timeline variability.
Underlying measurement precision varies by segment; missile systems carry tighter precision than emerging directed-energy platforms due to established procurement reporting. Forecasts reflect assumptions regarding AUKUS technology sharing implementation pace and Chinese rare earth export policy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
Airborne Fire Control Radar Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Global Missile Interceptor Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
Americas Air Defense Systems Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Air and Missile Defense Radar System Market