
 Americas Air Defense Systems Market | 2026-2036
Americas Air Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Air Defense Systems Market Outlook
The capability gap between legacy radar integrators and software-defined sensor developers is unwinding competitive hierarchies across the Americas. Lockheed Martin leverages its long-range discrimination radar footprint to anchor prime contractor positions on major US Army programs. RTX Corporation sustains dense production of effector systems while competing aggressively in directed-energy prototyping. Northrop Grumman differentiates through space-based infrared sensor layers that extend missile warning coverage across continental defense architectures.
Americas air defense systems encompass integrated weapon platforms, sensor networks, and battle management software engineered to detect, track, intercept, and destroy aerial threats ranging from ballistic missiles to unmanned aircraft; these systems typically operate at engagement altitudes from surface level to exo-atmospheric regimes and rely on phased-array radar architectures with refresh rates measured in milliseconds. Missile Systems command the largest value share as effector inventories require continuous replenishment against evolving threat profiles. Radar Systems represent the fastest structural expansion as gallium nitride transmitter technology displaces legacy gallium arsenide arrays. Command & Control Systems concentrate margin pools where software-defined networking enables rapid retasking of distributed assets.
The US Department of Defense, FAA, and Canada's Department of National Defence shape procurement through interoperability mandates, spectrum allocation rules, and NORAD modernization commitments that force cross-border standardization. Brazil's national telecommunications regulator and ANVISA impose localized certification requirements on imported electronic warfare subsystems. Stakeholders must monitor how Joint All-Domain Command and Control technical standards redistribute subcontractor access across the hemisphere's industrial base.
Market Dynamics
The Joint All-Domain Command and Control directive is compressing procurement cycles across the Americas as military buyers demand interoperable sensor-to-shooter architectures that collapse legacy stovepiped acquisition timelines.
Growth Catalysts
- NORAD Modernization Commitments:Canada and the United States are accelerating layered radar deployments along Arctic approaches under continental defense treaties.
- Gallium Nitride Transmitter Migration:Phased-array radar refresh programs are displacing legacy gallium arsenide substrates with higher-power-density semiconductor architectures.
- Southwestern US Test Range Clustering:Concentrated border surveillance requirements and missile defense proving grounds are anchoring procurement gravity in Arizona, New Mexico, and Texas.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium sourcing dependency on single-source foreign processors creates vulnerability in precision guidance motor production.
- Spectrum Allocation Friction:FCC and FAA coordination delays on S-band and C-band assignments are freezing radar deployment schedules at operational test sites.
- Directed-Energy Technical Ceiling:Atmospheric thermal blooming and beam coherence degradation limit effective engagement ranges for laser-based interceptors below operational thresholds.
Strategic Opportunities
- Brazilian Electronic Warfare Localization:ANVISA certification requirements create captive market access for domestically integrated counter-UAS subsystems.
- Space-Based Infrared Layer Convergence:Overhead persistent infrared sensor constellations are merging with terrestrial radar tracks to enable birth-to-death missile tracking.
- Software-Defined Networking Mandates:US Army Integrated Air and Missile Defense program requirements are opening subcontractor access for non-traditional battle management software vendors.
Industry Challenges
- GaN Fabrication Talent Scarcity:Compound semiconductor process engineering expertise concentrates at a handful of foundries, constraining radar transmitter yield ramps.
- Legacy System Integration Friction:PATRIOT and THAAD battle management architectures resist rapid retasking protocols required by distributed kill-chain concepts.
- Cross-Border Certification Timeline Compression:Canada's Department of National Defence and US DoD interoperability testing protocols impose multi-year validation gates on integrated fire control software releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Air Defense Systems Market |
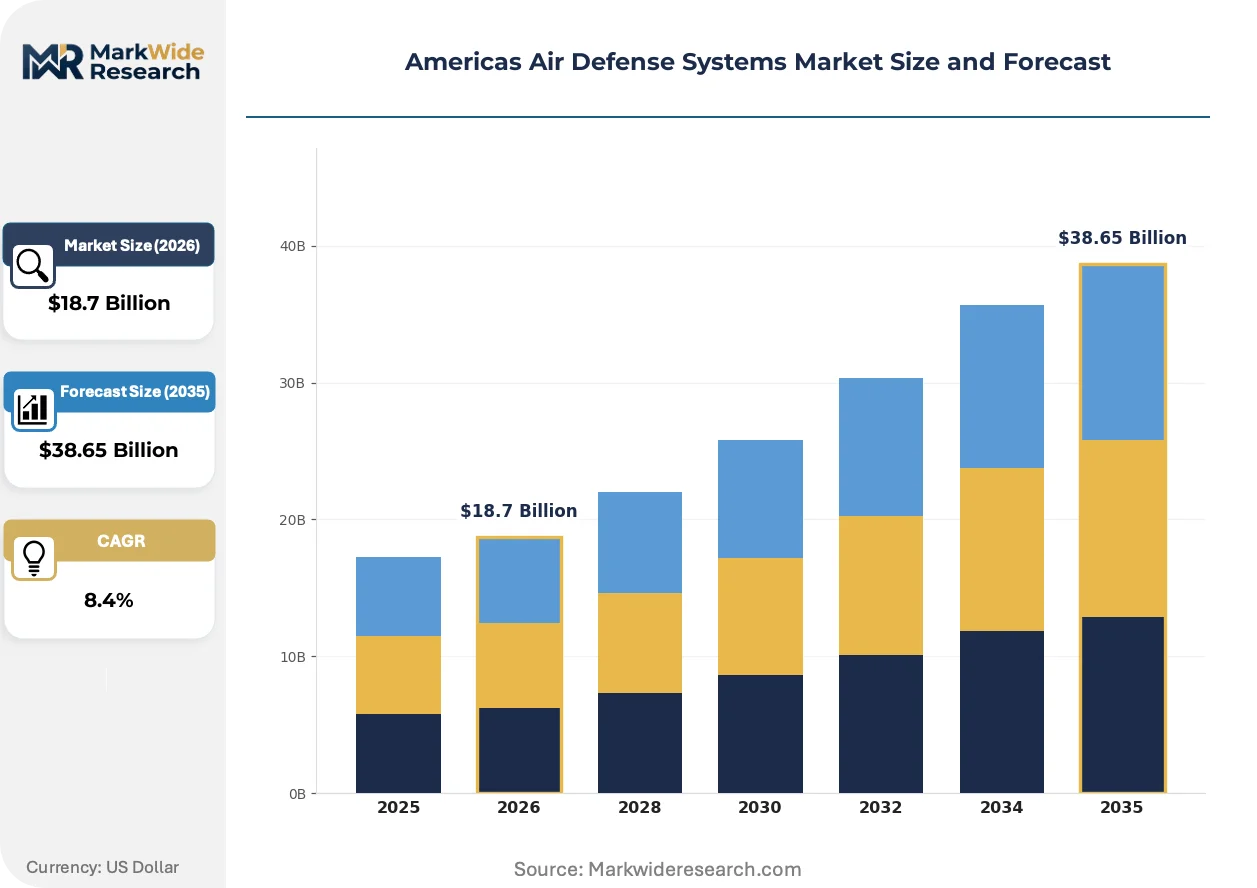
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Missile Systems, Radar Systems, Command & Control Systems, Electronic Warfare Systems End User: Military Organizations, Government Agencies, Private Security Firms, Defense Contractors Technology: Ground-Based Systems, Aerial Systems, Naval Systems, Space-Based Systems Deployment: On-Premises, Cloud-Based, Hybrid, Remote |
| Companies Covered | RTX Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, The Boeing Company, Israel Aerospace Industries Ltd, BAE Systems, General Dynamics Corporation, L3Harris Technologies, Raytheon Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Air Defense Systems Market Strategic Shifts
Active electronically scanned array architectures are fragmenting into modular, software-reconfigurable form factors that decouple hardware refresh cycles from threat adaptation timelines.
Gallium nitride monolithic microwave integrated circuits are bifurcating radar transmitter supply chains into high-reliability military-grade foundries and commercial-scale GaN-on-SiC producers. The US Missile Defense Agency is dual-sourcing from both tiers to de-risk production concentration. This technology split is compressing cost curves for mid-range air defense radars while preserving performance margins for long-range discrimination systems.
FAA spectrum reallocation proceedings on the 3.1-3.45 GHz band are forcing radar manufacturers to retune terminal high-altitude area defense seekers and fire control illuminators. The industrial consequence is a wave of engineering change orders across active production lines. Southwestern US test ranges are responding by petitioning for protected military operating areas that exempt developmental systems from commercial 5G interference constraints.
Consolidated prime contracting is concentrating subsystem vendor access as the US Army reduces qualified supplier lists for Lower Tier Air and Missile Defense Sensor programs. Mid-tier radar integrators are responding by forming exclusive teaming arrangements with platform primes rather than competing as standalone bidders. This channel restructuring is most visible in Huntsville, Alabama, where Army Aviation and Missile Command procurement officers are enforcing single-prime accountability for integrated fire unit deliveries.
Americas Air Defense Systems Market Segmentation
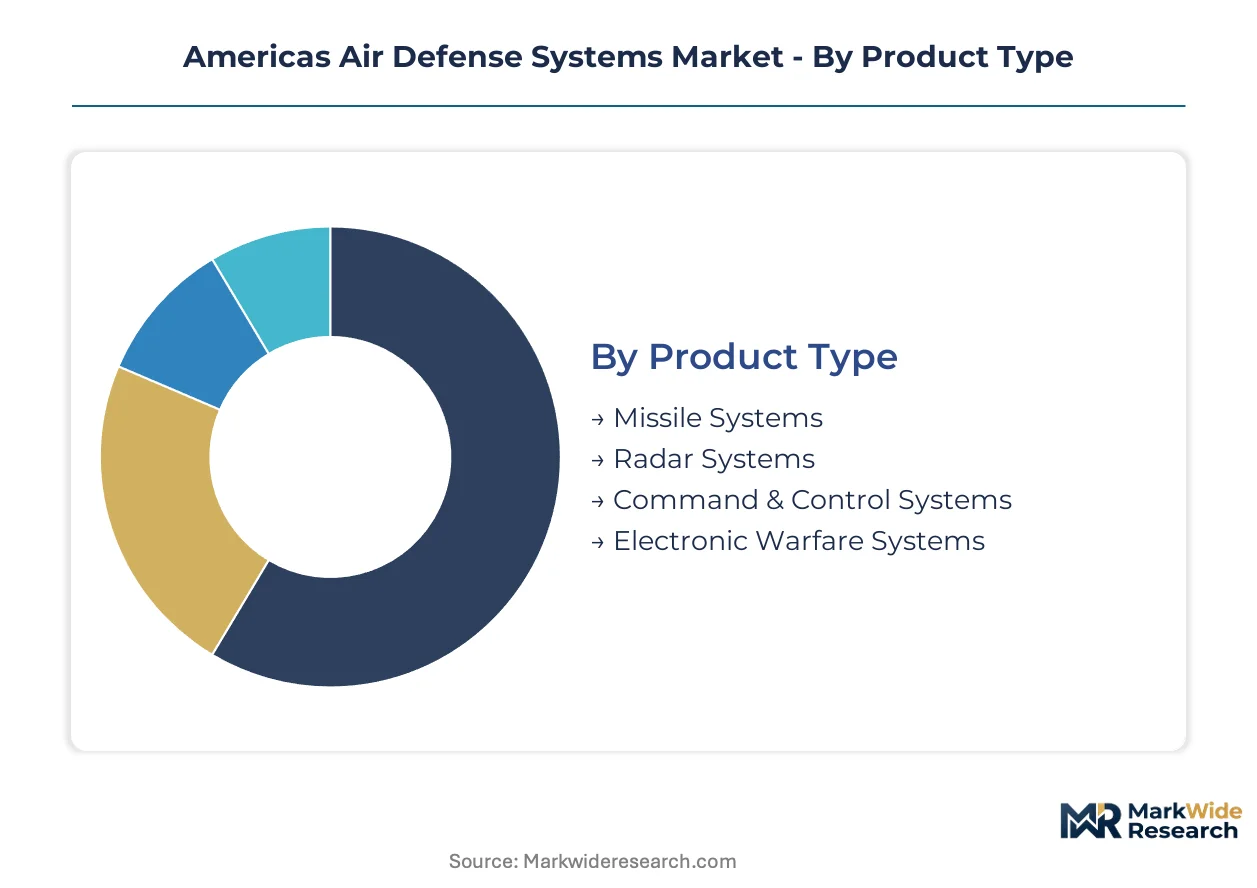
Americas air defense procurement splits across four orthogonal dimensions that reshape vendor access and margin capture. Product type determines hardware versus software revenue mix. End user classification governs certification rigor and contract vehicle selection. Technology and deployment modalities dictate supply chain geography and interoperability testing burden.
Product Type:
FCC spectrum rulings and US Army technical standards create divergent compliance pathways across hardware categories.
- Missile Systems:Kinetic effector platforms encompassing interceptors, surface-to-air missiles, and precision-guided munitions with solid-fuel propulsion architectures. Demand clusters at White Sands Missile Range and Eglin Air Force Base test complexes where the Missile Defense Agency validates new seeker algorithms against evolving threat replicas.
- Radar Systems:Phased-array and active electronically scanned array sensors operating across S-band, C-band, and X-band frequencies with gallium nitride transmitter backends. Procurement concentrates in the southwestern United States where FAA coordination on 5G interference mitigation has slowed deployment timelines but amplified demand for frequency-agile architectures.
- Command & Control Systems:Battle management software integrating sensor tracks into fire control solutions under Joint All-Domain Command and Control protocols.
- Electronic Warfare Systems:Counter-UAS and directed-energy platforms for non-kinetic threat neutralization.
Missile Systems handles the majority of throughput; Radar Systems is the fastest mover on share.
End User:
Contracting authority determines security clearance thresholds and domestic content requirements.
- Military Organizations:Department of Defense branches and National Guard units operating under Federal Acquisition Regulation defense supplements. Procurement flows through Army Contracting Command and Naval Air Systems Command with mandatory DFARS 252.225-7001 domestic sourcing clauses.
- Government Agencies:FAA, Department of Homeland Security, and Canada Border Services Agency installations requiring civil-military interoperability certifications. Demand centers on southern border surveillance corridors where Customs and Border Protection operates integrated radar networks.
- Private Security Firms:Critical infrastructure protection contractors operating under state-level licensing regimes.
- Defense Contractors:Prime and subcontractor internal test ranges and integration facilities.
Military Organizations dominates absolute spend; Government Agencies is expanding most quickly on new entrant access.
Technology:
Platform altitude determines sensor coverage geometry and satellite dependency.
- Ground-Based Systems:Fixed and mobile launchers, radar emplacements, and distributed fire units with terrestrial power and communications. Deployment concentrates at Fort Bliss and Fort Sill where the Army tests integrated air and missile defense battalion configurations against live-fire scenarios.
- Aerial Systems:Airborne early warning and fighter-integrated sensor platforms.
- Naval Systems:Shipboard Aegis and layered defense architectures for carrier strike group protection.
- Space-Based Systems:Overhead persistent infrared satellites and space domain awareness sensors. Canada's Department of National Defence co-funds NORAD modernization of polar-orbiting warning constellations under renewed continental defense commitments.
Ground-Based Systems carries the largest installed base; Space-Based Systems shows the steepest expansion trajectory.
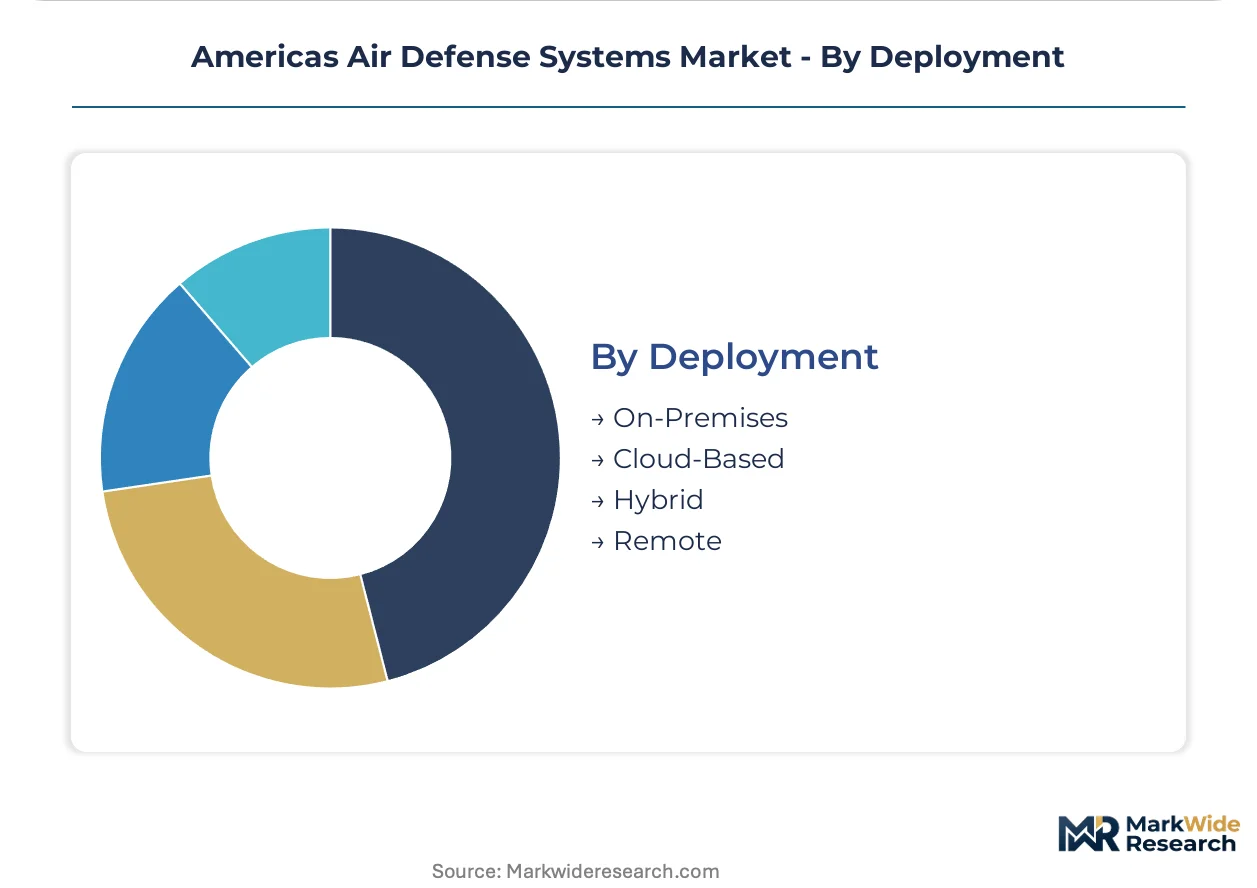
Deployment:
Data sovereignty rules and latency requirements fragment cloud adoption across operational echelons.
- On-Premises:Classified networks with air-gapped battle management nodes operating at secret and top-secret collateral levels. The Pentagon's Cloud Executive Steering Group mandates on-premises retention for nuclear command and control pathways.
- Cloud-Based:Unclassified logistics and training environments leveraging DISA milCloud or commercial equivalents with FedRAMP authorization.
- Hybrid:Split architectures with classified edge processing and unclassified cloud analytics.
- Remote:Forward-deployed and expeditionary configurations with satellite backhaul.
On-Premises retains the dominant share; Hybrid deployments are climbing the fastest as classification boundaries shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense buyers in Canada and Brazil exhibit acute price sensitivity to imported electronic warfare subsystems, whereas United States military procurement prioritizes performance thresholds over unit cost. This demand-elasticity contrast concentrates high-value radar and missile contracts in the southwestern United States while pushing mid-tier integrators toward localization mandates in Latin America.
United States
The US Department of Defense drives layered air defense procurement through Joint All-Domain Command and Control directives that mandate interoperable sensor-to-shooter architectures. FCC and FAA coordination on S-band and C-band spectrum allocation directly shapes radar deployment schedules across operational test sites. Arizona, New Mexico, and Texas anchor procurement gravity where White Sands Missile Range and border surveillance corridors cluster testing and acquisition activity.
Canada
Canada's Department of National Defence co-funds NORAD modernization commitments that accelerate Arctic radar deployments under continental defense treaties. Domestic content requirements and interoperability testing protocols with US DoD impose multi-year validation gates on integrated fire control software releases. Industrial activity concentrates in Ontario and Quebec where defense contractors align with federal procurement officers on cross-border standardization mandates.
Brazil
Brazilian military demand concentrates on counter-UAS and electronic warfare platforms subject to ANVISA certification requirements for imported subsystems. ANVISA and the national telecommunications regulator impose localized certification pathways that create captive market access for domestically integrated systems. São Paulo and Rio de Janeiro host integration facilities where mid-tier radar vendors form exclusive arrangements with platform primes to satisfy federal procurement rules.
Mexico
Mexican government agencies prioritize civil-military interoperability for southern border surveillance networks operated under national security frameworks. The Secretariat of National Defense shapes procurement through spectrum allocation coordination with federal telecommunications authorities. Northern border states concentrate deployment activity where Customs and Border Protection interoperability requirements intersect with domestic infrastructure protection mandates.
Americas Air Defense Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Americas air defense systems market, with long-range discrimination radar developers occupying distinct competitive positions from high-volume effector manufacturers. The vendor base stratifies into three tiers: consolidated primes with integrated fire unit accountability, mid-tier radar integrators dependent on exclusive teaming arrangements, and specialized directed-energy prototyping firms. Dominant competitive moves include exclusive prime-subcontractor channel restructuring around Army Contracting Command procurement and gallium nitride fabrication capacity expansion to de-risk transmitter supply concentration.
Among United States-based defense primes, Lockheed Martin Corporation, RTX Corporation, and Northrop Grumman Corporation exemplify the consolidated tier that anchors major program positions. Lockheed Martin represents the long-range radar integration archetype, RTX Corporation occupies the high-volume effector manufacturing position, and Northrop Grumman sits within the space-based sensor layer specialization. These three entities collectively illustrate how prime contracting concentration is reducing qualified supplier lists while redistributing subcontractor access across the hemisphere's industrial base.
| Leading Market Players |
|---|
| RTX Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| Israel Aerospace Industries Ltd |
| BAE Systems |
| General Dynamics Corporation |
| L3Harris Technologies |
| Raytheon Technologies |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-one-hundred-twenty-day lead times for gallium nitride monolithic microwave integrated circuits concentrate pricing power with military-grade foundries in the United States and Japan, while commercial-scale GaN-on-SiC producers compete on cost curves for mid-range radar systems. This inventory compression amplifies margin capture for qualified suppliers serving Joint All-Domain Command and Control programs.
Pricing Analysis
After-sales service contracts and extended logistics support agreements drive lifetime value capture across air defense platforms. Three-tier pricing structure across premium, standard, and economy levels separates long-range discrimination radar systems from mid-range mobile emplacements and export-configured counter-UAS units. Cost compression in effector manufacturing is intensifying because RTX Corporation and Lockheed Martin consolidate supplier lists under single-prime accountability. Military Organizations exhibit lowest price sensitivity where performance thresholds dominate, while Brazilian and Mexican government agencies face acute budget constraints on imported electronic warfare subsystems.
Supply Chain Analysis
Port congestion on transpacific lanes and container availability constraints at Long Beach and Los Angeles complicate inbound logistics for rare earth magnet processors supplying precision guidance motor production. Neodymium and dysprosium sourcing draws from China and Myanmar, with secondary refining capacity concentrated in the United States and Australia. Single-source vulnerability in gallium nitride epitaxy wafer supply creates qualification bottlenecks for radar transmitter programs. Distribution runs through prime contractor integration facilities in Huntsville, Alabama and Tucson, Arizona, with final assembly accountability enforced by Army Contracting Command procurement officers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated prime contractors as the US Army reduces qualified supplier lists for Lower Tier Air and Missile Defense Sensor programs, fragmenting access for standalone mid-tier radar integrators.
For Market Incumbents: Consolidate gallium nitride fabrication capacity through exclusive foundry partnerships or captive wafer supply agreements to de-risk transmitter yield ramps. Deepen backward integration into compound semiconductor process engineering talent pools concentrated at select universities and national laboratories. Lockheed Martin and RTX Corporation channel restructuring around Army Aviation and Missile Command procurement demonstrates how prime-subcontractor exclusivity defends program positions against software-defined sensor entrants. For New Entrants and Emerging Players: Anchor in Brazilian electronic warfare localization requirements where ANVISA certification creates captive market access for domestically integrated counter-UAS subsystems. Target software-defined battle management modules under US Army Integrated Air and Missile Defense program openings, where non-traditional vendors gain subcontractor access through rapid retasking protocol compliance. Pursue exclusive teaming arrangements with platform primes rather than competing as standalone bidders to bypass consolidated contracting barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across space-based infrared sensor layer convergence plays, as overhead persistent infrared constellation deployment requires sustained multi-year funding commitments. Acquisition target archetype: mid-tier radar integrators with gallium nitride transmitter backend expertise and established Army Contracting Command relationships. Watch for Joint All-Domain Command and Control technical standard releases as inflection indicators redistributing subcontractor access across the hemisphere's industrial base.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Fabrication Capacity Expansion | De-risks transmitter supply concentration for phased-array radar refresh programs at military-grade foundries. |
| Exclusive Prime-Subcontractor Teaming | Secures channel access as Army Contracting Command enforces single-prime accountability for fire unit deliveries. |
| Software-Defined Networking Certification | Opens subcontractor access for non-traditional battle management vendors under JADC2 protocol mandates. |
| Space-Based Infrared Layer Convergence | Merges overhead persistent infrared tracks with terrestrial radar for birth-to-death missile tracking coverage. |
| Brazilian Electronic Warfare Localization | Captures ANVISA-certified market access through domestic integration of counter-UAS subsystems. |
Study Parameters
The analysis maps missile systems, radar systems, command and control systems, and electronic warfare platforms, each validated through program managers at Army Contracting Command and Naval Air Systems Command, procurement officers at the Missile Defense Agency, and engineering leads at gallium nitride foundries. Primary interviews with defense prime contractor business development executives, mid-tier radar integrator general managers, and FAA spectrum coordination officials combined with secondary validation against DoD budget justification documents, FCC docket filings on 3.1-3.45 GHz reallocation, and NORAD modernization commitment disclosures. Bottom-up build-ups of program-level procurement data triangulated against top-down defense expenditure forecasts across the analysis window.
Consistency checks against Missile Defense Agency test range activity reports and Army Aviation and Missile Command contract award databases validated volume and value outputs. Segmentation modeling incorporated product type, end user classification, technology modality, and deployment architecture dimensions, with CAGRs derived from program-of-record funding profiles and projected effector replenishment rates. Forecast inputs included gallium nitride transmitter migration timelines, Joint All-Domain Command and Control technical standard adoption curves, and NORAD Arctic radar deployment schedules.
Underlying assumptions cover sustained DoD procurement priority for integrated air and missile defense, stable FCC-FAA spectrum coordination timelines, and continued gallium nitride foundry yield improvement trajectories, with deviation risk concentrated in rare earth magnet supply disruptions or directed-energy technical ceiling breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
Global Missile Interceptor Market
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Airborne Fire Control Radar Market