
 Air and Missile Defense Radar System Market | 2026-2036
Air and Missile Defense Radar System Market Size, Share, and Industry Trends Forecast 2026-2036
Air and Missile Defense Radar System Market Outlook
The US Department of Defense's shift toward distributed sensor architectures is rewriting the cost-of-entry calculus for new radar suppliers. Lockheed Martin Corporation leverages its vertically integrated gallium nitride foundry capacity to sustain margin control across the production chain. Raytheon Technologies Corporation anchors the Patriot ecosystem through captive sustainment revenues and upgrade cycles. Northrop Grumman Corporation differentiates via space-based radar integration with terrestrial fire-control networks.
Air and missile defense radar systems are active electromagnetic sensor platforms operating across S-band through X-band frequencies, employing electronically scanned arrays to detect, track, and classify aerial threats at ranges exceeding 400 nautical miles for integrated air and missile defense architectures. Ground-based radar dominates procurement volumes as nations replace Cold War-era fixed-site installations with transportable multi-mission units, while phased array radar captures the fastest expansion trajectory driven by gallium nitride transmitter-receiver module maturation and simultaneous multi-beam engagement requirements.
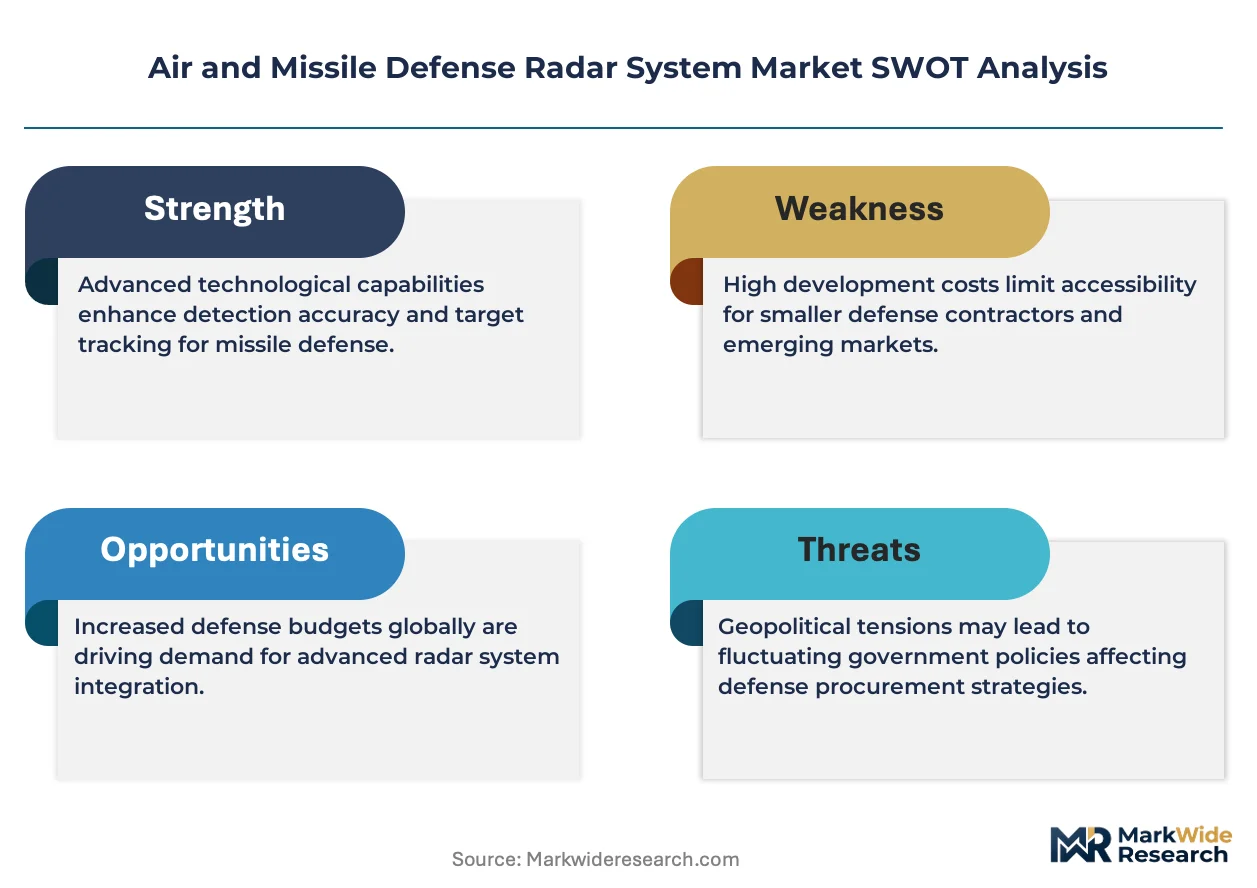
The US Department of Defense, NATO's Conference of National Armaments Directors, and Japan's Acquisition, Technology and Logistics Agency collectively shape demand through interoperability mandates, security-cleared supply chain requirements, and offset provisions that privilege domestic radar fabrication. These frameworks elevate barriers for non-allied component sourcing while accelerating certified software-defined radar architectures. Stakeholders must monitor gallium nitride substrate supply concentration and allied semiconductor export control harmonization as decisive variables for platform availability and program cost trajectories.
Market Dynamics
Gallium nitride substrate supply concentration in Japan and the United States is constraining phased array radar production timelines while NATO interoperability mandates force architectural standardization across national procurement programs.
Growth Catalysts
- Naval Modernization Mandates:NATO member states are accelerating destroyer and frigate replacement programs requiring integrated mast-mounted radar suites. The Conference of National Armaments Directors coordinates multi-nation bulk purchasing to achieve economies of scale.
- Indo-Pacific Territorial Tensions:Layered air defense investments across Japan, Australia, and South Korea drive demand for transportable ground-based radar systems with simultaneous multi-target tracking capability.
- Gallium Nitride Maturation:Higher power density and thermal efficiency in GaN transmitter-receiver modules enable smaller antenna footprints without range degradation, accelerating replacement of legacy gallium arsenide systems.
Market Restraints
- Substrate Supply Concentration:High-purity silicon carbide substrates for GaN epitaxy originate from a concentrated supplier base in Japan and the United States, creating single-source vulnerability for European and Indo-Pacific radar integrators.
- Security-Cleared Supply Chain Requirements:ITAR and EU export control harmonization block component sourcing from non-allied nations, extending lead times for specialized microwave components and digital beamforming processors.
- Fixed-Site Infrastructure Lock-In:Cold War-era radar installations in continental Europe and North America require costly environmental remediation and site preparation before transportable multi-mission units can replace them.
Strategic Opportunities
- Space-Based Radar Integration:Convergence of terrestrial fire-control networks with low-earth orbit sensor constellations creates demand for dual-use ground terminals capable of fusing orbital and atmospheric track data.
- Software-Defined Architectures:Open mission system standards enable hardware-agnostic radar modes, allowing field upgrades via firmware rather than hardware replacement and extending platform service life.
- Poland and Romania:These NATO eastern flank members are constructing integrated air and missile defense batteries with US Patriot and indigenous radar systems, creating greenfield installation demand without legacy infrastructure constraints.
Industry Challenges
- Electromagnetic Spectrum Certification:Each radar mode requires national spectrum regulator approval, with FCC in the United States and national postal and telecommunications authorities in Europe imposing multi-year testing protocols before operational deployment.
- GaN Foundry Capacity Bottlenecks:In-house and captive semiconductor fabrication facilities at prime contractors operate at capacity, forcing subcontractor reliance for secondary radar components and creating quality assurance complexity.
- Legacy System Interoperability:New phased array radars must maintain datalink compatibility with 1980s-era command and control networks, forcing expensive protocol translation hardware into otherwise modern architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air and Missile Defense Radar System Market |
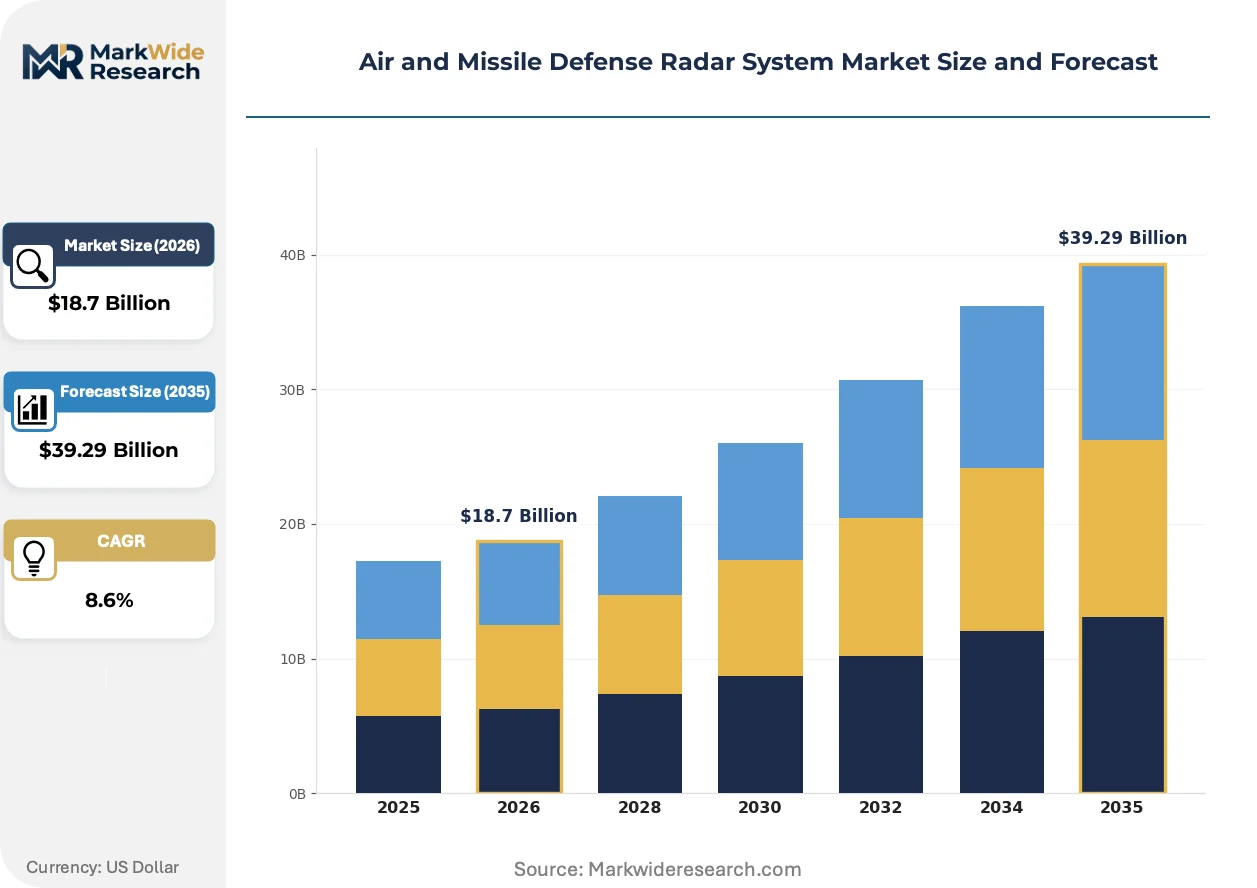
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-Based Radar, Airborne Radar, Naval Radar, Space-Based Radar Technology: Pulsed Radar, Continuous Wave Radar, Phased Array Radar, Doppler Radar End User: Military, Government, Defense Contractors, Aerospace Manufacturers Application: Air Defense, Missile Defense, Surveillance, Target Acquisition |
| Companies Covered | Israel Aerospace Industries, Leonardo S.p.A., Lockheed Martin Corporation, BAE Systems plc, Saab AB, Northrop Grumman Corporation, Thales Group, HENSOLDT AG, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air and Missile Defense Radar System Market Strategic Shifts
Distributed sensor architectures are fragmenting traditional prime contractor roles while digital beamforming and cognitive processing enable radar platforms to share targeting data across heterogeneous networks in real time.
Active electronically scanned array technology is decentralizing threat engagement authority across naval and ground formations. Surface combatant commanders and mobile battery operators now track and classify targets independently rather than relying on centralized sector control. This compression of sensor-to-shooter timelines is reshaping training doctrine and command structure investments across NATO and Indo-Pacific forces.
EU export control harmonization under the dual-use regulation revision is tightening component transfer licensing for gallium nitride semiconductors and high-speed analog-to-digital converters. European radar integrators face extended approval timelines for third-country sales, particularly to Indo-Pacific partners outside NATO frameworks. The regulation is accelerating in-house European GaN foundry investments to reduce ITAR and dual-use licensing exposure.
Lifecycle contracting is displacing discrete platform procurement in major defense acquisitions. The US Department of Defense and Japan's Acquisition, Technology and Logistics Agency now structure decade-long sustainment and upgrade commitments into initial radar awards, capturing vendors through recurring revenue streams rather than episodic production orders. This model concentrates vendor relationships and raises barriers for new radar suppliers seeking initial reference contracts.
Air and Missile Defense Radar System Market Segmentation
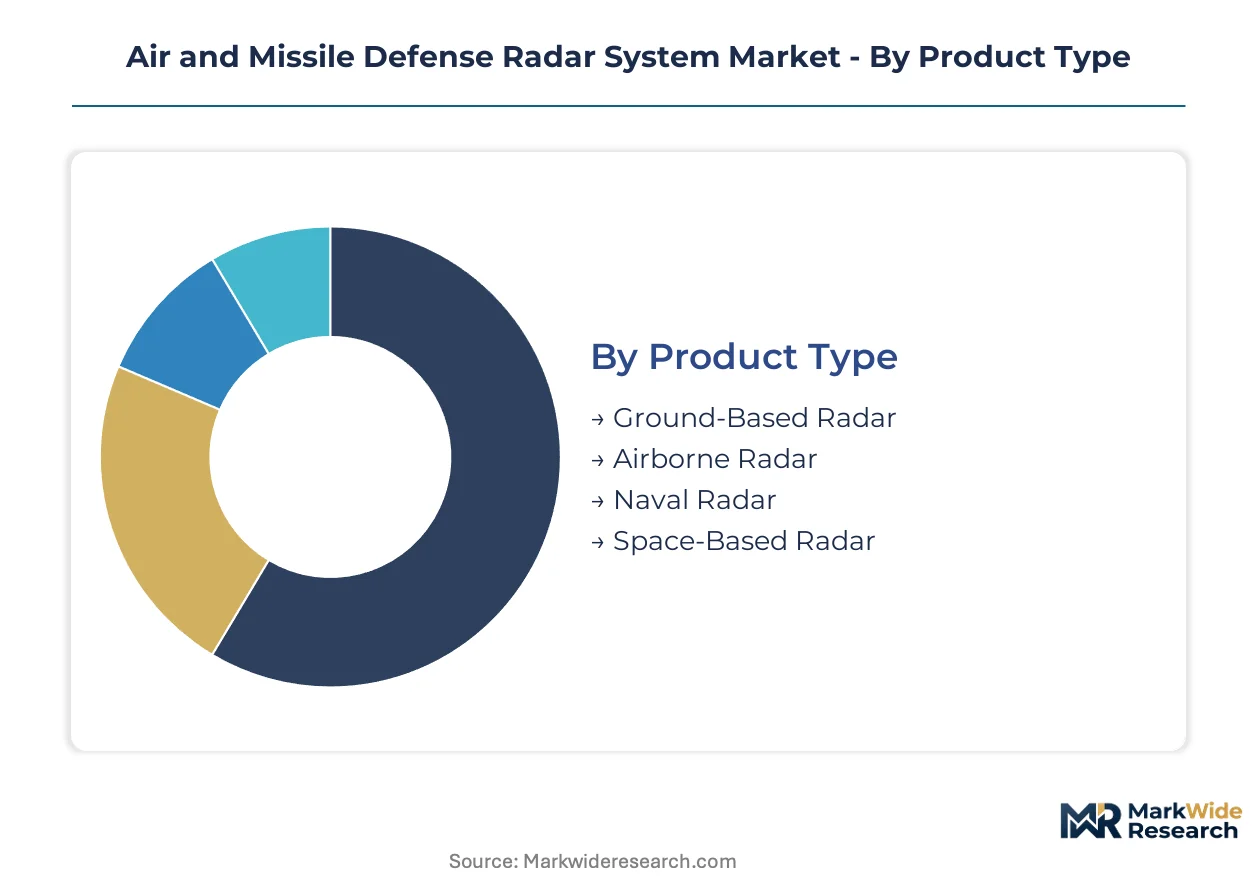
Segmentation reveals how procurement concentration varies sharply across platform types and technology generations. Defense agencies structure acquisition around threat environment, mobility requirements, and interoperability mandates rather than unit cost alone.
Product Type:
Ground-based systems dominate procurement volumes while naval platforms command premium pricing tiers due to integrated mast architecture complexity.
- Ground-Based Radar:Transportable multi-mission units replace fixed Cold War installations across NATO's eastern flank and the Indo-Pacific. Demand concentrates in Poland and Romania where greenfield integrated air and missile defense batteries avoid legacy infrastructure constraints.
- Naval Radar:Integrated mast-mounted phased array suites on destroyer and frigate replacement programs require simultaneous multi-beam engagement for anti-air and ballistic missile defense. NATO's Conference of National Armaments Directors coordinates multi-nation bulk purchasing for these systems.
- Airborne Radar:AWACS and fighter-integrated platforms provide over-the-horizon detection for expeditionary forces.
- Space-Based Radar:Low-earth orbit constellations fuse orbital track data with terrestrial fire-control networks.
Mature deployment sits with Ground-Based Radar. Newer deployment is concentrated in Space-Based Radar.
Technology:
Technology choices track directly to transmitter-receiver module material evolution and thermal management requirements.
- Phased Array Radar:Electronically scanned arrays with gallium nitride transmitter-receiver modules enable smaller antenna footprints without range degradation. Gallium nitride maturation is accelerating replacement of legacy gallium arsenide systems across US and Japanese procurement programs.
- Pulsed Radar:Conventional magnetron-based systems persist in cost-constrained upgrade cycles where digital beamforming processors can retrofit existing antenna architectures.
- Continuous Wave Radar:Low-probability-of-intercept modes for specialized surveillance applications.
- Doppler Radar:Velocity measurement precision for target classification in cluttered environments.
Phased Array Radar captures the steepest expansion trajectory as GaN substrate supply stabilizes.
End User:
Customer type determines contract structure, with military direct procurement favoring lifecycle sustainment models.
- Military:Service branches operate the preponderance of deployed systems under decade-long sustainment commitments that capture vendors through recurring upgrade revenue rather than episodic production orders.
- Government:National agencies manage spectrum certification and interoperability mandates that extend procurement timelines.
- Defense Contractors:Prime integrators source subsystems under ITAR and EU dual-use regulation constraints.
- Aerospace Manufacturers:Platform OEMs embed radar suites into complete weapon system deliveries.
Program scale concentrates with Military end users. Export licensing complexity is highest for Defense Contractors.
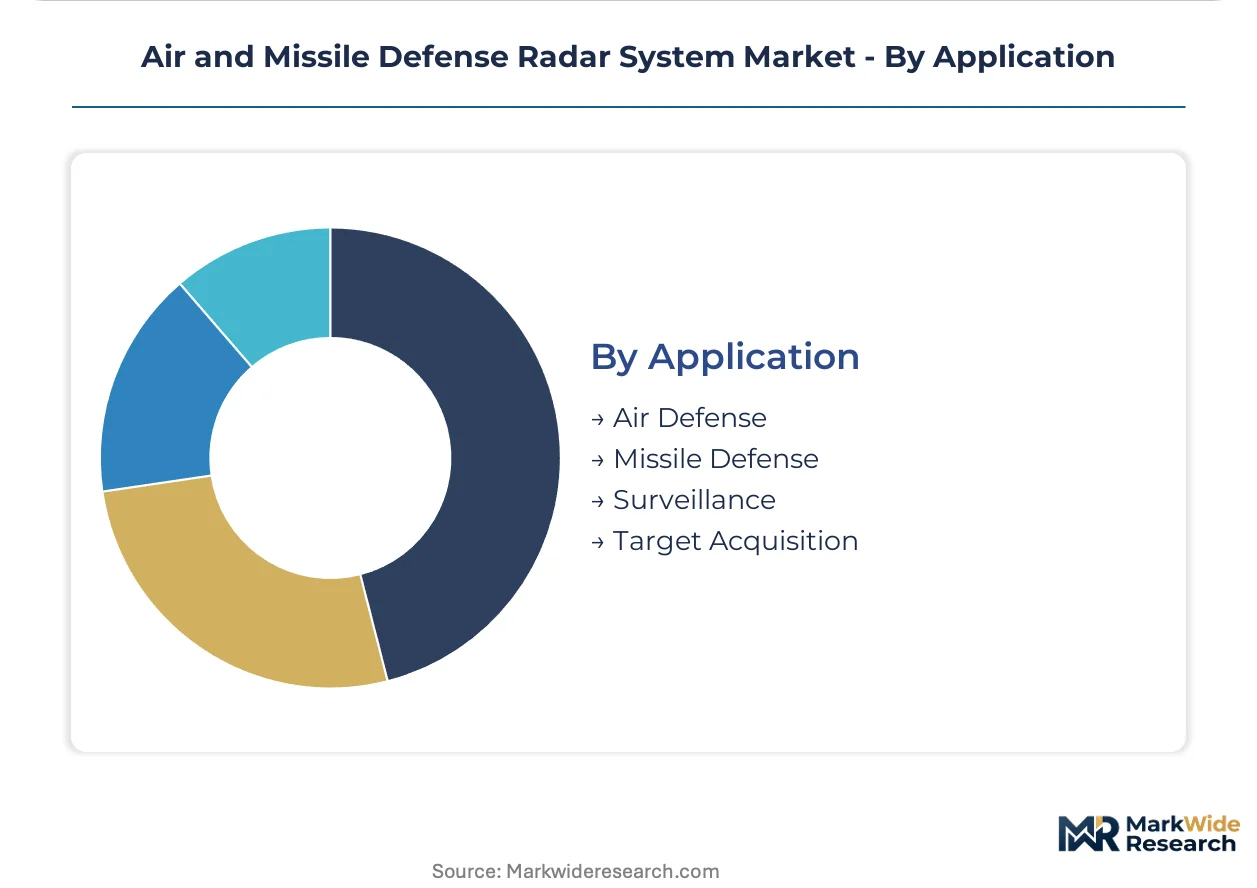
Application:
Application segmentation reflects threat hierarchy prioritization across integrated air and missile defense architectures.
- Missile Defense:Ballistic missile tracking requires S-band through X-band frequency coverage with range exceeding 400 nautical miles for early warning and fire-control quality tracks. Japan's Acquisition, Technology and Logistics Agency prioritizes layered defense investments for this application.
- Air Defense:Counter-cruise missile and aircraft engagement demands rapid beam steering for simultaneous multi-target tracking in dense threat environments.
- Surveillance:Persistent area coverage for border and maritime domain awareness.
- Target Acquisition:Precision cueing for surface-to-air and anti-ship missile batteries.
Capability investment prioritizes Missile Defense. Surveillance applications expand most quickly as software-defined architectures enable mode switching.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense innovation zones in the United States, Japan, and Germany concentrate phased array radar development through tax-advantaged research parks and security-cleared facility clusters. Procurement mandates from NATO, Japan's Acquisition, Technology and Logistics Agency, and the US Department of Defense shape regional production footprints.
United States
Naval modernization programs at Bath Iron Works and Ingalls Shipbuilding drive integrated mast-mounted radar demand for destroyer replacement. The Department of Defense's distributed sensor architecture mandates reshape contract structures toward decade-long sustainment commitments. Massachusetts and Maryland host concentrated GaN foundry capacity supporting transmitter-receiver module production.
Japan
Layered missile defense investments across Okinawa and Kyushu require transportable ground-based radar with simultaneous multi-target tracking. The Acquisition, Technology and Logistics Agency prioritizes interoperability with US Patriot ecosystems through offset provisions favoring domestic fabrication. Kawasaki Heavy Industries and Mitsubishi Electric anchor production in the Kanto industrial corridor.
Germany
NATO's Conference of National Armaments Directors coordinates multi-nation bulk purchasing for frigate radar suites through the European Defence Fund. EU dual-use regulation revisions tighten component transfer licensing for GaN semiconductors. Bavaria and Baden-Württemberg concentrate HENSOLDT AG and subsystem integrator clusters.
Poland
Greenfield integrated air and missile defense batteries avoid legacy infrastructure constraints through new Patriot deployments along NATO's eastern flank. Poland's offset provisions mandate domestic radar component sourcing. The Pomeranian and Masovian voivodeships host emerging defense industrial zones.
Australia
Indo-Pacific territorial tensions accelerate layered defense investments across northern bases and maritime patrol corridors. The Department of Defence's sovereign radar initiative mandates local assembly for transportable multi-mission units. South Australia and Victoria concentrate platform integration facilities.
Air and Missile Defense Radar System Market Competitive Environment
United States producers anchor the premium systems tier; European specialists hold the mid-market retrofit and NATO interoperability segments. The vendor base clusters around three strategic archetypes: vertically integrated primes with captive GaN foundries, platform-agnostic subsystem suppliers, and national champions serving protected domestic markets. Competitive positioning hardens through lifecycle contracting that captures vendors via recurring upgrade revenue, and through security-cleared supply chain certification that blocks non-allied component sourcing.
Within the vertically integrated prime tier, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify the GaN foundry-captive model that sustains margin control across production chains. Northrop Grumman Corporation occupies a position defined by space-based radar integration with terrestrial fire-control networks. Among European specialists, Leonardo S.p.A. and Thales Group represent the NATO interoperability-focused archetype, while Israel Aerospace Industries and Saab AB exemplify national champion positioning within protected domestic procurement frameworks.
| Leading Market Players |
|---|
| Israel Aerospace Industries |
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| BAE Systems plc |
| Saab AB |
| Northrop Grumman Corporation |
| Thales Group |
| HENSOLDT AG |
| Raytheon Technologies Corporation |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride substrate costs cascade through phased array radar pricing tiers, with high-purity silicon carbide wafers from Japanese and US suppliers commanding premiums that compress margins for European integrators while sustaining margin pools for vertically integrated primes.
Pricing Analysis
Short lead-time premiums for gallium nitride transmitter-receiver modules separate procurement tiers, with NATO interoperability mandates adding certification-grade pricing stratification across member-state programs. Price differentiation hinges on ITAR compliance status and domestic offset fulfillment, with Polish and Romanian greenfield installations showing lowest price sensitivity due to absence of legacy retrofit costs. Cost compression in mid-tier pulsed radar retrofits is intensifying as digital beamforming processors commoditize, while Patriot ecosystem sustainment contracts anchor premium pricing through captive upgrade cycles.
Supply Chain Analysis
Refurbishment flows for Cold War-era radar installations create secondary component markets that compete with new production, particularly for magnetron-based subsystems in cost-constrained European upgrades. Supply concentrates in Japan and the United States for GaN epitaxy substrates, with Germany and Australia assembling transportable multi-mission units from imported semiconductor dies. The chain rests on silicon carbide wafer supply, high-speed analog-to-digital converters, and secure firmware distribution networks. Single-source vulnerability in Japanese substrate production poses structural risk. Distribution runs through prime contractor captive foundries and security-cleared subsystem integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN foundry capacity expansion represents the decisive upstream lever in this vertical-integration race, with captive semiconductor fabrication determining margin control across the production chain.
For Market Incumbents: Lock in decade-long sustainment contracts with Japan's Acquisition, Technology and Logistics Agency and NATO's Conference of National Armaments Directors before software-defined architectures commoditize hardware differentiation. Defend against emerging European GaN foundry investments by accelerating proprietary substrate qualification programs. Prioritize certification investment in FCC electromagnetic spectrum approval to extend lead times for challenger systems. For New Entrants and Emerging Players: Begin with software-defined radar architectures for Poland and Romania's greenfield integrated air and missile defense batteries, where absence of legacy datalink constraints lowers interoperability barriers. Target surveillance applications as the most penetrable segment given mode-switching firmware requirements that favor agile development cycles. Pursue offset partnership structures with Australia's sovereign radar initiative to secure initial reference contracts. For Investors and Strategic Acquirers: EU dual-use regulation harmonization completion is the leading indicator that European GaN foundry investments will achieve viable scale independent of ITAR exposure. Long-term viability favors acquisition targets with software-defined architecture IP and security-cleared supply chain certification rather than hardware-locked platform vendors. Monitor gallium nitride substrate supply agreements between Japanese suppliers and Indo-Pacific integrators for early signals of supply constraint easing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Expansion | Captive semiconductor fabrication secures margin control against substrate supply concentration. |
| Software-Defined Architecture Development | Open mission system standards extend platform service life through firmware upgrade pathways. |
| Space-Based Radar Integration | Dual-use ground terminals fuse orbital track data with terrestrial fire-control networks. |
| NATO Interoperability Certification | Conference of National Armaments Directors mandates create barrier against non-allied component sourcing. |
| Lifecycle Sustainment Contracting | Recurring upgrade revenue captures vendor relationships and raises barriers for new entrants. |
Study Parameters
Multi-period observation of gallium nitride substrate supply allocations, NATO procurement award patterns, and electromagnetic spectrum certification timelines anchored the trend analysis, supplemented by interviews with radar system procurement officers at Japan's Acquisition, Technology and Logistics Agency, program managers at the US Department of Defense, semiconductor fabrication executives, and integrated air and missile defense battery commanders. Secondary validation drew from FCC equipment authorization databases, EU dual-use regulation filings, SEC 10-K disclosures from prime contractors, and customs records for high-purity silicon carbide wafer trade flows. Bottom-up platform deployment counts triangulated against top-down defense budget appropriation analysis.
Input-output matrices mapped transmitter-receiver module production capacity through phased array radar system deliveries across the analysis window, with segmentation dimensions spanning platform type, technology generation, end-user procurement structure, and regional regulatory cluster. CAGRs derived from production run-rate projections and upgrade cycle frequencies, incorporating gallium nitride yield improvement curves and software-defined architecture adoption slopes as industry-specific forecast inputs.
Underlying measurement precision varies by segment; ground-based radar procurement volumes carry tighter precision than space-based radar constellation deployment timelines given classified program boundaries. Forecasts reflect documented assumptions regarding ITAR harmonization progress and allied semiconductor export control alignment. Practitioners should monitor Japanese substrate supplier capacity announcements and Polish offset provision enforcement for early signals of supply constraint evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Global Missile Interceptor Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Airborne Fire Control Radar Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
Americas Air Defense Systems Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Europe Air Defense Systems Market