
 Airborne Fire Control Radar Market | 2026-2036
Airborne Fire Control Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Fire Control Radar Market Intelligence
Defense procurement offices are bifurcating between fifth-generation fighter integration programs and legacy platform retrofit cycles. Lockheed Martin Corporation leverages its F-35 sensor fusion architecture to dominate next-generation fire control contracts. Raytheon Technologies Corporation anchors the US market through captive production of gallium nitride transmit-receive modules. BAE Systems Plc competes across European combat air programs with sovereign radar supply chains.
Airborne fire control radar denotes an aircraft-mounted electromagnetic sensor system operating in X-band or Ku-band frequencies, employing monopulse or phased-array architectures to track, classify, and illuminate targets for precision-guided munitions. The primary purpose is to enable beyond-visual-range engagement and all-weather strike capability for manned and unmanned combat aircraft. Phased array radar systems occupy the premium tier of the technology segment, driven by electronic beam steering requirements in stealth platforms. The military end-user category sustains the dominant revenue share, while homeland security applications represent an emerging demand pocket for airborne border surveillance configurations.
The US Department of Defense mandates MIL-STD-461G electromagnetic compatibility and ITAR-controlled export thresholds that constrain non-US suppliers from accessing certain platform integrations. European procurement operates under OCCAR framework agreements and EU defense fund coordination mechanisms that prioritize cross-border industrial participation. China's MIIT enforces GB standards and indigenous substitution policies for military avionics procurement. Stakeholders must monitor gallium nitride supply chain concentration and sovereign content rules as determinants of contract eligibility across major procurement theaters.
Market Dynamics
The US Department of Defense's software-defined radar mandate is compressing hardware refresh cycles while fragmenting supplier tiers between GaN module specialists and system integrators. This architectural pivot forces legacy platform operators to choose between full sensor replacement or federated aperture upgrades.
Growth Catalysts
- Active Electronically Scanned Arrays:Fighter modernization programs in the United States, China, and NATO member states are mandating electronic beam steering for beyond-visual-range engagement capability.
- OCCAR Framework Agreements:European cross-border procurement mechanisms prioritize sovereign radar supply chains, creating protected demand pools for EU-based system integrators.
- Gallium Nitride Transmit-Receive Modules:Wider bandwidth and higher power density in GaN semiconductors enable multi-function apertures that consolidate electronic warfare and communications functions.
Market Restraints
- ITAR Export Controls:US State Department restrictions on X-band and Ku-band technologies block non-US suppliers from F-35 and other integrated platform programs.
- GaN Substrate Concentration:Epitaxial wafer production concentrates among three Japanese and US chemical suppliers, creating chokepoint vulnerability for transmit-receive module fabricators.
- Legacy Platform Architecture Lock:Mechanical scanning radars in F-15, F-16, and Su-27 variants require structural airframe modifications for phased-array retrofit, extending certification timelines.
Strategic Opportunities
- Homeland Security Airborne Surveillance:Border patrol and coastal monitoring agencies in the United States and Australia are procuring fire control radars for unmanned patrol aircraft configurations.
- Dual-Use Frequency Convergence:Software-defined architectures enable spectrum sharing between military fire control and civilian weather radar applications, opening FAA certification pathways.
- Indigenous Substitution Policies:China's MIIT enforcement of GB military avionics standards creates captive procurement pools for domestic radar developers serving J-20 and FC-31 programs.
Industry Challenges
- Electromagnetic Compatibility Certification:MIL-STD-461G testing for platform-level interference requires 18-24 month validation cycles that delay fielding schedules.
- Phased Array Thermal Management:Dense GaN module packaging demands liquid cooling integration with aircraft environmental control systems, complicating retrofit engineering.
- Software-Hardware Co-Development:Agile radar mode programming outpaces traditional defense acquisition timelines, creating version control conflicts between prime contractors and subsystem vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Fire Control Radar Market |
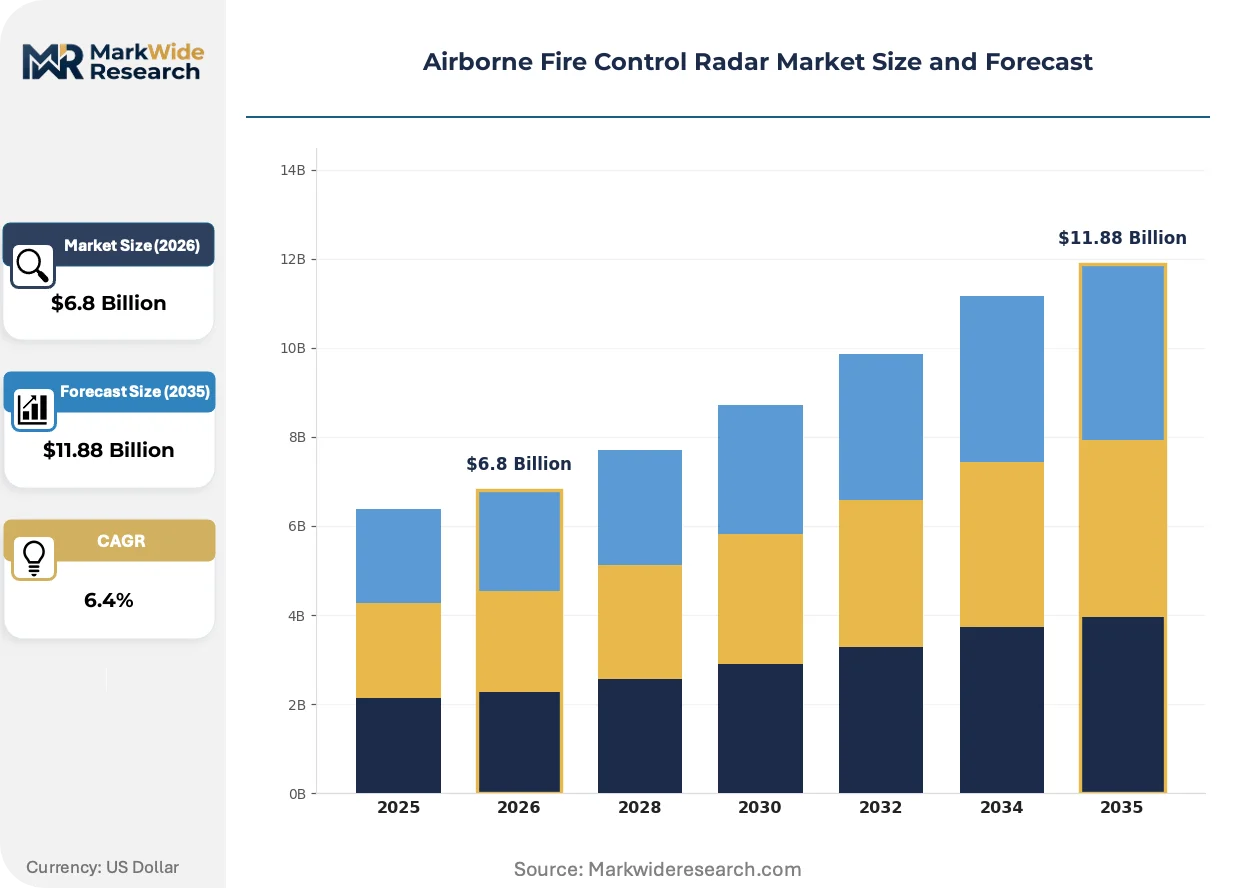
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Phased Array Radar, Synthetic Aperture Radar, Pulse Doppler Radar, Frequency Modulated Continuous Wave Radar End User: Military, Civil Aviation, Homeland Security, Aerospace Component: Transmitter, Receiver, Antenna, Processor Application: Target Detection, Surveillance, Weapon Guidance, Navigation |
| Companies Covered | BAE Systems Plc, Leonardo S.p.A., Lockheed Martin Corporation, Israel Aerospace Industries, Hensoldt AG, Northrop Grumman Corporation, Thales Group, Saab AB, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Fire Control Radar Market Strategic Shifts & Innovations
Digital beamforming and open systems architectures are dissolving the traditional boundary between hardware suppliers and software-defined capability providers. This shift enables third-party algorithm insertion while threatening incumbent integrated system margins.
Software-defined radar is fragmenting the value chain between aperture hardware vendors and mission software developers. Fifth-generation fighter programs in the United States and China are mandating programmable waveform generation for multi-spectral operations. This capability compression forces legacy suppliers to restructure engineering organizations around DevSecOps release cycles rather than hardware block upgrades.
EU defense fund coordination mechanisms are mandating cross-border industrial participation thresholds for combat air system contracts. The F-Gas Regulation and REACH chemical restrictions are constraining thermal interface materials used in high-density array packaging. European prime contractors are responding by qualifying alternative phase-change materials and solid-metal thermal spreaders for next-generation platforms.
Defense procurement offices are unbundling sensor hardware from long-term sustainment contracts, compressing supplier revenue recognition into discrete platform integration events. This disaggregation shifts risk to contractors for obsolescence management and spares forecasting. The United States and United Kingdom are most advanced in this transition, with Australia and Japan following through AUKUS and bilateral FMS arrangements.
Airborne Fire Control Radar Market Segmentation
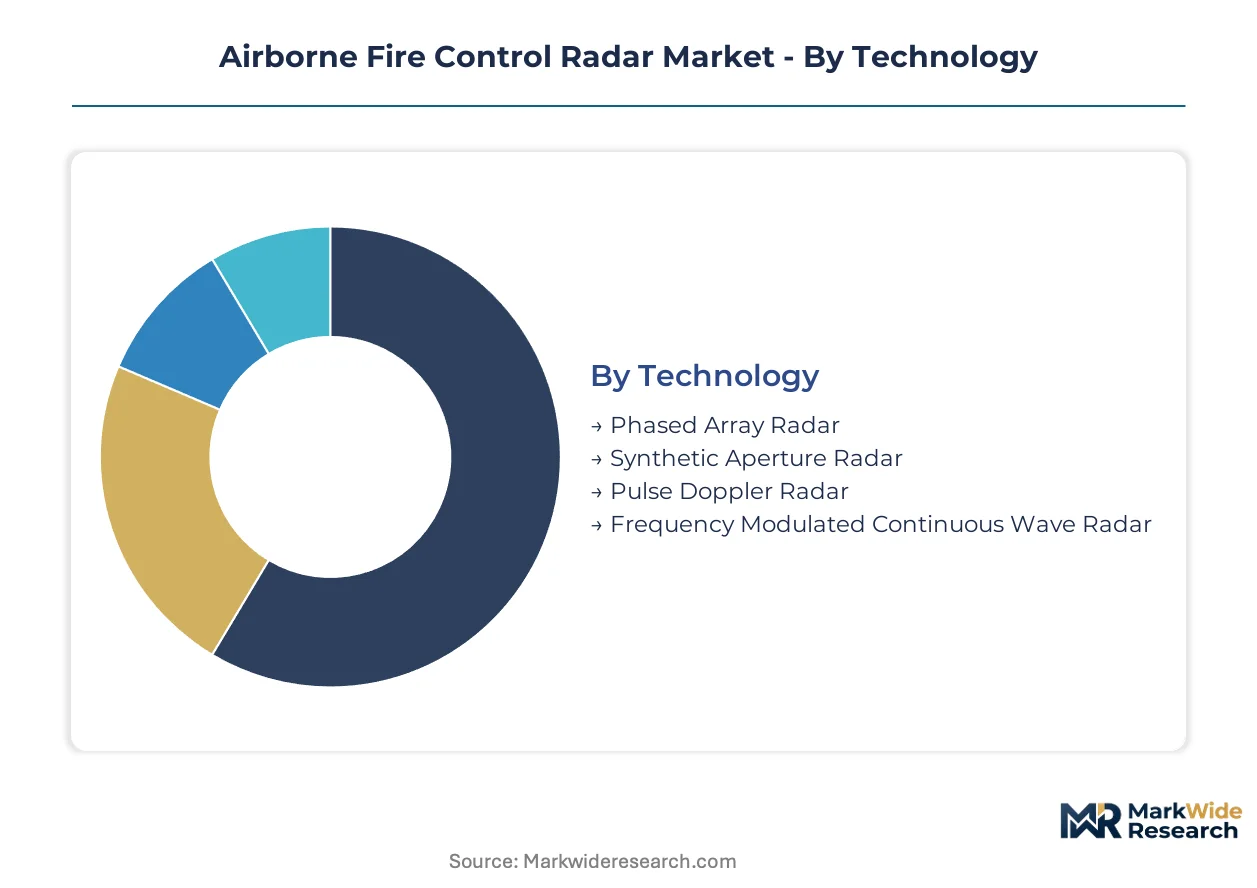
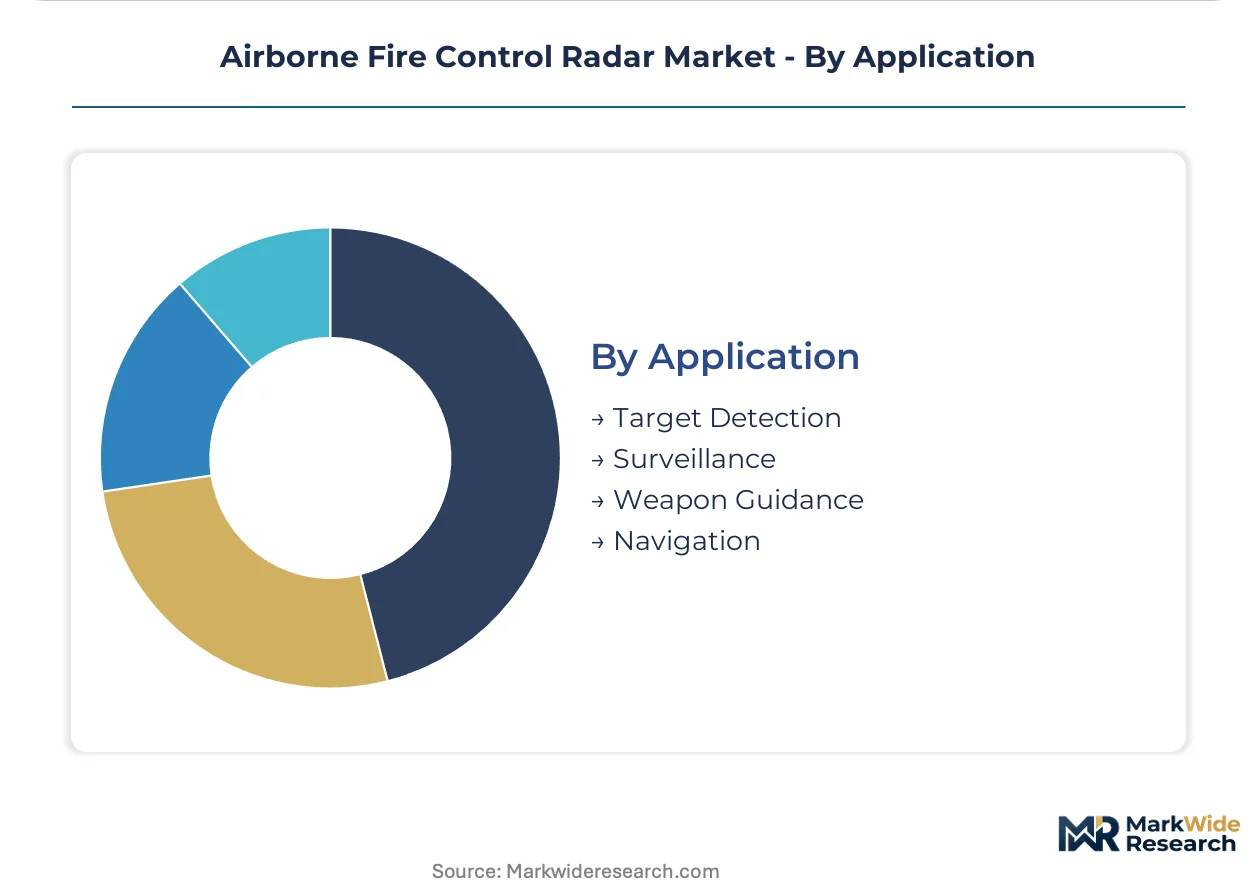
Segmentation in airborne fire control radar reveals how procurement budgets fragment across technology tiers and mission profiles. Military buyers prioritize electronic beam steering for fifth-generation platforms, while civil and security operators seek cost-optimized configurations for patrol and surveillance roles.
Technology:
Phased array architectures face substitution pressure from software-defined alternatives that compress hardware refresh cycles and fragment supplier tiers.
- Phased Array Radar:Electronic beam steering eliminates mechanical gimbals, enabling track-while-scan and low-observable aperture integration. Demand concentrates in F-35 and J-20 programs where sensor fusion mandates solid-state transmit-receive arrays. MIL-STD-461G electromagnetic compatibility requirements constrain retrofit timelines for legacy platforms.
- Synthetic Aperture Radar:Coherent processing of multiple radar returns generates high-resolution ground imagery for moving target indication and terrain mapping. Border patrol agencies in Australia and the United States procure SAR-equipped unmanned patrol aircraft for coastal monitoring missions. FAA certification pathways for dual-use spectrum sharing are expanding civilian procurement pools.
- Pulse Doppler Radar:Velocity discrimination through coherent pulse processing enables look-down shoot-down capability against low-altitude targets.
- Frequency Modulated Continuous Wave Radar:Continuous transmission architecture delivers low probability of intercept signatures for electronic warfare contested environments.
Phased array radar anchors the volume base while synthetic aperture radar gains share at the steepest rate.
End User:
Cost tier stratification separates sovereign military procurement from commercial aviation and security agency budgets.
- Military:Combat air programs in the United States, China, and NATO member states drive premium-tier demand for multi-function apertures consolidating electronic warfare and communications. OCCAR framework agreements and ITAR export controls create segmented procurement pools with divergent supplier access.
- Homeland Security:Unmanned border surveillance configurations represent an emerging demand pocket with lower performance thresholds and compressed acquisition timelines. Australian and US coastal patrol agencies are fielding fire control radars on medium-altitude long-endurance platforms.
- Civil Aviation:Weather penetration and terrain avoidance applications in regional transport aircraft favor cost-optimized pulse Doppler architectures.
- Aerospace:Research and test range applications require programmable waveform generation for algorithm validation and threat simulation.
Military end users anchor the volume base while homeland security gains share at the steepest rate.
Component:
Supply concentration in epitaxial wafer production creates margin pressure downstream in transmit-receive module fabrication.
- Transmitter:Gallium nitride power amplifiers enable wider bandwidth and higher power density than legacy gallium arsenide, consolidating electronic attack and communications functions into single apertures. Japanese and US chemical suppliers dominate epitaxial substrate production, creating chokepoint vulnerability for module fabricators.
- Receiver:Low-noise amplifiers and digital receivers convert RF signals to baseband for processing, with open systems architectures enabling third-party algorithm insertion.
- Antenna:Active electronically scanned arrays integrate thousands of transmit-receive modules with beamforming networks, demanding liquid cooling integration with aircraft environmental control systems.
- Processor:Mission software running on ruggedized computing hardware executes target tracking, classification, and fire control solutions with DevSecOps release cycles.
Transmitter components anchor the volume base while processor subsystems gain share at the steepest rate.
Application:
Mission type determines aperture size, power budget, and waveform complexity requirements across platform categories.
- Target Detection:Beyond-visual-range engagement capability demands high pulse repetition frequency modes and doppler processing for clutter rejection. Fighter modernization programs in NATO member states and China mandate detection ranges exceeding 150 nautical miles against reduced cross-section targets.
- Weapon Guidance:Illumination and datalink functions for precision-guided munitions require stable tracking loops and low sidelobe antenna patterns.
- Surveillance:Wide-area search and ground moving target indication favor synthetic aperture processing and stripmap imaging modes.
- Navigation:Terrain following and weather penetration applications in transport and rotary-wing aircraft use forward-looking radar for obstacle avoidance.
Target detection anchors the volume base while weapon guidance gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-based prime contractors export fire control radar systems to NATO allies through Foreign Military Sales channels, while Chinese suppliers serve domestic J-20 and FC-31 programs under MIIT procurement mandates.
United States
F-35 sensor fusion programs and legacy fighter retrofits drive procurement volume. The Department of Defense mandates MIL-STD-461G electromagnetic compatibility and ITAR-controlled export thresholds that constrain foreign supplier access. Lockheed Martin and Raytheon anchor production clusters in Texas and Arizona, consolidating gallium nitride module fabrication for domestic and allied platform integration.
China
J-20 stealth fighter production and indigenous avionics substitution policies accelerate demand. MIIT enforces GB military standards and captive procurement pools that exclude foreign radar developers. Chengdu and Xi'an host state-owned defense enterprises manufacturing active electronically scanned arrays for manned and unmanned combat aircraft programs.
Germany
Typhoon fighter modernization and FCAS sixth-generation development sustain sovereign radar requirements. OCCAR framework agreements prioritize cross-border industrial participation for combat air system contracts. Bavaria and Baden-Württemberg concentrate Hensoldt and Airbus Defence electronics operations serving European cooperative programs.
United Kingdom
Tempest fighter sensor development and F-35B carrier integration shape procurement priorities. BAE Systems leverages sovereign supply chains for radar subsystems under UK defense industrial strategy mandates. Lancashire and Greater Manchester host prime contractor facilities developing multi-function apertures for next-generation platforms.
Israel
Domestic fighter upgrade programs and unmanned combat aircraft exports sustain specialized radar demand. Israel Aerospace Industries and Elbit Systems operate under Ministry of Defense procurement frameworks with technology transfer restrictions. Central Israel's defense electronics corridor concentrates transmit-receive module development for regional and export markets.
Airborne Fire Control Radar Market Key Industry Players
Player mix skews toward vertically integrated defense primes with captive semiconductor fabrication and system integration capabilities. Market structure concentrates around US and European contractors holding platform-level integration contracts, with tier-two suppliers specializing in gallium nitride modules and antenna subassemblies. Strategic archetypes include sovereign radar champions serving national fighter programs, multi-domain sensor integrators leveraging software-defined architectures, and GaN module specialists supplying across prime contractor tiers. Competitive moves center on backward integration into epitaxial wafer supply and strategic partnerships for open systems software development.
Among US-based system integrators, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify the vertically integrated prime archetype, anchoring domestic F-35 and legacy platform retrofit programs. BAE Systems Plc represents the European sovereign champion model, competing across OCCAR-coordinated combat air initiatives with UK-centered supply chains. Thales Group and Saab AB occupy positions within the multi-national cooperative tier, participating in cross-border fighter development through risk-sharing arrangements. Leonardo S.p.A. and Hensoldt AG sit within the European specialist segment, supplying radar subsystems to prime contractors under industrial participation rules. Northrop Grumman Corporation and Israel Aerospace Industries anchor transatlantic and Middle Eastern demand vectors respectively, with the former concentrating on US Navy carrier aviation programs.
| Leading Market Players |
|---|
| BAE Systems Plc |
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| Israel Aerospace Industries |
| Hensoldt AG |
| Northrop Grumman Corporation |
| Thales Group |
| Saab AB |
| Raytheon Technologies Corporation |
| Others |
Cost & Logistics Intelligence
Gallium nitride substitution for gallium arsenide in transmit-receive modules simultaneously concentrates supply geography among Japanese and US epitaxial wafer producers and compresses pricing economics across hardware tiers. This material transition forces module fabricators to absorb upstream cost volatility while defense procurement offices unbundle sensor hardware from sustainment contracts.
Pricing Analysis
Phased array systems command substantial premiums over mechanical scanning architectures, with software-defined apertures introducing a third pricing tier based on programmable waveform capability. Three-tier pricing structure across premium, standard, and economy levels reflects MIL-STD-461G certification grade and sovereign content thresholds. Cost compression in legacy platform retrofits is intensifying because OCCAR framework agreements mandate cross-border industrial participation. Homeland security agencies exhibit highest price sensitivity due to compressed acquisition timelines, while fifth-generation fighter programs show lowest sensitivity given sensor fusion mandates.
Supply Chain Analysis
Inbound logistics costs for GaN epitaxial wafers hinge on container availability from Yokkaichi and Raleigh-Durham production clusters to transmit-receive module fabricators in Texas and Arizona. Supply concentrates in Japan, the United States, and Germany for substrate production, with module assembly drawing from Taiwan and South Korea for back-end packaging. Raw material dependencies span high-purity ammonia, sapphire substrates, and specialized metal-organic precursors. Single-source vulnerability in epitaxial growth equipment creates chokepoint exposure. Distribution runs through Foreign Military Sales channels for US-aligned procurement and direct state-owned enterprise allocation for Chinese programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined radar architectures fragment the value chain between aperture hardware vendors and mission software developers, creating specialist niches for algorithm providers and thermal management engineers. This demand-side shift rewards focused entrants while pressuring integrated primes to unbundle offerings.
For Market Incumbents: Shield F-35 and J-20 platform integration positions through backward integration into GaN epitaxial wafer supply, countering Japanese chemical supplier concentration. Prioritize DevSecOps certification investments to accelerate software release cycles against agile algorithm vendors. Lockheed Martin and Raytheon anchor positions depend on sustaining ITAR-compliant production clusters against emerging sovereign radar champions.
For New Entrants and Emerging Players: Anchor in homeland security unmanned patrol configurations, where Australian and US coastal agencies seek cost-optimized fire control radars with compressed procurement timelines. Target synthetic aperture radar processing subsystems as the most penetrable segment given dual-use FAA certification pathways. Pursue open systems architecture partnerships with prime contractors seeking third-party algorithm insertion.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors GaN module specialists with captive epitaxial relationships over hardware-integrated system primes. Long-term viability centers on software-defined capability providers serving multi-spectral operations. Watch gallium nitride substrate capacity expansion announcements as the inflection indicator for transmit-receive module margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Secures GaN substrate access against Japanese chemical supplier concentration for module fabricators. |
| Open Systems Architecture Certification | Enables third-party algorithm insertion under US Department of Defense software-defined radar mandates. |
| DevSecOps Engineering Organization Restructuring | Accelerates radar mode programming release cycles to match agile defense acquisition timelines. |
| Homeland Security Patrol Platform Partnership | Captures Australian and US coastal agency demand for medium-altitude long-endurance radar configurations. |
| Thermal Management Material Qualification | Addresses EU F-Gas Regulation constraints on high-density array packaging through alternative phase-change materials. |
Research Approach
Findings reconcile primary fieldwork against secondary review of US Department of Defense procurement disclosures, OCCAR framework agreement documentation, and MIIT GB standards filings. Primary interviews with radar subsystem procurement officers at defense primes, GaN module fabrication engineers, thermal management specialists, and open systems software architects combined with bottom-up platform integration forecasts and top-down defense budget allocation analysis.
Segmentation dimensions modeled span technology architecture, end-user category, component subsystem, and application mission type across the projection horizon. CAGRs derive from platform production forecasts triangulated against radar content-per-aircraft estimates and retrofit cycle timing. Industry-specific inputs include F-35 and J-20 production ramp schedules, Typhoon modernization commitments, and FCAS development milestones.
Decision-makers should treat outputs as directional under assumptions of sustained defense procurement acceleration and stable gallium nitride substrate supply; material deviation in either factor would warrant model refresh. Forecasts reflect assumptions of continued ITAR restriction enforcement and OCCAR industrial participation thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Global Missile Interceptor Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
Air Defense System Market
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Americas Air Defense Systems Market