
 Global Missile Interceptor Market | 2026-2036
Global Missile Interceptor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Missile Interceptor Market Foresight
Modular interceptor packaging is recalibrating procurement economics for defense ministries worldwide. Lockheed Martin Corporation leverages its hit-to-kill expertise across ground, sea, and space layers. RTX Corporation anchors the radar and sensor ecosystem that feeds targeting data into interceptor networks. MBDA competes through specialization in European theater defense architectures and naval point-protection systems.
A missile interceptor is a defensive weapon system engineered to detect, track, and neutralize hostile ballistic, cruise, or hypersonic projectiles through kinetic impact, explosive fragmentation, or directed-energy engagement, typically incorporating solid-fuel boosters, precision guidance suites, and exo-atmospheric or endo-atmospheric kill vehicles. Its primary purpose is to shield strategic assets, population centers, and military formations from aerial attack. Ground-based interceptors command the largest installed base and renewal budgets, while directed-energy technology represents the fastest-evolving frontier with potential to slash per-engagement costs. Sea-based platforms draw disproportionate investment from Indo-Pacific navies seeking mobile, distributed defense layers.
The U.S. Missile Defense Agency, NATO's Integrated Air and Missile Defence programme, and Japan's Ministry of Defense shape procurement timelines through certification regimes and joint development funding. These bodies enforce interoperability standards that favor suppliers with proven multi-domain integration records. Stakeholders must weigh sustained investment in kinetic boosters against the strategic optionality of maturing directed-energy and electronic warfare alternatives.
Market Dynamics
Directed-energy weapon maturation is compressing interceptor procurement cycles as defense ministries weigh kinetic booster replacement against laser-based point defense deployment timelines. The U.S. Missile Defense Agency's technology refresh mandates and NATO's interoperability certification regimes are forcing suppliers to reconfigure platform architectures around modular open systems.
Growth Catalysts
- Hypersonic threat proliferation:Russia's Avangard and China's DF-ZF deployments are compelling Japan, South Korea, and Australia to accelerate layered defense procurement under trilateral security frameworks.
- Next Generation Interceptor program:The U.S. Missile Defense Agency's $10 billion-plus development initiative is standardizing hit-to-kill architectures across ground-based midcourse defense sites.
- Directed-energy maturation:Solid-state laser advances are reducing per-engagement costs from kinetic interceptors' multi-million dollar price points toward single-digit million thresholds.
Market Restraints
- Rare earth supply concentration:Neodymium and dysprosium dependencies on Chinese processing infrastructure create vulnerability in precision guidance magnet production.
- Technical limitation:Atmospheric thermal blooming restricts effective range of laser interceptors below 10 kilometers against sea-skimming cruise missiles.
- Regulatory friction:ITAR export controls delay technology transfer timelines for Indo-Pacific joint development programs by 18-36 months.
Strategic Opportunities
- Underpenetrated geography:Poland's Wisla and Narew programs represent Europe's largest interceptor procurement expansion outside NATO's nuclear umbrella.
- Emerging application:Space-based sensor layers for boost-phase tracking offer intercept windows before hypersonic glide vehicles deploy countermeasures.
- Regulatory tailwind:Japan's 2022 National Security Strategy revision mandates integrated air and missile defense spending at 2% of GDP.
Industry Challenges
- Systems engineering talent scarcity:Exo-atmospheric kill vehicle guidance algorithm development requires specialized expertise concentrated at a handful of national laboratories.
- Integration complexity:NATO's Integrated Air and Missile Defence programme certification demands simultaneous compatibility with U.S., French, and Italian command-and-control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Missile Interceptor Market |
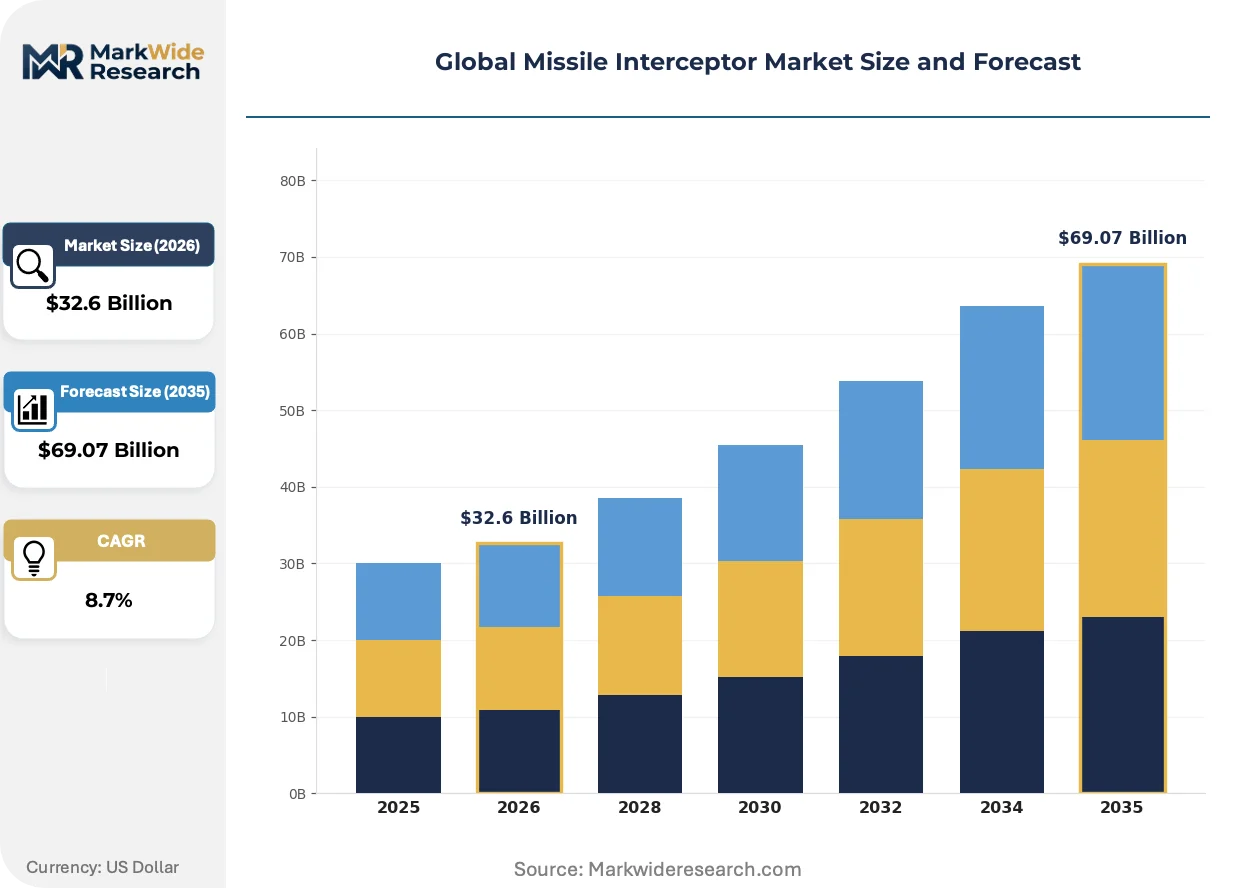
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $69.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Interceptor Type: Ground-Based, Sea-Based, Airborne, Mobile, Fixed-Site Technology: Hit-to-Kill, Directed Energy, Kinetic Energy, Electronic Warfare, Booster Technology Application: Ballistic Threat Neutralization, Cruise Missile Defense, Hypersonic Defense, Tactical Missile Protection, Strategic Asset Safeguard End User: Defense Forces, Missile Defense Agencies, Naval Command, Air Defense Units, Space Security Organizations |
| Companies Covered | Rafael Advanced Defense Systems Ltd., Boeing Defense, Space & Security, Lockheed Martin Corporation, Israel Aerospace Industries, MBDA, RTX Corporation, BAE Systems plc, Thales Group, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Missile Interceptor Market Shifts & Advancements
Interceptor kill vehicles are migrating toward multi-spectral seekers and artificial intelligence-enabled discrimination algorithms. Defense procurement offices are compressing development timelines while demanding open-architecture standards that prevent vendor lock-in.
Multi-object kill vehicle technology is consolidating the economics of midcourse defense by enabling single interceptors to address multiple reentry vehicles and decoys simultaneously. The U.S. Missile Defense Agency is accelerating flight test schedules for these architectures. This consolidation is reducing the interceptor-to-target cost ratio that has historically favored offensive missile proliferation.
REACH chemical registration requirements in Europe are restricting perchlorate-based solid propellant formulations used in booster stages. Manufacturers are reformulating propellant chemistry to maintain performance while eliminating restricted substances. Ground-based interceptor production lines in Germany and Italy are adapting certification documentation to satisfy both REACH and NATO standardization office requirements.
All-up-round contracting is displacing component-separate procurement across Indo-Pacific defense ministries. Australia's Guided Weapons and Explosive Ordnance Enterprise is mandating prime contractor accountability for full system performance rather than subsystem deliverables. This behavioral shift is most visible in Japan, where the Ministry of Defense now requires Lockheed Martin and Raytheon to assume integration risk for Aegis Ashore replacements.
Global Missile Interceptor Market Segmentation
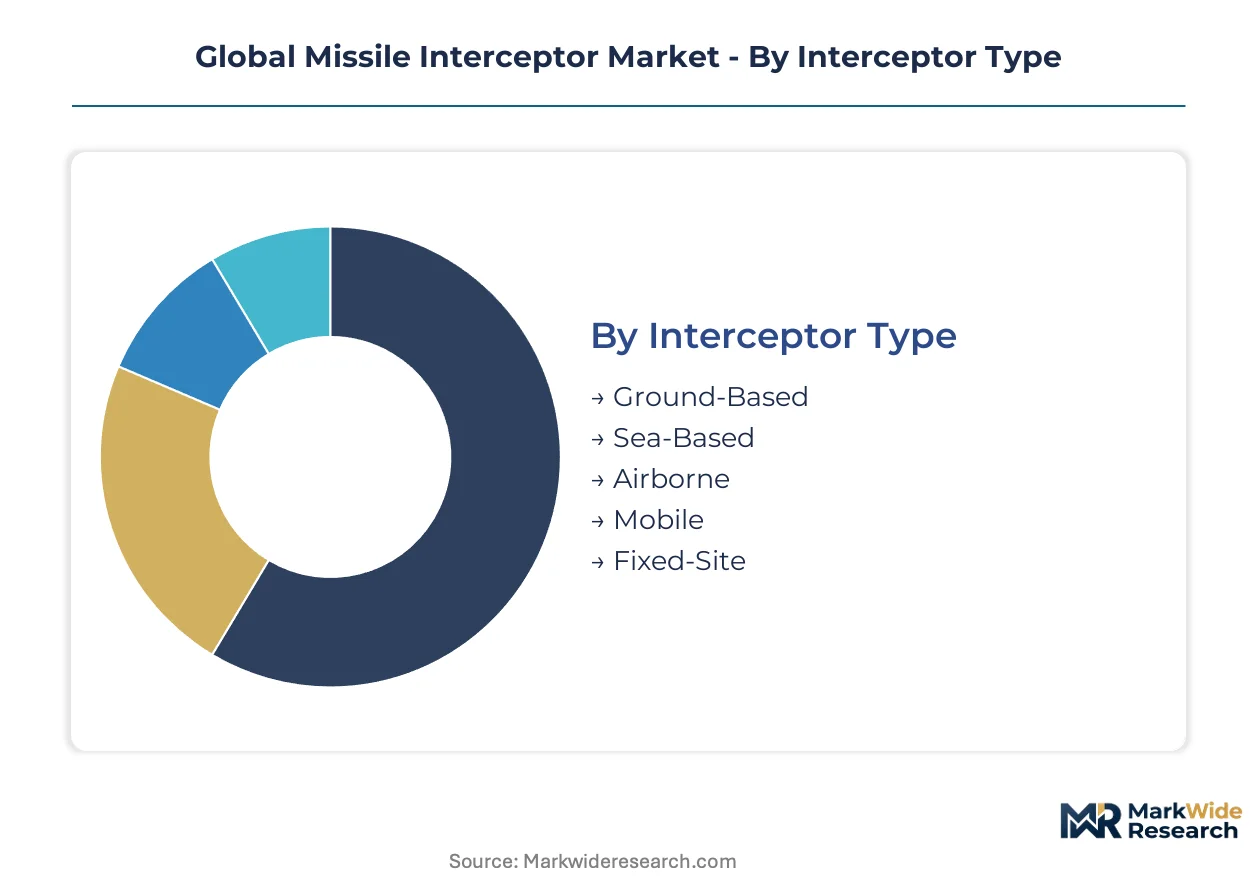
Missile interceptor procurement patterns diverge sharply across deployment modes and engagement technologies. Defense ministries calibrate investments against threat velocity, infrastructure constraints, and kill-chain complexity.
Interceptor Type:
Supply concentration tilts toward ground-based architectures where production lines achieve scale economies through multi-decade sustainment contracts.
- Ground-Based:Fixed emplacements at Fort Greely and Vandenberg Space Force Base anchor the U.S. Ground-based Midcourse Defense network. Japan's Ministry of Defense is replicating this architecture for Aegis Ashore replacements following 2020 program suspension.
- Sea-Based:Aegis Ballistic Missile Defense destroyers provide mobile defense layers across the Indo-Pacific. The U.S. Navy's distributed maritime operations doctrine is driving demand for additional vertical launch system capacity aboard Arleigh Burke-class hulls.
- Airborne:Boeing's Airborne Laser program legacy informs directed-energy demonstrations aboard modified commercial platforms.
- Mobile:Poland's Wisla program deploys PAC-3 MSE batteries on wheeled transporter-erector-launchers for rapid repositioning against eastern flank threats.
- Fixed-Site:Saudi Arabia's THAAD batteries at King Khalid Air Base exemplify hardened infrastructure protecting critical energy infrastructure.
Ground-Based absorbs the bulk of installed capacity; Sea-Based is expanding most quickly.
Technology:
Cost tier stratification separates mature kinetic boosters from developmental directed-energy platforms with order-of-magnitude engagement cost differentials.
- Hit-to-Kill:Exo-atmospheric kill vehicles use infrared seekers and divert thrusters for direct impact at orbital velocities. The U.S. Missile Defense Agency's Next Generation Interceptor program is standardizing this architecture across midcourse defense sites.
- Directed Energy:Solid-state laser maturation is compressing per-engagement costs toward single-digit million thresholds. The U.S. Navy's Layered Laser Defense program is integrating 60-kilowatt systems aboard destroyers for counter-UAS and cruise missile applications.
- Kinetic Energy:Hypervelocity projectiles fired from conventional naval guns offer point defense without explosive payloads.
- Electronic Warfare:RF countermeasures disrupt missile guidance during terminal phase without physical destruction.
- Booster Technology:Solid-propellant formulations face REACH chemical registration constraints in European production facilities.
Hit-to-Kill commands current procurement volumes; Directed Energy is climbing the fastest.
Application:
Threat velocity hierarchies prioritize hypersonic defense investments despite technical immaturity of countermeasures against maneuvering glide vehicles.
- Ballistic Threat Neutralization:Midcourse interceptors engage ICBM warheads outside the atmosphere where thermal signatures are distinct. The Ground-based Midcourse Defense system maintains operational readiness at Alaska and California sites.
- Hypersonic Defense:Glide vehicle trajectories below traditional radar horizons demand space-based sensor layers and accelerated intercept timelines. Australia's investment in hypersonic tracking capabilities supports trilateral information sharing with the U.S. and Japan.
- Cruise Missile Defense:Sea-skimming threats require layered radar and electro-optical detection for terminal engagement.
- Tactical Missile Protection:Short-range defenses shield maneuver formations against artillery rockets and battlefield missiles.
- Strategic Asset Safeguard:Fixed installations protect command nodes and nuclear infrastructure against decapitation strikes.
Ballistic Threat Neutralization retains the largest committed budget; Hypersonic Defense is gaining share fastest.
End User:
Procurement authority fragmentation across service branches creates coordination friction in integrated air and missile defense architectures.
- Defense Forces:Unified combatant commands operationalize interceptor networks through theater-specific deployment concepts. U.S. Indo-Pacific Command's distributed defense posture emphasizes sea-based mobility.
- Missile Defense Agencies:The U.S. Missile Defense Agency controls development funding and test schedules for next-generation architectures. Technology refresh mandates from this body force supplier reconfiguration around modular open systems.
- Naval Command:Fleet commanders prioritize magazine depth and reload capacity for sustained operations against saturation attacks.
- Air Defense Units:Army air defense artillery regiments operate Patriot and THAAD batteries with distinct training and logistics pipelines.
- Space Security Organizations:Emerging entities track boost-phase signatures for early warning and engagement cueing.
Defense Forces absorb the bulk of fielded systems; Missile Defense Agencies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States, Israel, and Western Europe, while consumption spreads across the Indo-Pacific rim as threat perceptions intensify. Defense ministries in Japan, South Korea, and Australia now absorb the fastest-growing procurement volumes.
United States
The Missile Defense Agency's Next Generation Interceptor program and layered defense architectures drive sustained procurement. FAA and DoD interoperability standards govern system certification for integrated air and missile defense networks. Huntsville, Alabama anchors the Ground-based Midcourse Defense industrial base with Boeing and Northrop Grumman production facilities.
Japan
Hypersonic glide vehicle threats from regional adversaries accelerate Aegis Ashore replacement programs and sea-based interceptor procurement. METI's 2022 National Security Strategy revision mandates defense spending at two percent of GDP with integrated air and missile defense priority. Nagasaki Prefecture hosts Mitsubishi Heavy Industries' seeker and guidance system manufacturing for joint U.S.-Japan development programs.
Israel
Multi-layered rocket and missile defense against short-range threats sustains Iron Dome, David's Sling, and Arrow system production. The country's national defense regulator certifies interceptors for both domestic deployment and export to NATO-aligned customers. Haifa's Rafael Advanced Defense Systems facilities specialize in hit-to-kill seekers and command-and-control integration for tiered defense architectures.
Poland
Eastern flank NATO positioning drives Europe's largest interceptor procurement expansion through Wisla and Narew layered defense programs. CE marking and NATO standardization office requirements shape certification timelines for U.S. and European suppliers. Warsaw's defense industrial zone concentrates Patriot battery integration and wheeled launcher manufacturing for rapid repositioning capabilities.
Australia
Trilateral security frameworks with the U.S. and Japan accelerate hypersonic tracking and sea-based interceptor investments under the Guided Weapons and Explosive Ordnance Enterprise. TGA-equivalent defense certification protocols align with U.S. Missile Defense Agency standards for joint development programs. South Australia's Osborne Naval Shipyard hosts Aegis combat system integration for Hobart-class destroyer missile defense upgrades.
Global Missile Interceptor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the missile interceptor market. Tier-one defense primes leverage multi-domain integration capabilities and decades-long sustainment relationships with national procurement agencies. Strategic archetypes include: vertically integrated system integrators commanding prime contractor roles; sensor and radar specialists feeding targeting data into interceptor networks; and niche seeker and kill vehicle developers. Competitive moves concentrate on modular open-system architecture adoption and directed-energy technology partnerships.
Within the vertically integrated tier, Lockheed Martin Corporation and RTX Corporation exemplify prime contractor archetypes with proven multi-domain track records. MBDA occupies a position representing European theater defense specialization and naval point-protection system development. These three entities anchor competitive positioning across the Atlantic and Indo-Pacific procurement theaters.
| Leading Market Players |
|---|
| Rafael Advanced Defense Systems Ltd. |
| Boeing Defense, Space & Security |
| Lockheed Martin Corporation |
| Israel Aerospace Industries |
| MBDA |
| RTX Corporation |
| BAE Systems plc |
| Thales Group |
| Northrop Grumman Corporation |
| Others |
Supply & Pricing Matrix
Rare earth oxide price indices for neodymium and dysprosium cascade through missile interceptor supply chains into three-tier pricing structures across premium, standard, and economy levels. Defense ministries with multi-decade sustainment contracts absorb volatility through cost-plus mechanisms, while Indo-Pacific procurement offices face spot-market exposure on magnet assemblies.
Pricing Analysis
Margin tightening in solid-propellant booster tiers reflects REACH chemical registration compliance costs and reformulation R&D. Contract-based long-term offtake dominates prime contractor relationships, with price differentiation resting on ITAR certification tier and volume scale. Cost-down pressure on seeker electronics accelerates as dual-use commercial sensor vendors enter the supplier base. Naval command buyers exhibit lowest price sensitivity due to mission-critical requirements; emerging European NATO members show highest sensitivity amid budget fragmentation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from U.S. Missile Defense Agency and Japan's Ministry of Defense, bypassing distributor markups on all-up-round contracts. Manufacturing concentrates in the United States, Israel, and Germany, with precision guidance magnet production drawing from Chinese rare earth processing infrastructure. Solid-propellant formulations, infrared seeker arrays, and exo-atmospheric kill vehicle divert thrusters constitute critical component dependencies. Single-source vulnerability in neodymium supply creates exposure to export restriction shocks. Distribution runs through national armament directorates with ITAR-controlled logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interceptor kill vehicle production capacity constrains supply response to accelerated Indo-Pacific procurement timelines, propping pricing power for qualified suppliers. This scarcity dynamic favors incumbents with certified manufacturing lines and multi-year backlog visibility.
For Market Incumbents: Acquire directed-energy subsystem specialists to hedge against kinetic booster replacement cycles. Lockheed Martin and RTX Corporation should deepen backward integration into solid-state laser component supply to capture margin from emerging naval point-defense demand. Defensive patent clustering around multi-spectral seeker algorithms blocks emerging entrant access to exo-atmospheric discrimination technology. For New Entrants and Emerging Players: Poland's Wisla and Narew program expansion represents an underserved buyer archetype seeking non-U.S. prime contractor alternatives for layered defense architectures. White-space entry points concentrate in wheeled mobile launcher platforms and seeker refurbishment services for legacy Patriot batteries. Go-to-market positioning through NATO standardization office certification accelerates access to eastern flank procurement pipelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor tier-two seeker and guidance electronics specialists in Israel and South Korea amid defense budget reallocation toward hypersonic tracking capabilities. Long-term viability hinges on space-based sensor layer integration credentials and trilateral U.S.-Japan-Australia joint development participation. Watch for U.S. Missile Defense Agency technology refresh mandate acceleration as inflection signal for directed-energy capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Directed-Energy Partnership Formation | Lockheed Martin's Layered Laser Defense collaboration with U.S. Navy compresses deployment timelines against cruise missile threats. |
| Multi-Domain Integration Certification | RTX Corporation's NATO IAMD command-and-control compatibility investment secures prime contractor positioning across European theater architectures. |
| Rare Earth Magnet Backward Integration | Northrop Grumman's Australian rare earth processing joint venture with Lynas Corporation reduces Chinese supply dependency for precision guidance. |
| All-Up-Round Contracting Adoption | Australia's Guided Weapons and Explosive Ordnance Enterprise mandates shift integration risk to primes, consolidating supplier accountability. |
| Hypersonic Tracking Capability Acquisition | MBDA's space-based sensor layer investment with European Space Agency addresses boost-phase engagement windows before glide vehicle deployment. |
Research Methodology
Document review covered U.S. Missile Defense Agency budget justifications, NATO standardization office certification records, and Japanese Ministry of Defense procurement white papers, complemented by interviews with interceptor program executives, radar systems integration leads, and defense ministry acquisition officers. Secondary validation drew from SEC 10-K filings of tier-one primes, FAA and DoD interoperability standards documentation, and REACH chemical registration databases. Bottom-up build from individual program commitments and top-down cross-check against national defense expenditure aggregates ensured triangulation integrity.
Unit cost and procurement volume outputs across the analysis window reflect segment-level modeling of ground-based, sea-based, and directed-energy technology tiers. Segmentation dimensions included interceptor deployment mode, engagement technology maturity, threat velocity application, and end-user procurement authority. CAGRs derived from defense budget trajectory correlation with threat perception indices and joint development funding announcements. Industry-specific inputs encompassed hypersonic glide vehicle deployment timelines and solid-state laser power scaling curves.
Revisions become necessary when U.S. congressional appropriation delays, NATO collective defense spending reallocations, or directed-energy technical breakthroughs materialize outside modeled assumptions. Forecasts reflect documented procurement timelines and certification gate milestones. Practitioners should monitor U.S. Indo-Pacific Command distributed maritime operations doctrine evolution and Japan's defense spending GDP ratio execution for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Americas Air Defense Systems Market
Air Defense
Airborne Fire Control Radar Market
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Europe Air Defense Systems Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market