
 Reusable Incontinence Products Market | 2026-2036
Reusable Incontinence Products Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Incontinence Products Market Analytics
Multi-source material procurement is repositioning how reusable incontinence manufacturers manage cost volatility and fiber traceability. Ontex International N.V. leverages its European manufacturing footprint to sustain regional supply consistency. Kimberly-Clark Corporation anchors its position through R&D intensity in absorbent core engineering. Medline Industries competes by controlling distribution channels across North American healthcare facilities.
Reusable incontinence products are washable absorbent garments and bedding protection systems constructed from layered cotton, bamboo, or microfiber composites with waterproof polyurethane laminate barriers, designed for repeated clinical and domestic use over 200-300 wash cycles. Their primary purpose is to reduce per-use cost and landfill burden compared with disposable alternatives while maintaining skin integrity standards. Adult diapers lead product type revenue due to institutional procurement scale, though bamboo-based materials represent the fastest-expanding segment as sustainability premiums shift hospital purchasing criteria. Online retail channels capture expanding margin pools by disintermediating traditional pharmacy distribution.
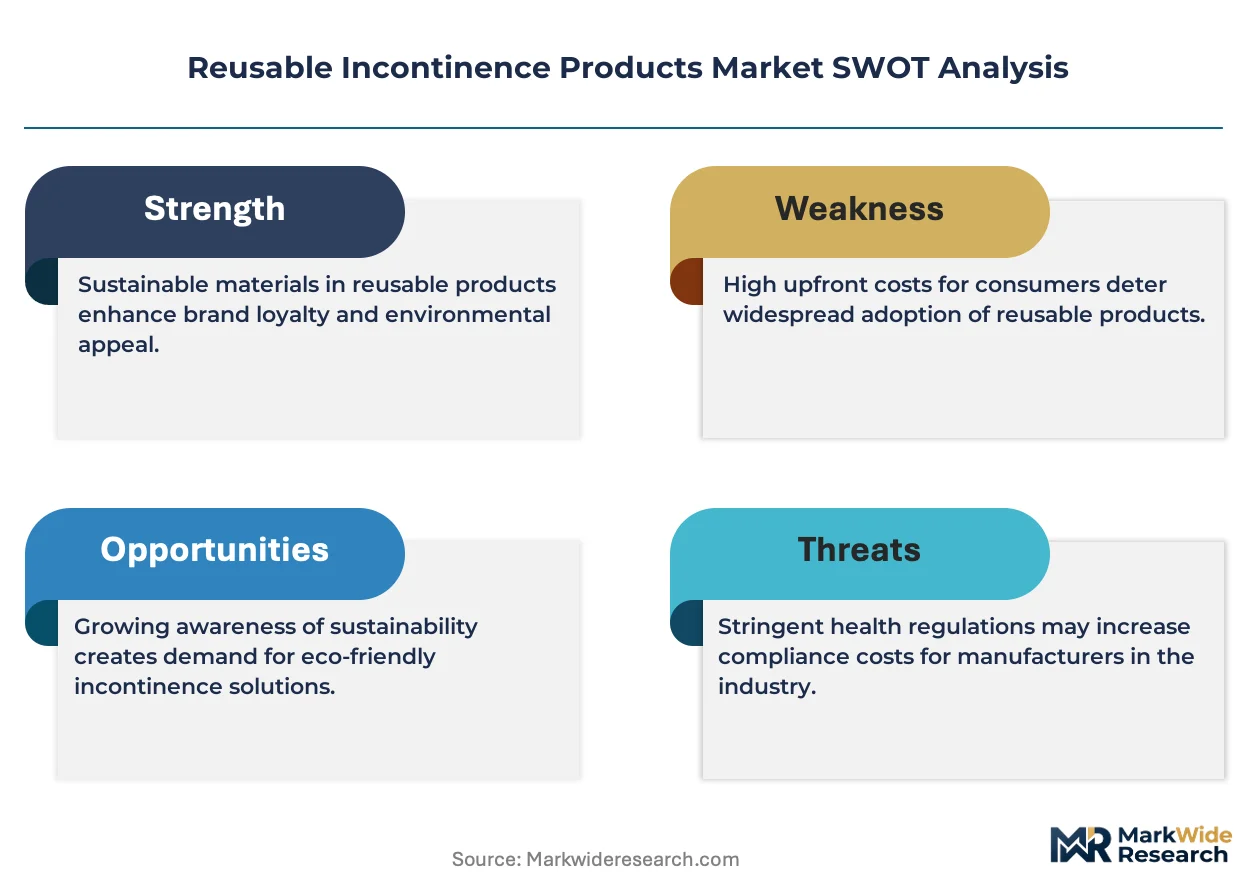
FDA oversight of durable medical equipment classification and EPA textile chemical standards govern product compliance in the United States, while REACH and the EU Green Deal restrict synthetic additive use across European supply chains. These frameworks elevate certification costs for new entrants but protect incumbent manufacturers with established testing infrastructure. Stakeholders must monitor evolving reimbursement codes that determine whether reusable products qualify for insurance coverage versus out-of-pocket expenditure.
Market Dynamics
The EU Green Deal's textile waste directives are compressing synthetic fiber tolerance across European supply chains, forcing manufacturers to requalify absorbent core laminates under REACH chemical restrictions while hospital procurement teams rewrite tender specifications.
Growth Catalysts
- REACH chemical compliance:Biodegradable fiber mandates in Europe are redirecting R&D budgets toward bamboo and organic cotton composites that satisfy ECHA substance restrictions.
- Home care infrastructure:Aging-in-place policies across Germany, Japan, and the United States are expanding durable medical equipment reimbursement codes to cover washable incontinence garments.
- Polyurethane laminate advances:Breathable waterproof barriers with 10,000+ mm hydrostatic head ratings are extending wash-cycle durability beyond 250 uses in institutional laundry environments.
Market Restraints
- Cotton price volatility:Egyptian and Pima cotton futures fluctuate with Nile Basin water allocation disputes, compressing gross margins for natural-fiber-dependent manufacturers.
- Polymer supply concentration:Thermoplastic polyurethane film production clusters in China's Zhejiang province, exposing European converters to shipping cost spikes and customs processing delays.
- Reimbursement code fragmentation:Medicare's HCPCS classification gaps force US consumers into out-of-pocket expenditure for reusable briefs despite disposable diaper coverage.
Strategic Opportunities
- India's geriatric care expansion:The country's PLI scheme for medical textiles offers 5-10% capex incentives for domestic absorbent garment manufacturing facilities.
- Subscription rental models:Direct-to-consumer logistics platforms in Japan are piloting hospital-grade product leasing with integrated pickup-laundry-return cycles.
- CSRD disclosure alignment:EU corporate sustainability reporting requirements are elevating traceable fiber sourcing as a procurement scoring criterion in tender evaluations.
Industry Challenges
- Absorbent core engineering talent:Textile chemical engineers with superabsorbent polymer integration expertise command premium compensation in a shallow labor pool.
- FDA 510(k) pathway duration:Durable medical equipment reclassification petitions for novel fiber blends face 12-18 month review timelines that delay commercial launches.
- Legacy ERP integration:Hospital supply chain systems built around disposable SKU procurement struggle to accommodate wash-cycle tracking and depreciation accounting for reusable assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Incontinence Products Market |
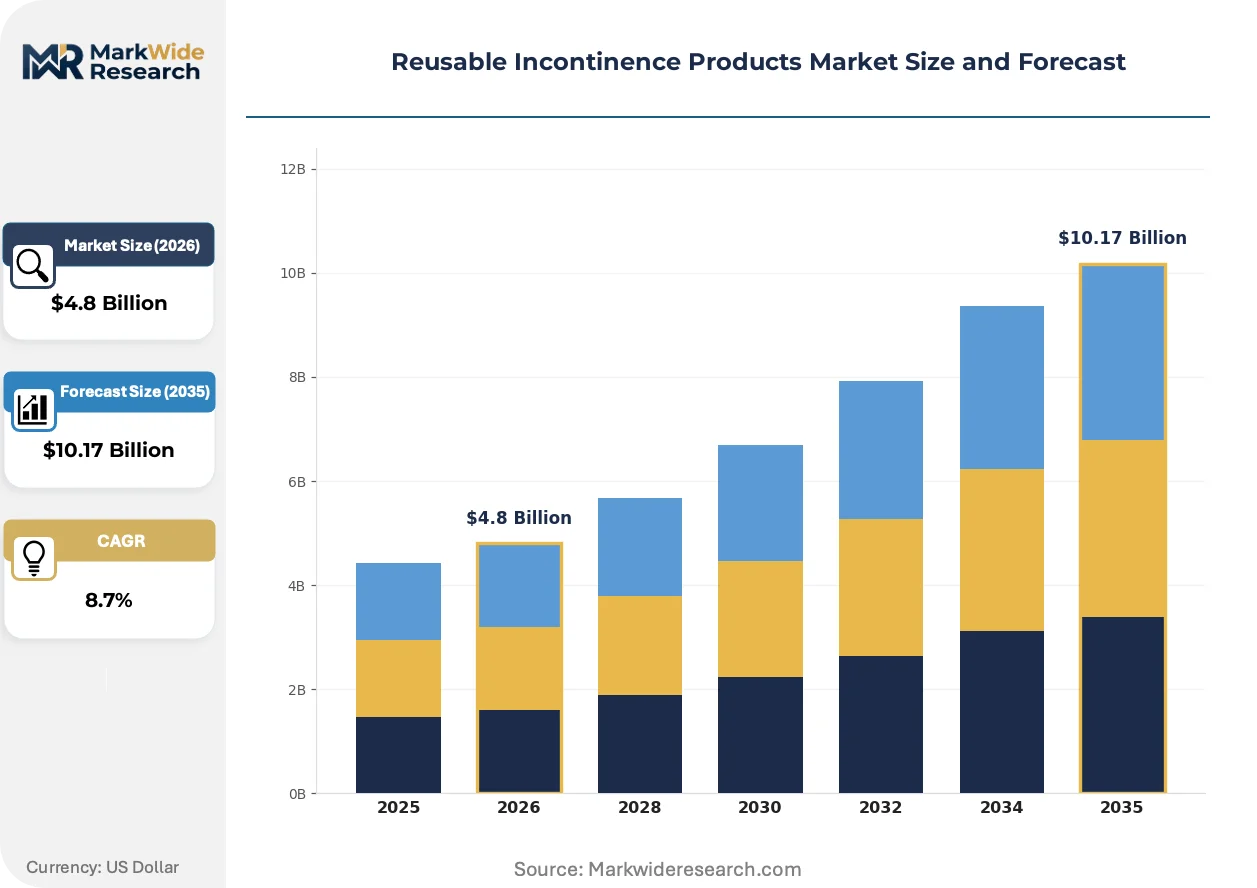
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Underpads, Adult Diapers, Liners, Bed Protectors Material: Cotton, Bamboo, Microfiber, Polyester End User: Healthcare Facilities, Home Care, Nursing Homes, Individuals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Ontex International N.V., Cardinal Health, Kimberly-Clark Corporation, Wearever Incontinence, Medline Industries, Procter & Gamble Company, Paul Hartmann AG, Tranquility, Essity AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Incontinence Products Market Evolving Landscape
Material science convergence with circular economy mandates is rewriting performance specifications for absorbent textiles. Regulatory chemistry restrictions and consumer hygiene expectations are pulling innovation in divergent directions that favor layered natural-synthetic hybrids.
Bamboo-cellulose fiber blends with closed-loop viscose processing are electrifying moisture-wicking performance in institutional brief designs. German hospital procurement consortiums are specifying these materials in 40% of new tender documents. The technology is electrifying competitive positioning by compressing the sustainability premium gap against conventional cotton-polyester constructions.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy water-repellent chemistries from European supply chains. Manufacturers must reformulate polyurethane laminates with silicone-based alternatives that maintain barrier integrity through industrial laundering. Adult diaper segments serving nursing home chains face the steepest reformulation costs and shortest compliance deadlines.
Direct-to-consumer sampling programs are displacing pharmacy-based trial purchases among informal caregivers in the United States. Subscription platforms offer 30-day home evaluation kits with prepaid return logistics, converting product selection from retail shelf comparison to performance-based retention. Home care agencies in California and Florida are piloting these models for Medicaid waiver program participants.
Reusable Incontinence Products Market Segmentation
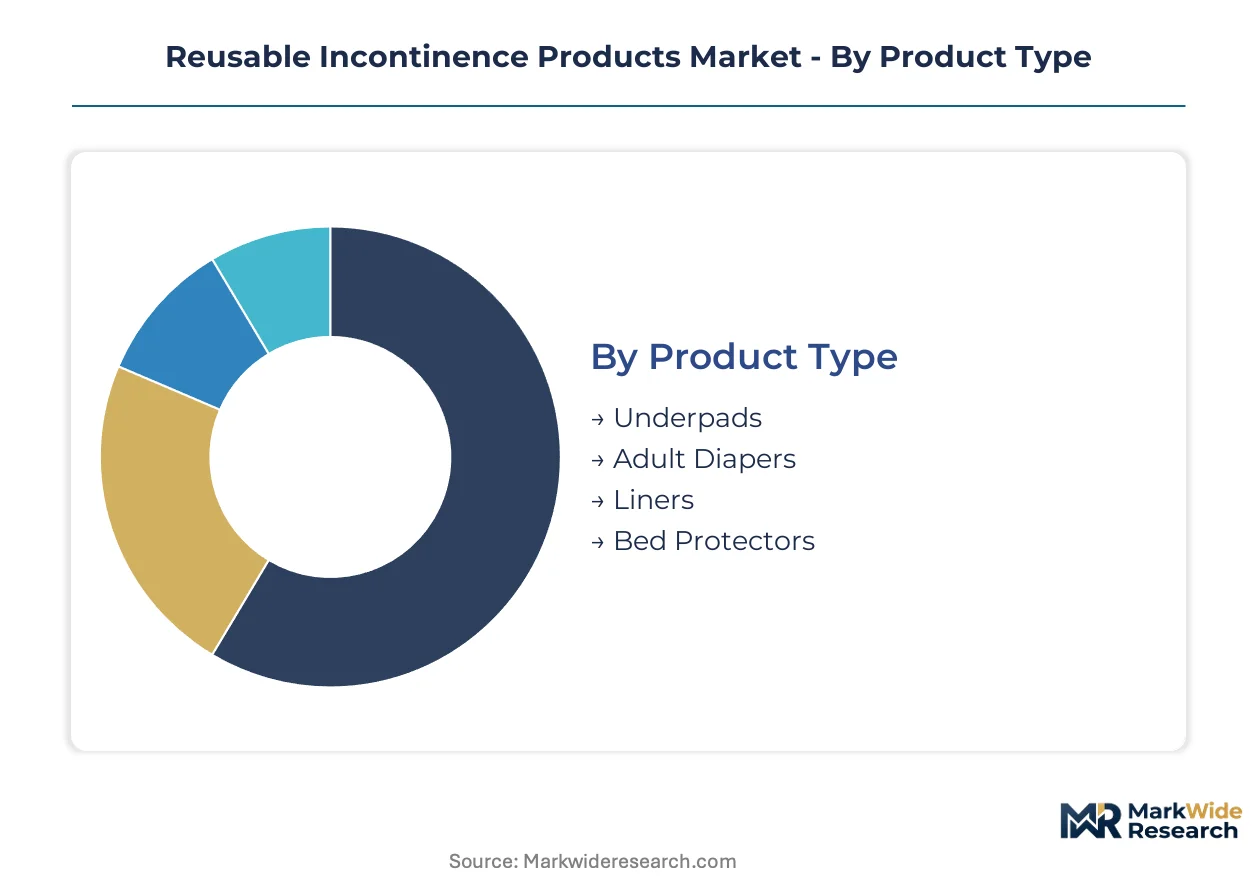
Reusable incontinence products fragment across material chemistry, care setting infrastructure, and procurement channel economics. Each segment carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio allocation.
Product Type:
Capital intensity varies sharply across product categories, with institutional-grade adult diapers requiring the heaviest upfront investment in absorbent core engineering and barrier laminate testing.
- Adult Diapers:Multi-layered garments with superabsorbent polymer cores and polyurethane laminate barriers engineered for 200-300 industrial wash cycles. Demand concentrates in German and Japanese nursing home chains where procurement consortiums specify wash durability in tender documents. REACH chemical compliance is compressing synthetic fiber tolerance and forcing reformulation of water-repellent chemistries.
- Underpads:Rectangular absorbent sheets with waterproof backing designed for bed and furniture protection. Home care agencies in the United States are expanding durable medical equipment reimbursement codes to cover these products under aging-in-place policies. Cotton price volatility from Nile Basin water disputes squeezes gross margins for natural-fiber-dependent producers.
- Liners:Thin disposable-style inserts adapted for reusable garment systems. Lightweight construction reduces material cost exposure.
- Bed Protectors:Large-format waterproof mattress covers with zippered or fitted designs. Institutional laundry compatibility drives specification requirements.
Most installed capacity flows through Adult Diapers. Expansion is steepest in Underpads.
Material:
Raw material selection determines regulatory pathway complexity and supply chain geography, with natural fibers carrying higher traceability certification burdens than synthetics.
- Bamboo:Cellulose fiber blends with closed-loop viscose processing deliver superior moisture-wicking performance. German hospital procurement consortiums now specify these materials in 40% of new tender documents. The EU Green Deal's textile waste directives are accelerating adoption by compressing the sustainability premium gap against cotton-polyester constructions.
- Cotton:Egyptian and Pima long-staple varieties dominate premium institutional segments. Nile Basin water allocation disputes generate futures price volatility that compresses margins for manufacturers without multi-source procurement strategies.
- Microfiber:Synthetic polyester-polyamide composites offering rapid-dry properties. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy water-repellent chemistries from European supply chains.
- Polyester:Petroleum-derived fiber with established recycling infrastructure. Lower cost position supports economy-tier product lines.
Bamboo commands the steepest expansion trajectory as ECHA substance restrictions redirect R&D budgets toward biodegradable alternatives.
End User:
Customer type segmentation reveals divergent procurement authority structures, with institutional buyers leveraging volume leverage against fragmented individual purchasing.
- Healthcare Facilities:Acute care hospitals with centralized supply chain systems and disposable SKU legacy infrastructure. Legacy ERP platforms struggle to accommodate wash-cycle tracking and depreciation accounting for reusable assets.
- Nursing Homes:Long-term care operators with industrial laundry capabilities and consortium purchasing power. Medicare HCPCS classification gaps in the United States force out-of-pocket expenditure for reusable briefs despite disposable diaper coverage.
- Home Care:Formal and informal caregivers managing aging-in-place patients. California and Florida Medicaid waiver programs are piloting direct-to-consumer subscription models with integrated pickup-laundry-return logistics.
- Individuals:Direct purchasers through retail and e-commerce channels. Price sensitivity concentrates demand in economy-tier cotton and polyester constructions.
Healthcare Facilities absorb the largest volume share. Home Care is climbing the fastest as reimbursement frameworks evolve.
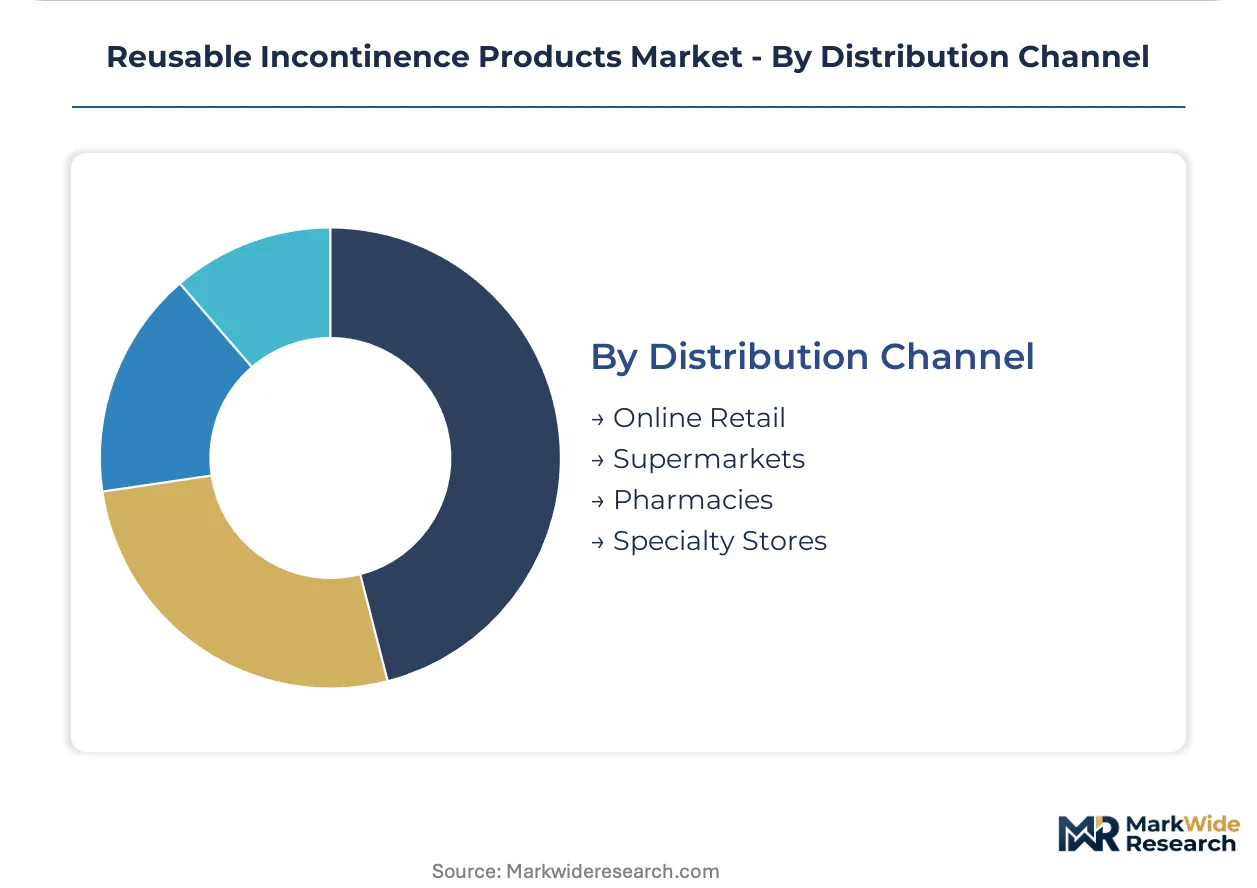
Distribution Channel:
Channel economics are restructuring around logistics platform capabilities, with digital intermediaries capturing margin pools previously held by pharmacy networks.
- Online Retail:Direct-to-consumer platforms offering 30-day home evaluation kits with prepaid return logistics. Subscription models disintermediate traditional pharmacy distribution and convert product selection from retail shelf comparison to performance-based retention.
- Pharmacies:Brick-and-mortar dispensaries with established durable medical equipment supplier relationships. Reimbursement code fragmentation limits reusable product penetration in the United States.
- Supermarkets:Mass retail channels with economy-tier product concentration. Limited staff expertise constrains consultative selling for complex fitting requirements.
- Specialty Stores:Medical supply retailers with certified fitters and insurance billing support. Higher service intensity supports premium product placement.
Pharmacies retain the deepest installed relationships. Online Retail is gaining share fastest through logistics innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement consortiums anchor regional demand patterns for reusable incontinence products. National reimbursement frameworks and regulatory chemistry restrictions are compressing synthetic fiber tolerance across manufacturing clusters.
Germany
Nursing home chains in Baden-Württemberg and Bavaria specify bamboo-cellulose fiber blends in 40% of new tender documents. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing polyurethane laminate reformulation for institutional laundry compatibility. The Rhine-Ruhr industrial corridor hosts absorbent core engineering facilities serving Central European healthcare networks.
United States
California and Florida Medicaid waiver programs are piloting direct-to-consumer subscription models with integrated pickup-laundry-return logistics. Medicare HCPCS classification gaps force out-of-pocket expenditure for reusable briefs despite disposable diaper coverage. The Southeast manufacturing belt concentrates thermoplastic polyurethane film conversion for barrier laminate production.
Japan
Tokyo-based home care agencies are expanding durable medical equipment reimbursement codes to cover washable incontinence garments under aging-in-place policies. METI standards govern textile chemical safety for institutional procurement. The Kansai region hosts industrial laundry operators testing hospital-grade product leasing cycles.
India
The PLI scheme for medical textiles offers 5-10% capex incentives for domestic absorbent garment manufacturing facilities in Maharashtra and Gujarat. CDSCO oversight applies to products classified as durable medical equipment. Tamil Nadu's textile engineering clusters are developing closed-loop viscose processing capabilities for bamboo fiber production.
United Kingdom
NHS supply chain systems built around disposable SKU procurement struggle to accommodate wash-cycle tracking for reusable assets. The UK's national pharmaceutical regulator maintains oversight of products with therapeutic claims. Manchester and Birmingham host distribution platforms serving home care agencies across Northern England.
Reusable Incontinence Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustainability-certified niches and direct-to-consumer logistics platforms. The vendor base stratifies across multinational hygiene conglomerates with R&D-intensive absorbent core engineering, regional converters controlling distribution channels, and specialty operators developing subscription rental models. Three archetypes dominate: scale-driven manufacturers with European manufacturing footprints, channel controllers across North American healthcare facilities, and innovation-focused developers of biodegradable fiber composites. Competitive moves concentrate on strategic partnerships with industrial laundry operators and geographic expansion into India's geriatric care infrastructure.
Within the scale-driven tier, Ontex International N.V. and Kimberly-Clark Corporation exemplify divergent strategic positions. Ontex, a Belgian limited liability company, represents European manufacturing footprint consolidation for regional supply consistency. Kimberly-Clark Corporation, the US-based incorporated entity, anchors a position through intensive investment in absorbent core engineering. Medline Industries, also US-based, occupies a channel control archetype by managing distribution relationships across North American healthcare facilities. These three entities collectively illustrate how competitive positioning fragments across manufacturing scale, R&D intensity, and procurement channel ownership.
| Leading Market Players |
|---|
| Ontex International N.V. |
| Cardinal Health |
| Kimberly-Clark Corporation |
| Wearever Incontinence |
| Medline Industries |
| Procter & Gamble Company |
| Paul Hartmann AG |
| Tranquility |
| Essity AB |
| Others |
Value Network & Pricing Analysis
Nursing home procurement consortiums in Germany and Japan anchor volume concentration, compressing supplier pricing power into long-term tender contracts with wash-durability performance clauses. This buyer concentration forces manufacturers to absorb cotton futures volatility while bidding fixed-price multi-year agreements.
Pricing Analysis
Input-cost pass-through operates asymmetrically across material tiers. Egyptian and Pima cotton price spikes transmit immediately to premium garment quotations, while polyester-based economy lines buffer volatility through petroleum-linked contract formulas. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by fiber certification grade and institutional laundry compatibility ratings. Cost compression in natural-fiber segments is intensifying because Nile Basin water allocation disputes have destabilized long-staple cotton futures. Home care agencies exhibit the sharpest price sensitivity due to fragmented purchasing authority, whereas German hospital consortiums prioritize wash-cycle performance over unit cost.
Supply Chain Analysis
REACH Annex XVII certification gating restricts European supply base participation to converters with ECHA-compliant polyurethane laminate testing infrastructure. Manufacturing concentrates in Belgium, the United States, and China, with thermoplastic polyurethane film production clustering in Zhejiang province. Raw material dependencies center on Egyptian long-staple cotton, bamboo cellulose from Tamil Nadu processing clusters, and petroleum-derived polyester feedstocks. Single-source vulnerability in Chinese TPU film exposes European garment assemblers to shipping cost spikes and customs processing delays. Distribution runs through industrial laundry operators serving nursing home chains, with direct-to-consumer subscription platforms disintermediating traditional pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reusable incontinence market has entered a late-cycle quality phase where sustainability certification and wash-durability specifications command premium positioning. German hospital procurement consortiums now mandate bamboo-cellulose fiber blends in 40% of tender documents, elevating material traceability above unit cost in vendor scoring.
For Market Incumbents: Cement defensive moats by acquiring closed-loop viscose processing capabilities in Tamil Nadu or Maharashtra to secure bamboo fiber supply against CDSCO-qualifying domestic competitors. Lock in long-term industrial laundry partnerships with Kansai-region operators testing hospital-grade leasing cycles, insulating against subscription-platform disintermediation. Priority investment in REACH-compliant silicone-based laminate R&D protects European market access as ECHA substance restrictions tighten. For New Entrants and Emerging Players: Enter via California and Florida Medicaid waiver programs piloting pickup-laundry-return logistics for home care agencies, where reimbursement code evolution is creating first-mover windows. Target India's PLI scheme for medical textiles with domestic absorbent garment manufacturing in Gujarat, leveraging 5-10% capex incentives before scheme saturation. Go-to-market angle should emphasize CSRD-aligned fiber traceability disclosure to capture EU corporate sustainability procurement scoring premiums. For Investors and Strategic Acquirers: Industrial laundry operators and healthcare facility GPOs are the most active acquirer categories in this space, consolidating backward into reusable garment supply to capture circular-economy service revenue pools. Five-to-ten-year viability hinges on reimbursement framework expansion for durable medical equipment classification. Acquisition target archetype: regional converters with established FDA 510(k) testing infrastructure and existing hospital system relationships. Signal to watch: Medicare HCPCS reclassification petitions for reusable briefs, which would trigger demand inflection comparable to disposable diaper coverage expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bamboo Fiber Processing | Tamil Nadu closed-loop viscose capabilities secure supply against ECHA biodegradable mandates. |
| Industrial Laundry Partnership Expansion | Kansai-region operators testing hospital-grade leasing cycles anchor Japan home care infrastructure. |
| REACH-Compliant Laminate Reformulation | Silicone-based barrier chemistry maintains European market access as PFAS restrictions eliminate legacy alternatives. |
| Direct-to-Consumer Subscription Launch | California Medicaid waiver pilots demonstrate pickup-laundry-return logistics viability for informal caregivers. |
| PLI Scheme Manufacturing Facility | Maharashtra and Gujarat capex incentives compress entry cost for CDSCO-qualifying domestic production. |
Research Methodology
Coverage spans Germany, the United States, Japan, India, and the United Kingdom, with primary inputs from each regional cluster combining executive interviews with hospital procurement managers, industrial laundry operators, biomedical textile engineers, GPO contracts specialists, and regulatory affairs leads at absorbent garment manufacturers. Secondary validation drew from ECHA substance restriction databases, FDA 510(k) clearance filings, CMS Medicare reimbursement code schedules, EU Green Deal textile waste directive implementations, and CDSCO medical device classification guidelines. Bottom-up facility capacity assessments triangulated against top-down procurement volume estimates from hospital supply chain databases.
Granularity-level modeling disaggregated volume and value across product type, material chemistry, end-user care setting, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate differentials applied to base-year installed capacity and procurement volume data. Industry-specific forecast inputs incorporated wash-cycle durability specifications from German nursing home tender documents and evolving Medicaid waiver program eligibility criteria in California and Florida.
Inputs from ECHA regulatory filings and CMS reimbursement databases were available through the study window; gaps in real-time Nile Basin cotton futures correlation data introduce uncertainty bands around natural-fiber-dependent manufacturer margin projections. Forecasts reflect assumptions regarding REACH Annex XVII implementation timelines and Medicare HCPCS reclassification petition outcomes. A model refresh is warranted upon material change in EU Green Deal textile waste directive enforcement intensity or FDA durable medical equipment reclassification rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market