
 Poppy Seed Market | 2026-2036
Poppy Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Poppy Seed Market Analysis
A capital-intensity divergence between integrated processors and commodity traders is unwinding competitive stability in poppy seed supply chains. Frontier Co-op leverages its organic certification infrastructure to command premium shelf placement in North American retail channels. Belmar A.S anchors Central European supply through direct contracting with Polish and Czech agricultural cooperatives. Bata Food competes on volume throughput from Turkish and Balkan origination points, sustaining margin through bulk pharmaceutical-grade contracts.
Poppy seeds are the dried, oil-rich reproductive units of Papaver somniferum, typically containing 40–50% lipid content by weight and legally traded only in varieties bred for negligible morphine alkaloid levels below regulatory thresholds. The seeds function primarily as a textural and flavor ingredient in baked goods, condiments, and pressed-oil applications across food manufacturing and culinary service sectors. Whole seeds dominate commercial trade volumes due to extended shelf stability and versatility across baking and cooking applications, while oil extraction commands higher unit margins from pharmaceutical and cosmetics buyers. Pharmaceutical applications represent the fastest-expanding segment as manufacturers seek natural-source lipid compounds for topical formulation bases.
EFSA alkaloid limits, USDA organic certification requirements, and FDA import alert protocols collectively shape product standards and cross-border market access for poppy seed suppliers. The EU F-Gas Regulation indirectly pressures oil extraction facilities to adopt lower-emission solvent recovery systems, altering processing economics for European refiners. Stakeholders must monitor alkaloid testing protocol harmonization between European and North American regulators, as divergent enforcement thresholds threaten to fragment qualified supplier pools and redirect trade flows toward jurisdictions with clearer compliance pathways.
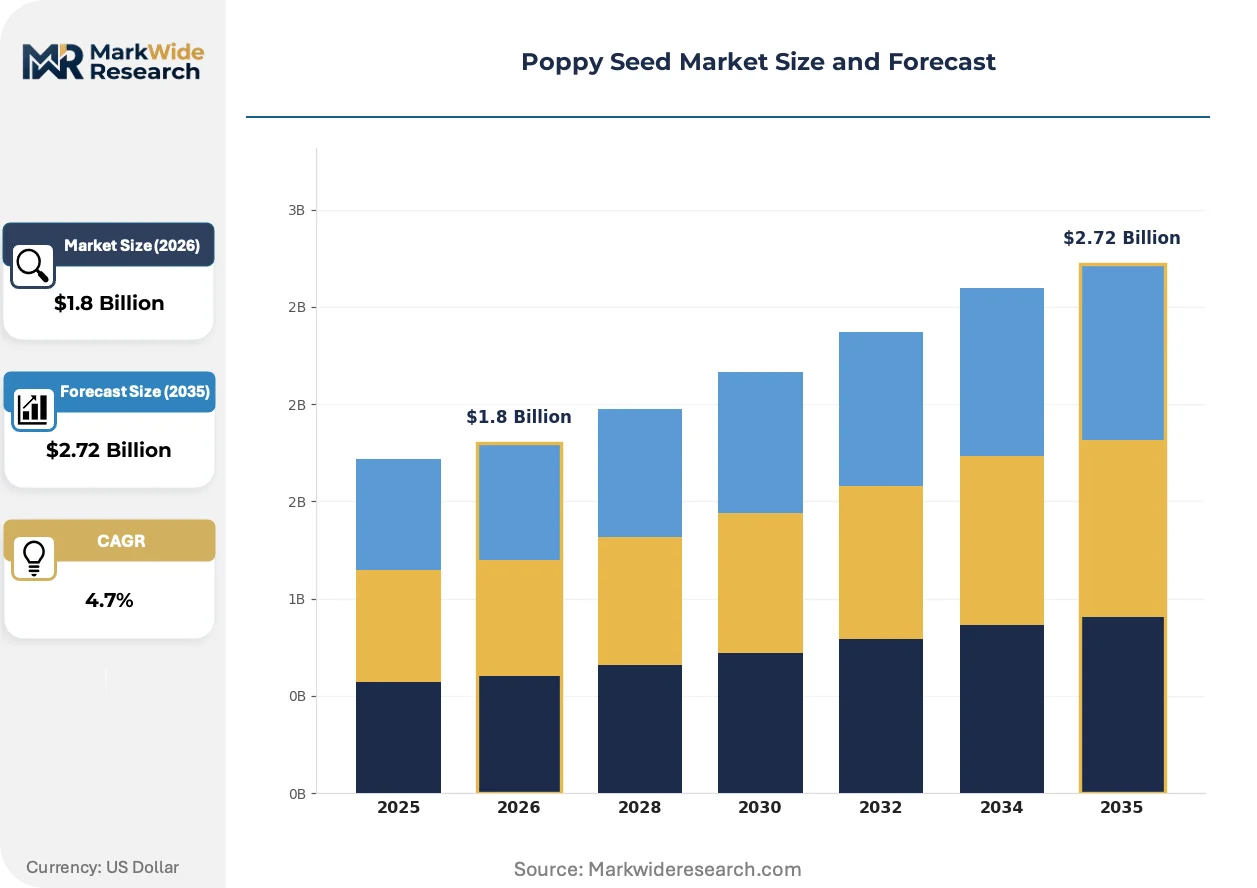
Market Dynamics
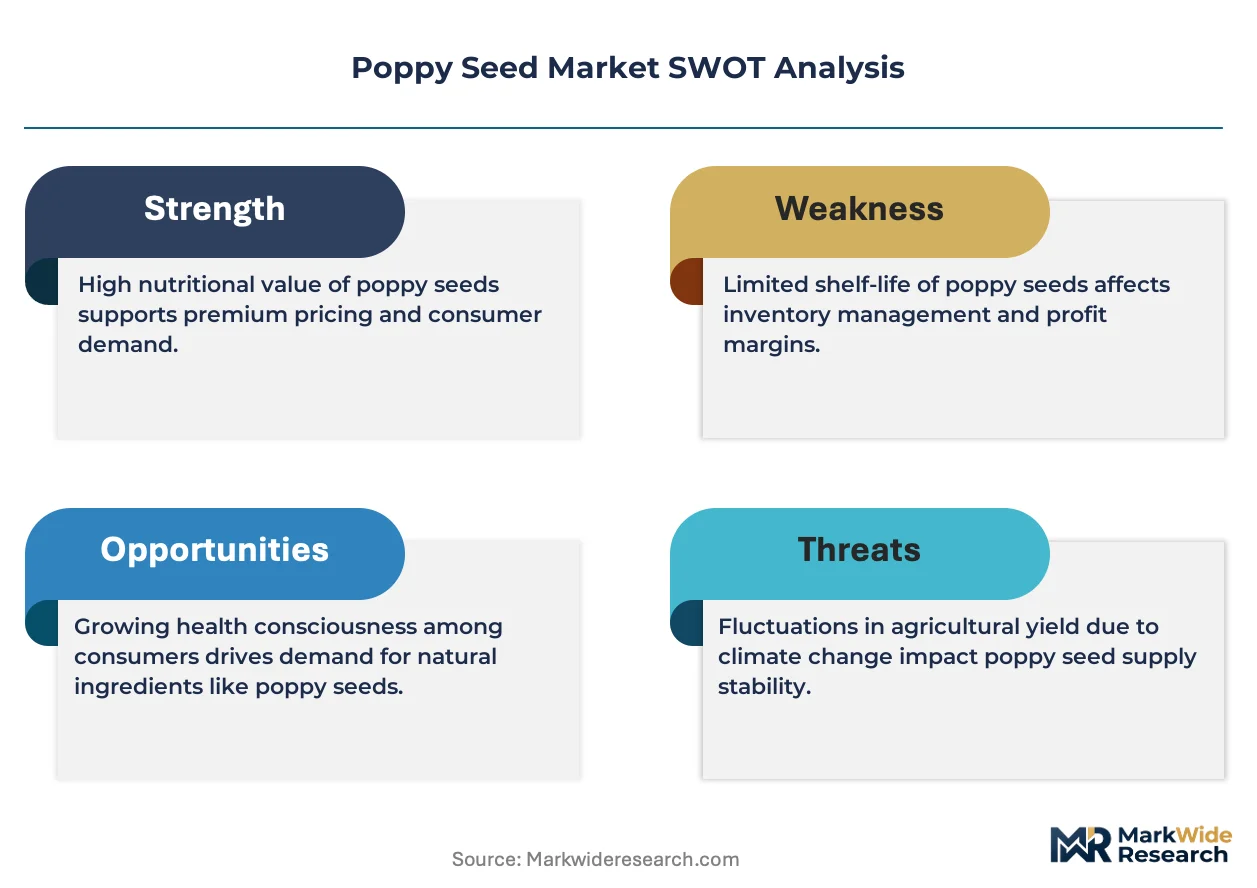
EFSA alkaloid thresholds and USDA organic certification requirements are compressing supplier pools while redirecting trade flows toward jurisdictions with established testing infrastructure and clearer compliance pathways.
Growth Catalysts
- Pharmaceutical-grade lipid demand:Cosmetics and topical formulation manufacturers seek natural-source lipid bases, expanding addressable volume beyond food applications into higher-margin pharmaceutical contracts.
- German bakery tradition:Sustained per-capita consumption of poppy seed pastries and fillings maintains baseline demand stability regardless of export volatility.
- REACH-compliant solvent recovery:EU F-Gas Regulation mandates lower-emission extraction systems, advantaging processors who invested in closed-loop refining technology ahead of enforcement timelines.
Market Restraints
- Input cost volatility:Turkish and Balkan origination points face weather-driven yield fluctuation, transmitting price instability through bulk commodity contracts.
- Supply concentration risk:Polish and Czech agricultural cooperatives control disproportionate share of EU-qualified seed stock, creating single-source vulnerability for integrated processors.
- Regulatory friction:Divergent FDA import alert protocols and EFSA testing methodologies fragment qualified supplier pools and inflate cross-border compliance overhead.
Strategic Opportunities
- Underpenetrated North American retail:Organic certification infrastructure gaps in US and Canadian channels create first-mover advantage for certified suppliers securing premium shelf placement.
- Cosmeceutical convergence:Cold-pressed poppy seed oil meets dual demand for clean-label emollients and sustainable sourcing credentials in prestige skincare formulations.
- Direct-to-bakery distribution:Bypassing commodity traders to contract directly with artisan and industrial bakeries captures margin currently absorbed by intermediaries.
Industry Challenges
- Alkaloid testing standardization:Harmonization delays between European and North American protocols force suppliers to maintain dual certification tracks, extending compliance timelines and inflating quality assurance headcount.
- Legacy extraction equipment retrofit:EU F-Gas Regulation compliance requires capital-intensive solvent recovery system upgrades, straining mid-scale refiners without captive pharmaceutical-grade contract revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poppy Seed Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Ground Seeds, Oil, Extract Application: Baking, Cooking, Pharmaceuticals, Cosmetics Packaging Type: Bags, Bottles, Tins, Bulk Containers End User: Food Manufacturers, Bakeries, Restaurants, Retailers |
| Companies Covered | Frontier Co op, Olivenation LLC, Belmar A.S, Baker Creek Heirloom Seeds, Probi Spol s.r.o, Woodland Foods Ltd., ITC Ltd., Central Garden and Pet Co., Bata Food, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poppy Seed Market Emerging Trajectories
Cold-press extraction technology, regulatory protocol convergence, and procurement model evolution are simultaneously reshaping competitive positioning and margin architecture across food and pharmaceutical applications.
Supercritical CO2 extraction systems are fragmenting the traditional solvent-based refining landscape. Pharmaceutical and cosmetics manufacturers adopting this technology extract higher-purity lipid fractions without residual solvent contamination. The capital barrier to entry is compressing contract manufacturing margins while enabling smaller-scale processors to compete on quality certification rather than volume throughput.
EU F-Gas Regulation enforcement is tightening solvent recovery requirements for oil extraction facilities. European refiners face accelerated equipment replacement cycles or facility consolidation. German and Czech processors with existing closed-loop infrastructure capture contract flow from competitors facing compliance-driven shutdown risk.
Certification-driven procurement now dominates bakery and pharmaceutical buyer decision frameworks. USDA organic and EFSA-compliant alkaloid documentation function as table stakes rather than differentiators. Polish and German cooperatives with pre-certified stockpiles secure multi-year supply agreements while uncertified traders face channel exclusion.
Poppy Seed Market Segmentation
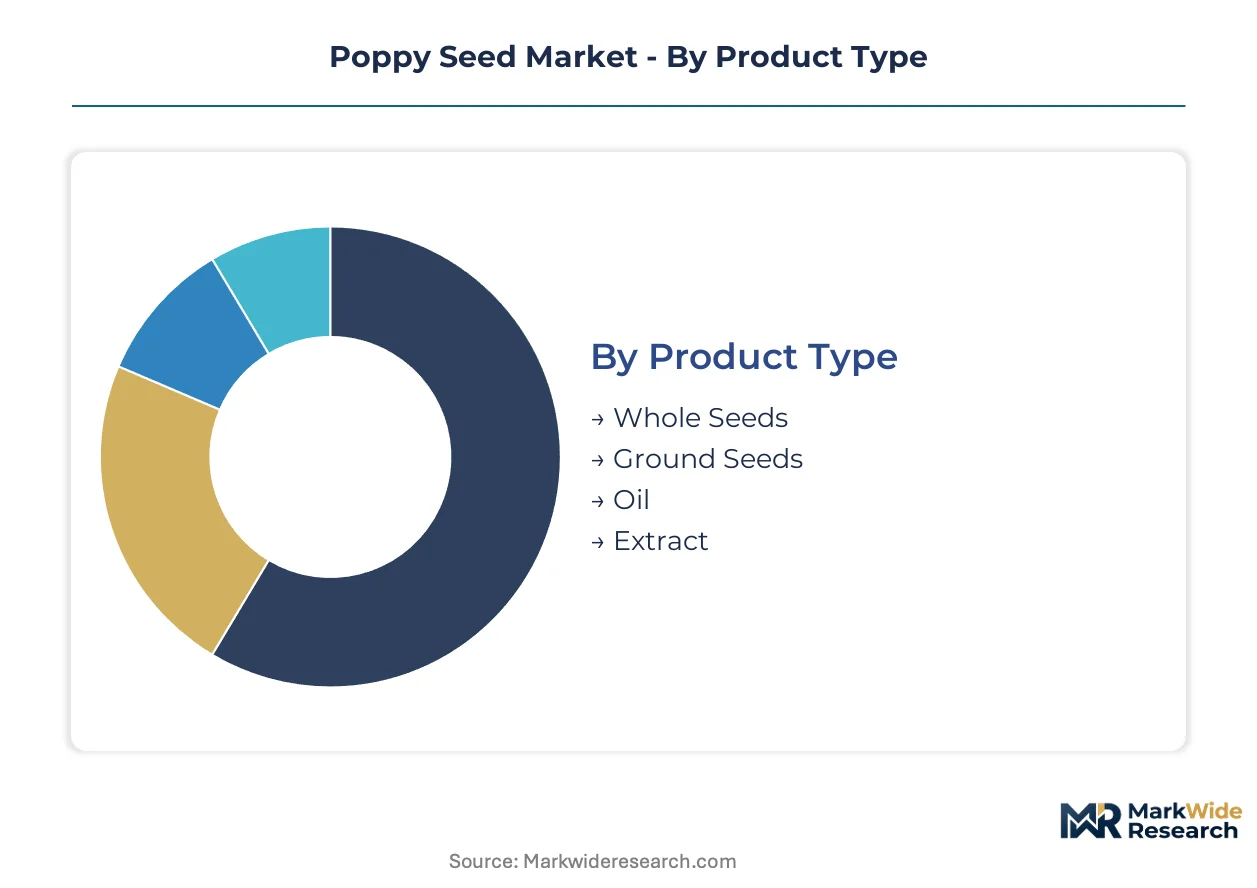
Poppy seed segmentation reveals divergent margin architectures across food and pharmaceutical channels. Channel selection determines certification requirements, pricing power, and regulatory exposure for suppliers navigating EFSA and FDA compliance frameworks.
Product Type:
Channel mix splits sharply between commodity foodservice flows and premium pharmaceutical routes, with processing intensity determining margin capture.
- Whole Seeds:Dried reproductive units retain 40–50% lipid content and achieve extended shelf stability through minimal processing. German and Czech industrial bakeries consume the majority of EU-qualified stock, with per-capita pastry tradition sustaining baseline demand regardless of export volatility.
- Oil:Cold-pressed extraction yields pharmaceutical-grade lipid fractions for topical formulation bases without residual solvent contamination. Cosmetics manufacturers in prestige skincare channels drive the steepest expansion trajectory as clean-label emollient demand accelerates.
- Ground Seeds:Milled product serves condiment and filling applications where texture integration matters. Polish cooperatives dominate supply through direct contracting with regional food manufacturers.
- Extract:Concentrated alkaloid-free fractions target specialized pharmaceutical and nutraceutical formulations. REACH-compliant solvent recovery requirements compress mid-scale refiner participation.
By volume, Whole Seeds leads. By growth pace, Oil is ahead.
Application:
Cost tier stratification separates mass-market food ingredients from specification-driven pharmaceutical contracts, with certification grade determining price realization.
- Baking:Traditional European pastry applications anchor volume demand, with German manufacturers maintaining per-capita consumption stability. EFSA alkaloid thresholds compress supplier pools while redirecting trade toward jurisdictions with established testing infrastructure.
- Pharmaceuticals:Natural-source lipid compounds for topical formulation bases command premium unit economics. Supercritical CO2 extraction technology enables smaller-scale processors to compete on quality certification rather than volume throughput.
- Cooking:Whole and ground seeds function as textural ingredients across Eastern European culinary traditions. Czech and Polish household consumption patterns sustain steady channel flow.
- Cosmetics:Cold-pressed oil meets dual demand for sustainable sourcing credentials and clean-label emollients in prestige skincare. EU F-Gas Regulation enforcement advantages processors with existing closed-loop refining infrastructure.
Baking captures the largest volume share. Pharmaceuticals and Cosmetics together claim the fastest combined expansion rate.
Packaging Type:
Customer type dictates format selection, with institutional buyers prioritizing handling efficiency and retail channels demanding shelf differentiation.
- Bulk Containers:Industrial food manufacturers and pharmaceutical refiners source tonnage quantities through direct contracting. Turkish and Balkan origination points face weather-driven yield fluctuation, transmitting price instability through these commodity contracts.
- Bags:Standard retail and small-scale foodservice packaging dominates North American mass-market distribution. USDA organic certification gaps create first-mover positioning for qualified suppliers.
- Bottles:Premium oil products target cosmeceutical and specialty food channels where provenance signaling matters. German processors with EFSA-compliant documentation secure multi-year supply agreements.
- Tins:Heritage-format packaging serves gift and export markets emphasizing traditional Central European origin narratives. Polish cooperatives leverage pre-certified stockpiles for channel exclusion of uncertified competitors.
Bulk Containers move the greatest tonnage. Bottles achieve the highest unit margin expansion.
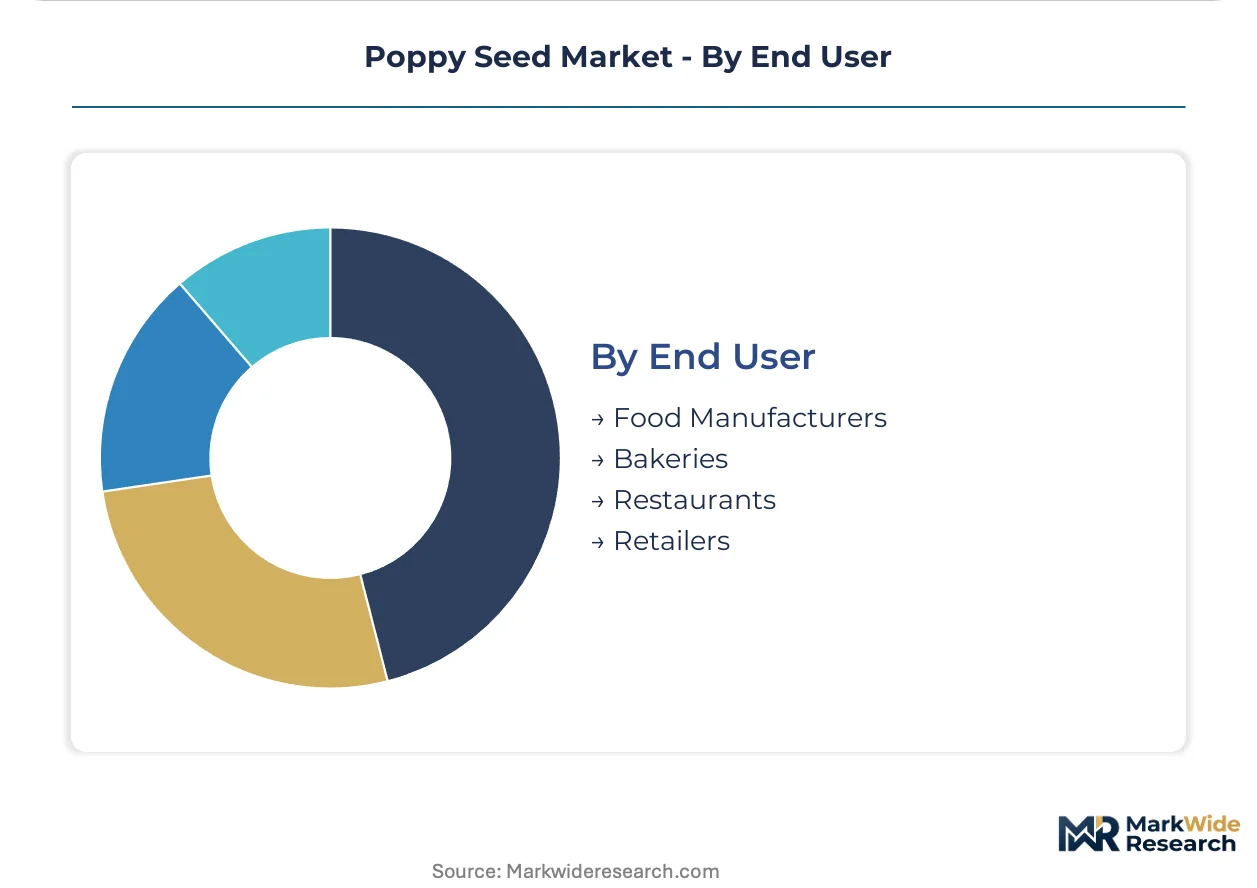
End User:
Supply concentration aligns with geographic clustering of qualified processing capacity, creating single-source vulnerability for integrated buyers.
- Food Manufacturers:Industrial-scale baking and condiment production consumes the majority of EU-qualified whole and ground seed supply. Direct contracting with Polish and Czech agricultural cooperatives bypasses commodity trader margins.
- Retailers:North American organic certification infrastructure gaps create shelf placement advantages for certified suppliers. Frontier Co-op leverages its organic infrastructure to command premium positioning.
- Bakeries:Artisan and industrial operations across Germany, Poland, and the Czech Republic maintain culturally embedded per-capita consumption. Bypassing intermediaries to contract directly captures margin currently absorbed by traders.
- Restaurants:Foodservice channels demand consistent alkaloid documentation for liability protection. Divergent FDA import alert protocols and EFSA testing methodologies inflate cross-border compliance overhead.
Food Manufacturers absorb the largest volume. Retailers present the steepest penetration opportunity in undercertified North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major consuming regions. Germany and Poland maintain structural deficits filled by Czech and Turkish supply, while North American buyers source increasingly from certified organic channels to satisfy retail compliance requirements.
Germany
Industrial bakeries in Bavaria and Baden-Württemberg consume the largest EU-qualified seed volumes for traditional pastry production. EFSA alkaloid thresholds under Regulation (EU) 2015/1958 compress import eligibility to pre-certified origins. The Stuttgart industrial cluster houses multiple mid-scale refiners upgrading solvent recovery systems to meet F-Gas Regulation deadlines.
Poland
Per-capita consumption exceeds all other EU members, with household baking and commercial food manufacturing absorbing steady flows. Direct contracting between agricultural cooperatives and processors bypasses commodity trader margins. The Greater Poland Voivodeship concentration of qualified seed stock creates single-source vulnerability for integrated buyers.
Czech Republic
Domestic consumption patterns mirror Polish demand, with additional export orientation toward German industrial buyers. The country's national agricultural regulator enforces alkaloid testing protocols aligned with EFSA methodologies. South Moravian processing facilities leverage geographic proximity to Austrian and Slovak markets for regional distribution efficiency.
United States
Retail channel expansion outpaces foodservice recovery, with organic certification gaps creating first-mover positioning for qualified suppliers. FDA import alert protocols fragment qualified supplier pools versus European standards. Pacific Northwest and Midwest distribution hubs increasingly bypass East Coast import terminals to reduce cross-border compliance overhead.
Turkey
Balkan and Anatolian origination points supply volume-driven pharmaceutical-grade contracts to European refiners. Weather-driven yield fluctuation transmits price instability through bulk commodity flows. Izmir and Mersin port infrastructure anchors export logistics for Black Sea and Mediterranean trade routes.
Poppy Seed Market Vendor Landscape
Concentration sits with integrated processors controlling certified seed stock and extraction infrastructure. Mid-scale commodity traders face margin compression from alkaloid testing standardization and equipment retrofit requirements. Three archetypes dominate: organic-certified retail specialists, Central European cooperative-anchored processors, and Turkish volume exporters. Competitive moves center on backward integration into agricultural contracting and technology licensing for supercritical extraction systems.
Within the organic-certified tier, Frontier Co-op occupies a position representing retail channel specialization. Among Central European processors, Belmar A.S and Probi Spol s.r.o exemplify cooperative-anchored supply structures. Bata Food sits within the volume-export archetype, anchoring Turkish origination capacity for pharmaceutical-grade contract flows.
| Leading Market Players |
|---|
| Frontier Co op |
| Olivenation LLC |
| Belmar A.S |
| Baker Creek Heirloom Seeds |
| Probi Spol s.r.o |
| Woodland Foods Ltd. |
| ITC Ltd. |
| Central Garden and Pet Co. |
| Bata Food |
| Others |
Supply Flow & Price Mechanics
EFSA alkaloid thresholds and USDA organic certification requirements simultaneously gate supply qualification and price differentiation, compressing supplier pools while enabling certified processors to command premium realizations across food and pharmaceutical channels.
Pricing Analysis
Industrial bakery buyers anchor contract-based long-term offtake structures, with pricing stratifying across EFSA-compliant, USDA organic, and uncertified commodity tiers. Certification grade and volume scale drive price differentiation, with pharmaceutical-grade cold-pressed oil capturing the widest spreads. Cost compression in commodity whole seeds is intensifying because Turkish and Balkan weather volatility transmits through bulk contracts. Artisan bakeries exhibit the highest price sensitivity, while cosmetics manufacturers demonstrate the least due to clean-label emollient specifications.
Supply Chain Analysis
Inventory cycles extend through harvest-season concentration, with Polish and Czech agricultural cooperatives holding disproportionate qualified seed stock. Raw material flows draw from Turkish and Balkan origination points for volume contracts, while German and Czech processors feed from captive cooperative networks. Single-source vulnerability concentrates in Greater Poland Voivodeship qualified stockpiles. Distribution runs through direct contracting between cooperatives and industrial buyers, bypassing commodity trader margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade lipid adoption represents an early-cycle expansion story, with cosmetics manufacturers accelerating clean-label emollient sourcing beyond traditional food applications.
For Market Incumbents: Fortify backward integration into Polish and Czech agricultural cooperatives to secure pre-certified seed stockpiles before EFSA testing protocol harmonization raises compliance barriers. Expand closed-loop solvent recovery capacity to capture contract flow from competitors facing F-Gas Regulation-driven shutdown risk. For New Entrants and Emerging Players: Differentiate on USDA organic certification infrastructure to exploit shelf placement gaps in North American retail channels. Target underpenetrated Pacific Northwest and Midwest distribution hubs with direct-to-bakery distribution models that bypass East Coast import terminal compliance overhead. For Investors and Strategic Acquirers: EFSA-FDA testing protocol harmonization reshapes the acquisition landscape toward processors with dual-certification infrastructure. Over a multi-year horizon, vertically integrated mid-scale refiners with captive pharmaceutical-grade contract revenue present the most resilient acquisition profile. Watch alkaloid testing standardization timelines as the inflection signal for supplier pool compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Cooperatives | Captures margin from commodity traders while securing EFSA-compliant seed stockpiles. |
| Closed-Loop Solvent Recovery Investment | Positions German and Czech processors to absorb contract flow from F-Gas non-compliant competitors. |
| USDA Organic Certification Expansion | Enables first-mover shelf placement in undercertified North American retail channels. |
| Supercritical CO2 Extraction Licensing | Allows smaller-scale processors to compete on pharmaceutical-grade quality certification. |
| Direct-to-Bakery Distribution Buildout | Bypasses intermediary margins in German, Polish, and Czech industrial bakery markets. |
Methodological Framework
Initial hypotheses were tested against primary input from agricultural cooperative managers, pharmaceutical procurement officers, cosmetics formulators, and industrial bakery supply chain directors and refined through secondary validation against EFSA regulatory filings, USDA organic certification databases, customs trade records, and EU F-Gas Regulation enforcement disclosures. Bottom-up volume estimates from processor capacity and cooperative yield data were triangulated against top-down demand projections from end-use consumption patterns.
Variance decomposition across the projection horizon isolates volume drivers by product type, application channel, certification tier, and regional production cluster. CAGRs were derived from segmented growth rate modeling incorporating pharmaceutical-grade lipid demand trajectories, bakery consumption stability indices, and regulatory compliance cost pass-through assumptions.
Forecasts assume regulatory continuity in EFSA alkaloid thresholds and USDA organic protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Quinoa Seed Market
Seeds
Buckwheat Market
Seeds
Rapeseed Market
Seeds
Global Forage Seeds Market
Seeds
Custom Selected Seed Market
Seeds
Myanmar Maize Seed Market
Seeds
Chamomile Seeds Market
Seeds
United States Seed Market
Seeds
Vegetable Seed Protein Market
Seeds
Avena Sativa Market
Seeds
Russia Seed Market
Seeds
Sweet Corn Seeds Market
Seeds
Myanmar Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Nepal Seeds Market