
 Global Egg Processing Market | 2026-2036
Global Egg Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Egg Processing Market Foresight
Specialized pasteurization technicians is rotating toward automated membrane separation lines, easing throughput bottlenecks in high-volume plants. Cal-Maine Foods leverages vertical integration from shell egg production through liquid breaking to control input costs. Rose Acre Farms sustains geographic dominance across the US Southeast with integrated feed-to-break operations. Rembrandt Foods anchors its position through R&D intensity in extended-shelf-life liquid formulations.
Egg processing encompasses the industrial transformation of shell eggs into value-added forms through mechanical breaking, thermal pasteurization, dehydration, and controlled freezing, with liquid whole egg typically standardized to 24-26% solids content for bakery consistency. The primary commercial purpose is to supply food-safe, shelf-stable egg ingredients that eliminate shell handling and reduce microbial risk in industrial kitchens. Liquid eggs leads product type demand due to its direct substitution utility in large-scale bakery and foodservice operations, while spray drying commands technology margins through energy-efficient powder production for nutraceuticals and animal feed. Dried eggs represents the fastest-growing product category as export logistics favor reduced weight and ambient storage.
FDA pasteurization standards and USDA egg safety rules govern US market access, while EU EFSA guidelines and REACH chemical compliance shape formulation and packaging requirements across European food manufacturers. China's SAMR and GB standards enforce domestic safety thresholds that foreign processors must meet for import eligibility. Stakeholders must monitor divergence between regional pathogen reduction protocols and emerging low-temperature pasteurization technologies that promise flavor retention without regulatory grandfathering.
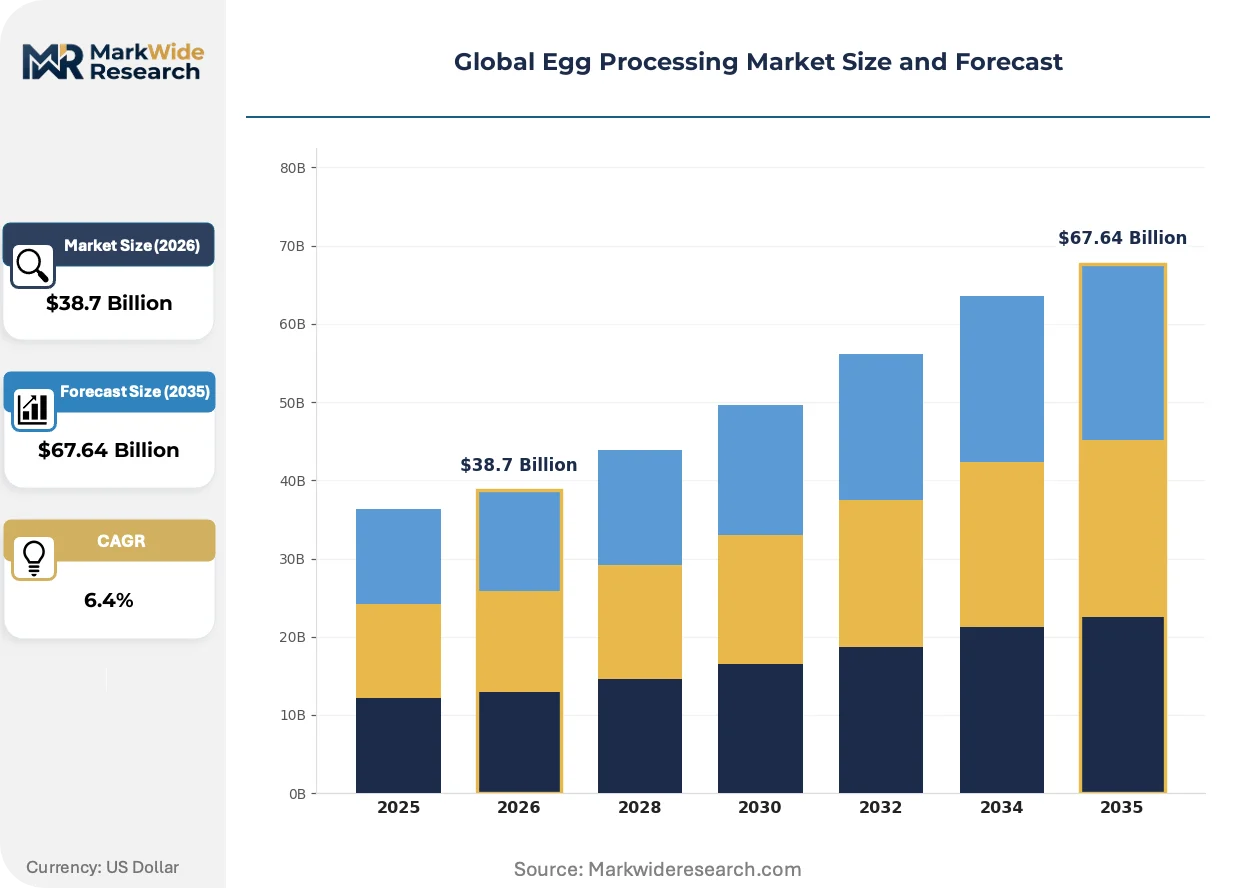
Market Dynamics
EU F-Gas Regulation phase-down schedules are forcing cold-chain equipment retrofits across liquid egg facilities, compressing operating margins while accelerating membrane filtration adoption as an energy-efficient alternative to thermal pasteurization.
Growth Catalysts
- REACH compliance frameworks:European food manufacturers are reformulating packaging materials to eliminate PFAS and other restricted substances, creating demand for compliant barrier films in egg powder and liquid cartons.
- Ready-to-eat food manufacturing:Industrial bakeries and prepared meal producers are substituting shell eggs with pasteurized liquid whole egg to eliminate on-site breaking and reduce Salmonella liability.
- Shandong and Henan provinces:Centralized food processing hubs in these Chinese regions are aggregating procurement volumes, driving bulk liquid egg contracts with integrated breaking operations.
Market Restraints
- Feed cost volatility:Corn and soybean meal prices fluctuate with commodity markets, squeezing margin predictability for integrated egg processors who captive-produce shell eggs.
- Concentrated shell egg supply:The US Southeast and China's Henan province dominate shell egg production, creating geographic risk exposure for processors dependent on regional breaking supply.
- Low-temperature pasteurization regulatory lag:FDA and USDA have not grandfathered emerging non-thermal pathogen reduction technologies, blocking flavor-retentive liquid egg formulations from commercial scale.
Strategic Opportunities
- India foodservice expansion:Quick-service restaurant chains and cloud kitchens in Mumbai, Delhi, and Bangalore are adopting liquid egg for standardized kitchen operations, opening import and local production pathways.
- Dual carbon goals alignment:China's MEE enforcement of carbon intensity targets creates competitive advantage for processors deploying solar-powered drying and anaerobic digesters at breaking facilities.
- Spray drying and membrane filtration convergence:Hybrid processing lines that pre-concentrate liquid egg via ultrafiltration before spray drying reduce energy consumption per kilogram of powder output.
Industry Challenges
- Specialized pasteurization technician scarcity:Automated membrane separation systems require operators trained in both thermal processing and filtration engineering, a skill combination lacking in most food manufacturing labor pools.
- Extended-shelf-life certification timelines:Validating 90-day liquid egg stability under refrigerated conditions demands 12-18 month protocol studies, delaying product launches and freezing R&D capital.
- Cold-chain reconfiguration costs:EU F-Gas refrigerant phase-down mandates equipment replacement across distribution networks, requiring capital deployment without guaranteed throughput recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Egg Processing Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Eggs, Dried Eggs, Frozen Eggs, Whole Eggs, Egg Yolk, Egg White Application: Bakery Products, Confectionery, Foodservice, Nutraceuticals, Cosmetic Products, Animal Feed Technology: Pasteurization, Spray Drying, Freezing, Vacuum Packaging, Ultrafiltration, Membrane Separation End User: Food Manufacturers, Personal Care Producers, Nutritional Supplements, Feed Mills, Institutional Kitchens, Food Retailers |
| Companies Covered | Cal-Maine Foods, Inc., Rose Acre Farms, Rembrandt Foods, Interovo Egg Group BV, Eurovo Srl, Avril SCA, IGRECA, Ovobel Foods Limited, SKM Egg Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Egg Processing Market Shifts & Advancements
Membrane filtration and automated breaking systems are redrawing competitive boundaries between thermal pasteurization specialists and equipment-integrated processors, while regulatory chemical phase-downs accelerate packaging material substitution cycles.
Ultrafiltration and microfiltration systems for liquid egg concentration and bacteria reduction are bifurcating the pasteurization equipment market. High-volume plants in the US and EU are retrofitting membrane lines to cut energy costs by eliminating secondary heating stages. This technology is compressing the advantage of traditional thermal-only processors who cannot match throughput per kilowatt-hour.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling European egg processors to validate alternative grease-resistant coatings for paperboard liquid egg cartons. Industrial consequence includes 18-24 month reformulation cycles and qualification delays with retail buyers. Powder egg exporters to the EU face parallel pressure to transition multi-layer laminated pouches to mono-material structures compatible with mechanical recycling streams.
Food manufacturers are consolidating supplier relationships around integrated liquid egg providers who control feed-to-breaking operations. Large-scale bakery and prepared meal producers are displacing fragmented shell egg vendors with multi-year liquid supply contracts specifying pathogen log-reduction guarantees and lot-level traceability. This concentration is most visible in China's Shandong province, where central kitchen operators for chain restaurants now specify SAMR-compliant liquid egg over provincial shell egg markets.
Global Egg Processing Market Segmentation
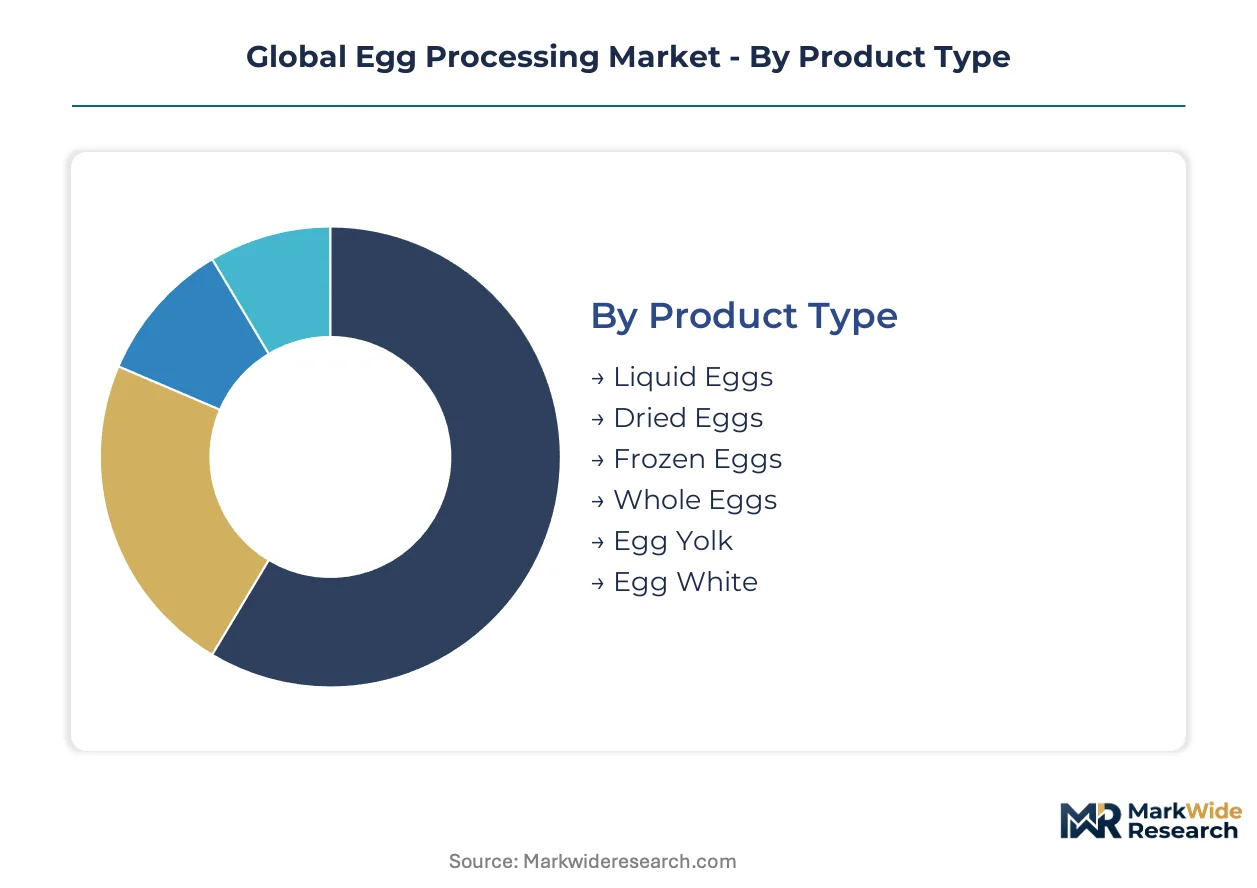
Product form and processing technology determine channel economics in egg processing, with liquid formats commanding foodservice volumes while dried products unlock export logistics. Application-specific specifications create divergent margin profiles across bakery, nutraceutical, and feed end-uses.
Product Type:
Liquid eggs flow through foodservice distributors and industrial bakery supply chains, while dried and frozen formats serve export-oriented nutraceutical and feed manufacturers with longer shelf-life requirements.
- Liquid Eggs:Standardized to 24-26% solids content for consistent bakery performance, this format eliminates on-site breaking for industrial kitchens. Demand concentrates in China's Shandong and Henan province food processing hubs, where centralized kitchens for chain restaurants specify SAMR-compliant liquid over provincial shell markets.
- Dried Eggs:Spray-dried powder reduces shipping weight by 70% versus liquid equivalents, enabling ambient storage for export logistics. Nutraceutical manufacturers in India and animal feed compounders across Southeast Asia are expanding procurement of dried whole egg and yolk powder for formulation stability.
- Frozen Eggs:Blast-frozen at minus 18 degrees Celsius for extended distribution reach in regions with underdeveloped cold chains.
- Whole Eggs:Unseparated liquid form preferred by industrial bakeries for simplified inventory management and consistent emulsification.
- Egg Yolk:High-lecithin fraction targeted by mayonnaise and sauce manufacturers for emulsion stability.
- Egg White:Albumen-dominant form specified by confectionery producers for foaming applications and sports nutrition brands for protein isolation.
Liquid eggs dominate installed base in mature markets. Dried eggs is where expansion concentrates for cross-border supply security.
Application:
Cost tier stratification separates commodity feed applications from premium nutraceutical and cosmetic segments, with bakery and foodservice occupying the high-volume mid-tier.
- Bakery Products:Industrial bread and cake manufacturers specify pasteurized liquid whole egg for consistent crumb structure and reduced Salmonella liability. Large-scale operations in the US Southeast and EU member states are displacing fragmented shell egg vendors with multi-year liquid supply contracts.
- Confectionery:Meringue and nougat production requires high-whip albumen with specified dry matter content for aeration control.
- Foodservice:Quick-service restaurant chains and cloud kitchens in Mumbai, Delhi, and Bangalore are adopting liquid egg for standardized kitchen operations, opening import and local production pathways.
- Nutraceuticals:Protein isolate and phospholipid extraction for dietary supplements commands technology margins through specialized fractionation.
- Cosmetic Products:Lecithin and protein derivatives for hair and skin formulations occupy the premium pricing tier.
- Animal Feed:Spray-dried egg powder for aquaculture and pet food formulations represents the volume base with compressed margins.
Bakery products anchor procurement volumes. Nutraceuticals is climbing the fastest as functional food investment accelerates.
Technology:
Margin structure bifurcates between energy-intensive thermal methods and membrane-based alternatives that reduce per-unit processing costs.
- Pasteurization:Thermal pathogen reduction at 60-64 degrees Celsius for 3.5-6 minutes remains the regulatory baseline for FDA and USDA compliance, though EU F-Gas Regulation phase-downs are forcing cold-chain equipment retrofits that compress operating margins.
- Spray Drying:Atomization and hot-air dehydration for powder production dominates export-oriented processing, with hybrid ultrafiltration pre-concentration lines reducing energy consumption per kilogram of output.
- Freezing:Blast and plate freezing for extended distribution in regions with intermittent cold-chain infrastructure.
- Vacuum Packaging:Modified atmosphere sealing for extended shelf-life liquid retail formats.
- Ultrafiltration:Pressure-driven concentration and bacteria reduction without thermal damage to functional proteins.
- Membrane Separation:Microfiltration systems for liquid egg concentration are retrofitting high-volume plants in the US and EU to cut energy costs by eliminating secondary heating stages.
Pasteurization holds the largest installed equipment base. Membrane separation is gaining share fastest as energy efficiency mandates tighten.
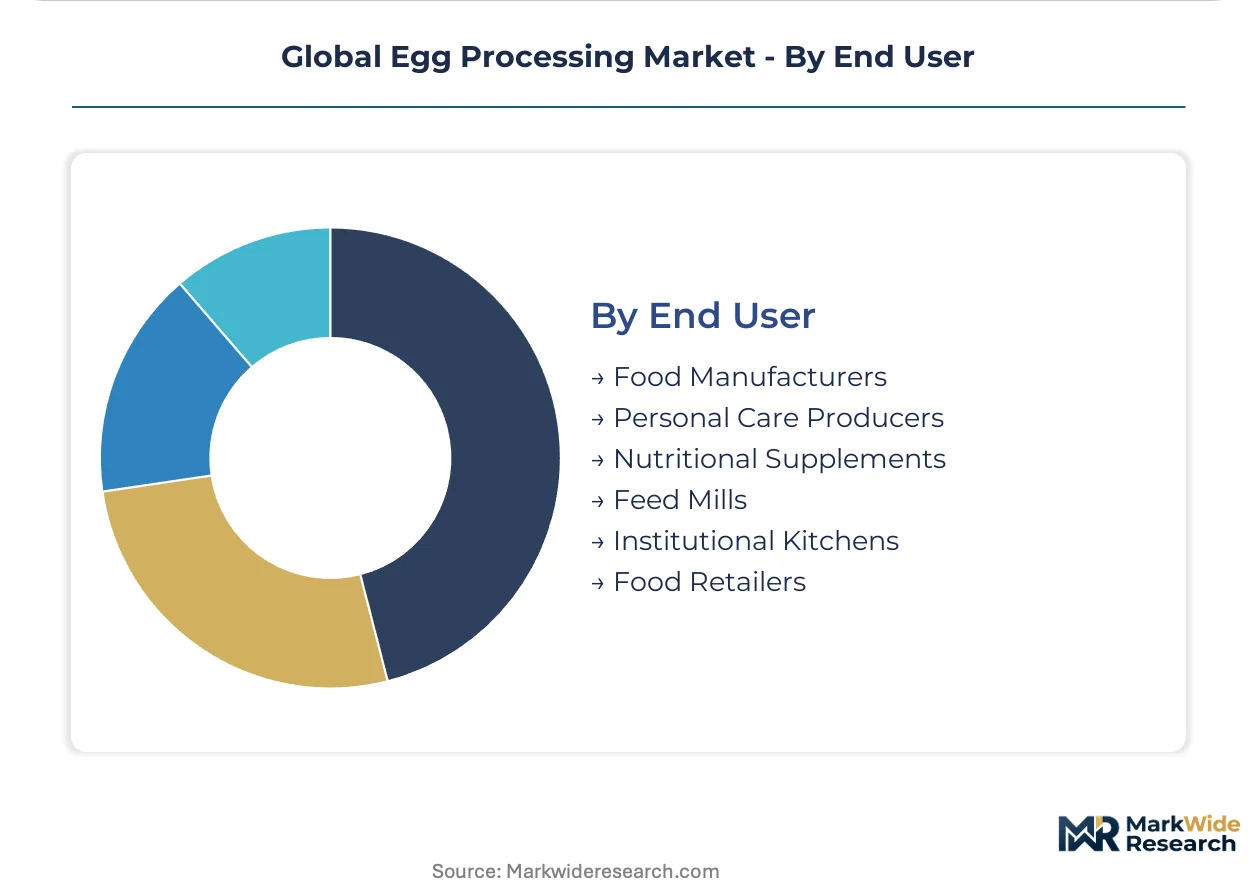
End User:
Customer type determines specification stringency, with food manufacturers demanding lot-level traceability while feed mills prioritize unit economics.
- Food Manufacturers:Industrial bakeries and prepared meal producers are consolidating supplier relationships around integrated liquid egg providers who control feed-to-breaking operations, specifying pathogen log-reduction guarantees and extended-shelf-life certification.
- Personal Care Producers:Cosmetic formulators in South Korea and Japan source phospholipid-rich yolk derivatives for emulsion stability.
- Nutritional Supplements:Sports nutrition brands in North America and Europe drive demand for microfiltered egg white protein isolates.
- Feed Mills:Aquaculture and pet food compounders in Southeast Asia procure spray-dried powder for formulation consistency.
- Institutional Kitchens:Hospital and school catering operations in India are adopting pasteurized liquid egg to eliminate on-site breaking labor and contamination risk.
- Food Retailers:Private-label liquid egg carton programs require REACH-compliant barrier films as European regulators phase down PFAS-containing coatings.
Food manufacturers represent the dominant demand block. Institutional kitchens is where adoption is accelerating most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA and USDA standards anchor the United States as the regulatory benchmark for pasteurized liquid egg safety, while China's SAMR enforcement and the EU's EFSA guidelines create parallel compliance frameworks that shape cross-border trade flows.
United States
Industrial bakeries in the Southeast specify pasteurized liquid whole egg for consistent emulsification and reduced Salmonella liability. FDA pasteurization standards at 60-64 degrees Celsius for 3.5-6 minutes remain the commercial baseline. Cal-Maine Foods and Rose Acre Farms anchor production clusters across Georgia, Alabama, and Mississippi with integrated feed-to-breaking operations.
China
Centralized food processing hubs in Shandong and Henan provinces are aggregating procurement volumes for bulk liquid egg contracts. SAMR and GB standards enforce domestic safety thresholds that foreign processors must meet for import eligibility. Zhengzhou and Jinan host the largest concentration of automated breaking facilities serving chain restaurant central kitchens.
Germany
REACH compliance frameworks are compelling reformulation of packaging materials to eliminate PFAS from liquid egg cartons. EU F-Gas Regulation phase-down schedules force cold-chain equipment retrofits across liquid egg distribution networks. Bavaria and Lower Saxony concentrate spray-drying capacity for powder exports to nutraceutical manufacturers.
India
Quick-service restaurant chains and cloud kitchens in Mumbai, Delhi, and Bangalore are adopting liquid egg for standardized kitchen operations. FSSAI safety thresholds govern domestic production while DGFT import policies shape cross-border supply pathways. Maharashtra and Karnataka host emerging breaking operations targeting foodservice institutional demand.
Netherlands
Rotterdam and Amsterdam serve as distribution gateways for EU egg powder exports to Southeast Asian feed compounders. EFSA guidelines and REACH Annex XVII restrictions on per- and polyfluoroalkyl substances accelerate packaging material substitution cycles. The Randstad region concentrates R&D activity in extended-shelf-life liquid formulations.
Global Egg Processing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated feed-to-breaking operations commanding procurement relationships from industrial bakeries and prepared meal producers. The upper tier captures multi-year supply contracts specifying pathogen log-reduction guarantees, while mid-scale processors compete on regional distribution reach and formulation flexibility. Two archetypes dominate: vertically integrated agribusinesses controlling shell egg supply and technology-focused specialists deploying membrane filtration for energy-efficient concentration. Competitive moves center on backward integration into captive shell egg production and geographic expansion through hub-and-spoke breaking networks.
Within the integrated agribusiness tier, Cal-Maine Foods exemplifies the feed-to-breaking model with operations spanning the US Southeast, while Rose Acre Farms occupies a parallel position through geographic concentration across multiple southern states. Rembrandt Foods represents the R&D-intensive archetype, anchoring competitive position through formulation capabilities in extended-shelf-life liquid products. These three US-based entities collectively illustrate how scale, vertical control, and technical specialization create defendable market positions.
| Leading Market Players |
|---|
| Cal-Maine Foods, Inc. |
| Rose Acre Farms |
| Rembrandt Foods |
| Interovo Egg Group BV |
| Eurovo Srl |
| Avril SCA |
| IGRECA |
| Ovobel Foods Limited |
| SKM Egg Products |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day liquid egg inventory cycles in European cold-chain networks concentrate pricing power with integrated feed-to-breaking operators who bypass spot-shell volatility. This lead-time band tightens when EU F-Gas refrigerant phase-downs force equipment retrofits, compressing margins for processors dependent on third-party breaking supply.
Pricing Analysis
Geographic price spreads between US Southeast shell egg origins and EU liquid egg terminals widen during feed cost spikes, favoring contract-based long-term offtake structures over spot procurement. Three-tier pricing structure across extended-shelf-life premium, standard pasteurized, and economy feed-grade segments differentiates by certification level and pathogen log-reduction guarantees. Pricing pressure stems from membrane filtration capital deployment costs as EU energy efficiency mandates tighten. Food manufacturers with multi-year supply agreements exhibit lowest price sensitivity; animal feed compounders remain most exposed to spot powder volatility.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for spray-dried powder shipments from Chinese processing hubs. Supply concentrates in the United States, China, and the Netherlands, with shell egg production anchored in Georgia and Henan province and powder drying capacity clustering in Bavaria and Shandong. Corn and soybean meal feed inputs, refrigerant gases, and barrier film packaging materials constitute critical dependencies. Single-source vulnerability concentrates in the US Southeast shell egg belt. Distribution runs through foodservice distributors and industrial bakery supply chains with direct-to-manufacturer contracts displacing fragmented shell egg vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as centralized food processing hubs in China and India's quick-service restaurant chains accelerate pasteurized liquid egg adoption ahead of legacy shell egg infrastructure penetration.
For Market Incumbents: Consolidate feed-to-breaking operations in Henan and Shandong provinces to lock in procurement relationships with chain restaurant central kitchens. Acquire membrane filtration engineering capabilities before EU energy mandates compress thermal-only processor margins. Defensive priority centers on blocking emerging Indian and Southeast Asian entrants from capturing foodservice institutional demand. For New Entrants and Emerging Players: Extended-shelf-life certification gaps among mid-scale European processors create service-layer white space for R&D-focused specialists. Target India's cloud kitchen and hospital catering segments where FSSAI compliance requirements favor imported or locally produced pasteurized liquid over provincial shell markets. Go-to-market angle: partner with quick-service restaurant chains for standardized kitchen operations in Mumbai, Delhi, and Bangalore. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because membrane filtration technology deployment and REACH-compliant packaging reformulation favor scaled operators with capital reserves. Acquisition target archetype: mid-cap European processors with installed spray-drying capacity but underinvested in ultrafiltration pre-concentration lines. Signal to watch: FDA grandfathering decisions on low-temperature pasteurization technologies as inflection indicator for flavor-retentive formulation viability.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | EU F-Gas phase-downs force energy-efficient pathogen reduction adoption in US and European plants. |
| REACH-Compliant Packaging Transition | PFAS elimination mandates compel 18-24 month barrier film reformulation cycles for liquid egg cartons. |
| Backward Integration into Feed Production | Corn and soybean meal cost volatility drives captive shell egg supply strategies across Southeast US. |
| Extended-Shelf-Life Certification Investment | 90-day refrigerated stability protocols require 12-18 month validation studies freezing R&D capital. |
| Hub-and-Spoke Breaking Network Expansion | Shandong and Henan province central kitchens aggregate procurement volumes for bulk liquid contracts. |
Research Methodology
Desk research of trade flow databases, EU F-Gas regulatory filings, and SAMR import eligibility standards preceded structured interviews with pasteurization equipment engineers, liquid egg procurement managers at industrial bakeries, cold-chain logistics operators, and membrane filtration system vendors. Bottom-up triangulation across facility-level capacity data and top-down validation against customs records and feed-to-breaking operational disclosures anchored volume estimates. Primary fieldwork with Chinese central kitchen operators and Indian quick-service restaurant chains supplemented secondary validation.
Variance decomposition across product form, processing technology, and end-use application segments structured the analytical framework over the projection horizon. Modeled dimensions included liquid versus dried versus frozen formats, thermal pasteurization versus membrane separation technologies, and bakery versus foodservice versus nutraceutical applications. CAGRs derived from segment-level growth rate blending weighted by installed capacity and trade flow intensity. Forecast inputs incorporated EU energy efficiency mandate compliance timelines and China's dual carbon enforcement trajectories at MEE.
Forecasts assume regulatory continuity in FDA pasteurization standards, EU REACH Annex XVII restrictions, and SAMR GB safety thresholds; material policy shifts would require re-modeling. Pathogen reduction protocol divergence between jurisdictions and emerging low-temperature technology regulatory lag constitute specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Maize Milling Machine Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Seed Processing Equipment Market