
 GCC OOH and DOOH Market | 2026-2036
GCC OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
GCC OOH and DOOH Market Insights
LED substrate technology is broadening the addressable cost envelope for large-format roadside installations across the Gulf. JCDecaux SE leverages its street furniture concessions in Dubai and Abu Dhabi to sustain premium positioning in high-traffic zones. BackLite Media LLC anchors its competitive stance through exclusive digital billboard rights along Sheikh Zayed Road. ELAN Group differentiates via specialized retail mall networks that integrate programmatic trading capabilities.
Out-of-home and digital out-of-home advertising encompasses physical and electronic media placed in public environments to deliver brand messages to audiences outside their residences, with digital variants employing networked LED and LCD displays capable of real-time content rotation and audience measurement. Transit advertising dominates volume deployment across the GCC's expanding metro and bus rapid transit systems, while digital billboards capture the fastest value growth due to higher CPM realization and dynamic creative optimization. LED displays lead technology adoption given superior luminance performance in high-ambient-light desert conditions, whereas projection mapping remains a niche experiential format concentrated around landmark architecture and event activations.
The General Authority for Audiovisual Media in Saudi Arabia enforces content screening protocols that shape campaign lead times and creative localization requirements for foreign advertisers. The UAE's Telecommunications and Digital Government Regulatory Authority governs network connectivity standards for programmatic DOOH platforms, influencing infrastructure investment decisions by media owners. MOHAP content guidelines in Dubai additionally constrain pharmaceutical and healthcare messaging formats. Stakeholders must monitor evolving data privacy interpretations across Saudi Arabia, the UAE, and Qatar as facial analytics and mobile device proximity tracking become standard audience measurement inputs.
Market Dynamics
Programmatic trading infrastructure is compressing campaign deployment cycles across GCC digital screen networks, forcing media owners to restructure sales operations around real-time auction mechanics rather than fixed-rate card systems.
Growth Catalysts
- Metro corridor expansion:Dubai and Abu Dhabi transit authorities are adding kilometers of tunnel and elevated track annually, creating captive audience environments with extended dwell times. Advertisers gain guaranteed reach against commuting professionals.
- GAMR content protocols:Saudi Arabia's standardized approval workflows, despite initial friction, ultimately reduce creative ambiguity and accelerate repeat campaign cycles for established brands.
- LED luminance advances:Next-generation diode arrays maintain visibility above 50°C ambient temperatures, eliminating the historical Gulf summer blackout periods that forced seasonal revenue cliffs.
Market Restraints
- Copper and rare-earth volatility:LED driver components and power distribution hardware face input cost swings that compress installation margins on fixed-price municipal contracts.
- Grid interconnection queues:Utility approval timelines for high-load digital billboards in Riyadh and Jeddah extend project commissioning by four to eight months beyond hardware delivery.
- Static print residual demand:Heritage hospitality and government clients in Oman and Bahrain continue specifying vinyl and paper formats for ceremonial and seasonal messaging, limiting full-fleet digital conversion.
Strategic Opportunities
- Qatar's Lusail and Msheireb districts:New-build smart city infrastructure embeds screen-ready mounting and power architecture, reducing retrofit capex for early-entrant media owners.
- 5G edge computing convergence:Low-latency networks enable synchronized multi-screen storytelling and augmented reality trigger layers across adjacent displays.
- MOHAP healthcare pathway:Dubai's streamlined pharmaceutical advertising guidelines create a compliant template that specialized agencies can replicate across GCC markets.
Industry Challenges
- Programmatic talent scarcity:Trading desk operators with DOOH-specific auction experience command premium compensation in Dubai and Riyadh, constraining operational scale-up.
- Legacy CMS integration:Mixed-vendor screen fleets from 2015-2019 hardware generations resist unified content management, forcing parallel workflow maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC OOH and DOOH Market |
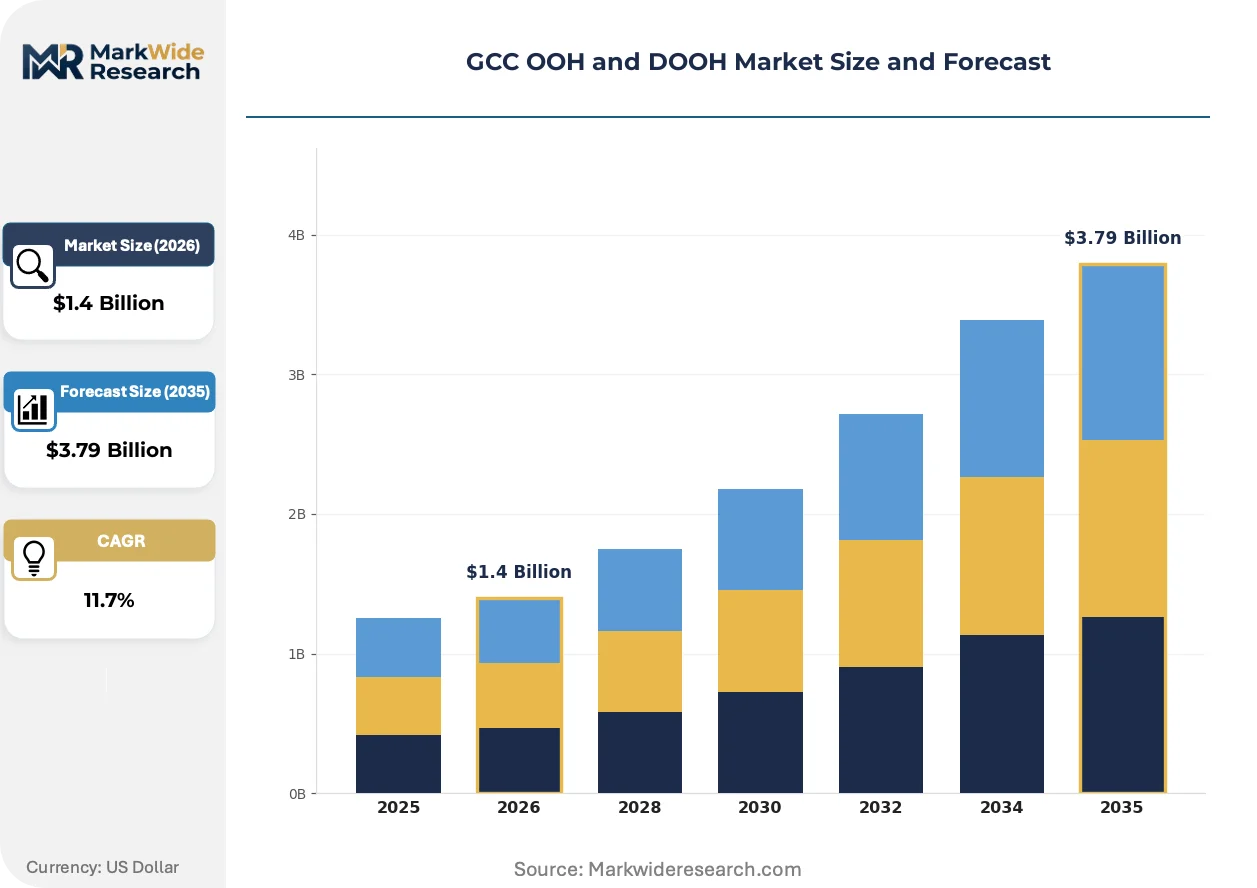
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Advertising Type: Digital Billboards, Transit Advertising, Street Furniture, Posters Technology: LED Displays, LCD Screens, Projection Mapping, Static Displays Client Type: Retail Brands, Automotive Manufacturers, Tourism Boards, Event Organizers Content Type: Brand Promotions, Product Launches, Public Service Announcements, Experiential Marketing |
| Companies Covered | JCDecaux SE, ELAN Group, Hills Advertising L.L.C., Emirates Neon Group, Al Arabiya, Dooha Media, HyperMedia FZ LLC, BackLite Media LLC, Elevision, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC OOH and DOOH Market Trends and Innovations
Real-time audience measurement is displacing circulation-based rate cards as the primary currency for inventory valuation, with buyers demanding impression verification comparable to digital display channels.
Computer vision systems with on-device processing are automating demographic classification and attention-duration scoring without transmitting raw facial imagery. Retail mall operators in Dubai and Abu Dhabi are deploying these units fastest, using dwell-time data to reprice premium atrium positions weekly. The technology is automating the shift from monthly rate commitments to dynamic yield-managed auctions.
GAMR's 2024 technical standards for screen brightness and content transition speeds are mandating hardware refresh cycles across Saudi Arabia's existing roadside inventory. Media owners must retrofit or replace units installed before 2020 to maintain operating licenses. The policy is compressing secondary equipment markets as decommissioned screens flow to Oman and Kuwait.
Brand procurement teams are consolidating DOOH spend under centralized trading desks, disintermediating the traditional agency-of-record model for out-of-home. Direct platform relationships between advertisers and supply-side platforms are displacing commission-based buying in the UAE's retail and automotive verticals. This concentration is most visible in Saudi Arabia, where three holding companies now control majority share of programmatic DOOH transactions.
GCC OOH and DOOH Market Segmentation
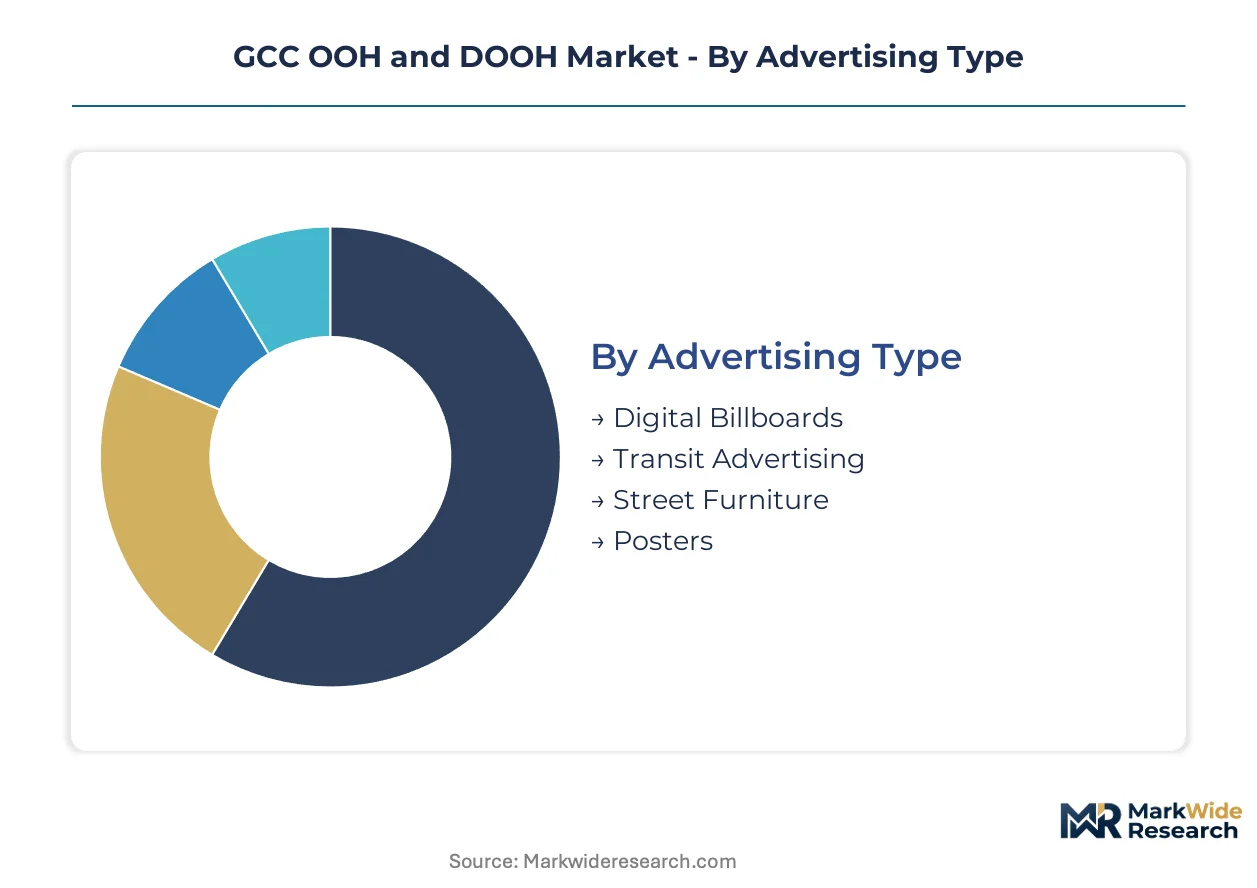
Segmentation in the GCC OOH and DOOH market reveals how regulatory compliance burdens, technology cost tiers, and client procurement maturity create distinct investment profiles across advertising formats and display technologies.
Advertising Type:
Certification requirements vary sharply by format: GAMR mandates brightness and transition standards for roadside digital billboards, while transit authorities enforce separate safety protocols for platform and vehicle-mounted displays.
- Digital Billboards:Large-format LED installations along highways and urban corridors command premium rates through dynamic creative rotation and real-time audience targeting. Demand concentrates on Sheikh Zayed Road in Dubai and Riyadh's King Fahd Road where traffic density sustains CPM premiums. GAMR's 2024 hardware refresh mandates are accelerating replacement cycles for pre-2020 installations.
- Transit Advertising:Metro corridor screens and bus rapid transit wraps capture extended dwell times in Dubai and Abu Dhabi's expanding rail networks. Inventory scales fastest where tunnel and elevated track additions create captive commuter audiences with guaranteed daily reach.
- Street Furniture:Bus shelters, kiosks, and urban fixtures integrate digital panels into municipal concession agreements. JCDecaux SE maintains exclusive positioning in Dubai and Abu Dhabi high-traffic zones.
- Posters:Static vinyl and paper formats persist in Oman and Bahrain where heritage hospitality and government clients specify ceremonial and seasonal messaging.
Leading the category by volume: Transit Advertising. Growing fastest: Digital Billboards.
Technology:
Cost tiers separate segments by upfront capex, operating energy load, and hardware refresh frequency, with premium formats requiring specialized power infrastructure and cooling systems.
- LED Displays:High-luminance diode arrays maintain visibility above 50°C ambient temperatures, eliminating historical Gulf summer blackout periods. Next-generation substrates are broadening the addressable cost envelope for large-format roadside installations across Saudi Arabia and the UAE.
- LCD Screens:Lower-brightness panels suit indoor mall and transit shelter environments where ambient light is controlled. BackLite Media LLC deploys these along retail corridors with moderate foot traffic.
- Projection Mapping:Niche experiential format concentrated around landmark architecture and event activations in Doha and Dubai. High production costs limit deployment to short-term brand activations.
- Static Displays:Non-digital vinyl and paper formats retain residual demand in Bahrain and Oman where budget constraints and ceremonial use cases resist full digital conversion.
Highest capex segment: LED Displays. Steepest expansion trajectory: Projection Mapping in experiential verticals.
Client Type:
Procurement sophistication varies by vertical, with retail and automotive brands pioneering programmatic trading while tourism and event clients rely on traditional fixed-rate commitments.
- Retail Brands:Programmatic DOOH investments concentrate in Dubai and Abu Dhabi mall networks where ELAN Group integrates real-time trading capabilities. Three Saudi holding companies now control majority share of programmatic transactions.
- Automotive Manufacturers:Premium positioning along highway corridors and metro stations targets commuting professionals with model launch campaigns. Direct platform relationships are displacing commission-based agency buying.
- Tourism Boards:Seasonal campaigns leverage landmark digital billboards and airport arrivals corridors. MOHAP content guidelines constrain healthcare-adjacent wellness messaging formats.
- Event Organizers:Short-term activations favor projection mapping and temporary LED installations around Doha and Dubai entertainment districts.
Most advanced programmatic adoption: Retail Brands. Fastest budget growth: Tourism Boards.
Content Type:
Approval timelines and localization requirements differ by message category, with pharmaceutical and public service content facing additional regulatory scrutiny.
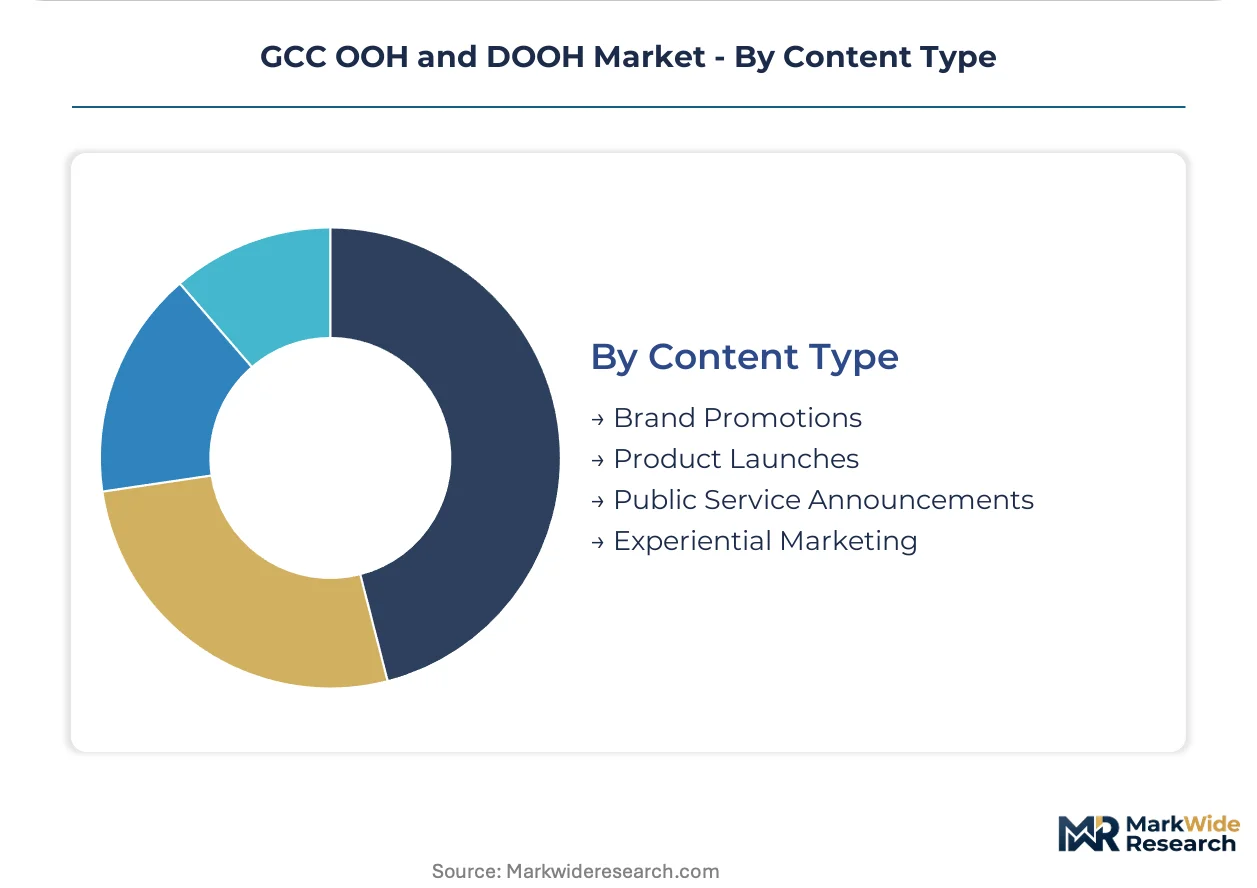
- Brand Promotions:Core revenue driver across all formats with standardized GAMR approval workflows reducing creative ambiguity for established advertisers. Repeat campaign cycles accelerate once initial compliance is achieved.
- Product Launches:Time-sensitive deployments benefit from programmatic infrastructure compressing campaign deployment cycles. Real-time auction mechanics replace fixed-rate card systems.
- Public Service Announcements:Government and health authority messaging requires MOHAP content screening in Dubai and equivalent protocols in Riyadh and Jeddah.
- Experiential Marketing:Immersive formats combine projection mapping with mobile-triggered augmented reality layers. 5G edge computing enables synchronized multi-screen storytelling.
Dominant volume share: Brand Promotions. Gaining share fastest: Experiential Marketing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Media free zones in Dubai and Abu Dhabi concentrate inventory ownership through concession-based operating rights that bundle street furniture, transit, and roadside assets under single-license frameworks.
Saudi Arabia
Riyadh's King Fahd Road corridor drives premium digital billboard demand from automotive and retail advertisers targeting affluent commuters. GAMR enforces 2024 hardware refresh mandates requiring luminance and transition speed compliance for operating licenses. Jeddah's expanding metro network creates captive audience environments with extended platform dwell times.
United Arab Emirates
Dubai's Sheikh Zayed Road maintains the GCC's highest CPM realization for large-format LED installations given traffic density and tourist visibility. MOHAP content guidelines constrain pharmaceutical messaging formats while streamlining approval pathways for compliant advertisers. Abu Dhabi's metro corridor expansion adds kilometers of tunnel and elevated track annually, scaling transit inventory fastest.
Qatar
Lusail and Msheireb smart city districts embed screen-ready mounting and power architecture into new-build infrastructure, reducing retrofit capex for early entrants. The country's national media regulator governs content standards for public display networks. Doha's landmark architecture hosts concentrated projection mapping activations for short-term experiential campaigns.
Kuwait
Decommissioned Saudi LED screens flow into secondary equipment markets here as GAMR mandates force hardware refresh cycles elsewhere. The national telecommunications authority oversees network connectivity standards for programmatic platforms. Kuwait City's retail mall networks lag Dubai and Abu Dhabi in programmatic trading adoption.
Oman
Heritage hospitality and government clients specify static vinyl and paper formats for ceremonial and seasonal messaging, resisting full digital conversion. The sultanate's national media regulator maintains content approval protocols for outdoor advertising. Muscat's traditional souk districts preserve non-digital inventory for cultural authenticity requirements.
GCC OOH and DOOH Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service media owners controlling premium roadside and transit concessions while technology integrators supply hardware and software infrastructure. The vendor base clusters around three archetypes: concession-holding incumbents with municipal exclusivity, programmatic technology platforms enabling real-time trading, and specialized retail network operators. Consolidation pressure concentrates in Saudi Arabia and the UAE where three holding companies now control majority programmatic transaction share. Dominant competitive moves include exclusive concession renewals for high-traffic zones and backward integration into proprietary audience measurement systems.
Within the concession-holder tier, JCDecaux SE and BackLite Media LLC exemplify divergent geographic anchoring strategies. JCDecaux SE occupies a position tied to Dubai and Abu Dhabi street furniture portfolios, while BackLite Media LLC sits within the Sheikh Zayed Road premium corridor. ELAN Group represents the retail-specialist archetype, with positioning concentrated in mall network programmatic capabilities.
| Leading Market Players |
|---|
| JCDecaux SE |
| ELAN Group |
| Hills Advertising L.L.C. |
| Emirates Neon Group |
| Al Arabiya |
| Dooha Media |
| HyperMedia FZ LLC |
| BackLite Media LLC |
| Elevision |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive LED substrate manufacturing anchors both supply security and pricing power for GCC media owners facing copper and rare-earth volatility. This upstream control insulates premium corridor operators from input cost swings while compressing margins for fixed-price municipal contractors lacking similar sourcing leverage.
Pricing Analysis
Volume-driven transit advertising splits from margin-rich digital billboards across distinct pricing architectures. Three-tier pricing structure across premium corridor, standard roadside, and economy transit tiers separates Sheikh Zayed Road positioning from metro platform inventory. Price differentiation rests on traffic density guarantees and programmatic trading readiness, with heritage hospitality clients in Oman and Bahrain exhibiting highest sensitivity due to static format residual demand. Cost compression in LED hardware procurement is intensifying as GAMR refresh mandates accelerate replacement cycles.
Supply Chain Analysis
Regional distribution centers in Dubai and Jeddah orchestrate hub-and-spoke patterns for LED driver components and power distribution hardware. Manufacturing concentration draws from China, South Korea, and Taiwan for diode arrays and control systems. Supply chain risk centers on single-source vulnerability for specialized cooling systems rated above 50°C ambient operation. Distribution runs through concession-holding incumbents with municipal exclusivity rather than open equipment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC OOH and DOOH market consolidation accelerates as programmatic talent scarcity forces smaller media owners toward exit. Three holding companies now control majority programmatic transaction share, squeezing independent operators without trading desk capabilities.
For Market Incumbents: Deepen exclusive concession renewals for high-traffic zones in Dubai and Abu Dhabi metro corridors before competitive bidding reopens. Invest proprietary audience measurement systems to defend against disintermediation from brand trading desks. Capture GAMR compliance certification as a barrier against decommissioned equipment flows from Saudi refresh cycles.
For New Entrants and Emerging Players: Capture Qatar's Lusail and Msheireb smart city districts where screen-ready infrastructure reduces retrofit capex. Target Kuwait's secondary equipment market for decommissioned Saudi LED screens as a lower-cost fleet build strategy. Deploy 5G edge computing capabilities as a differentiated go-to-market angle for synchronized multi-screen storytelling.
For Investors and Strategic Acquirers: Exit pathways concentrate in concession-holding incumbents with municipal exclusivity and programmatic trading infrastructure. Long-term viability favors operators with captive supply relationships and proprietary yield management platforms. Watch GAMR content protocol enforcement as an inflection indicator for compliance cost barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Concession Renewal | JCDecaux SE and BackLite Media LLC leverage municipal relationships to lock premium corridor access. |
| Programmatic Trading Platform Integration | Real-time auction mechanics displace fixed-rate card systems across Saudi and UAE retail verticals. |
| LED Hardware Refresh Compliance | GAMR 2024 luminance mandates force pre-2020 installation replacement, accelerating capital deployment. |
| Proprietary Audience Measurement Development | Computer vision systems with on-device processing automate demographic classification without privacy exposure. |
| 5G Edge Computing Infrastructure | Low-latency networks enable synchronized multi-screen storytelling across adjacent Dubai mall displays. |
Research Methodology
Independent corroboration across media owner executives, programmatic trading desk operators, and municipal concession administrators underwrites the qualitative findings. Primary interviews with LED hardware procurement leads, GAMR compliance officers, and brand media planners combined with secondary validation from customs records, municipal concession filings, and telecommunications authority connectivity standards. Bottom-up inventory counts triangulate against top-down advertising spend estimates across the analysis window.
Rate-of-change decomposition separates volume expansion in transit corridors from value growth in premium digital billboards throughout the forecast period. Segmentation dimensions span advertising format, display technology, client procurement maturity, and content approval pathway complexity. CAGRs derive from installed base projections, replacement cycle acceleration, and programmatic trading penetration curves. Model inputs incorporate GAMR hardware refresh mandates and MOHAP content guideline enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and rare-earth price volatility, grid interconnection queue delays, and evolving data privacy interpretations across Saudi Arabia, the UAE, and Qatar. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market