
 United States Marketing Agencies Market | 2026-2036
United States Marketing Agencies Market Size, Share, and Industry Trends Forecast 2026-2036
United States Marketing Agencies Market Insights
Service unbundling from traditional retainer contracts into modular, project-based configurations is realigning how corporate procurement teams evaluate agency partners. WPP leverages its integrated network structure to sustain multi-market campaigns for Fortune 500 clients. Omnicom Group anchors premium positioning through specialized healthcare and technology vertical practices. VaynerMedia competes aggressively in social-first content production, controlling direct-to-consumer brand narratives at scale.
Marketing agencies are professional services firms that plan, execute, and measure paid, owned, and earned media campaigns across channels, combining creative production with data analytics infrastructure to drive customer acquisition and retention. The service type dimension shows digital marketing and SEO commanding the largest revenue pools as brands redirect spend from linear television to programmatic and search platforms. Client type segmentation reveals small businesses and startups as the fastest-expanding engagement category, though corporations still occupy the deepest margin pools through multi-year retainers.
The Federal Trade Commission enforces truth-in-advertising standards that shape claim substantiation requirements for campaigns targeting US consumers, while the Securities and Exchange Commission governs investor-facing communications for publicly traded clients. State-level privacy frameworks, including the California Consumer Privacy Act and emerging laws in Virginia and Colorado, are forcing agencies to restructure data handling protocols and audience targeting methodologies. Stakeholders must monitor how fragmented state privacy legislation will reshape cross-border campaign execution and client liability allocation.
Market Dynamics
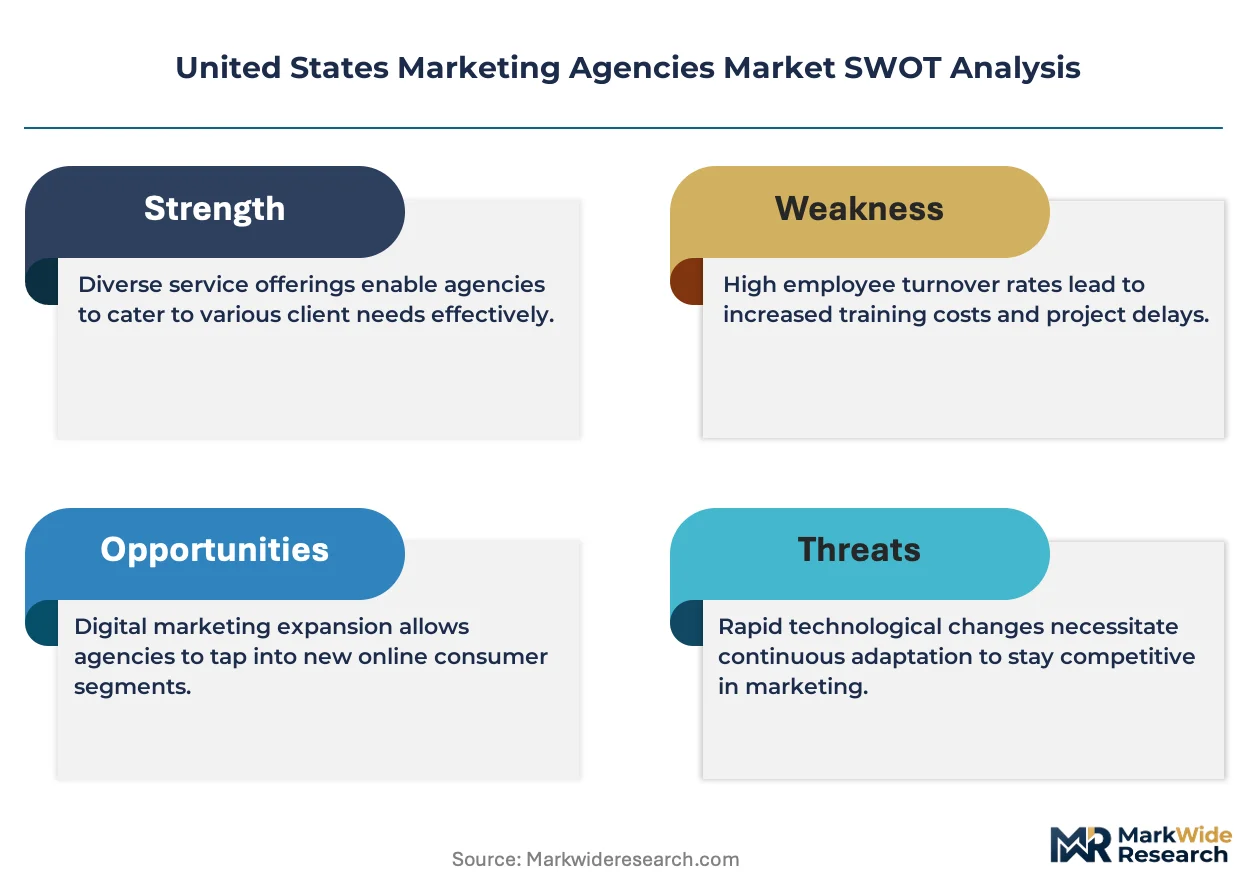
Fragmented state privacy legislation is forcing marketing agencies to rebuild data infrastructure and retainer pricing models around jurisdictional compliance rather than audience scale.
Growth Catalysts
- Healthcare vertical expansion:HIPAA tightening around patient-targeted campaigns drives providers toward specialized agency partnerships with certified data governance protocols.
- Performance marketing infrastructure:Programmatic platforms and search engine optimization tools redirect brand budgets from linear television toward measurable digital channels.
- California cluster density:Los Angeles and San Francisco concentrate digital-native brand headquarters and specialized talent pools that anchor national campaign execution.
Market Restraints
- Data handling cost inflation:Compliance with the California Consumer Privacy Act and emerging Virginia and Colorado frameworks requires expensive infrastructure reconfiguration.
- Talent concentration risk:Performance marketing specialists cluster in coastal metropolitan areas, creating wage pressure and retention challenges for mid-market agencies.
- Platform dependency:Algorithm changes by dominant social media and search platforms disrupt campaign performance without warning or recourse.
Strategic Opportunities
- Modular service unbundling:Project-based configurations replace traditional retainers, opening procurement access to small businesses and startups previously priced out of agency relationships.
- First-party data architecture:Brands building direct customer data pipelines create demand for agencies with customer data platform implementation expertise.
- Artificial intelligence content production:Generative tools converging with creative workflows compress production timelines and expand volume capacity for mid-tier accounts.
Industry Challenges
- Cross-state campaign execution complexity:Fragmented privacy legislation forces agencies to maintain multiple targeting methodologies and liability frameworks for single national campaigns.
- Measurement standardization gaps:Inconsistent attribution models across platforms and clients complicate performance reporting and fee justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Marketing Agencies Market |
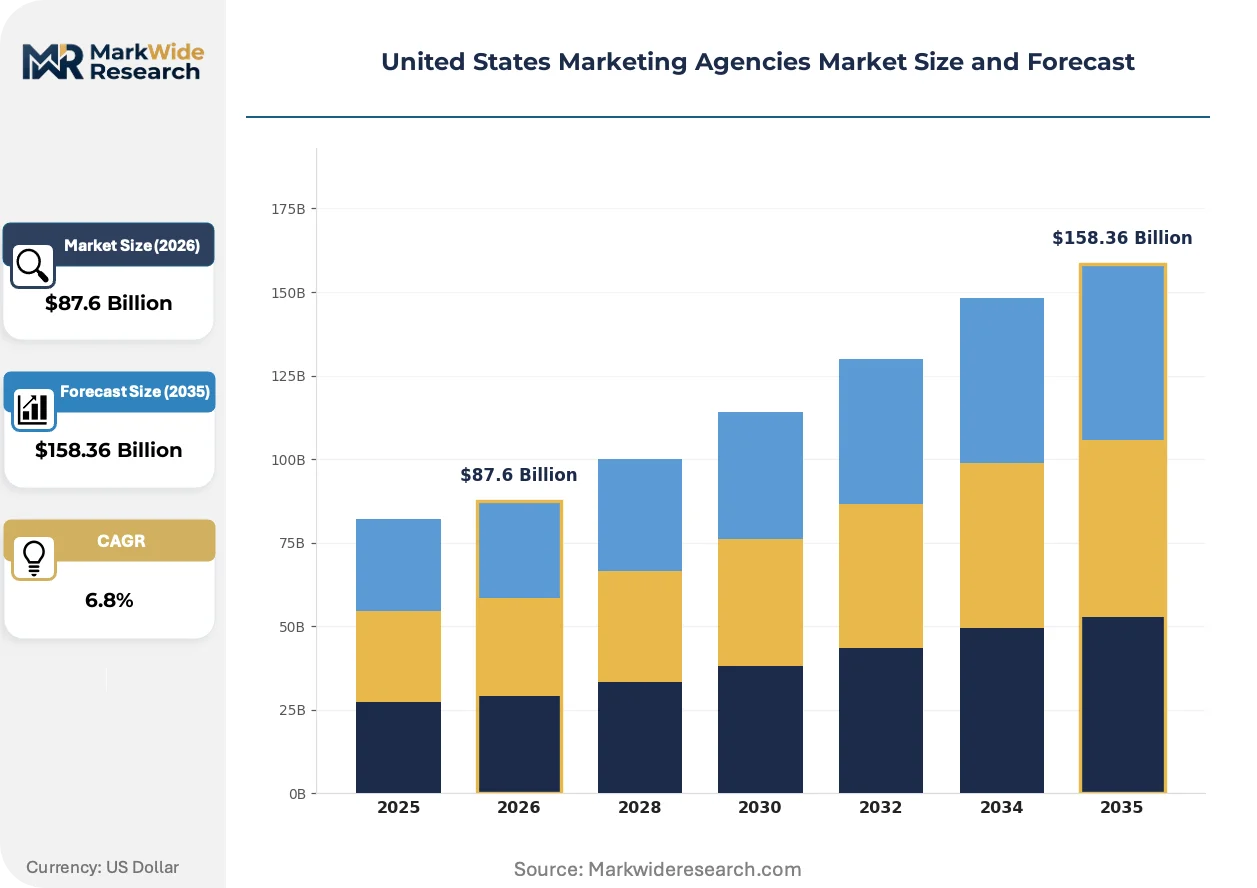
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Marketing, Content Creation, SEO, Social Media Management Client Type: Small Businesses, Corporations, Nonprofits, Startups Engagement Model: Project-Based, Retainer, Hourly Rate, Performance-Based Industry Vertical: Retail, Technology, Healthcare, Education |
| Companies Covered | WPP, Omnicom Group, Interpublic Group, Publicis Groupe, Dentsu Group, Havas, Stagwell, Horizon Media, VaynerMedia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Marketing Agencies Market Trends and Innovations
Agency business models are compressing around speed-to-creative and compliance-first infrastructure, displacing the traditional retainer-plus-commission structure that dominated the past two decades.
Generative artificial intelligence is expanding into creative production workflows, automating variant generation for A/B testing and personalized messaging at scale. Mid-market brands and direct-to-consumer retailers adopt these tools fastest, cutting production timelines from weeks to days. The technology is expanding into lower-funnel content categories previously reserved for human copywriters and designers.
The Federal Trade Commission enforces truth-in-advertising standards that reshape claim substantiation requirements for campaigns targeting US consumers. Substantiation documentation now extends to influencer partnerships and user-generated content amplification, not just traditional paid media. Healthcare and financial services verticals face the steepest compliance burdens, with agencies building dedicated legal review layers into production workflows.
Corporate procurement teams now demand modular project scopes with fixed deliverables rather than open-ended monthly retainers. Small businesses and startups access agency talent through this structure, while enterprise clients unbundle strategy from execution to optimize spend. California and New York metropolitan markets show the fastest adoption of this purchasing pattern, with procurement professionals rotating vendors by campaign objective rather than maintaining exclusive relationships.
United States Marketing Agencies Market Segmentation
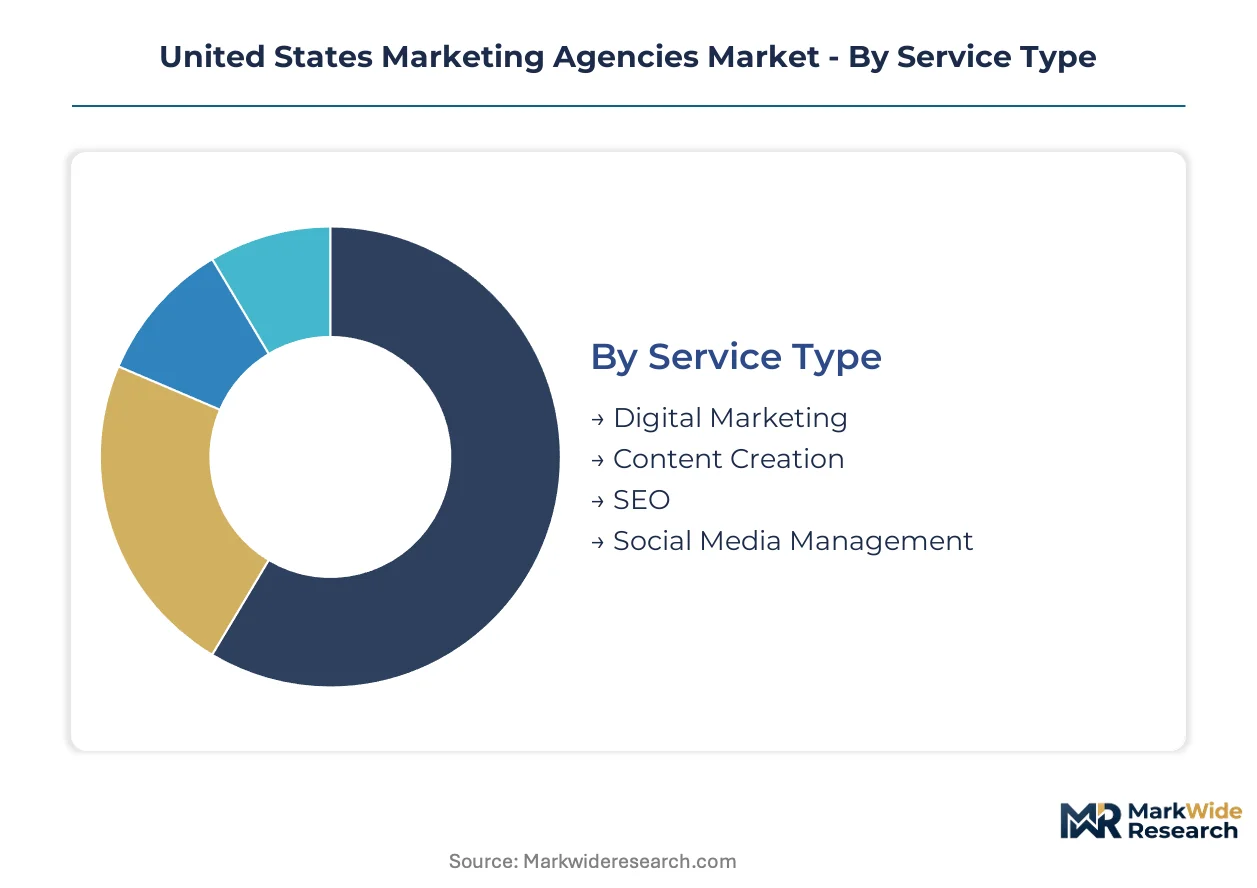
Marketing agencies structure their service portfolios around distinct buyer priorities, from compliance-heavy healthcare verticals to speed-focused startup engagements. Procurement teams evaluate partners through multiple lenses simultaneously, creating segmentation patterns that directly shape pricing power and contract duration.
Service Type:
Budget allocation decisions now favor measurable outcomes over brand awareness, compressing the traditional media mix toward performance channels.
- Digital Marketing:Programmatic buying platforms and search engine marketing dominate spend redirection from linear television. California-based brands in Los Angeles and San Francisco anchor the deepest agency relationships here, driven by direct-to-consumer retail and technology sector concentration.
- SEO:Technical optimization and content architecture services command premium pricing as first-party data strategies displace third-party cookie targeting. Healthcare providers expanding HIPAA-compliant patient acquisition campaigns represent the steepest demand slope within this segment.
- Content Creation:Video and interactive asset production for social-first distribution.
- Social Media Management:Community operations and influencer coordination at platform-native speed.
Volume sits with Digital Marketing; growth tilts toward SEO.
Client Type:
Contract structure flexibility determines access tiers, with procurement sophistication varying sharply across organizational maturity levels.
- Corporations:Multi-year retainers with dedicated account teams and integrated agency networks sustain the deepest margin pools. Fortune 500 procurement teams unbundle strategy from execution, rotating specialists by campaign objective rather than maintaining exclusive relationships.
- Startups:Venture-backed direct-to-consumer brands demand modular project scopes with fixed deliverables and compressed timelines. San Francisco and New York metropolitan markets show the fastest adoption of this purchasing pattern.
- Small Businesses:Local service providers and regional retailers accessing talent through self-service platforms.
- Nonprofits:Grant-constrained organizations prioritizing pro-bono and discounted rate structures.
Revenue concentrates with Corporations; expansion accelerates fastest among Startups.
Engagement Model:
Risk transfer mechanisms reshape how agencies price talent deployment and outcome accountability.
- Project-Based:Fixed-scope deliverables with defined timelines replace open-ended monthly commitments. Small businesses and startups previously priced out of agency relationships access talent through this structure.
- Performance-Based:Fee structures tied to customer acquisition metrics or revenue outcomes align agency incentives with client results. Technology and retail verticals show the strongest adoption as attribution infrastructure matures.
- Retainer:Ongoing strategic partnership with predictable monthly billing.
- Hourly Rate:Time-and-materials billing for advisory and consulting engagements.
Retainers still capture the largest revenue base; Performance-Based contracts are climbing the fastest.
Industry Vertical:
Regulatory burden intensity separates verticals with compliance-premium pricing from commodity-competitive segments.
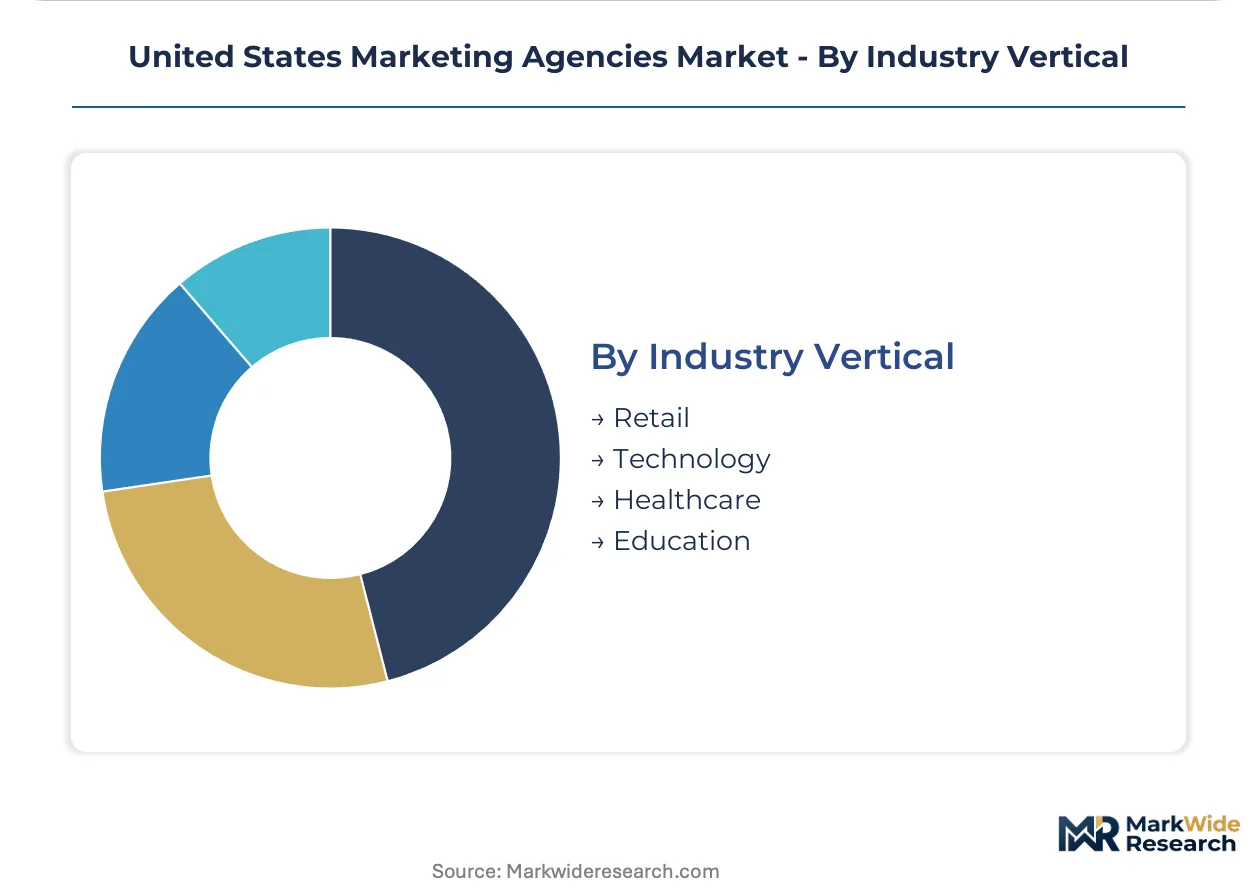
- Healthcare:HIPAA tightening around patient-targeted campaigns drives providers toward specialized agency partnerships with certified data governance protocols. FTC substantiation requirements and state privacy frameworks force dedicated legal review layers into production workflows.
- Technology:Software and platform companies demand speed-to-creative and technical integration expertise. Los Angeles and San Francisco cluster density concentrates both client headquarters and specialized agency talent pools.
- Retail:Direct-to-consumer and omnichannel brands redirecting spend toward programmatic and social commerce.
- Education:Institutions and edtech platforms targeting enrollment and engagement outcomes.
Healthcare commands the steepest pricing premium; Technology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and state-level tax incentives in California, Texas, and New York are concentrating marketing agency headquarters and specialized talent pools. These designated districts offer capital gains deferrals that attract venture-backed startups and established holding companies alike. The resulting geographic clustering reshapes competitive dynamics across the national market.
California
Los Angeles and San Francisco anchor the nation's densest concentration of digital-native brands and performance marketing specialists. The California Consumer Privacy Act forces agencies to restructure data handling protocols and retainer pricing models around jurisdictional compliance. San Francisco's South of Market district and Los Angeles' Arts District host the fastest-growing clusters of social-first content studios serving direct-to-consumer retailers.
New York
Manhattan and Brooklyn command premium positioning for financial services and luxury brand campaigns requiring sophisticated regulatory navigation. The SEC governs investor-facing communications for publicly traded clients headquartered in the metropolitan area. DUMBO and Hudson Yards have emerged as the primary locations for agencies unbundling strategy from execution for Fortune 500 procurement teams.
Texas
Austin and Dallas are drawing technology sector marketing spend away from coastal markets through lower operational costs and state tax advantages. The absence of comprehensive state privacy legislation reduces compliance overhead for campaigns targeting national audiences. Austin's East Side and Dallas' Design District concentrate emerging agencies specializing in programmatic buying and search engine optimization infrastructure.
Illinois
Chicago sustains deep relationships with healthcare systems and pharmaceutical manufacturers navigating HIPAA tightening around patient-targeted campaigns. The city's central time zone and transportation infrastructure support multi-market campaign coordination. The Loop and West Loop districts house specialized practices building certified data governance protocols for provider networks.
Florida
Miami and Tampa are capturing healthcare and hospitality vertical expansion as providers seek alternatives to saturated Northeast and California markets. State-level tax incentives for business relocation accelerate talent migration from higher-cost metropolitan areas. Wynwood and Ybor City have developed distinct agency ecosystems focused on multicultural audience targeting and Spanish-language content production.
United States Marketing Agencies Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure defined by scale and vertical depth. The market consolidates around holding company networks with integrated service capabilities spanning creative, media, and data analytics. Three archetypes dominate: global full-service networks, vertical specialists with certified compliance infrastructure, and social-native content studios. Competitive moves center on modular service unbundling and first-party data architecture partnerships.
Within the integrated network tier, WPP and Omnicom Group exemplify scale-driven positioning through multi-market campaign coordination. VaynerMedia occupies a distinct position as a social-first specialist competing aggressively in direct-to-consumer brand narrative production. These three anchors demonstrate how divergent scale and specialization strategies coexist within the same competitive space.
| Leading Market Players |
|---|
| WPP |
| Omnicom Group |
| Interpublic Group |
| Publicis Groupe |
| Dentsu Group |
| Havas |
| Stagwell |
| Horizon Media |
| VaynerMedia |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between HIPAA-compliant healthcare specialists and commodity creative shops manifests simultaneously in rate card spreads and talent sourcing geography. Premium pricing for certified data governance protocols coexists with compressed margins in undifferentiated content production, while coastal talent concentration forces mid-market agencies toward remote contractor networks.
Pricing Analysis
Short lead-time premiums dominate project-based engagements, with rush fees attaching to campaigns compressed below standard production timelines. Three-tier pricing structure across premium, standard, and economy levels separates enterprise retainer relationships from modular startup engagements and self-service platform access. Cost compression in social-first content production intensifies as generative tools displace human copywriting at volume tiers. Price sensitivity peaks among small businesses accessing talent through unbundled project scopes, while healthcare verticals absorb premium rates for compliance infrastructure.
Supply Chain Analysis
Specialized creative talent supply rests on Los Angeles, San Francisco, and New York metropolitan concentration, with secondary pools emerging in Austin and Miami. Inputs span proprietary data analytics platforms, licensed generative AI tools, and third-party audience targeting infrastructure. Single-source vulnerability concentrates in dominant social media platform APIs, where algorithm changes disrupt campaign performance without recourse. Distribution runs through direct client relationships, platform-managed service marketplaces, and holding company network referrals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into first-party data architecture and customer data platform implementation capabilities is accelerating as brands displace third-party cookie dependencies. Agencies capturing upstream data infrastructure relationships secure downstream creative retainers.
For Market Incumbents: Cement multi-year healthcare partnerships through certified HIPAA compliance infrastructure before specialized competitors replicate governance protocols. Acquire customer data platform implementation capabilities to capture upstream data architecture spend. Defensive consolidation around first-party data consulting protects against platform-native agency encroachment. For New Entrants and Emerging Players: Social commerce content studios represent the most penetrable white-space target, serving direct-to-consumer retailers with platform-native creative at compressed timelines. Modular project scopes for venture-backed startups in Austin and Miami bypass coastal wage pressure. Go-to-market through self-service platform interfaces with transparent rate cards disrupts traditional RFP processes. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists possessing certified healthcare or financial services compliance infrastructure given regulatory tightening across state privacy frameworks. Long-term viability favors agencies with durable first-party data architecture partnerships rather than platform-dependent execution shops. Watch HIPAA enforcement actions as inflection indicators for healthcare vertical premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Architecture Partnership | Customer data platform implementation expertise captures upstream brand relationships before creative execution. |
| HIPAA Compliance Certification Investment | Certified data governance protocols unlock healthcare provider retainer premiums and defensive moats. |
| Generative AI Creative Workflow Integration | Automated variant generation compresses production timelines for mid-market direct-to-consumer accounts. |
| Modular Service Unbundling | Fixed-scope project configurations expand addressable market to small businesses previously priced out. |
| Geographic Talent Pool Diversification | Austin and Miami satellite offices reduce coastal wage pressure while maintaining platform access. |
Research Methodology
Document review covered SEC filings of publicly traded holding companies, state privacy legislation databases, and platform API documentation, complemented by interviews with agency managing directors, healthcare marketing compliance officers, brand procurement leads, and programmatic platform engineers. Secondary sources included FTC enforcement action records, CMS hospital marketing expenditure data, and venture capital financing databases. Bottom-up service line estimates triangulated against top-down holding company revenue disclosures.
Cross-referencing historical financial trajectories against expert panel inputs anchored growth projections across the analysis window. Segmentation dimensions modeled encompassed service type, client organizational maturity, engagement risk transfer mechanism, and industry vertical regulatory intensity. CAGRs derived from weighted average of historical trajectory continuation and structural shift impact assessment, incorporating platform spend redirection rates and compliance cost inflation assumptions.
Inputs from agency financial disclosures and platform partnership announcements were available through the study window; gaps in private company project-level pricing introduce uncertainty bands around segment-level estimates. Forecasts reflect assumptions regarding state privacy legislation adoption timelines and platform algorithm stability. A small set of triggers—FTC enforcement intensity, HIPAA audit frequency, and generative AI copyright litigation outcomes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Middle East and Africa Programmatic Advertising Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market