
 Advertising Services Market | 2026-2036
Advertising Services Market Size, Share, and Industry Trends Forecast 2026-2036
Advertising Services Market Analysis
Agency-to-in-house sourcing is hardening as large advertisers build internal studios and data science teams. WPP plc sustains its position through technology-led consolidation of media buying and creative production. Omnicom Group Inc. differentiates via integrated customer experience platforms spanning CRM and commerce. Publicis Groupe S.A. leverages its first-party data infrastructure to compete directly with walled-garden platforms.
Advertising services encompass strategic planning, creative development, media placement, and performance measurement across channels, executed through a mix of human expertise and automated systems including real-time bidding protocols and dynamic creative optimization. The primary commercial purpose is to allocate advertiser capital toward measurable audience engagement and conversion outcomes. Digital advertising dominates service-type revenue as programmatic infrastructure and retail media networks capture margin pools once held by traditional media. Data analytics within the technology segment is expanding fastest as advertisers demand closed-loop attribution across fragmented consumer journeys.
The EU AI Act and GDPR constrain algorithmic targeting and cross-border data flows for campaigns reaching European consumers. The FTC in the United States enforces transparency in influencer marketing and native advertising disclosures, reshaping creative production workflows. China's SAMR scrutinizes data collection practices in programmatic ecosystems. Stakeholders must monitor how privacy regulations fragment addressable audiences and force reinvention of measurement standards.
Market Dynamics
The Advertising Services Market is being fundamentally restructured by the deprecation of third-party cookies and the corresponding migration toward first-party data infrastructure, forcing advertisers to rebuild targeting and measurement systems from the ground up.
Growth Catalysts
- Retail Media Networks:E-commerce platforms are capturing closed-loop ad inventory that links exposure directly to purchase, drawing budget from traditional display and search channels.
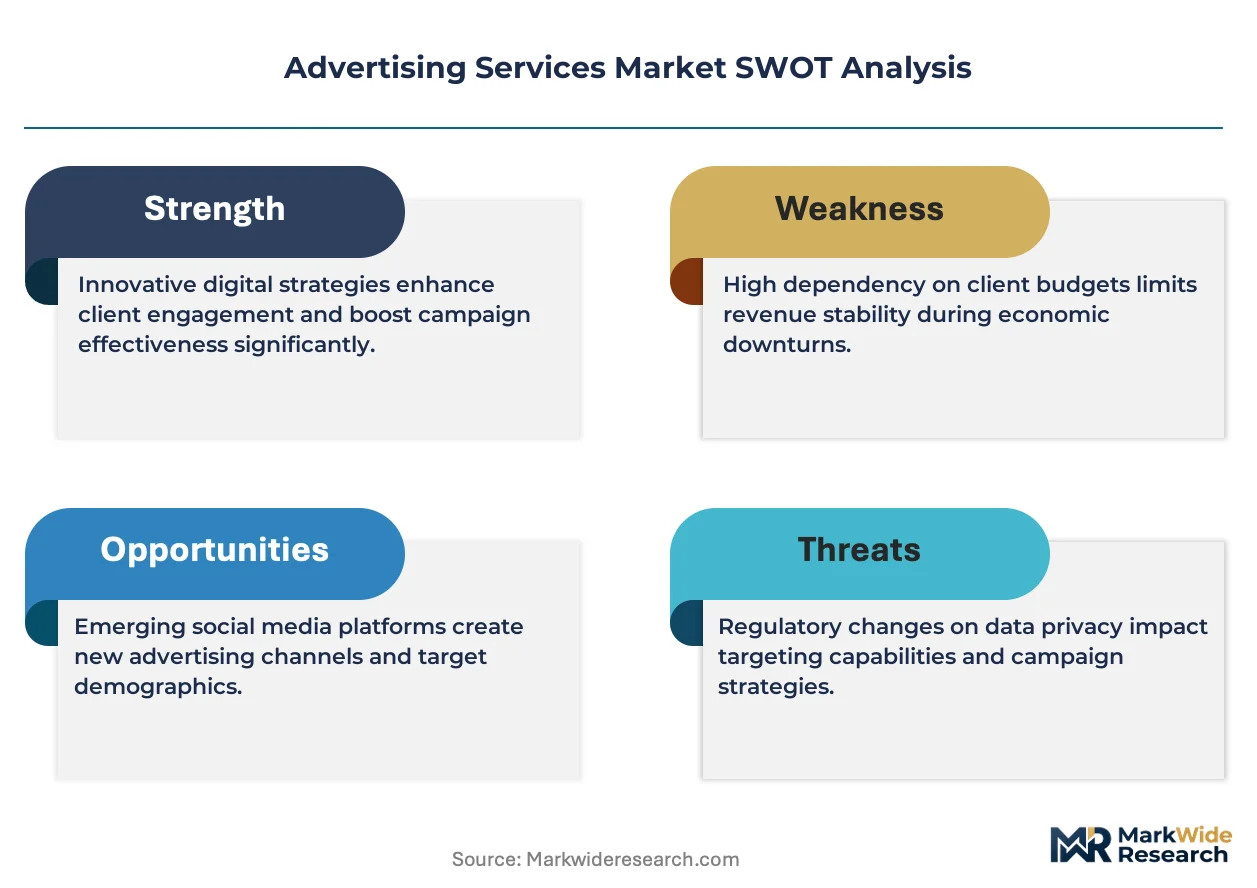
- EU AI Act:Algorithmic transparency mandates are accelerating investment in explainable AI tools for campaign optimization and audience segmentation.
- Connected TV:Streaming inventory is expanding addressable reach for brand advertisers seeking television-scale impact with digital precision.
Market Restraints
- Signal Loss:Apple's ATT framework and browser cookie blocking have degraded cross-site attribution, compressing measurable return on ad spend.
- Cloud Infrastructure Concentration:AWS, Google Cloud, and Azure dominate the compute layer for programmatic platforms, creating cost and resilience vulnerabilities.
- GDPR Enforcement:Cross-border data transfer restrictions have fragmented European audience pools and complicated multi-market campaign execution.
Strategic Opportunities
- Clean Rooms:Privacy-preserving data collaboration environments are enabling advertiser-publisher partnerships without raw data sharing.
- Commerce Media:Non-retail verticals including travel and financial services are building ad-supported platforms on transaction data.
- Influencer Disclosure Rules:FTC transparency mandates are professionalizing creator economics and opening budget flows to verified measurement providers.
Industry Challenges
- Data Science Talent:Shortages in probabilistic modeling and differential privacy expertise are constraining in-house capability builds.
- Legacy Stack Integration:Advertisers face friction connecting new identity graphs to entrenched DMP and CRM architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advertising Services Market |
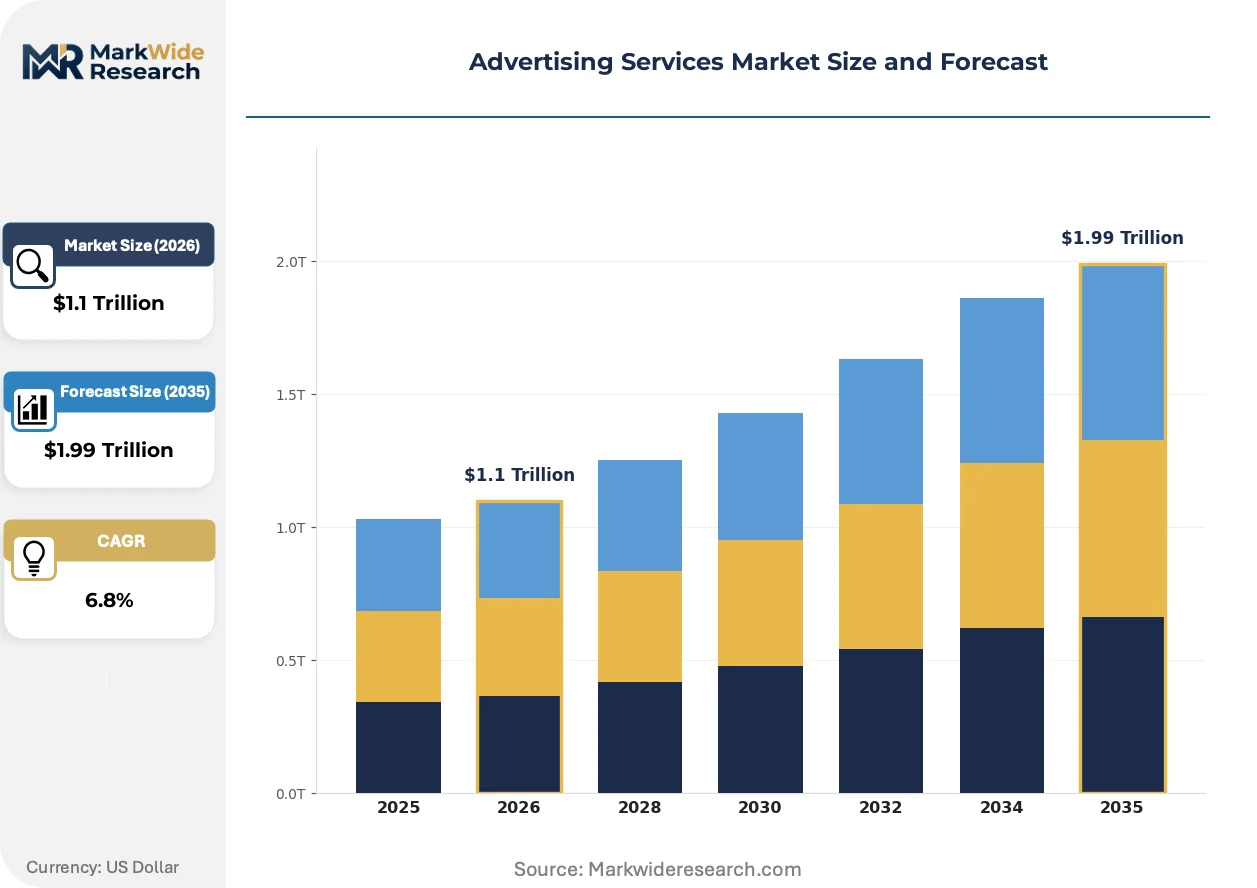
| Market Size in 2026 | $1.1 Trillion |
| Market Size in 2035 | $1.99 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Advertising, Print Advertising, Broadcast Advertising, Outdoor Advertising Client Type: Small Businesses, Corporations, Non-Profits, Government Agencies Delivery Model: In-House, Agency-Supported, Freelance, Collaborative Technology: Programmatic Advertising, SEO Tools, Social Media Marketing, Data Analytics |
| Companies Covered | WPP plc, Omnicom Group Inc., Publicis Groupe S.A., Dentsu Group Inc., The Interpublic Group of Companies Inc., Havas S.A., Stagwell Inc., Accenture plc, Hakuhodo DY Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advertising Services Market Emerging Trajectories
Programmatic infrastructure is fragmenting as privacy constraints and platform competition redistribute power among data owners, technology intermediaries, and measurement providers.
Identity resolution technology is decentralizing control over audience targeting. Retailers and publishers are deploying proprietary graphs based on authenticated user relationships. Advertisers are adopting multi-graph strategies rather than relying on single-source identifiers. This architecture is decentralizing data power away from walled-garden platforms toward first-party data holders.
GDPR enforcement actions against Meta and other platforms have established precedent for fines tied to unlawful data processing for ad targeting. The European Data Protection Board's consistency mechanism is harmonizing penalty frameworks across member states. Cross-border campaign planners are now building jurisdiction-specific consent and data minimization protocols.
Brand advertisers are unbundling creative production from media buying, establishing direct relationships with creator studios and generative AI tooling providers. Agencies are responding by building modular service layers around strategy and measurement. This restructuring is most visible in the United States, where large CPG and automotive advertisers have built internal content engines.
Advertising Services Market Segmentation
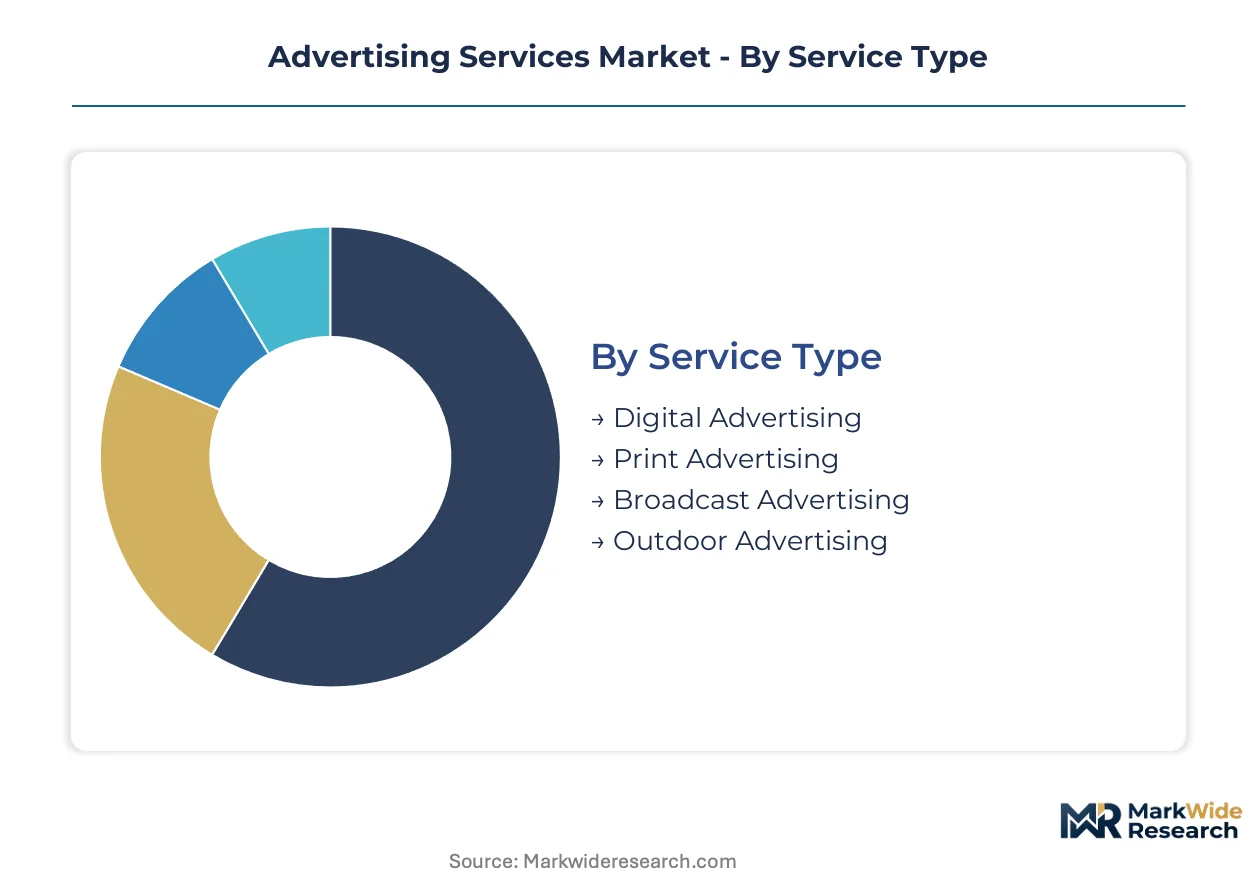
Segmentation in advertising services reveals where capital allocation and capability investments concentrate. Advertisers prioritize segments offering measurable attribution and privacy-compliant targeting infrastructure.
Service Type:
Capital intensity varies sharply across service types, with digital infrastructure demanding sustained technology investment while traditional formats require fixed asset deployment.
- Digital Advertising:Encompasses programmatic display, search, social, and retail media inventory traded through automated platforms. Demand concentrates in the United States where retail media networks and connected TV inventory capture dominant budget flows from brand advertisers seeking closed-loop attribution.
- Broadcast Advertising:Includes linear television and radio placement negotiated through upfront markets and scatter inventory. Corporations in automotive and consumer packaged goods sustain investment here despite audience fragmentation, driven by television-scale reach for brand-building campaigns.
- Print Advertising:Newspaper and magazine placement with declining volume share. Remains relevant for local business targeting and luxury brand adjacencies in specific European markets with aging readership demographics.
- Outdoor Advertising:Billboards, transit shelters, and digital out-of-home networks requiring physical asset deployment. Transit authorities and municipal governments control inventory access in dense urban corridors.
Digital Advertising absorbs the bulk of installed capacity; Broadcast Advertising is expanding most quickly through connected TV convergence.
Client Type:
Procurement sophistication and budget scale differentiate client segments, determining service configuration and pricing architecture.
- Corporations:Multinational advertisers with dedicated procurement teams and annual media commitments exceeding thresholds for direct platform negotiations. In-house studios and data science teams are hardening across Fortune 500 CPG and automotive advertisers in the United States, reducing agency dependency.
- Small Businesses:Local and regional advertisers relying on self-serve platforms and managed service tiers from major technology platforms. Meta and Google dominate this segment through automated campaign tools with minimal human intervention.
- Government Agencies:Public health, tourism, and electoral campaigns with strict procurement regulations and transparency mandates. FTC disclosure requirements and EU public procurement directives constrain vendor selection and creative approval workflows.
- Non-Profits:Cause-driven organizations accessing donated or discounted inventory through platform grant programs. Measurement emphasis falls on awareness metrics rather than conversion attribution.
Corporations command the deepest agency relationships; Small Businesses are gaining share fastest through platform self-serve automation.
Delivery Model:
Organizational boundaries between advertiser and service provider are restructuring as technology enables direct capability ownership.
- In-House:Advertiser-employed teams managing strategy, creative, and media execution internally. Requires substantial fixed investment in talent and technology infrastructure, now standard among large US-based retailers and direct-to-consumer brands.
- Agency-Supported:Full-service or specialized agencies retained on retainer or project basis. WPP, Omnicom, and Publicis compete here through technology-led consolidation of media buying and first-party data infrastructure.
- Freelance:Individual contractors engaged for creative production, media planning, or analytics. Creator economy platforms professionalize this segment under FTC influencer disclosure mandates.
- Collaborative:Hybrid arrangements combining in-house strategy with external execution for specific channels or campaigns. Emerging as default configuration for mid-market advertisers balancing control with flexibility.
Agency-Supported retains the largest installed base; In-House is climbing the fastest as advertisers internalize data capabilities.
Technology:
Technology segmentation tracks where automation and data infrastructure investments flow, determining competitive differentiation.
- Data Analytics:Attribution modeling, customer journey mapping, and predictive segmentation tools. Expanding fastest as advertisers demand closed-loop measurement across fragmented touchpoints, constrained by signal loss from Apple's ATT framework and browser cookie deprecation.
- Programmatic Advertising:Real-time bidding infrastructure and demand-side platforms for automated inventory procurement. Cloud concentration in AWS, Google Cloud, and Azure creates cost vulnerabilities for platform operators.
- Social Media Marketing:Native advertising and organic content management across Meta, TikTok, and LinkedIn. EU AI Act transparency requirements are reshaping algorithmic targeting capabilities for European campaigns.
- SEO Tools:Search engine optimization platforms for organic visibility and technical site management. Google Search algorithm updates and Helpful Content system changes force continuous capability reinvestment.
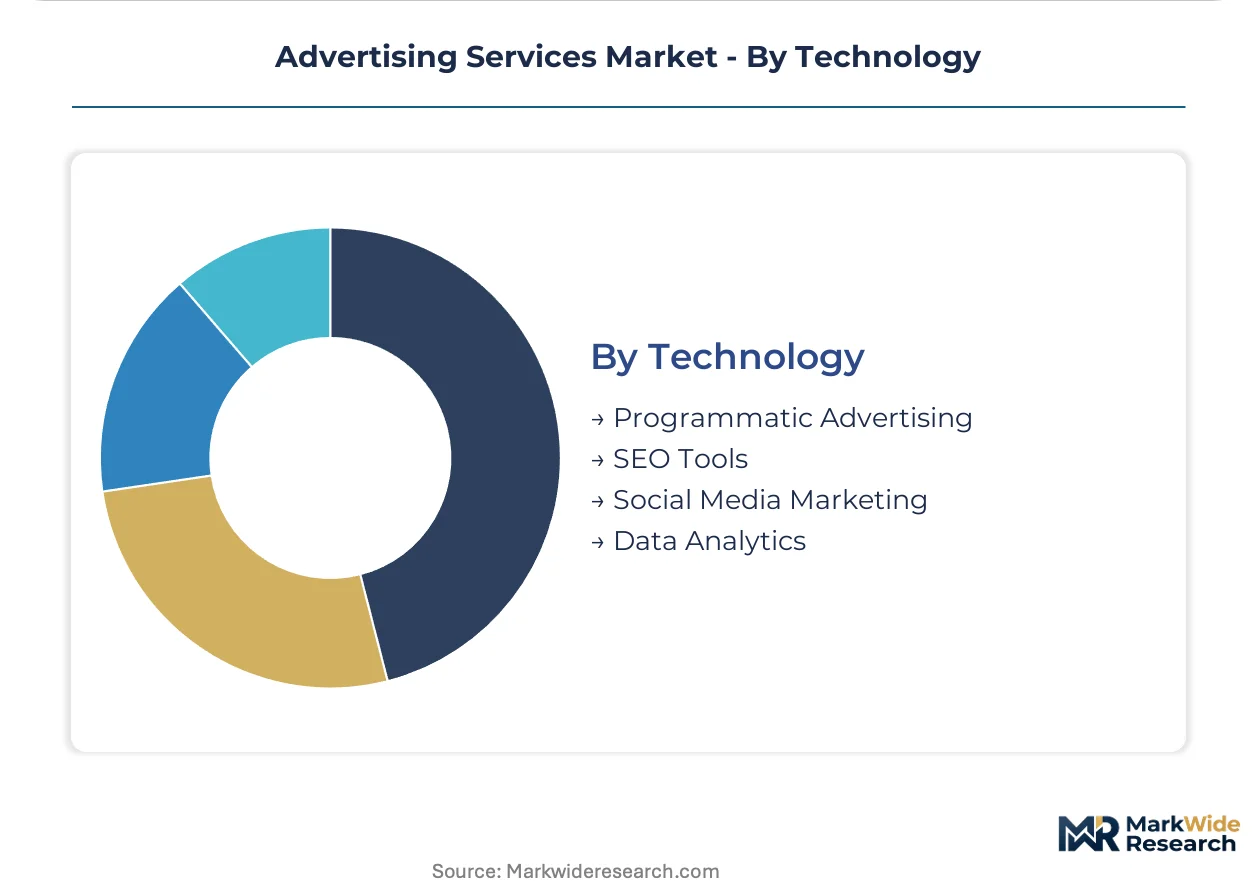
Programmatic Advertising holds the deepest technology investment; Data Analytics is gaining share fastest as measurement demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertising Services Market demand concentrates in the United States, where connected TV inventory and retail media networks capture dominant shares of national ad spend. The EU AI Act and GDPR enforcement are tightening algorithmic transparency requirements for ad-tech platforms reaching European consumers. China's SAMR scrutinizes data collection practices in programmatic ecosystems.
United States
Connected TV inventory and retail media networks drive budget concentration as Fortune 500 CPG and automotive advertisers build internal studios and data science teams. The FTC enforces transparency in influencer marketing and native advertising disclosures, reshaping creative production workflows. New York and Los Angeles anchor media buying and creative production clusters where agency-to-in-house sourcing is hardening.
China
E-commerce platforms expand programmatic ad budgets as first-party data strategies replace cookie-based targeting in the world's largest digital advertising market. SAMR scrutinizes data collection practices in programmatic ecosystems, constraining cross-border data flows. Beijing and Shanghai host dominant ad-tech infrastructure clusters where local platforms compete with multinational technology intermediaries.
United Kingdom
Integrated customer experience platforms spanning CRM and commerce attract investment from multinational advertisers seeking closed-loop attribution. GDPR enforcement actions against Meta have established precedent for fines tied to unlawful data processing for ad targeting. London concentrates media buying expertise and fintech-adjacent advertising innovation clusters.
Germany
Automotive and industrial advertisers sustain broadcast advertising investment despite audience fragmentation, driven by television-scale reach for brand-building campaigns. The European Data Protection Board's consistency mechanism harmonizes penalty frameworks across member states. Munich and Hamburg anchor creative production and automotive advertising specialization clusters.
Japan
Traditional media buying retains significance as established advertisers balance digital expansion with legacy channel relationships. METI guidelines shape data governance expectations for programmatic platforms operating in the market. Tokyo concentrates the headquarters of Hakuhodo DY Holdings and other domestic agency networks competing with global holding companies.
Advertising Services Market Vendor Landscape
Technology-led consolidation dominates the current landscape as holding companies acquire data infrastructure and creative technology assets. The vendor base concentrates among global agency networks, consulting firms with marketing capabilities, and independent specialists serving regional markets. Three archetypes define competitive positioning: integrated holding companies with first-party data infrastructure, consulting-origin players embedding advertising within digital transformation services, and independent agencies defending creative differentiation. M&A activity and in-house capability builds represent the dominant competitive moves reshaping service provider relationships.
Within the integrated holding company tier, WPP plc, Omnicom Group Inc., and Publicis Groupe S.A. occupy positions defined by technology-led consolidation of media buying and creative production. WPP sustains its position through consolidated infrastructure spanning media buying and creative production. Omnicom differentiates via integrated customer experience platforms spanning CRM and commerce. Publicis leverages first-party data infrastructure to compete directly with walled-garden platforms. These three exemplify how scale and technology investment define competitive viability as advertisers internalize data capabilities and reduce agency dependency.
| Leading Market Players |
|---|
| WPP plc |
| Omnicom Group Inc. |
| Publicis Groupe S.A. |
| Dentsu Group Inc. |
| The Interpublic Group of Companies Inc. |
| Havas S.A. |
| Stagwell Inc. |
| Accenture plc |
| Hakuhodo DY Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Data science talent concentration in the United States and United Kingdom widens pricing-tier spreads between premium managed-service engagements and automated self-serve platforms, as labor-cost differentials in probabilistic modeling expertise force tier separation between human-led strategy and algorithmic execution.
Pricing Analysis
Service-bundling unbundles creative production from media buying and measurement, with premium engagements retaining integrated strategy-execution while economy tiers strip out human oversight for pure programmatic access. Pricing stratifies across premium, standard, and economy tiers based on customization depth and first-party data infrastructure ownership. Cost compression in the self-serve tier intensifies as Meta and Google automate campaign management, eroding agency markup capture. Small businesses exhibit highest price sensitivity, while Fortune 500 advertisers prioritize attribution accuracy over rate negotiation.
Supply Chain Analysis
Dual-sourcing requirements from enterprise advertisers mandate qualification of multiple demand-side platforms and clean-room providers, fragmenting technology vendor concentration despite cloud infrastructure dominance. Supply concentrates in the United States, United Kingdom, and China for ad-tech development, with creative production clusters anchored in Los Angeles, London, and Tokyo. Raw material dependencies span cloud compute from AWS, Google Cloud, and Azure, creator talent pools, and first-party data assets. Single-source vulnerability in cloud infrastructure creates resilience risk for platform operators. Distribution runs through direct platform relationships, agency holding companies, and self-serve interfaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data science talent scarcity props pricing power for providers owning probabilistic modeling capabilities, constraining supply expansion as advertisers internalize attribution infrastructure.
For Market Incumbents: Anticipate continued agency disintermediation by accelerating first-party data infrastructure investments that mirror walled-garden platform capabilities. Consolidate measurement and creative technology assets to defend retainer relationships against in-house builds. Vertical integration into clean-room technology and differential privacy tooling offers defensive positioning as signal loss degrades third-party alternatives.
For New Entrants and Emerging Players: The mid-market price-point gap between premium holding-company retainers and pure self-serve automation opens white-space for modular service layers targeting mid-market advertisers balancing control with flexibility. Commerce media verticals beyond retail—travel, financial services, healthcare—remain underpenetrated for closed-loop attribution platforms. A vertical-specialist go-to-market anchored in industry-specific measurement protocols accelerates credibility establishment against generalist competitors.
For Investors and Strategic Acquirers: Re-rating potential sits with independent measurement and identity-resolution specialists given regulatory enforcement accelerating demand for privacy-compliant attribution alternatives. Long-term viability across the forecast horizon favors providers with durable data partnerships and technical differentiation in probabilistic modeling. The signal to watch is FTC disclosure-rule expansion into synthetic media and generative AI advertising, which would force capability reinvestment across the vendor base.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Buildout | Enables closed-loop attribution as cookie deprecation eliminates cross-site tracking for European and North American campaigns. |
| Clean-Room Technology Partnership | Privacy-preserving collaboration environments satisfy GDPR and EU AI Act requirements for algorithmic transparency in audience targeting. |
| Creator Economy Platform Integration | FTC disclosure mandates professionalize influencer economics and open budget flows to verified measurement providers. |
| Retail Media Network Expansion | Non-retail verticals leverage transaction data to capture ad budgets migrating from traditional display and search channels. |
| Explainable AI Tool Deployment | EU AI Act transparency requirements reshape algorithmic optimization capabilities for campaigns reaching European consumers. |
Methodological Framework
Independent corroboration across media buying executives, ad-tech platform engineers, brand-side marketing procurement leads, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with demand-side platform operators, clean-room technology providers, and creator economy platform managers combined with secondary validation from SEC filings, IAB industry reports, and enforcement action databases from the FTC and European Data Protection Board. Bottom-up triangulation across service-type revenue flows and top-down validation against holding-company financial disclosures anchored market sizing.
Comparable-period anchoring to historical advertising expenditure patterns across digital, broadcast, and out-of-home channels established the forecast baseline. The analytical framework models segmentation dimensions spanning service type, client type, delivery model, and technology infrastructure across the projection horizon. CAGRs derive from regression analysis against macroeconomic indicators and advertising intensity ratios. Forecast inputs incorporate programmatic infrastructure investment cycles, retail media network expansion trajectories, and regulatory enforcement probability assessments.
Inputs from platform operator disclosures and holding-company financial filings were available through the study window; gaps in privately held ad-tech firm financials introduce uncertainty bands around emerging segment estimates. Deviation in EU AI Act enforcement intensity or FTC disclosure-rule expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
Europe Programmatic Advertising Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Smart Advertising Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
Global Music Copyright Market