
 Magazine Advertising Market | 2026-2036
Magazine Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Magazine Advertising Market Intelligence
Programmatic inventory management is decoupling ad placement from traditional insertion-order workflows, letting publishers sell remnant space through automated pipelines. WPP plc leverages its GroupM trading desk to bundle print with digital reach extension. Omnicom Group anchors magazine spend within integrated media plans that span OTT and social. Publicis Groupe differentiates through Epsilon data overlays that match subscriber files against CRM segments.
Magazine advertising comprises paid promotional placements within periodical publications, typically produced through gravure or offset lithography on coated paper stocks weighing 60–100 lbs, designed to deliver brand messaging to targeted readerships with dwell time exceeding digital formats. Display ads occupy the largest revenue pool among ad types, while sponsored content commands expanding share as editorial-advertising boundaries blur. Consumer magazines retain the deepest advertiser relationships, though niche publications attract higher CPMs from specialized B2B buyers.
The Federal Trade Commission enforces native advertising disclosure rules that shape how sponsored content must be labeled in US magazines, while the EU's GDPR constrains subscriber data use for ad targeting across European titles. The Advertising Standards Authority in the UK polices misleading environmental claims on paper sourcing, pressuring publishers toward chain-of-custody certification. Stakeholders must weigh print's attention-quality advantage against mounting pressure to demonstrate carbon-accountable supply chains.
Market Dynamics
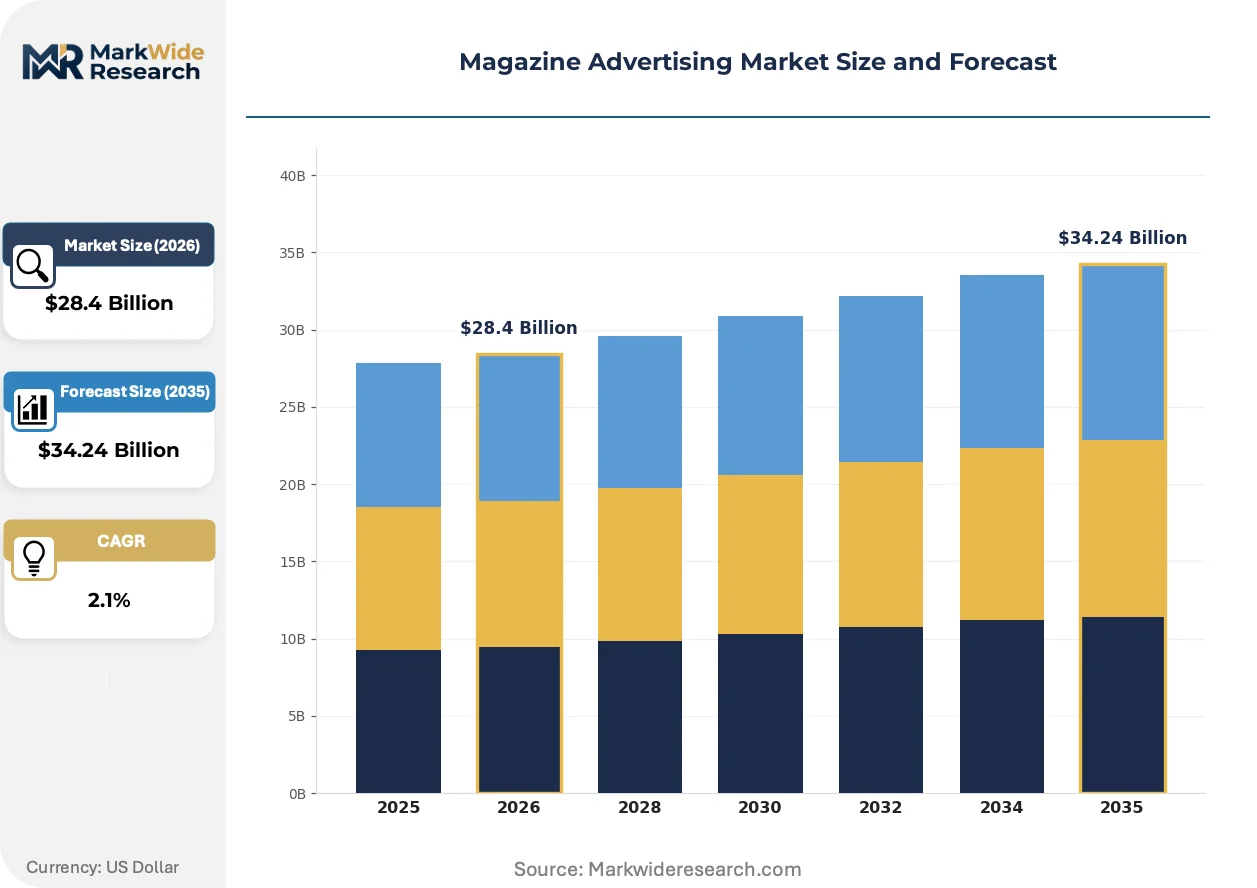
Programmatic trading infrastructure is fragmenting magazine advertising's traditional rate-card hierarchy, compressing premium inventory valuation while expanding addressable remnant supply through automated yield management.
Growth Catalysts
- EU Green Deal paper mandates:Chain-of-custody certification requirements for recycled stock are differentiating compliant publishers in sustainability-conscious advertiser RFPs.
- Luxury goods tactile storytelling:High-end cosmetics and fashion houses continue prioritizing gravure-printed placements for unboxing-adjacent brand experiences.
- Subscriber data monetization:First-party audience files enable precision targeting that competes with digital CPM efficiency in privacy-restricted environments.
Market Restraints
- Pulp cost volatility:Coated mechanical paper prices fluctuate with Scandinavian pulp mill capacity constraints and energy input spikes.
- Postal rate compression:United States Postal Service periodical rate increases erode subscriber acquisition economics for regional titles.
- Digital-native substitution:Programmatic display and connected TV capture brand budgets previously allocated to print awareness flights.
Strategic Opportunities
- India's premium lifestyle verticals:English-language titles in Mumbai and Delhi attract multinational luxury entrants seeking affluent readership concentration.
- Carbon-accountability integration:Scope 3 emissions tracking aligns magazine placements with corporate net-zero procurement mandates.
- QR-to-commerce bridging:Printed augmented reality triggers connect static pages to shoppable digital experiences, closing attribution gaps.
Industry Challenges
- Gravure cylinder lead times:Eight-week production windows for high-volume rotogravure runs conflict with agile campaign activation timelines demanded by performance marketers.
- GDPR-compliant audience matching:European publishers face technical complexity harmonizing subscriber PII with advertiser CRM segments under consent-layer restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magazine Advertising Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $34.24 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Type: Display Ads, Classified Ads, Inserts, Sponsored Content Publication Type: Consumer Magazines, Trade Magazines, Digital Magazines, Niche Publications Advertiser Type: Brands, Small Businesses, Agencies, Nonprofits Distribution Channel: Subscription, Newsstand, Direct Mail, Retail |
| Companies Covered | Interpublic Group, Havas Group, WPP plc, Accenture Song, Stagwell Inc., Omnicom Group, Dentsu Group, BlueFocus, Publicis Groupe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magazine Advertising Market Strategic Shifts & Innovations
Automation is penetrating every layer of magazine advertising operations, from inventory yield optimization through creative production pipelines, compressing traditional workflow timelines while expanding accessible scale for mid-market advertisers.
Dynamic creative optimization software is automating variant generation for print-to-digital extension campaigns. Mid-tier consumer brands now deploy personalized cover wraps and regional insert combinations without manual studio intervention. This compression of production economics is automating access to customization previously reserved for largest-spend accounts.
The EU's Corporate Sustainability Reporting Directive mandates supply-chain emissions disclosure for large advertisers, extending accountability to media placement decisions. Publishers holding FSC or PEFC certification gain preferred-vendor status in audited procurement processes. European fashion and cosmetics verticals are responding by embedding paper provenance requirements into annual media agency briefs.
Buyer concentration among holding-company media trading desks is consolidating negotiation leverage against individual publishers. Independent titles are responding through cooperative sales consortiums and shared audience data cooperatives. This consolidation dynamic is most visible in the United Kingdom and Germany, where legacy mastheads face rate-card pressure from bundled print-digital guarantees.
Magazine Advertising Market Segmentation
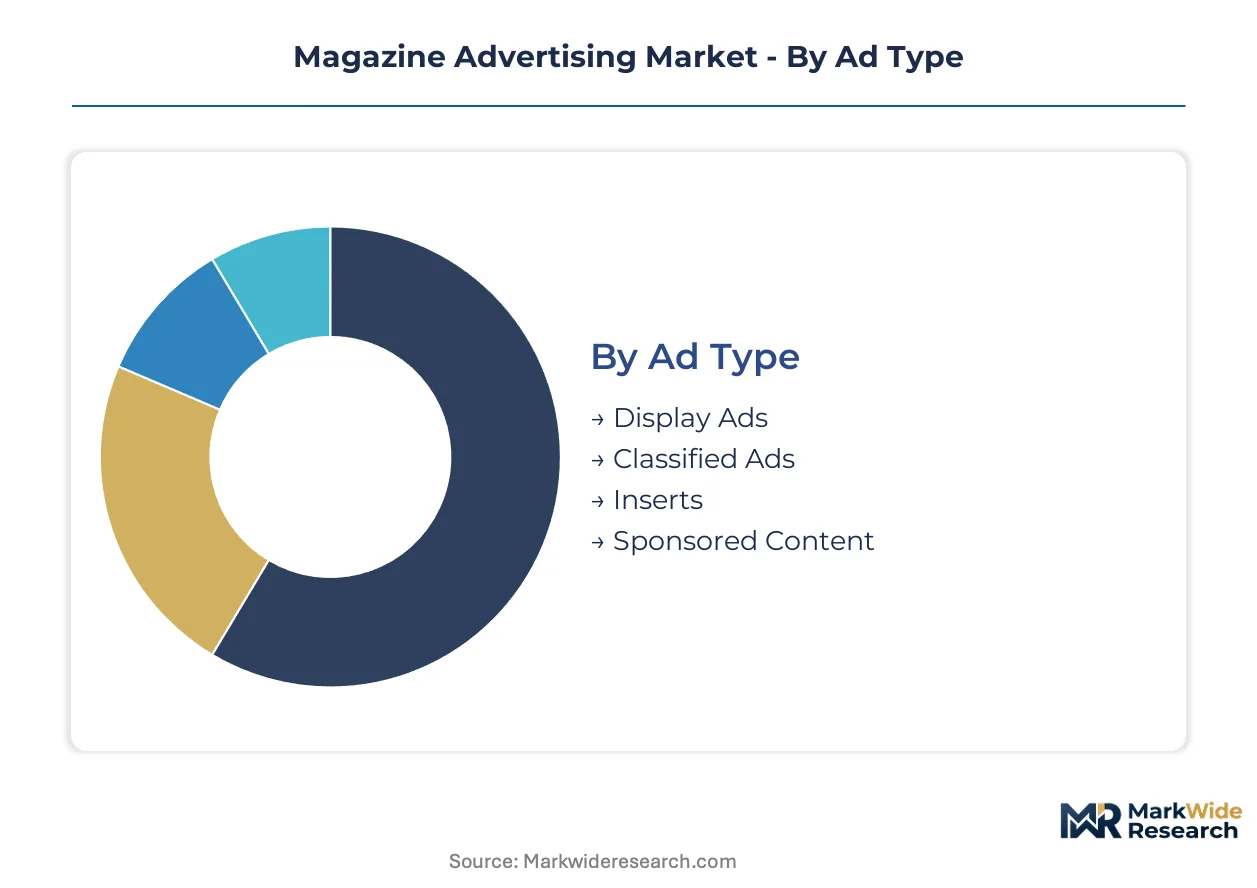
Magazine advertising segmentation reveals how inventory configuration, audience composition, and distribution mechanics shape pricing power and campaign performance across distinct buyer profiles. Understanding these dimensions enables publishers to optimize yield management and advertisers to match format selection with communication objectives.
Ad Type:
Standardization dominates high-volume placements while customization concentrates in premium sponsorships that merge editorial voice with brand narrative.
- Display Ads:Full-page and spread formats printed on coated stock deliver visual impact through gravure or offset lithography. Luxury cosmetics and automotive manufacturers in the United States concentrate spend here, driven by tactile brand storytelling requirements that digital formats cannot replicate.
- Sponsored Content:Native editorial integrations require FTC-compliant disclosure labeling and blend advertiser messaging with publication voice. Fashion houses and lifestyle brands seeking unboxing-adjacent experiences are expanding allocations, constrained by eight-week gravure cylinder lead times that conflict with agile activation timelines.
- Classified Ads:Text-dense recruitment and real estate listings occupy back-matter positions with minimal production overhead.
- Inserts:Pre-printed flyers and samples bound into circulation provide direct-response mechanics with postal-rate exposure.
Most installed capacity flows through Display Ads. Expansion is steepest in Sponsored Content.
Publication Type:
Volume scale inversely correlates with audience specificity, with mass-reach titles commanding rate-card premiums through scarcity while niche publications extract higher CPMs from specialized B2B buyers.
- Consumer Magazines:Glossy lifestyle and fashion titles with national circulation anchor legacy advertiser relationships. Legacy mastheads in the United Kingdom and Germany retain premium pricing power through bundled print-digital guarantees, though cooperative sales consortiums among independent titles are compressing negotiation leverage.
- Niche Publications:Hyper-specialized verticals serving discrete professional communities command elevated CPMs from B2B buyers seeking concentrated decision-maker access. Medical and legal sector titles in Mumbai and Delhi attract multinational entrants targeting affluent readership concentration.
- Trade Magazines:Industry-specific periodicals deliver procurement-influencer audiences with measurable engagement metrics.
- Digital Magazines:Tablet-optimized replicas and web-native formats extend reach with programmatic inventory management.
Revenue concentration sits with Consumer Magazines. Climbing the fastest are Niche Publications.
Advertiser Type:
Procurement sophistication separates enterprise-scale commitments with integrated agency management from self-serve placements with compressed creative cycles.
- Agencies:Holding-company trading desks consolidate negotiation leverage through bundled media plans spanning OTT, social, and print extension. WPP plc and Omnicom Group anchor magazine spend within cross-channel strategies, while Publicis Groupe differentiates through Epsilon data overlays matching subscriber files against CRM segments.
- Brands:Direct advertiser relationships with publishers enable customized cover wraps and regional insert combinations without intermediary margin.
- Small Businesses:Local service providers utilize remnant space through automated yield management pipelines.
- Nonprofits:Cause-driven organizations leverage donated or discounted inventory for awareness campaigns.
Transaction volume concentrates through Agencies. Gaining share fastest are Brands pursuing direct publisher relationships.
Distribution Channel:
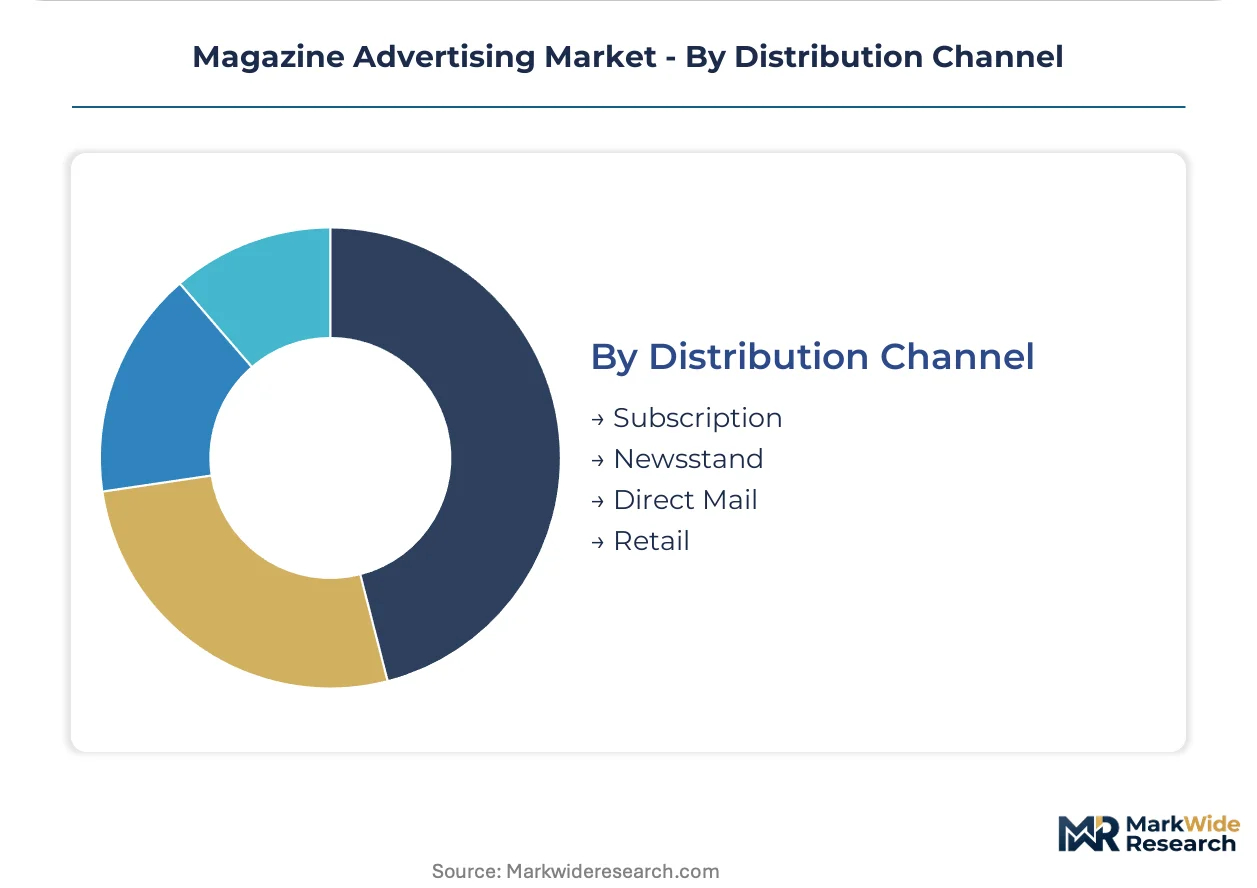
Subscriber acquisition economics vary sharply across fulfillment mechanics, with postal-rate structures and retail commission frameworks reshaping margin profiles.
- Subscription:Guaranteed circulation enables first-party data monetization and precision targeting that competes with digital CPM efficiency. United States Postal Service periodical rate increases are eroding economics for regional titles, pushing publishers toward digital extension and QR-to-commerce bridging.
- Newsstand:Impulse-driven single-copy sales concentrate in airport terminals and urban retail corridors with high dwell-time environments.
- Direct Mail:Addressed distribution bypasses retail intermediaries but carries postage cost exposure.
- Retail:Big-box and grocery channel placements capture mass-market browsing behavior with revenue-share arrangements.
Circulation scale flows through Subscription. Steepest expansion trajectory belongs to Newsstand in travel-hub locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where publishers concentrate premium inventory production, with EU Green Deal compliance costs driving some gravure capacity toward jurisdictions with less stringent chain-of-custody mandates while legacy markets defend rate-card power through first-party data depth.
United States
Legacy mastheads in New York and Los Angeles retain premium pricing through bundled print-digital guarantees, with luxury cosmetics and automotive manufacturers prioritizing tactile brand storytelling. FTC native advertising disclosure rules shape how sponsored content must be labeled across titles. Chicago and Dallas publishing clusters are experimenting with QR-to-commerce bridging to close attribution gaps.
Germany
Holding-company trading desks in Frankfurt and Munich consolidate negotiation leverage against individual publishers through bundled media plans. EU Green Deal paper mandates push publishers toward FSC or PEFC certification to differentiate in sustainability-conscious advertiser RFPs. The Hamburg-Berlin corridor hosts cooperative sales consortiums among independent titles responding to rate-card pressure.
United Kingdom
The Advertising Standards Authority polices misleading environmental claims on paper sourcing, pressuring publishers toward chain-of-custody certification. London anchors legacy advertiser relationships with glossy lifestyle and fashion titles, though independent mastheads face compression from bundled print-digital guarantees. Manchester and Birmingham regional titles are eroding subscriber acquisition economics under Royal Mail rate pressures.
France
Paris-based fashion houses expand sponsored content allocations seeking unboxing-adjacent brand experiences, constrained by eight-week gravure cylinder lead times. GDPR constrains subscriber data use for ad targeting across European titles, creating technical complexity for audience matching. The Lyon publishing cluster is developing carbon-accountability integration to align with corporate net-zero procurement mandates.
India
English-language titles in Mumbai and Delhi attract multinational luxury entrants seeking affluent readership concentration. BIS standards influence paper quality specifications for imported coated stocks. The Bangalore-Hyderabad corridor is emerging as a testing ground for programmatic inventory management in premium lifestyle verticals.
Magazine Advertising Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with holding-company media trading desks consolidating negotiation leverage against individual publishers while independent titles respond through cooperative sales consortiums. The vendor base stratifies into three archetypes: integrated agency networks bundling cross-channel reach, data-enabled specialists monetizing first-party subscriber files, and programmatic infrastructure providers automating remnant yield. Dominant competitive moves include M&A to capture data assets and strategic partnerships to embed carbon-accountability tracking into media procurement workflows.
Within the integrated agency network tier, WPP plc and Omnicom Group exemplify the scale-driven archetype, with the former leveraging its GroupM trading desk to bundle print with digital reach extension. Publicis Groupe occupies a differentiated position through Epsilon data overlays that match subscriber files against CRM segments. Among Asia-Pacific-based operators, BlueFocus represents the emerging-market specialist archetype.
| Leading Market Players |
|---|
| Interpublic Group |
| Havas Group |
| WPP plc |
| Accenture Song |
| Stagwell Inc. |
| Omnicom Group |
| Dentsu Group |
| BlueFocus |
| Publicis Groupe |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between FSC-certified premium inventory and uncertified commodity stock shapes divergent pricing power and sourcing configurations across the magazine advertising supply chain. EU Green Deal compliance costs concentrate in Scandinavian pulp mills while legacy publishers in the United States and United Kingdom defend rate-card premiums through first-party data depth.
Pricing Analysis
Agency trading desk margins compress publisher rate-cards through bundled print-digital guarantees, while direct-to-brand relationships enable customized cover-wrap premiums. Price differentiation rests on chain-of-custody certification and subscriber file granularity, with luxury cosmetics manufacturers least sensitive and regional B2B buyers most responsive to CPM fluctuations. Pricing pressure intensifies as programmatic pipelines expand addressable remnant supply without editorial scarcity premiums.
Supply Chain Analysis
Gravure cylinder engraving talent concentrates in Germany, Italy, and Japan, constraining high-volume rotogravure capacity expansion. Coated mechanical paper draws from Scandinavian pulp mills, with energy input volatility and EU emissions trading scheme exposure creating margin instability. Single-source vulnerability sits with gravure cylinder suppliers for fashion-sector glossies. Distribution runs through postal networks in subscription-heavy markets and retail commission structures in newsstand-dependent geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
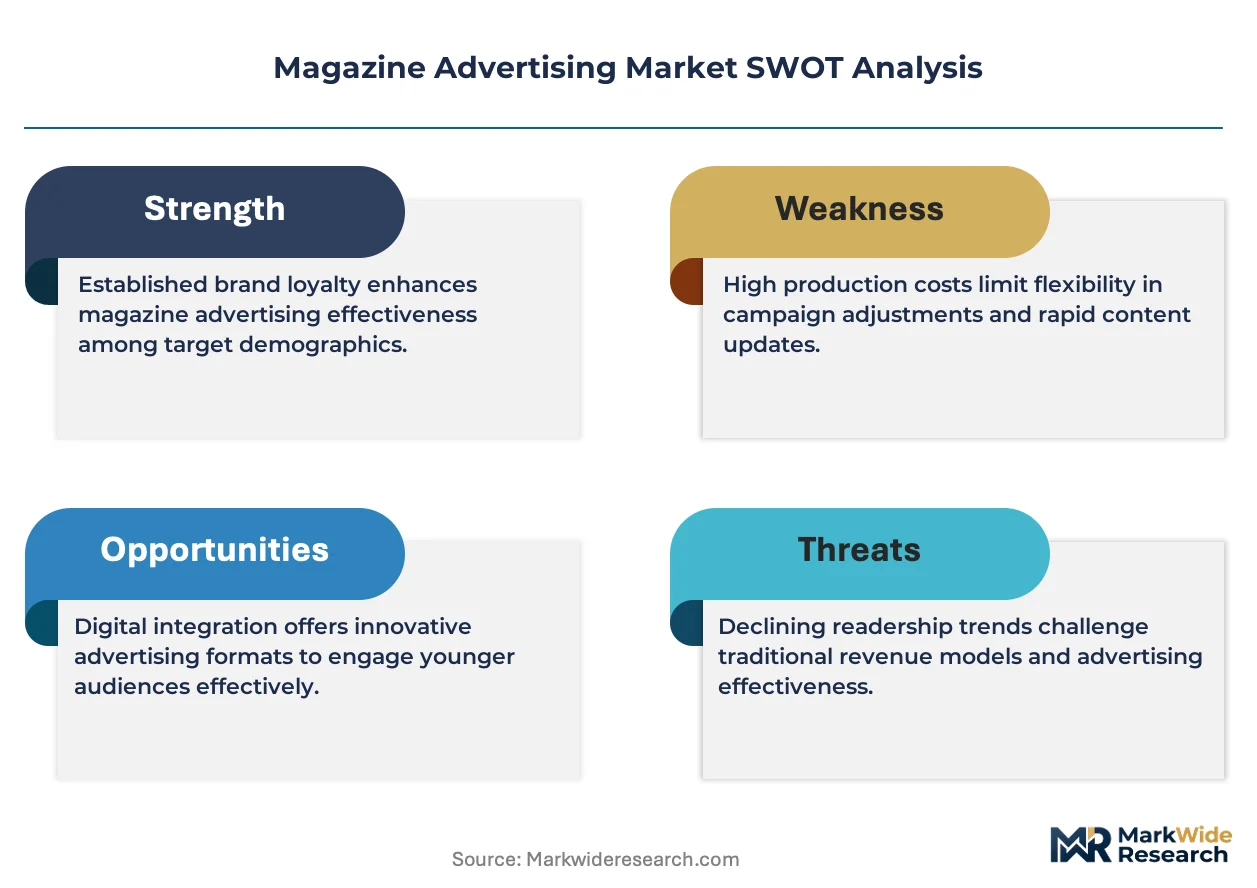
Magazine advertising functions as a stable compounder where luxury brand tactile storytelling requirements sustain premium inventory valuation against digital substitution pressures.
For Market Incumbents: Extend first-party data monetization capabilities through Epsilon-style CRM matching investments, defending against holding-company trading desk consolidation. Secure FSC or PEFC certification to capture EU advertiser procurement mandates. Build QR-to-commerce attribution infrastructure to close performance-marketer activation gaps.
For New Entrants and Emerging Players: Programmatic yield optimization platforms offer white-space entry against legacy insertion-order workflows. Target India's English-language lifestyle verticals in Mumbai and Delhi where multinational luxury entrants seek concentrated affluent readership. Pursue cooperative sales consortium models to match bundled negotiation leverage of established trading desks.
For Investors and Strategic Acquirers: Consolidation pressure builds where independent titles face rate-card compression from bundled print-digital guarantees. Long-term viability favors publishers with authenticated subscriber files and carbon-accountable supply chains. Monitor EU Corporate Sustainability Reporting Directive enforcement as inflection signal for certified-inventory premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Investment | Subscriber file matching against advertiser CRM segments enables precision targeting that competes with digital CPM efficiency. |
| Chain-of-Custody Certification Program | FSC or PEFC certification aligns magazine placements with EU Green Deal procurement mandates and corporate net-zero requirements. |
| Programmatic Yield Management Platform | Automated remnant inventory pipelines expand addressable scale for mid-market advertisers without manual insertion-order workflows. |
| QR-to-Commerce Attribution Bridge | Printed augmented reality triggers connect static pages to shoppable digital experiences, closing performance-marketer activation gaps. |
| Cooperative Sales Consortium Formation | Shared audience data cooperatives among independent titles consolidate negotiation leverage against holding-company trading desks. |
Research Approach
Multiple input streams — publisher rate-card disclosures, media agency trading desk interviews, and postal service circulation data — were reconciled through bottom-up and top-down triangulation. Primary discussions with magazine publishers, media buying directors at holding companies, gravure cylinder manufacturers, and paper procurement managers were validated against secondary sources including FTC native advertising guidance, EU Green Deal compliance documentation, and Advertising Standards Authority rulings.
Data-stream reconciliation across the projection horizon applied analytical frameworks segmenting by ad type, publication category, advertiser procurement sophistication, and distribution channel mechanics. CAGRs were derived from trend extrapolation of insertion-order volumes and programmatic pipeline growth, with inputs including pulp cost indices, postal rate trajectories, and luxury brand media budget allocations.
The model holds under stable regulatory enforcement of paper sustainability mandates; deviation in EU Green Deal compliance timelines or USPS periodical rate acceleration would shift publisher margin assumptions. Practitioners should monitor FTC native advertising disclosure enforcement and GDPR consent-layer technical developments for early signals of targeting capability constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Social Media Advertisement Market