
 China OOH and DOOH Market | 2026-2036
China OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
China OOH and DOOH Market Insights
Multi-source technology procurement is recalibrating how Chinese operators build their display networks. Focus Media Holding Ltd leverages its elevator screen density to dominate captive-audience environments in residential and office towers. JCDecaux Group sustains premium transit hub concessions through direct municipal partnerships in Shenzhen and Chengdu. Dentsu Inc. anchors integrated media planning services that bundle OOH with digital campaign analytics for multinational brand clients.
Out-of-home and digital out-of-home advertising encompasses static and dynamically addressable display surfaces deployed in public and semi-public spaces, typically employing LED modules with pixel pitches ranging from P2.5 to P10 for varying viewing distances, designed to deliver targeted commercial messaging to audiences outside residential settings. Digital screens within the Media Type category command the highest margin pools due to programmatic trading capabilities and real-time audience measurement, while billboards retain volume leadership in lower-tier city expansions. LED technology leads the Technology segment through energy efficiency gains and outdoor durability, whereas virtual reality integrations remain nascent but attract event marketing budgets seeking immersive brand activations.
SAMR enforces advertising content standards that restrict misleading claims on public displays, while MIIT mandates data security protocols for internet-connected DOOH infrastructure under national cybersecurity frameworks. GB standards specify electromagnetic compatibility and electrical safety thresholds for outdoor digital installations. Stakeholders must weigh compliance costs against the revenue upside of granular audience targeting as regulatory scrutiny intensifies.
Market Dynamics
Programmatic trading infrastructure is absorbing premium inventory across China's tier-one commercial districts, compressing the traditional direct-sales model for digital screen operators while elevating data-driven audience targeting as the primary competitive differentiator.
Growth Catalysts
- MIIT cybersecurity mandates:Mandatory data security protocols for internet-connected displays are forcing network operators to upgrade firmware and encryption layers, creating replacement demand for compliant hardware.
- Retail media networks:Grocery and convenience store chains are deploying captive-audience screens at checkout zones, converting dwell time into incremental ad inventory.
- LED pixel pitch advancement:P2.5 and P3 modules are penetrating indoor transit corridors where viewing distances demand higher resolution than legacy P6-P10 installations.
Market Restraints
- GB electromagnetic compliance:Certification timelines for outdoor digital installations extend 4-8 months, delaying revenue recognition for new screen deployments.
- Shanghai-Shenzhen screen concentration:Premium inventory clusters in these two municipalities, creating pricing volatility when major advertisers shift quarterly budgets.
- Static billboard substitution:Lower-tier cities retain cost advantages for vinyl and paper-based formats, slowing DOOH penetration outside tier-one clusters.
Strategic Opportunities
- Chengdu-Chongqing corridor:Western China metropolitan zones remain under-screened relative to coastal density, offering first-mover concessions in subway and airport terminals.
- SAMR content automation:Regulatory frameworks permitting AI-generated creative pre-approval are enabling real-time dynamic creative optimization for compliant advertisers.
- 5G+edge computing convergence:Low-latency connectivity is absorbing latency-sensitive applications like interactive gesture-based campaigns into DOOH networks.
Industry Challenges
- Programmatic talent scarcity:Operators lack data science and ad-tech engineering capacity to manage demand-side platform integrations and real-time bidding optimization.
- Legacy CMS fragmentation:Proprietary content management systems from disparate hardware vendors complicate unified network management and cross-screen campaign orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China OOH and DOOH Market |
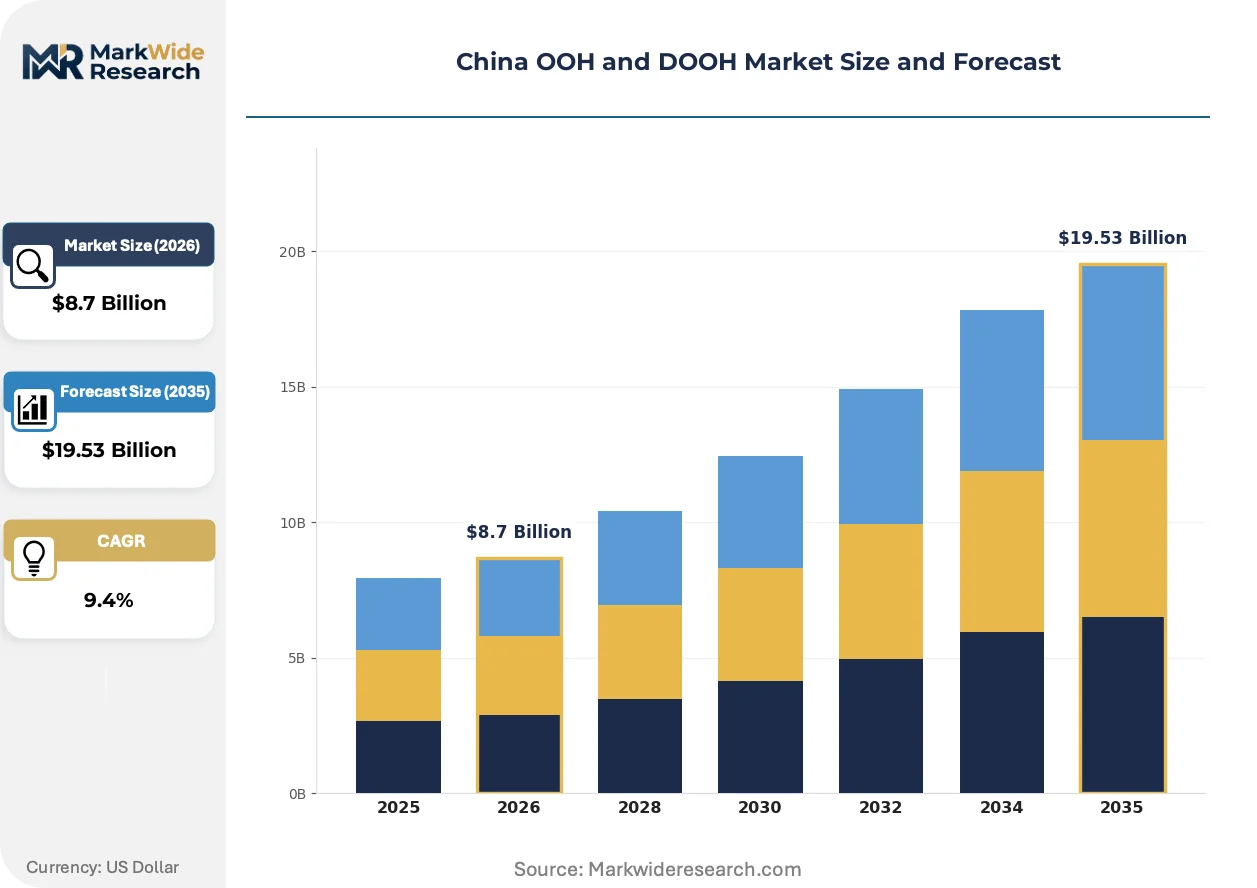
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Digital Screens, Billboards, Kiosks, Posters Application: Advertising, Brand Promotion, Event Marketing, Public Information Technology: LED, LCD, Projection, Virtual Reality Client Type: Retailers, Corporates, Event Organizers, Government |
| Companies Covered | Focus Media Holding Ltd, ChinaDOOH, JCDecaux Group, Hakuhodo Inc., ASIAPAC NET MEDIA LIMITED, Clear Channel Outdoor Holdings Inc., Asiaray Media Group Limited, Outfront Media Inc., Dentsu Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China OOH and DOOH Market Trends and Innovations
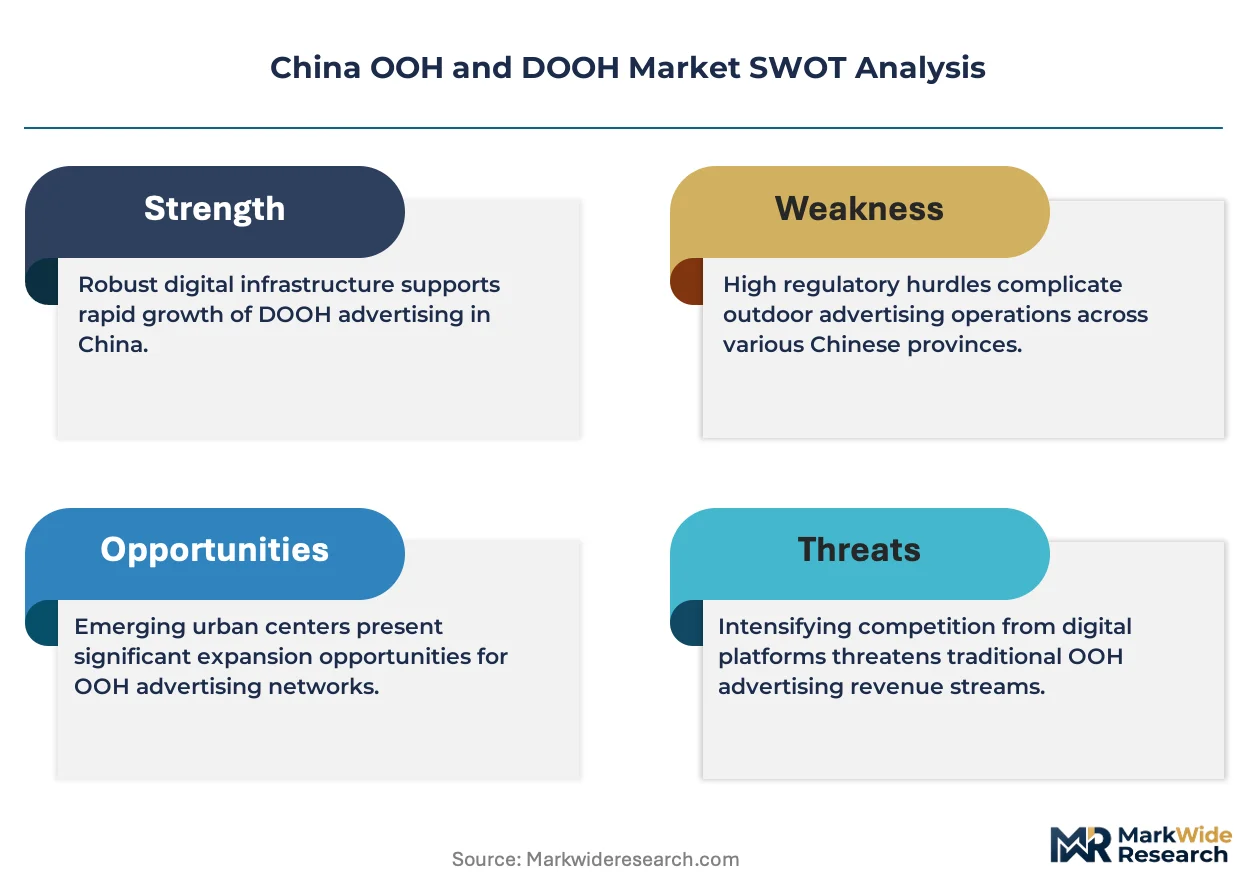
China's OOH operators are absorbing three concurrent pressures: hardware commoditization, regulatory data localization, and advertiser demand for closed-loop attribution. These forces are compressing legacy business models while opening new service layers.
AI-powered audience measurement is absorbing camera-based impression verification into standard campaign reporting. Transit hub operators in Beijing and Shenzhen are adopting computer vision systems that estimate demographics and dwell time without storing biometric data. This capability is absorbing premium rate card premiums from static measurement methods, compressing the value of traditional traffic-count guarantees.
MIIT's data localization requirements are absorbing cross-border cloud infrastructure out of DOOH operations. Network operators must now deploy domestic edge servers for all audience data processing, elevating compliance costs but creating captive vendor relationships with certified local hardware suppliers. Tier-one city deployments face the steepest reconfiguration timelines.
Advertiser procurement is absorbing outcome-based verification clauses into insertion orders. Brand marketers in Shanghai's financial district now demand foot-traffic lift studies and subsequent conversion attribution, displacing legacy CPM-based buying. This pattern is most visible among FMCG and automotive verticals with direct retail distribution networks.
China OOH and DOOH Market Segmentation
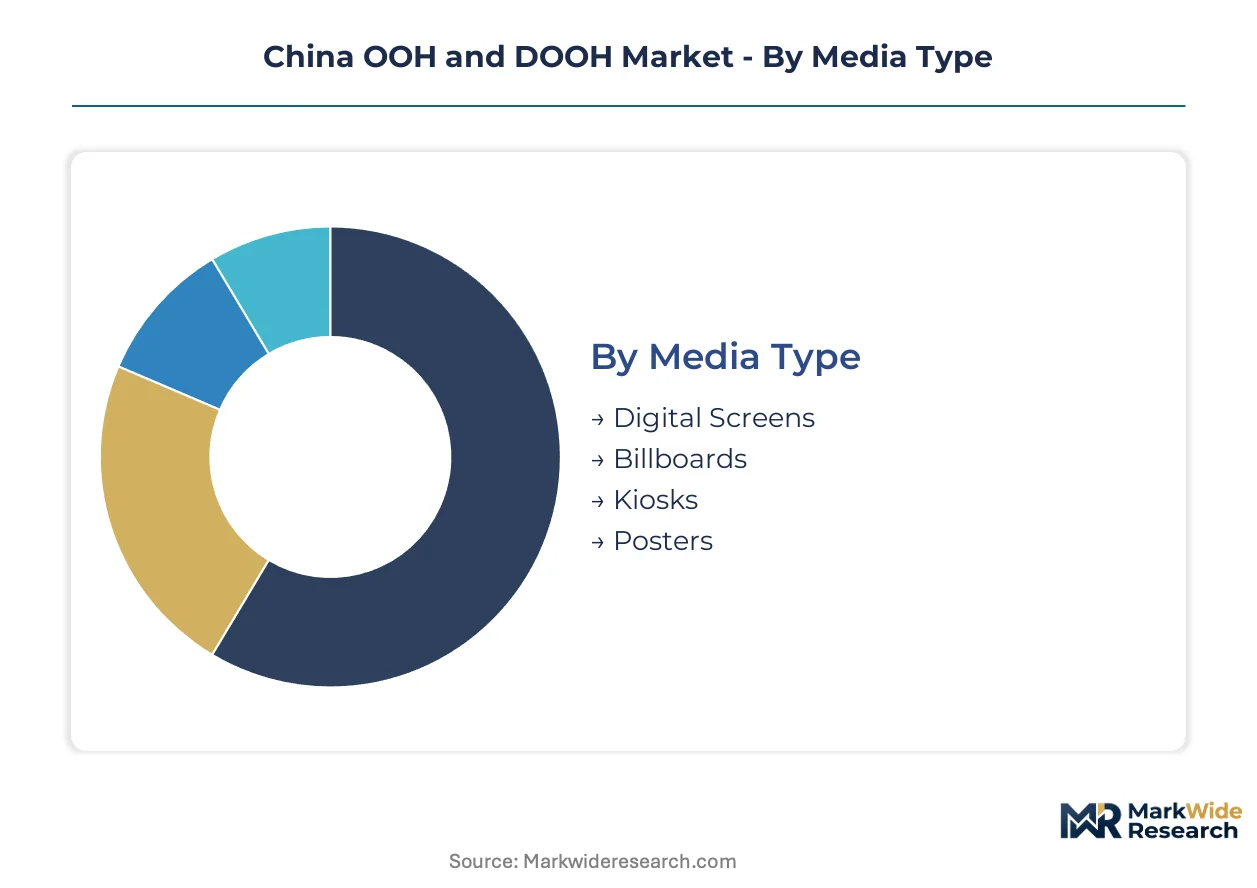
China's OOH and DOOH market fragments across hardware specifications, deployment contexts, and buyer procurement patterns. Segment boundaries shift as programmatic trading absorbs premium inventory and regulatory compliance reshapes technology investment priorities.
Media Type:
Supply concentration clusters around formats with programmatic trading infrastructure and captive-audience deployment potential.
- Digital Screens:LED and LCD modules with P2.5-P10 pixel pitches enable real-time content rotation and audience targeting. Shanghai and Beijing commercial districts absorb premium programmatic inventory as retailers demand closed-loop attribution.
- Billboards:Static vinyl and paper-based formats dominate lower-tier city expansions where DOOH infrastructure costs exceed local advertiser budgets. Chengdu and Chongqing corridors retain volume leadership for traditional roadside installations.
- Kiosks:Interactive touchscreen terminals concentrate in subway stations and airport terminals, converting dwell time into engagement metrics for transit hub operators.
- Posters:Paper-based transit shelter advertising persists in residential districts where municipal concessions favor low-maintenance formats.
Digital Screens absorb the bulk of installed capacity; Kiosks are expanding most quickly through transit hub modernization.
Application:
Cost tier differentiation separates premium brand campaigns from public service deployments with constrained procurement budgets.
- Advertising:Programmatic trading platforms enable real-time bidding on impression-verified inventory. FMCG and automotive verticals in Shanghai's financial district now demand foot-traffic lift studies.
- Brand Promotion:Elevator screen networks in residential and office towers deliver captive-audience exposure during dwell intervals. Focus Media Holding Ltd dominates this channel through density advantages.
- Event Marketing:Temporary LED installations and projection mapping serve product launches and seasonal campaigns. Virtual reality integrations attract immersive activation budgets despite nascent deployment scale.
- Public Information:Government procurement favors compliant hardware meeting GB electromagnetic and MIIT cybersecurity standards for municipal display networks.
Advertising commands the highest revenue concentration; Event Marketing is climbing the fastest as experiential budgets shift from traditional media.
Technology:
Volume deployment favors mature display technologies with established supply chains and certification pathways.
- LED:Energy efficiency gains and outdoor durability sustain market leadership. P2.5 and P3 modules penetrate indoor transit corridors where viewing distances demand higher resolution.
- LCD:Indoor commercial environments favor liquid crystal displays for color accuracy and lower power consumption in climate-controlled settings.
- Projection:Large-format temporary installations serve event marketing and building facade activations with lower capital commitment than fixed LED arrays.
- Virtual Reality:Headset-based and immersive room-scale systems attract experimental brand budgets seeking differentiation through sensory engagement.
LED absorbs the bulk of installed capacity; Virtual Reality is gaining share fastest from a small base as event marketing budgets expand.
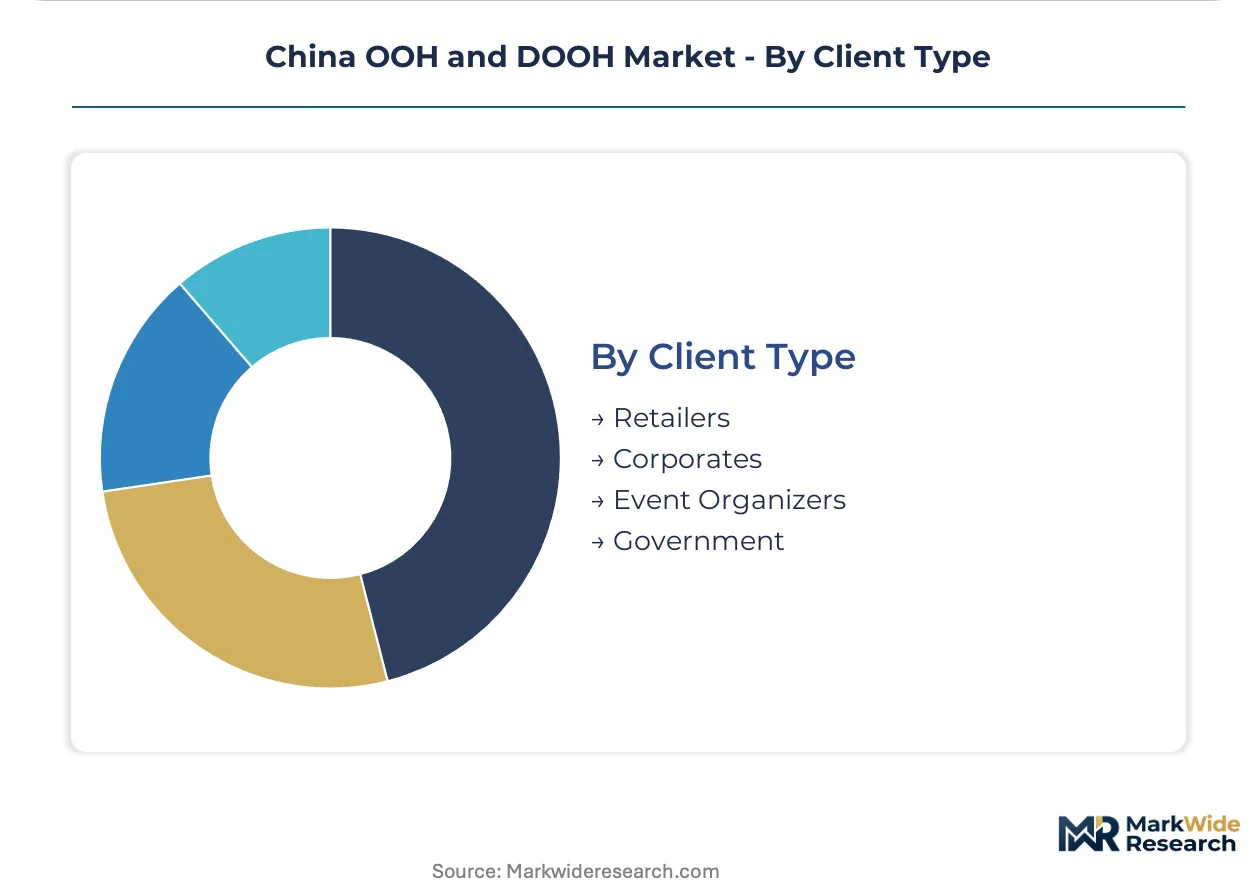
Client Type:
Procurement patterns diverge between multinational brand marketers with integrated media planning and domestic retailers building captive networks.
- Retailers:Grocery and convenience store chains deploy checkout-zone screens to convert dwell time into incremental ad inventory. SAMR content rules constrain promotional messaging.
- Corporates:Multinational brand marketers bundle OOH with digital campaign analytics through agency holding companies. Dentsu Inc. anchors this service layer.
- Event Organizers:Temporary deployment demand concentrates in tier-one cities with venue infrastructure and affluent consumer density.
- Government:Municipal procurement prioritizes GB standards compliance and domestic edge server deployment for MIIT data localization requirements.
Retailers absorb the bulk of installed capacity; Event Organizers are expanding most quickly as experiential marketing recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's eastern coastal corridor where advertiser budgets flow toward high-income consumer density and established programmatic infrastructure.
Yangtze River Delta
Shanghai anchors premium digital screen deployment with elevator networks and transit hub concessions absorbing multinational FMCG spend. MIIT cybersecurity standards mandate domestic edge server deployment for all connected displays. Suzhou and Hangzhou satellite cities expand retail media networks through grocery chain checkout-zone installations.
Pearl River Delta
Shenzhen's technology sector drives demand for high-resolution LED installations in corporate campuses and commercial districts. SAMR advertising content rules restrict misleading claims on public displays. Guangzhou's subway modernization program creates concession opportunities for interactive kiosk operators.
Beijing-Tianjin-Hebei
Government and state-owned enterprise procurement sustains public information display networks across municipal infrastructure. GB electromagnetic compatibility standards extend certification timelines for outdoor digital installations. Beijing's airport and high-speed rail terminals concentrate premium inventory for luxury brand campaigns.
Sichuan-Chongqing
Western China metropolitan zones remain under-screened relative to coastal density, offering first-mover concessions in subway terminals. Dual carbon goals accelerate LED retrofit programs replacing legacy static billboards. Chengdu's consumption-led growth model attracts experiential marketing budgets for temporary event installations.
China OOH and DOOH Market Competitive Landscape
Strategic partnerships dominate the current landscape as operators seek technology integration and municipal concession security. The vendor base organizes around three tiers: elevator network specialists with residential tower density, transit hub concessionaires holding municipal contracts, and integrated media agencies bundling OOH with digital analytics. Competitive moves cluster on concession renewal negotiations, programmatic platform development, and compliance infrastructure upgrades for MIIT data localization.
Among China-based operators, Focus Media Holding Ltd exemplifies the captive-audience archetype through elevator screen density in residential and office towers. JCDecaux Group occupies a position representing premium transit hub concessions through direct municipal partnerships. Dentsu Inc. anchors the integrated services tier, bundling OOH planning with digital campaign analytics for multinational clients.
| Leading Market Players |
|---|
| Focus Media Holding Ltd |
| ChinaDOOH |
| JCDecaux Group |
| Hakuhodo Inc. |
| ASIAPAC NET MEDIA LIMITED |
| Clear Channel Outdoor Holdings Inc. |
| Asiaray Media Group Limited |
| Outfront Media Inc. |
| Dentsu Inc. |
| Others |
Pricing and Supply Chain Analysis
Advertiser demands for MIIT-compliant hardware with domestic edge server deployment are forcing network operators to absorb higher procurement costs for certified LED modules and encrypted firmware stacks, compressing margins on legacy screen deployments while elevating rate cards for premium programmatic inventory in Shanghai and Beijing.
Pricing Analysis
Volume leadership sits with static billboards in lower-tier cities where vinyl and paper formats sustain thin margins, while digital screens command premium pricing through programmatic trading capabilities and real-time audience measurement. Three-tier pricing structure across premium, standard, and economy levels reflects pixel pitch resolution, with P2.5-P3 modules in transit corridors extracting highest rates. Cost compression in standard-tier inventory is intensifying because hardware commoditization erodes differentiation. Municipal procurement for public information displays exhibits highest price sensitivity; multinational FMCG campaigns in tier-one commercial districts show least.
Supply Chain Analysis
Direct-to-operator channels handle hyperscale demand from Focus Media and JCDecaux for standardized LED arrays, while project-based integrators serve event marketing deployments with temporary projection and VR installations. LED module production concentrates in China, South Korea, and Taiwan, with P2.5-P10 driver ICs drawing from semiconductor foundries in Taiwan and South Korea. Supply chain risk rests on single-source vulnerability for high-brightness LED chips from select wafer suppliers. Distribution runs through certified domestic hardware vendors mandated by MIIT data localization requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Screen deployment capacity in tier-one cities faces hard constraints from municipal concession availability and GB electromagnetic certification bottlenecks, propping pricing power for incumbent operators with secured transit hub and elevator network positions.
For Market Incumbents: To counter programmatic talent scarcity eroding demand-side platform integration capabilities, anchor competitive position through backward integration into proprietary content management systems and captive data science hiring pipelines in Shenzhen and Beijing. Secure concession renewals in Chengdu-Chongqing corridor ahead of infrastructure modernization waves. For New Entrants and Emerging Players: Capture under-screened western China metropolitan zones through first-mover subway terminal concessions in Chengdu and Chongqing, where dual carbon goals accelerate LED retrofit demand. Target event marketing verticals with temporary high-resolution LED and projection mapping services, leveraging lower capital commitment than fixed network builds. For Investors and Strategic Acquirers: The window for entry favors operators with secured municipal partnerships and compliant edge server infrastructure already deployed. Long-term viability hinges on programmatic trading platform ownership rather than pure screen density. Monitor SAMR content automation rulemaking as signal for real-time creative optimization capability valuations.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Compliance Infrastructure Upgrade | Domestic edge server deployment satisfies data localization mandates while locking in certified vendor relationships. |
| Programmatic Platform Development | Real-time bidding integration elevates rate card premiums above static traffic-count guarantees in Shanghai. |
| Chengdu-Chongqing Concession Expansion | First-mover subway terminal positions capture western China demand before coastal saturation replicates inland. |
| AI-Powered Audience Measurement Deployment | Computer vision systems enable demographic verification without biometric storage, absorbing premium from static methods. |
| Retail Media Network Partnership | Grocery chain checkout-zone installations convert dwell time into incremental programmatic inventory for FMCG verticals. |
Research Methodology
Document review covered MIIT cybersecurity circulars, SAMR advertising content guidelines, GB electromagnetic compatibility standards, and municipal concession procurement records, complemented by interviews with network operations executives at tier-one city operators, programmatic platform engineers, transit hub concession managers, and LED module procurement leads at display manufacturers. Secondary validation drew from customs trade data for LED component imports, operator SEC filings where available, and municipal infrastructure development budgets. Bottom-up screen deployment counts were triangulated against top-down advertising spend allocation estimates across the analysis window.
Cross-referencing historical deployment trajectories against panel input from network operators and media buyers shaped the analytical framework. Segmentation dimensions modeled include media type, application context, technology tier, pixel pitch specification, and client procurement pattern. CAGRs were derived from installed capacity growth rates and revenue per screen trends. Industry-specific forecast inputs incorporated MIIT compliance timeline assumptions and SAMR content automation rulemaking progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to municipal concession renewal cycles, dual carbon policy acceleration, and 5G infrastructure rollout pace in western China. Forecasts reflect assumptions about advertiser budget shifts toward closed-loop attribution and hardware replacement waves triggered by cybersecurity mandate enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
GCC OOH and DOOH Market