
 Singapore OOH and DOOH Market | 2026-2036
Singapore OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore OOH and DOOH Market Insights
Asset-light leasing models for digital screen networks is reconfiguring competitive entry barriers across Singapore's out-of-home sector. JCDecaux leverages its long-term municipal concessions to dominate transit display infrastructure. Clear Channel Outdoor sustains scale through centralized content management platforms spanning multiple landlord relationships. Actmedia Singapore specializes in retail proximity networks, anchoring shopper marketing budgets near point-of-sale locations.
Out-of-home (OOH) and digital out-of-home (DOOH) advertising encompasses physical and electronic display media installed in public and semi-public spaces, with digital variants employing LED, LCD, or projection technologies capable of real-time content rotation and programmatic ad serving. The primary commercial purpose is to deliver brand messaging to audiences during transit, dwell, or consumption moments when mobile and television engagement drops. Digital Screens capture the fastest expansion as programmatic trading platforms connect media buyers to inventory with audience-level targeting. Static Ads within the Content Format dimension retain utility for sustained brand presence in high-traffic zones where production simplicity reduces campaign turnaround. Transit Displays benefit from ridership recovery patterns, with rail network dwell times supporting both awareness and directional messaging formats.
Singapore's Infocomm Media Development Authority (IMDA) governs broadcast and telecommunications infrastructure underlying networked digital displays, while the Personal Data Protection Commission (PDPC) constrains camera-based audience measurement through consent and anonymization requirements. The Building and Construction Authority (BCA) influences installation standards for exterior building-mounted screens through facade safety and energy efficiency codes. Advertisers and media owners must monitor how evolving data governance intersects with addressable DOOH capabilities to preserve measurement accountability without triggering regulatory exposure.
Market Dynamics
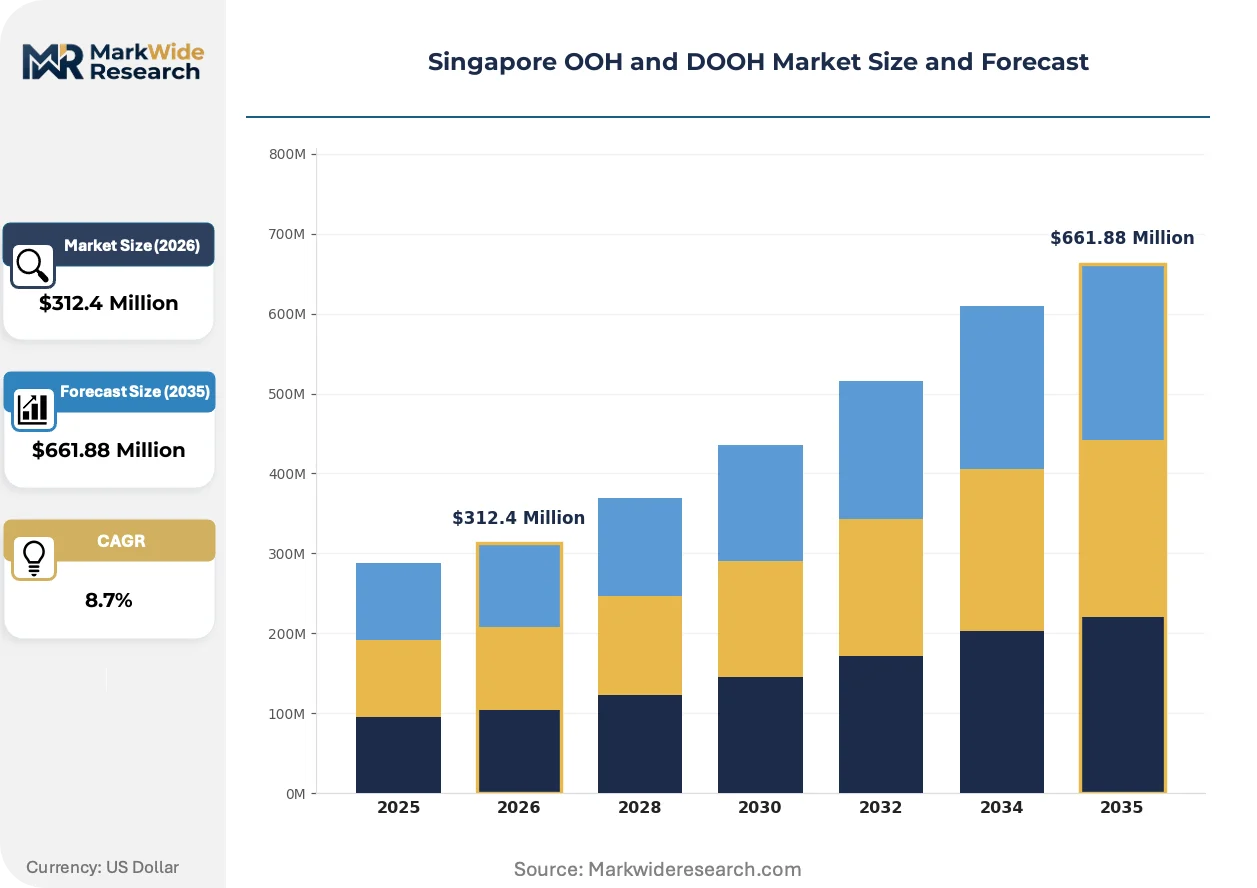
Programmatic trading platforms are collapsing the traditional insertion-order workflow that once governed Singapore's out-of-home sector, compressing campaign activation from weeks to hours and forcing media owners to reconfigure yield management systems around real-time bidding infrastructure.
Growth Catalysts
- PDPC Anonymization Framework:Singapore's Personal Data Protection Commission guidelines on camera-based audience measurement are channeling investment toward privacy-compliant analytics tools that preserve accountability without consent friction.
- Retail Media Networks:Supermarket and mall operators are deploying proximity digital screens at point-of-sale locations, capturing shopper marketing budgets that previously flowed to print catalogues.
- IMDA 5G Infrastructure:The Infocomm Media Development Authority's network densification enables low-latency content synchronization across distributed screen networks.
Market Restraints
- Prime Inventory Concentration:Orchard Road-Raffles Place corridor landlords command premium lease rates that compress margins for network operators without municipal concessions.
- Display Hardware Import Dependency:LED module supply concentrates among East Asian manufacturers, exposing operators to shipping cost volatility and customs clearance timelines.
- BCA Facade Safety Codes:The Building and Construction Authority's structural load and energy efficiency requirements extend permitting timelines for exterior building-mounted installations.
Strategic Opportunities
- Transit Hub Undersaturation:MRT station concourses outside the central corridor offer unsold inventory at price points accessible to mid-market advertisers.
- Retail Analytics Convergence:Integration of DOOH exposure data with point-of-sale transaction systems enables closed-loop attribution for FMCG brands.
- IMDA Digital Content Grant:Government co-funding for interactive and location-based creative production lowers campaign development barriers for local advertisers.
Industry Challenges
- Programmatic Talent Scarcity:Shortage of traders capable of operating demand-side platforms for DOOH inventory forces reliance on generalist digital media buyers.
- Legacy CMS Migration:Transitioning from scheduled-playback systems to API-connected infrastructure demands capital expenditure and operational downtime.
- Cross-Screen Frequency Capping:Absence of unified device graphs complicates deduplication when buyers run concurrent mobile and DOOH campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore OOH and DOOH Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Billboards, Transit Displays, Digital Screens, Posters Target Audience: Urban Professionals, Tourists, Families, Students Content Format: Static Ads, Video Ads, Interactive Displays, Augmented Reality Advertising Duration: Short-term, Long-term, Campaign-based, Event-specific |
| Companies Covered | Actmedia Singapore, Quirkraft, JCDecaux, INX Events & Productions, Billboarders, Clear Channel Outdoor, Boopin, Instamedia Labs, Talon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore OOH and DOOH Market Trends and Innovations
Automation is collapsing the traditional separation between media planning and execution in Singapore's out-of-home sector, compressing decision cycles and forcing structural reconfiguration of agency-client relationships around real-time optimization capabilities.
Dynamic creative optimization is collapsing the production bottleneck that historically constrained DOOH campaign complexity. Retail brands and transit advertisers are adopting templated creative frameworks that swap messaging based on time-of-day, weather, or inventory levels without human intervention. This compression enables A/B testing at scale and reduces the minimum viable campaign budget for performance-oriented buyers.
Singapore's PDPC guidelines on biometric data collection are constraining camera-based audience measurement, forcing media owners toward privacy-preserving alternatives. The regulatory friction is accelerating adoption of mobile signal aggregation and synthetic audience modeling that infer demographics without facial recognition. Transit display operators face the steepest compliance burden given high-density passenger environments.
Agency trading desks are consolidating DOOH buying authority previously dispersed across outdoor specialists and digital teams. The behavioral shift compresses vendor relationship counts and elevates platforms offering unified reporting across programmatic and direct-sold inventory. FMCG advertisers with established programmatic competencies are migrating fastest, particularly those with existing private marketplace arrangements for online video.
Singapore OOH and DOOH Market Segmentation
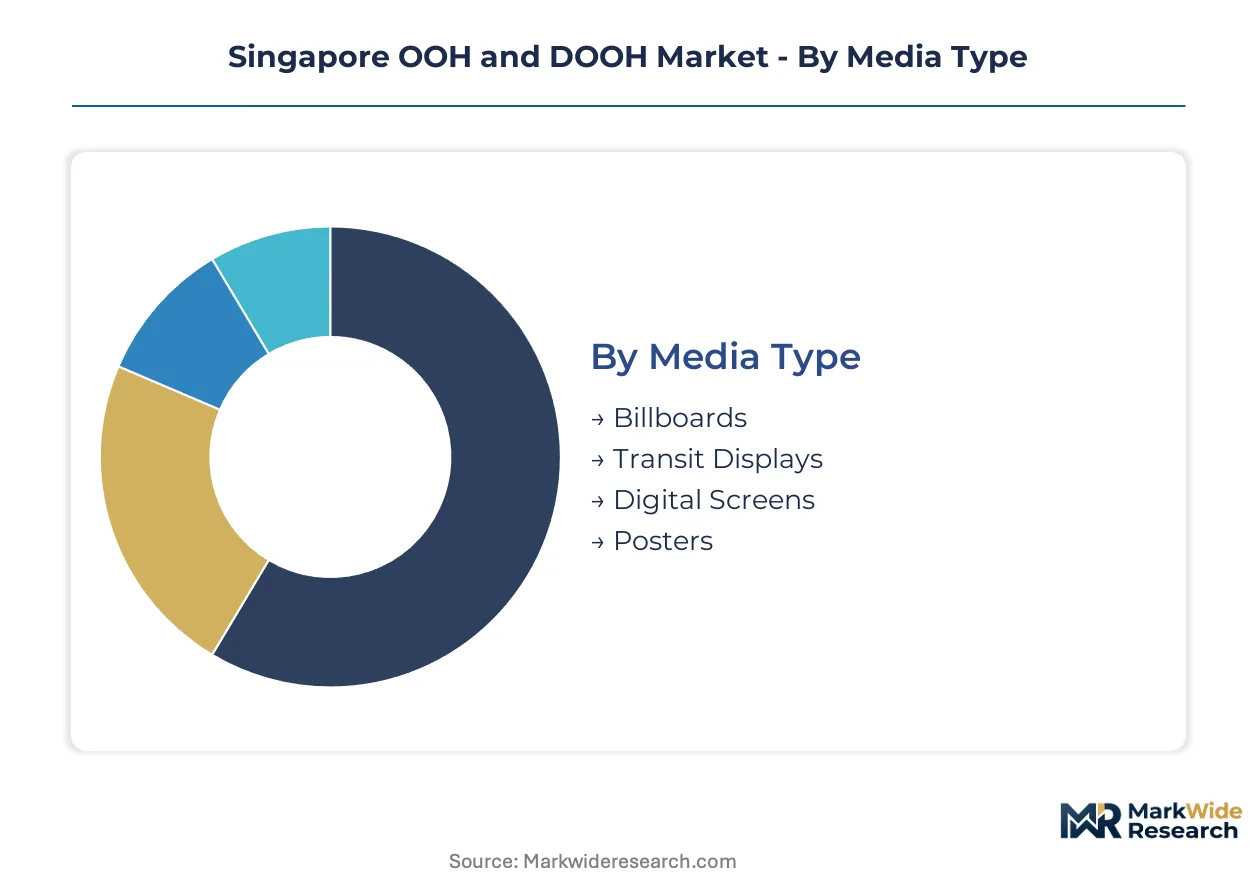
Segmentation in Singapore's out-of-home sector reveals how inventory characteristics, audience composition, and campaign mechanics interact to determine pricing power and yield management strategies for network operators.
Media Type:
Digital Screens turn over inventory in hours through programmatic pipes, while Static Posters lock in campaigns for weeks or months, creating divergent capital recovery timelines across the installed base.
- Digital Screens:LED and LCD displays enable real-time content rotation and programmatic ad serving through API-connected content management systems. Transit hub concourses and retail proximity locations concentrate demand as FMCG brands and financial services advertisers seek impression-level accountability and dynamic creative optimization.
- Transit Displays:Rail network panels, bus shelter wraps, and MRT station dominations capture ridership recovery patterns with dwell times supporting both awareness and directional messaging. The IMDA's 5G infrastructure densification enables low-latency synchronization across distributed networks.
- Billboards:Large-format building-mounted and roadside structures command premium positioning for sustained brand presence in high-visibility corridors.
- Posters:Standardized paper-based displays in street furniture and retail environments offer entry-level pricing for local advertisers with longer production lead times.
Digital Screens dominate installed base expansion. Transit Displays are where revenue growth concentrates most steeply.
Target Audience:
Audience segments stratify by dwell-time patterns and purchase authority, with Urban Professionals commanding the highest CPMs and Families offering the broadest reach at lower price points.
- Urban Professionals:CBD commuters and knowledge workers exhibit high disposable income and short decision windows during transit. The Orchard Road-Raffles Place corridor concentrates inventory investment toward this segment as luxury and financial services advertisers prioritize proximity to workplaces and premium retail.
- Tourists:Changi Airport arrivals and hotel district visitors generate concentrated demand from hospitality, entertainment, and retail brands seeking conversion near point-of-experience.
- Families:Suburban mall visitors and weekend recreational travelers attract FMCG and education sector budgets with longer consideration cycles.
- Students:University corridor and youth precinct traffic supports telecommunications and beverage brand campaigns with price-sensitive media plans.
Urban Professionals anchor premium pricing tiers. Tourists are gaining share fastest as border reopening patterns reshape inventory allocation.
Content Format:
Production complexity and creative adaptation cycles separate formats, with Static Ads offering same-day turnaround and Augmented Reality requiring multi-week development timelines.
- Video Ads:Motion content with 15-30 second loops maximizes engagement on digital screens with sound-off optimization for transit environments. Retail media networks and transit operators prioritize video-capable inventory as programmatic platforms enable sequential storytelling and brand lift measurement.
- Static Ads:Single-image or text-based creative retains utility for sustained presence in high-traffic zones where production simplicity reduces campaign turnaround and extends effective creative lifecycles.
- Interactive Displays:Touch-enabled or gesture-responsive screens enable audience-initiated engagement with brand content and data capture mechanics.
- Augmented Reality:Camera-integrated experiences overlay digital elements on physical environments, constrained by PDPC guidelines on biometric data collection and processing.
Video Ads command the majority of digital inventory trading. Interactive Displays are climbing the fastest as retail media networks expand point-of-sale deployment.
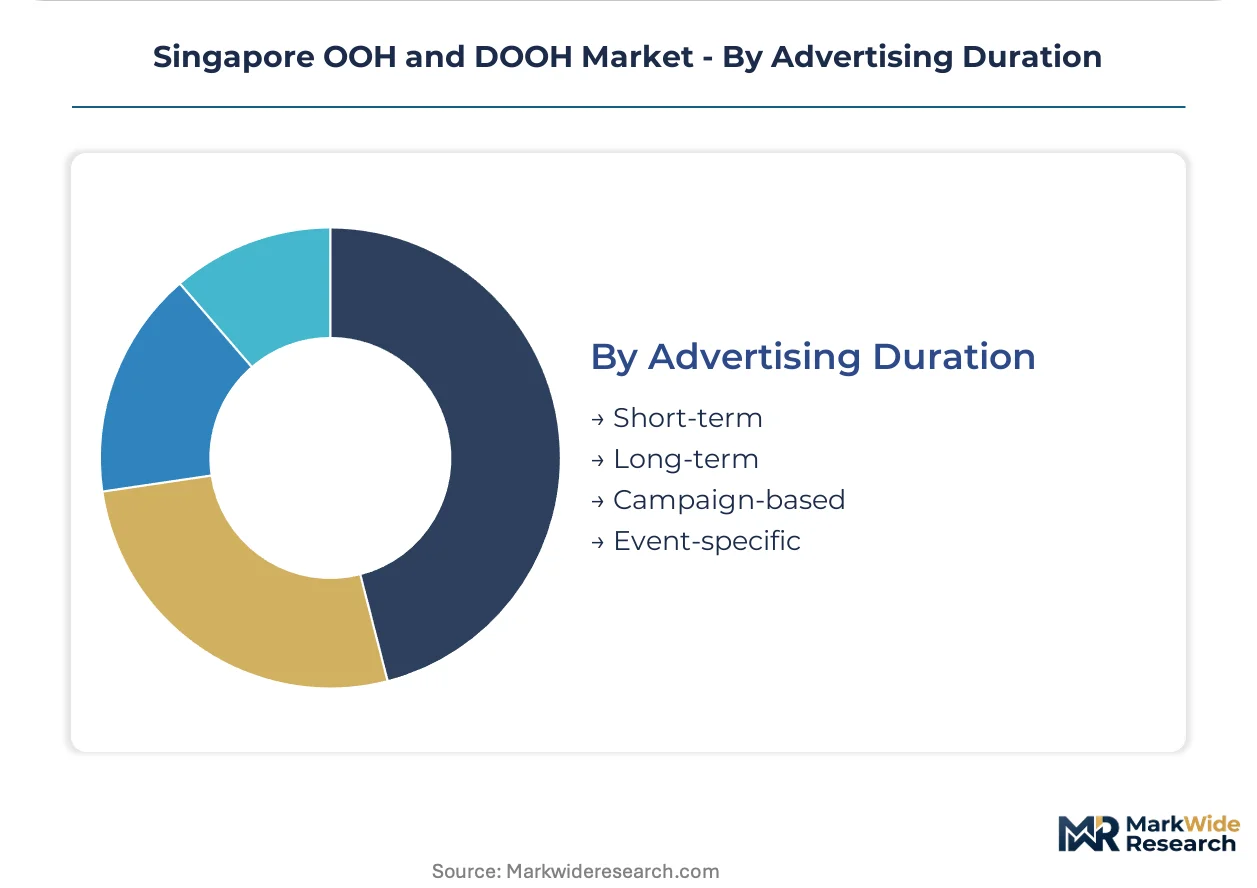
Advertising Duration:
Campaign commitment lengths determine yield management flexibility, with Short-term bookings enabling dynamic pricing and Long-term contracts providing revenue predictability for network operators.
- Campaign-based:Flighted activations aligned to product launches, seasonal promotions, or competitive response cycles dominate programmatic trading volumes. FMCG and fashion retailers concentrate spending in concentrated bursts synchronized with inventory cycles and consumer purchase patterns.
- Long-term:Annual or multi-year site dominations provide sustained brand presence for market leaders in financial services, automotive, and telecommunications with established outdoor allocation.
- Short-term:Day-part or week-long bookings enable tactical response to weather, events, or inventory conditions with premium pricing for flexibility.
- Event-specific:Fixed-date activations around Formula 1, cultural festivals, or product releases command scarcity pricing and require advance reservation commitments.
Long-term contracts anchor network operator revenue baselines. Campaign-based buying is where demand elasticity and pricing optimization concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Infocomm Media Development Authority (IMDA) co-funding programs and the Personal Data Protection Commission (PDPC) anonymization framework are directing investment toward privacy-compliant digital display infrastructure across Southeast Asian markets. The analysis examines how policy incentives and regulatory constraints are reshaping out-of-home advertising development in key regional economies.
Thailand
Bangkok's BTS and MRT transit networks are expanding digital screen deployment as retail media budgets shift from print to proximity displays. The country's National Broadcasting and Telecommunications Commission (NBTC) governs content standards for public electronic signage. Sukhumvit and Silom corridors concentrate premium inventory investment from FMCG and financial services advertisers seeking high-income commuter audiences.
Malaysia
Kuala Lumpur's KL Sentral and Bukit Bintang districts are witnessing accelerated DOOH installation as mall operators deploy programmatic-capable networks. The Malaysian Communications and Multimedia Commission (MCMC) regulates broadcast infrastructure underlying synchronized display systems. Klang Valley's integrated transit-retail clusters attract cross-border media buyers extending Singapore-based campaign frameworks into Malaysian markets.
Vietnam
Ho Chi Minh City's District 1 and Hanoi districts are emerging as DOOH growth nodes as international brands establish localized outdoor strategies. The Ministry of Information and Communications (MIC) oversees content licensing for electronic advertising displays. Metro Line 1 construction is creating transit display opportunities analogous to Singapore's MRT network development patterns.
Indonesia
Jakarta's Sudirman-Thamrin corridor and Surabaya's central business district are seeing premium digital billboard deployment despite regulatory fragmentation across municipal jurisdictions. The Ministry of Communication and Informatics (Kominfo) issues permits for outdoor electronic media with varying enforcement intensity by province. Mall-based retail media networks in Tangerang and Bekasi are replicating Singapore's point-of-sale proximity advertising models.
Philippines
Metro Manila's EDSA corridor and Cebu City's central districts maintain high static billboard density with gradual digital conversion constrained by power infrastructure limitations. The National Telecommunications Commission (NTC) governs broadcast frequencies for networked displays. Bonifacio Global City's planned development incorporates integrated DOOH infrastructure resembling Singapore's Orchard Road-Raffles Place premium positioning.
Singapore OOH and DOOH Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Singapore's out-of-home sector, creating a tiered structure where municipal concession holders and retail network operators occupy distinct competitive positions. Transit infrastructure operators leverage long-term public contracts to secure exclusive display rights in high-dwell environments. Retail media specialists capture shopper marketing budgets through point-of-sale proximity networks. Technology-enabled independents compete on programmatic trading capabilities and dynamic creative execution speed.
Among transit-focused operators, JCDecaux and Clear Channel Outdoor anchor the infrastructure-controlled tier through municipal concession relationships and centralized content management platforms spanning multiple landlord contracts. Actmedia Singapore exemplifies the retail-specialist archetype, concentrating deployment in supermarket and mall environments where shopper marketing budgets concentrate near transaction points. These three entities represent the dominant strategic groupings, with JCDecaux and Clear Channel Outdoor competing on transit network scale while Actmedia Singapore defends retail proximity positioning.
| Leading Market Players |
|---|
| Actmedia Singapore |
| Quirkraft |
| JCDecaux |
| INX Events & Productions |
| Billboarders |
| Clear Channel Outdoor |
| Boopin |
| Instamedia Labs |
| Talon |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's LED module manufacturing clusters anchor global display hardware supply, with their capacity utilization rates directly transmitting into Singapore network operators' procurement costs and margin structures. Transit hub landlords in the Orchard Road-Raffles Place corridor exploit this upstream concentration to extract premium lease rates that compress downstream operator yields.
Pricing Analysis
Screen resolution and IP65 outdoor certification grade create the primary spread between premium transit dominations and standard retail proximity placements. Three-tier pricing structure across premium, standard, and economy levels reflects dwell-time differentials and audience data granularity. Pricing pressure stems from programmatic trading platforms compressing insertion-order premiums as media buyers demand impression-level accountability. Mid-market FMCG advertisers exhibit highest price sensitivity, while luxury brands tolerate premium positioning costs for sustained CBD presence.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor components constrain content management system processing capabilities flowing into Southeast Asian markets. LED module supply concentrates in China, South Korea, and Taiwan, with Singapore operators drawing from Shenzhen and Seoul manufacturing hubs. NAND flash memory and high-brightness diode dependencies expose networks to shipping cost volatility and customs clearance timelines. Single-source vulnerability concentrates in premium outdoor-rated display panels. Distribution runs through regional electronics distributors with local installation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
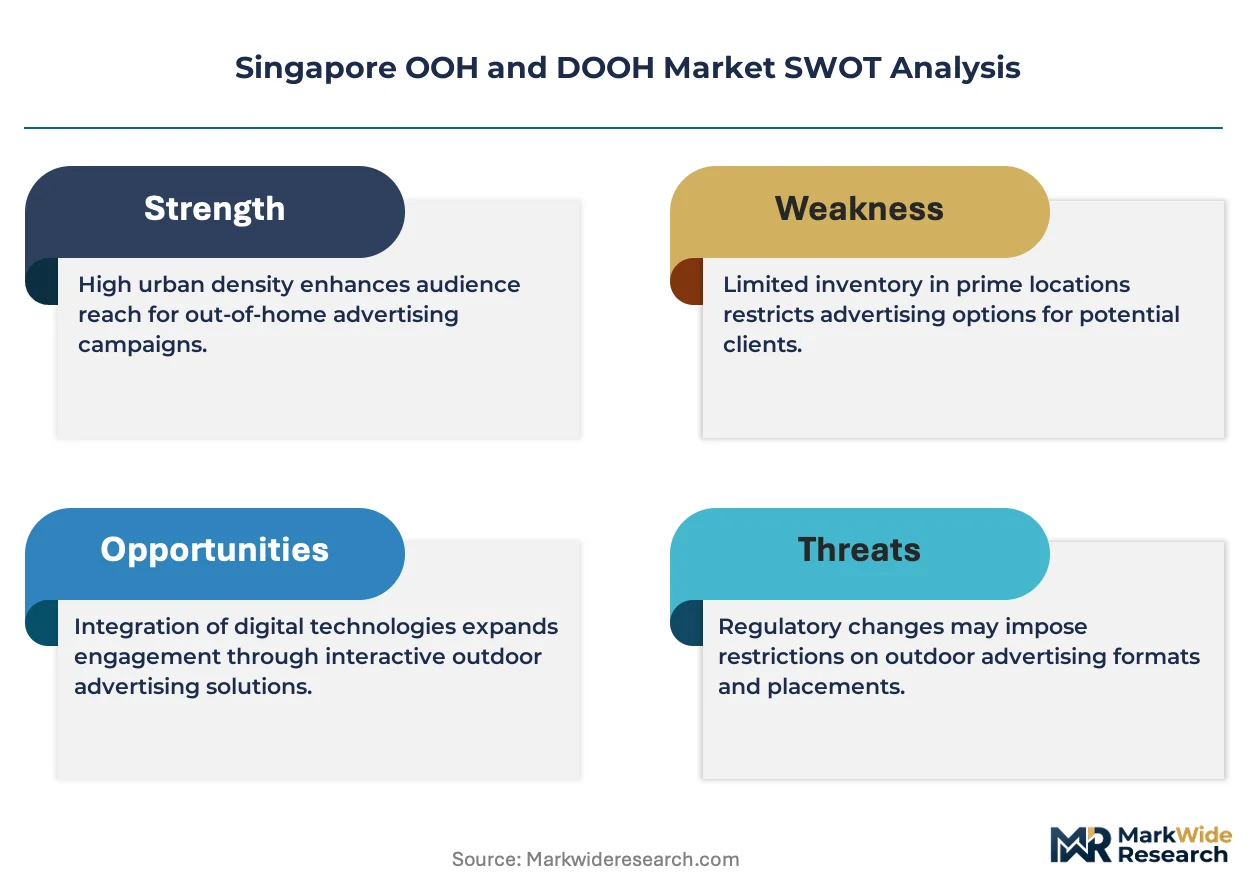
Singapore's OOH and DOOH market sits in a cyclical recovery phase as transit ridership patterns normalize post-border reopening and retail foot traffic rebuilds toward pre-crisis baselines.
For Market Incumbents: Insulate concession-based revenue streams by accelerating API-connected content management system deployment before programmatic-only competitors capture trading desk relationships. Secure long-term municipal transit contracts ahead of concession renewal windows. Invest in privacy-compliant audience analytics certification to defend measurement accountability against PDPC enforcement exposure.
For New Entrants and Emerging Players: Pursue undersaturated MRT station concourses outside the central corridor where mid-market advertiser demand exceeds quality inventory supply. Target retail media network partnerships with supermarket operators seeking shopper marketing budget migration from print catalogues. Lead with dynamic creative optimization capabilities as the primary go-to-market differentiator against legacy scheduled-playback incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors retail-specialist network operators with established point-of-sale proximity relationships over transit infrastructure plays facing concession renewal uncertainty. Long-term viability hinges on closed-loop attribution integration with FMCG point-of-sale transaction systems. Monitor IMDA digital content grant disbursement velocity as the signal indicating government commitment to interactive DOOH infrastructure development.
| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Platform Integration | API-connected trading infrastructure enables real-time bidding from demand-side platforms and compresses campaign activation cycles. |
| Privacy-Compliant Analytics Certification | PDPC-aligned audience measurement tools preserve accountability without consent friction in high-density transit environments. |
| Retail Media Network Expansion | Supermarket and mall proximity screen deployment captures shopper marketing budgets migrating from print catalogues. |
| 5G Infrastructure Leverage | IMDA network densification enables low-latency content synchronization across distributed screen networks. |
| Dynamic Creative Optimization Capability | Templated creative frameworks reduce minimum viable campaign budgets and enable A/B testing at scale for performance buyers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with network operations directors, programmatic trading desk leads, retail media buyers, and PDPC compliance officers; and secondary validation against IMDA infrastructure disclosures, PDPC guideline documents, BCA facade safety codes, and transit authority ridership statistics. Bottom-up estimates of installed screen counts and lease rate structures were triangulated against top-down advertising expenditure allocations by sector.
Forecast inputs span media type segmentation across digital screens, transit displays, billboards, and posters; audience targeting dimensions including urban professionals, tourists, families, and students; and content format categories from static ads through interactive displays. CAGRs were derived from elasticity modeling against transit ridership recovery trajectories and retail foot traffic indices. Analysis window assumptions incorporate IMDA 5G rollout timelines and PDPC enforcement intensity projections.
Sensitivities concentrate around transit ridership recovery velocity, LED module import cost fluctuations, and PDPC biometric data interpretation shifts. Forecasts reflect documented assumptions on programmatic adoption curves and retail media budget migration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Middle East and North Africa Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
Brazil OOH and DOOH Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Out of Home Advertising Market