
 Outdoor Advertising Market | 2026-2036
Outdoor Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Advertising Market Intelligence
Software-defined programmatic buying is repositioning how outdoor media inventory gets monetized, shifting contracts from fixed slots to impression-based auctions. Lamar Advertising Company leverages its national billboard footprint to anchor programmatic scale across United States highway corridors. JCDecaux sustains dominance in transit advertising through exclusive municipal concessions in Paris, London, and other European capitals. Clear Channel Outdoor competes by extending its digital screen network across urban street furniture and airport terminals.
Outdoor advertising encompasses physical display structures deployed in public spaces to deliver commercial messages to pedestrian and vehicular audiences, typically using vinyl substrates, LED arrays, or printed mesh rated for wind loads and UV stability; its primary commercial purpose is to capture attention during transit and dwell moments when digital device engagement drops. Digital displays command premium rate cards due to dynamic creative rotation and daypart targeting capabilities, while static billboards retain margin pools in rural interstate zones where electrification costs outweigh revenue uplift. Street furniture formats specialize in hyperlocal retail proximity campaigns, and transit advertising leads in audience reach density across metropolitan rail and bus networks.
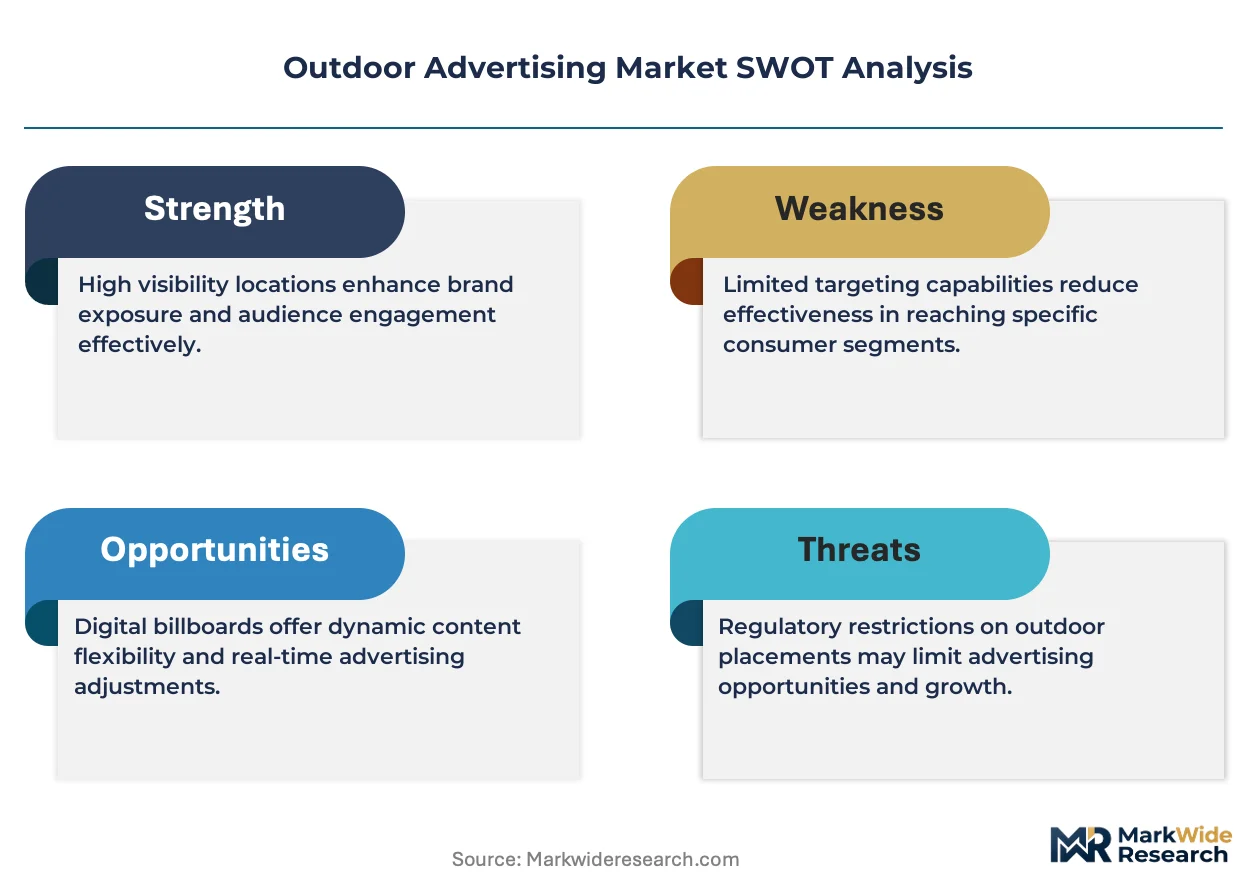
The United States Federal Highway Administration governs billboard spacing and lighting to preserve driver safety, while the EU Green Deal's energy efficiency mandates accelerate LED retrofit requirements across member states, and India's Central Electricity Authority enforces grid compliance standards for digital display networks. Stakeholders must monitor how municipal zoning reforms and decarbonization rules reshape permissible inventory locations and operating cost structures.
Market Dynamics
Programmatic trading infrastructure is collapsing the traditional insertion-order model for outdoor inventory, compressing sales cycles from weeks to milliseconds while fragmenting buyer access across demand-side platforms.
Growth Catalysts
- EU Green Deal retrofit mandates:Energy efficiency directives across member states are compelling operators to replace static vinyl substrates with LED arrays, creating replacement demand for electrified inventory.
- Transit infrastructure densification:Metropolitan rail expansions in India are unlocking exclusive concession agreements for platform and rolling-stock advertising, concentrating audience reach in high-dwell environments.
- Dynamic creative optimization:Real-time data feeds enabling weather-triggered and traffic-responsive creative rotation are commanding rate premiums from retail and quick-service restaurant advertisers.
Market Restraints
- Copper and semiconductor input volatility:LED module production depends on spot-market metals and chip foundry allocation, squeezing margin predictability for display manufacturers.
- Municipal zoning fragmentation:Billboard spacing restrictions governed by the United States Federal Highway Administration and counterpart state agencies constrain greenfield site development along interstate corridors.
- Digital device attention competition:In-vehicle infotainment and smartphone penetration during commute periods are eroding the captive-audience assumption that underpins highway inventory valuations.
Strategic Opportunities
- Retail media network convergence:Grocery and pharmacy chains are integrating parking-lot digital screens with in-store point-of-sale data, enabling closed-loop attribution for packaged goods brands.
- India's smart city deployments:Municipal Wi-Fi and sensor infrastructure investments are creating street furniture inventory bundles that combine advertising with public service delivery.
- Programmatic guaranteed contracts:Automated guaranteed buying workflows are opening national billboard access to mid-market advertisers previously excluded by minimum spend thresholds.
Industry Challenges
- Data science talent scarcity:Inventory yield optimization requires specialized expertise in geospatial analytics and real-time bidding algorithms that outstrips current workforce supply.
- Legacy static contract migration:Long-term vinyl lease obligations with municipal landlords complicate the capital reallocation needed for digital screen deployment.
- Attribution standardization gaps:Cross-platform measurement consortiums have failed to establish unified footfall-to-purchase verification protocols accepted by major media buying agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Advertising Market |
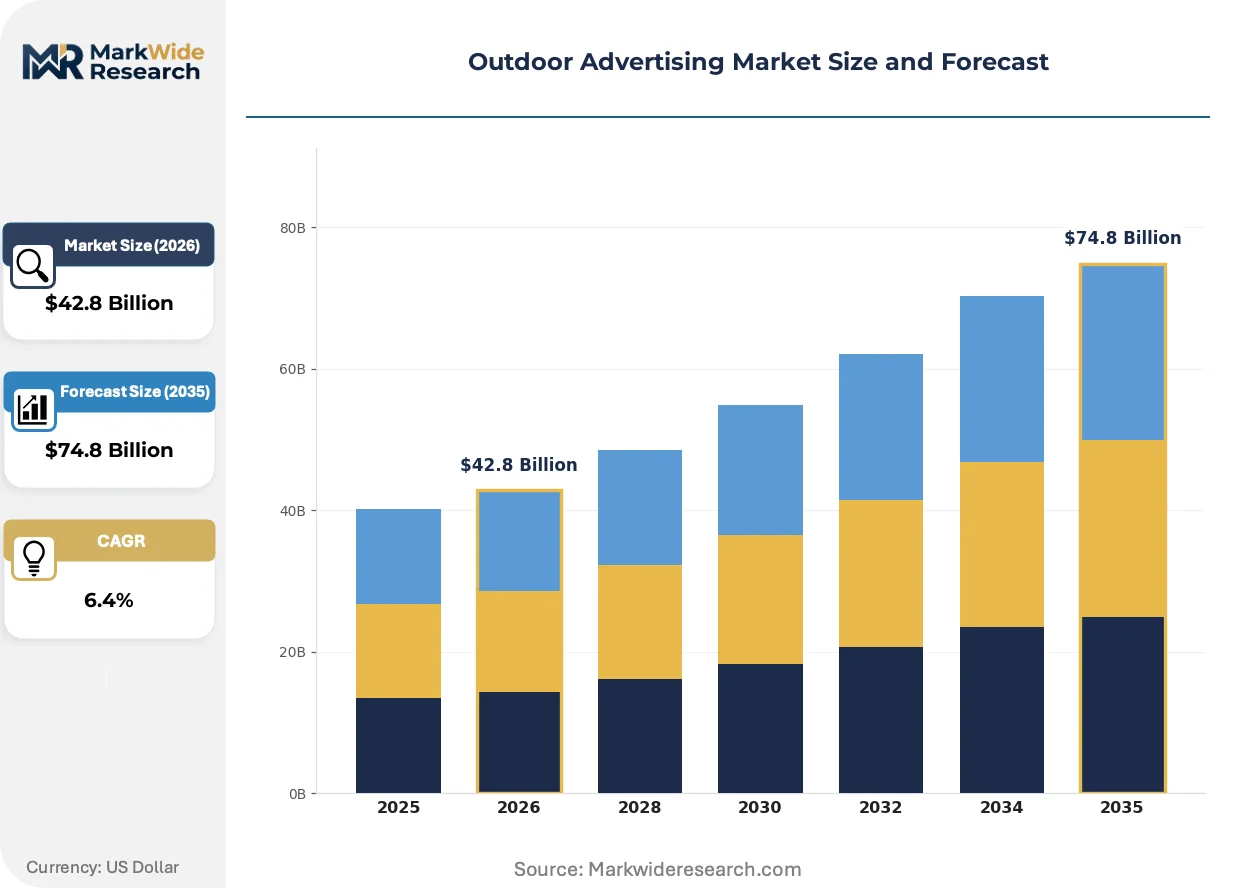
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium: Billboards, Transit Advertising, Street Furniture, Digital Displays Audience Type: Urban Residents, Tourists, Commuters, Event Attendees Format: Static, Digital, Mobile, Wall Mural Application: Brand Promotion, Event Marketing, Political Campaigns, Public Awareness |
| Companies Covered | Lamar Advertising Company, Ströer, JCDecaux, oOh! media, Global, Clear Channel Outdoor, Focus Media, APG | SGA, Outfront Media, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Advertising Market Strategic Shifts & Innovations
Artificial intelligence and edge computing architectures are embedding responsiveness directly into display hardware, transforming passive signage into sensor-enabled engagement surfaces that adapt to ambient conditions.
Computer vision-enabled audience measurement is electrifying how outdoor inventory gets priced and verified. Cameras integrated into digital screen bezels anonymously estimate viewer demographics and attention duration. Media owners in London and New York are adopting these systems to shift from traffic-based rate cards to verified impression guarantees. Advertisers are compressing planning cycles as this data feeds directly into programmatic buying interfaces.
The EU Green Deal's energy efficiency mandates are accelerating LED retrofit requirements across member states, with France and Germany enforcing phased compliance deadlines for display networks above specified power thresholds. Operators face capital-intensive upgrades or inventory retirement. Municipal concession renewals increasingly incorporate sustainability clauses that privilege low-energy technologies in competitive bidding.
Retail brands are expanding programmatic digital out-of-home campaigns that synchronize messaging across online video, mobile, and physical display touchpoints. Quick-service restaurant chains are piloting daypart-specific creative that shifts from breakfast to lunch promotions based on real-time sales data. This convergence is most visible in the United States, where demand-side platforms have integrated outdoor inventory alongside connected television and streaming audio.
Outdoor Advertising Market Segmentation
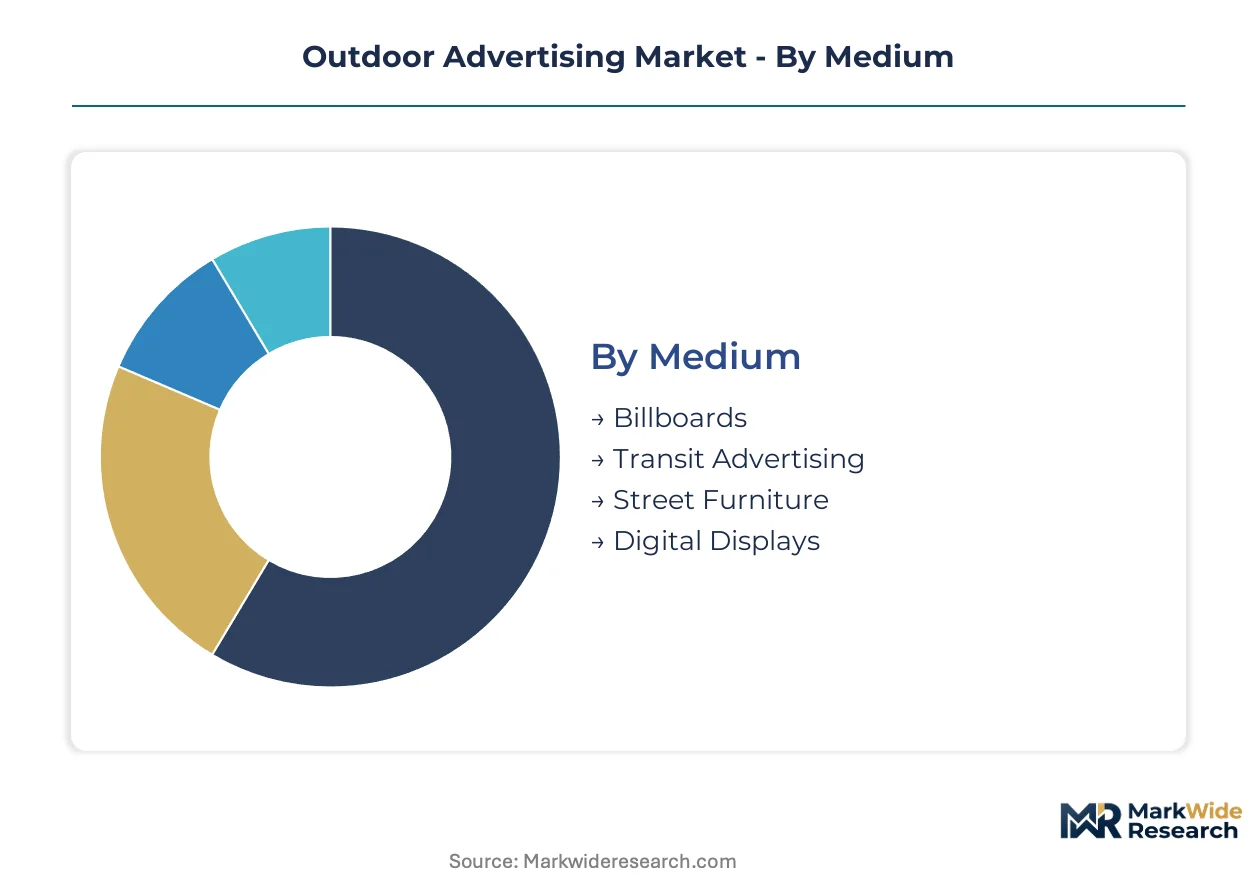
Outdoor advertising segmentation reveals how inventory monetization varies dramatically by physical placement, audience mobility patterns, and technological sophistication. Operators must align capital deployment with format-specific replacement cycles and municipal concession structures.
Medium:
LED retrofit mandates across European member states are accelerating replacement demand for electrified inventory while static substrates face obsolescence risk.
- Billboards:Large-format structures positioned along highways and arterial roads, typically employing vinyl substrates or LED arrays rated for wind loads. Demand concentrates in United States interstate corridors where Lamar Advertising Company anchors national scale, though electrification cost burdens in rural zones preserve static margin pools.
- Transit Advertising:Inventory deployed across rail platforms, rolling stock, and bus shelters capturing high-dwell metropolitan audiences. India's metropolitan corridor expansions are unlocking exclusive concession agreements, with JCDecaux sustaining dominance through Paris and London municipal contracts.
- Street Furniture:Bus shelters, newsstands, and kiosks positioned at pedestrian eye level for hyperlocal retail proximity campaigns. France and Germany enforce phased EU Green Deal compliance deadlines for these networks.
- Digital Displays:Programmable LED and LCD screens enabling dynamic creative rotation and daypart targeting. Rate premiums reflect real-time data feed integration for weather-triggered and traffic-responsive messaging.
Billboards sit at the top of the volume ranking, with Digital Displays climbing the fastest.
Audience Type:
Audience mobility patterns determine dwell time and attention availability, with commuters presenting the most contested valuation assumptions.
- Urban Residents:Repeat exposure populations enabling frequency-based campaign optimization across neighborhood-level street furniture networks.
- Tourists:High-discretionary-income visitors concentrated in airport terminals and city-center districts where Clear Channel Outdoor extends digital screen density.
- Commuters:Rail and highway transit users experiencing device-competition erosion from in-vehicle infotainment and smartphone penetration during journey periods.
- Event Attendees:Temporary high-density gatherings requiring rapid-deployment mobile formats and stadium-adjacent inventory.
Commuters generate the largest impression volumes, though Tourists command the steepest rate premiums.
Format:
Format selection hinges on creative flexibility requirements versus capital intensity constraints, with static inventory facing accelerated depreciation in electrified zones.
- Static:Printed vinyl or mesh substrates with UV stability ratings, retaining viability in rural interstate corridors where electrification costs outweigh revenue uplift.
- Digital:Programmable LED arrays enabling dynamic rotation and real-time bidding integration, commanding premium rate cards from retail and quick-service restaurant advertisers.
- Mobile:Vehicle-mounted or trailer-based displays enabling rapid repositioning for event marketing and political campaigns.
- Wall Mural:Building-integrated painted or printed surfaces offering neighborhood-scale brand presence in dense urban districts.
Static formats still dominate unit counts, yet Digital is gaining share fastest among new deployments.
Application:
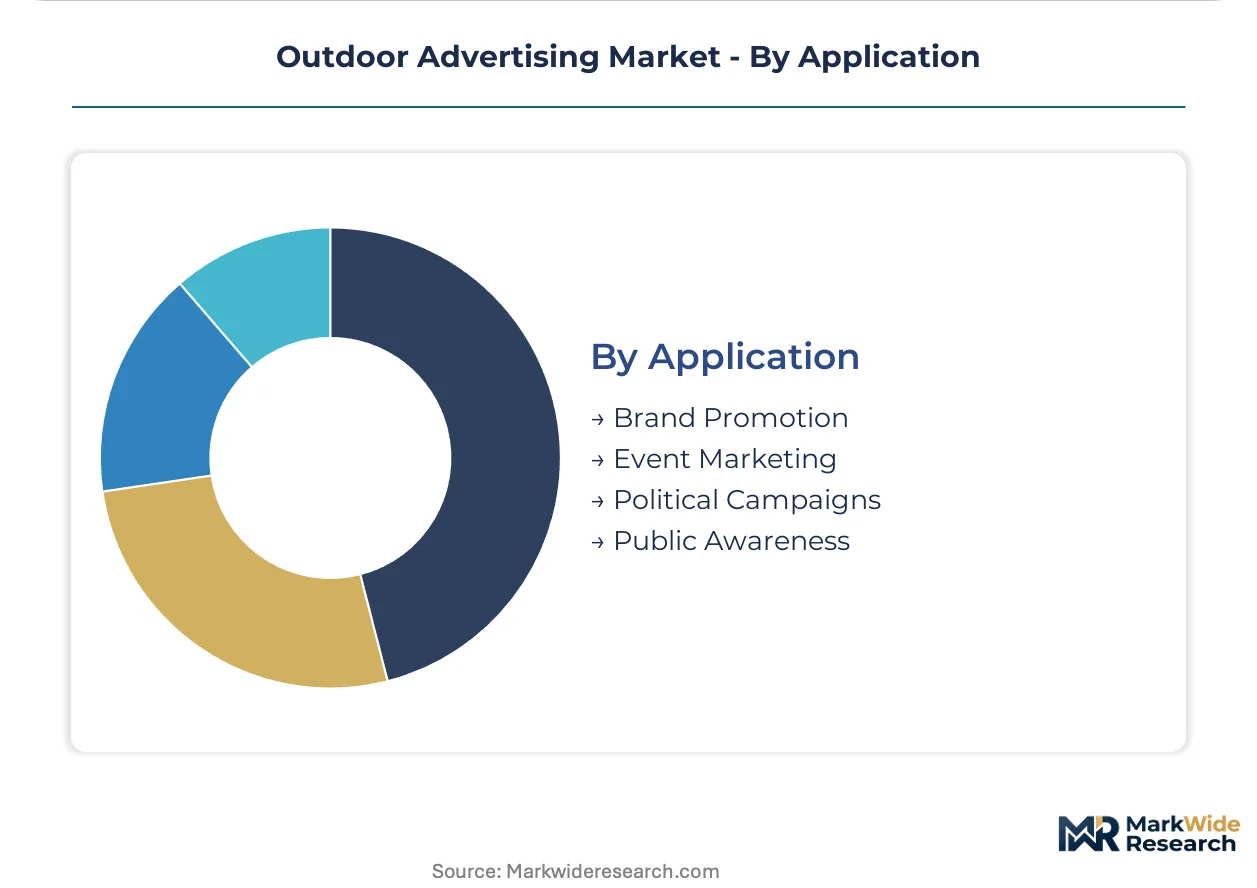
Application segmentation tracks how campaign objectives reshape inventory selection and measurement requirements.
- Brand Promotion:Sustained awareness campaigns leveraging highway billboards and urban digital networks for reach maximization.
- Event Marketing:Time-bound activations requiring mobile formats and transit shelter domination around venue clusters.
- Political Campaigns:High-velocity buying cycles favoring programmatic guaranteed contracts and rapid creative rotation capabilities.
- Public Awareness:Government and nonprofit messaging often bundled with municipal street furniture concessions as public service obligations.
Brand Promotion anchors revenue concentration, while Event Marketing shows the most volatile seasonal spikes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands highway corridor density that Germany cannot replicate under stricter municipal spacing codes, while India's transit expansion outpaces both markets in concession velocity. National regulatory frameworks and infrastructure investment cycles create divergent inventory growth trajectories across these three markets.
United States
Interstate corridor density and retail media network convergence drive inventory demand, with grocery and pharmacy chains integrating parking-lot digital screens. The Federal Highway Administration governs billboard spacing and lighting standards to preserve driver safety. Lamar Advertising Company anchors national scale across highway corridors, while Clear Channel Outdoor extends digital density through urban street furniture and airport terminals.
Germany
EU Green Deal energy efficiency mandates compel LED retrofit deployment across static substrate networks. France and Germany enforce phased compliance deadlines for display networks above specified power thresholds. Municipal concession renewals in Berlin and Hamburg increasingly incorporate sustainability clauses that privilege low-energy technologies in competitive bidding.
India
Metropolitan rail expansions in Mumbai, Delhi, and Bangalore unlock exclusive concession agreements for platform and rolling-stock advertising. The Central Electricity Authority enforces grid compliance standards for digital display networks. Transit infrastructure densification concentrates audience reach in high-dwell environments where JCDecaux-style municipal contracts are proliferating.
France
Street furniture format specialization supports hyperlocal retail proximity campaigns in Paris and Lyon commercial districts. EU Green Deal retrofit requirements accelerate replacement demand for electrified inventory across bus shelter and newsstand networks. JCDecaux sustains dominance through exclusive municipal concessions in Paris that bundle advertising with public service obligations.
United Kingdom
Computer vision-enabled audience measurement systems are shifting London inventory pricing from traffic-based rate cards to verified impression guarantees. The country's advertising regulator monitors data privacy compliance for camera-integrated demographic estimation. Clear Channel Outdoor and JCDecaux compete for digital screen density across Transport for London rail and bus networks.
Outdoor Advertising Market Key Industry Players
Top-tier vendors anchor national billboard and transit concession scale, while mid-tier specialists concentrate on regional street furniture or programmatic technology layers. The vendor base stratifies across three archetypes: infrastructure-heavy concession holders, technology-enabled programmatic platforms, and hybrid retail-media integrators. Consolidation pressure runs through municipal lease renewals and digital retrofit capital requirements. Competitive moves center on exclusive municipal concession bidding and demand-side platform partnerships that collapse sales cycles.
Among infrastructure-heavy concession holders, Lamar Advertising Company and JCDecaux exemplify divergent geographic anchoring strategies, with the former representing United States highway corridor dominance and the latter occupying a position in European transit advertising through municipal exclusivity. Clear Channel Outdoor sits within the hybrid tier, bridging airport terminal and urban street furniture networks across multiple continents. These three entities represent how concession duration and municipal relationship depth create defensive moats against programmatic disruption.
| Leading Market Players |
|---|
| Lamar Advertising Company |
| Ströer |
| JCDecaux |
| oOh! media |
| Global |
| Clear Channel Outdoor |
| Focus Media |
| APG | SGA |
| Outfront Media |
| Others |
Cost & Logistics Intelligence
Digital-static format divergence splits the outdoor advertising market into premium programmable inventory and commodity vinyl substrates, with electrification mandates in France and Germany compressing margins on legacy static assets while LED arrays command rate premiums from retail advertisers seeking dynamic rotation capabilities. This bifurcation reshapes procurement patterns as operators face capital reallocation pressures between retrofit compliance and greenfield digital deployment.
Pricing Analysis
Capacity additions in China's LED module manufacturing are reshaping price floors for digital display hardware, enabling faster payback periods on electrified inventory investments. The market operates on a hybrid pricing model combining fixed lease rates for static billboards with programmatic auction mechanisms for digital screens, where rate differentiation hinges on audience verification capabilities and real-time data feed integration. Cost compression in rural interstate zones is intensifying because electrification costs outweigh revenue uplift, leaving static formats viable only where traffic density fails to justify LED capital expenditure. Mid-market advertisers exhibit highest price sensitivity, excluded by minimum spend thresholds until programmatic guaranteed contracts opened national billboard access.
Supply Chain Analysis
Regional distribution centers in Germany, China, and South Korea anchor hub-and-spoke patterns for LED module and semiconductor component fulfillment, with display manufacturers drawing from concentrated Asian foundry capacity for driver ICs and copper-intensive power management systems. Raw material dependencies center on copper interconnects, gallium nitride substrates, and polycarbonate enclosure materials sourced through volatile spot markets. Single-source vulnerability in semiconductor foundry allocation poses structural risk, as chip shortages can halt display production regardless of downstream demand. Distribution runs through municipal concession holders who bundle installation and maintenance services with hardware procurement, compressing vendor direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in outdoor advertising rests on LED retrofit completion cycles that eliminate static substrate maintenance costs while enabling premium programmatic rate cards from data-enabled advertisers.
For Market Incumbents: Deepen municipal relationship infrastructure to secure concession renewals incorporating sustainability clauses that privilege low-energy technologies, insulating against emerging programmatic pure-plays lacking physical inventory control. Prioritize vertical integration into audience measurement technology to shift rate cards from traffic-based proxies to verified impression guarantees, defending against margin erosion from device-competition during commute periods. For New Entrants and Emerging Players: Mid-market advertisers previously excluded by minimum spend thresholds represent the most penetrable buyer archetype, accessible through programmatic guaranteed workflows that collapse sales cycles from weeks to milliseconds. Target India's metropolitan corridor expansions where transit infrastructure densification creates new inventory without entrenched concession competition, leveraging exclusive platform agreements to establish foothold before JCDecaux-style municipal contracts proliferate. For Investors and Strategic Acquirers: Consolidation pressure builds where legacy static lease obligations complicate capital reallocation for digital deployment, creating distressed acquisition opportunities among regional operators facing EU Green Deal compliance deadlines. Long-term viability favors hybrid retail-media integrators combining parking-lot digital screens with in-store point-of-sale data for closed-loop attribution. Monitor municipal Wi-Fi and sensor infrastructure investments as inflection indicators for street furniture inventory bundles that merge advertising with public service delivery.| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Acceleration | EU Green Deal mandates in France and Germany force compliance-driven replacement demand for electrified inventory. |
| Programmatic Platform Integration | Demand-side platform partnerships collapse sales cycles and open national access to mid-market advertisers. |
| Audience Measurement Technology | Computer vision systems in London and New York shift pricing from traffic proxies to verified impression guarantees. |
| Municipal Concession Renewal | Sustainability clauses in Berlin and Hamburg privilege low-energy technologies in competitive bidding processes. |
| Retail Media Network Convergence | Grocery and pharmacy chains integrate parking-lot screens with in-store data for packaged goods attribution. |
Research Approach
Coverage spans the United States, Germany, India, France, and the United Kingdom, with primary inputs from each market combining interviews with outdoor media operators, municipal concession managers, programmatic platform engineers, and retail media network directors alongside secondary validation. Bottom-up and top-down triangulation draws from SEC filings of listed operators, EU Green Deal implementation tracking, Indian Central Electricity Authority grid compliance records, Transport for London procurement disclosures, and municipal zoning databases across metropolitan corridors.
Granularity-level modeling segments the market by medium, audience type, format, and application, with additional dimensioning across electrification status and concession structure type. CAGRs derive from replacement cycle analysis for static-to-LED conversion, transit infrastructure investment pipelines, and programmatic adoption curves across demand-side platforms. Forecast inputs incorporate copper and semiconductor spot price volatility, municipal zoning reform timelines, and retail media network integration velocity without year-specific anchoring.
Underlying measurement precision varies by segment; digital display and programmatic trading volumes carry tighter precision than static billboard inventory where lease structures obscure utilization rates. Forecasts reflect documented assumptions regarding infrastructure investment continuity, regulatory compliance deadlines, and technology adoption thresholds. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging that copper input volatility, municipal zoning fragmentation, and digital device attention competition could materially revise trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
Multiscreen Advertising Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
Vietnam OOH and DOOH Market
Advertising and Marketing Media
Middle East and Africa Programmatic Advertising Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market
Advertising and Marketing Media
In-Flight Advertising Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market