
 Latin America Programmatic Advertising Market | 2026-2036
Latin America Programmatic Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Programmatic Advertising Market Foresight
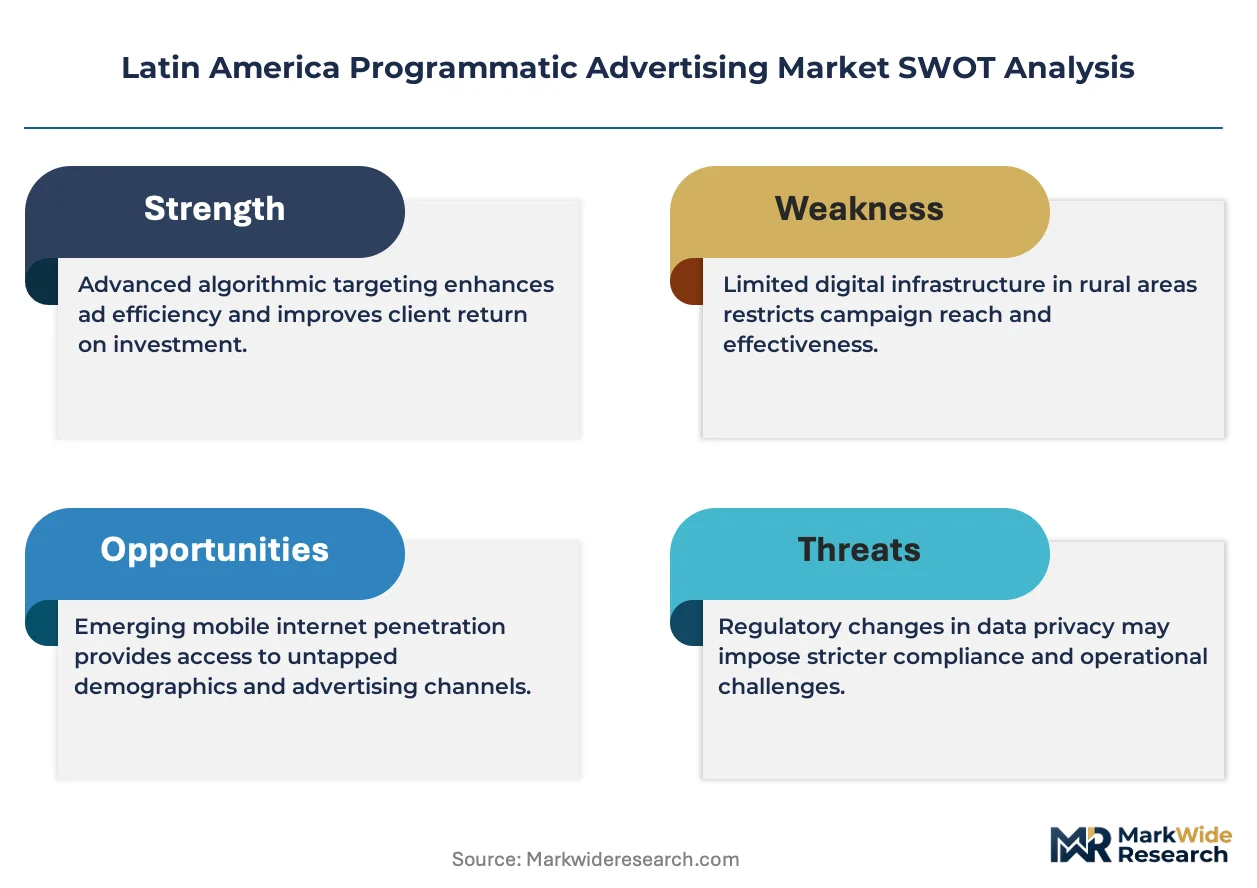
LGPD enforcement is pivoting the cost-of-entry calculus for programmatic advertisers across Brazil and beyond. MediaMath Inc. leverages its demand-side infrastructure to sustain cross-border campaign execution. The Trade Desk anchors its regional position through advanced data management capabilities. Google competes by integrating supply-side and exchange functions within a unified stack.
Programmatic advertising denotes the algorithmic buying and selling of digital ad impressions through real-time bidding protocols, typically executing transactions within 100 milliseconds via ad exchanges. Demand-side platforms automate bid optimization across inventory sources, while supply-side platforms manage publisher yield. Video ad formats within mobile device channels represent the fastest-expanding margin pool, whereas display ads on desktop computers retain mature volume leadership. Data management platforms concentrate value by unifying first-party identifiers as third-party cookies deprecate.
ANPD in Brazil, INAI in Mexico, and Colombia's SIC enforce data protection standards that reshape audience targeting methodologies and consent architecture. LGPD alignment costs are filtering smaller resellers from auction-based sales channels. Stakeholders must monitor regulatory divergence between Mercosur members and Pacific Alliance economies to calibrate platform compliance investments.
Market Dynamics
Connected TV inventory expansion across Brazil, Mexico, and Colombia is compressing auction dynamics and forcing DSPs to reallocate algorithmic bidding capacity toward streaming endpoints. The LGPD consent architecture is simultaneously raising data governance costs for audience targeting.
Growth Catalysts
- CTV Inventory Scaling:Streaming platforms in Brazil and Mexico are releasing premium video impressions into programmatic pipes. Advertisers gain addressable reach beyond linear television.
- LGPD Compliance Maturation:Brazil's data protection authority ANPD has issued enforcement guidance that clarifies lawful processing grounds. Clarity reduces legal uncertainty for platform investments.
- Retail Media Networks:E-commerce marketplaces in Colombia and Chile are opening first-party data segments to external DSPs. Closed-loop attribution attracts FMCG budgets.
Market Restraints
- Consent Infrastructure Costs:LGPD-mandated consent management platforms require continuous technical maintenance. Smaller resellers lack capital to sustain compliance engineering.
- Supply Concentration:Premium CTV inventory in Brazil clusters among three domestic broadcasters. Limited competition inflates floor prices for guaranteed video views.
- Cross-Border Data Friction:Mercosur members lack mutual recognition for data transfer adequacy. Campaigns spanning Argentina and Brazil face segmentation silos.
Strategic Opportunities
- Peru and Chile Expansion:Santiago and Lima metro areas show CTV penetration above regional averages. Early DSP entrants capture undervalued inventory before competition intensifies.
- Retail-Ecommerce Convergence:In-store digitization in Mexican supermarkets generates location-triggered mobile impressions. Proximity targeting bridges online-offline attribution gaps.
- Cookieless Identity Graphs:Publisher consortiums in Colombia are pooling authenticated user signals. First-party data cooperatives offer alternatives to deprecated third-party cookies.
Industry Challenges
- Programmatic Talent Scarcity:Brazil's São Paulo metro faces acute shortage of data scientists fluent in real-time bidding algorithms. Universities lag curriculum updates for ad-tech specializations.
- Legacy SSP Integration:Mexican publishers operate decade-old yield management systems. API modernization demands divert engineering resources from audience product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Programmatic Advertising Market |
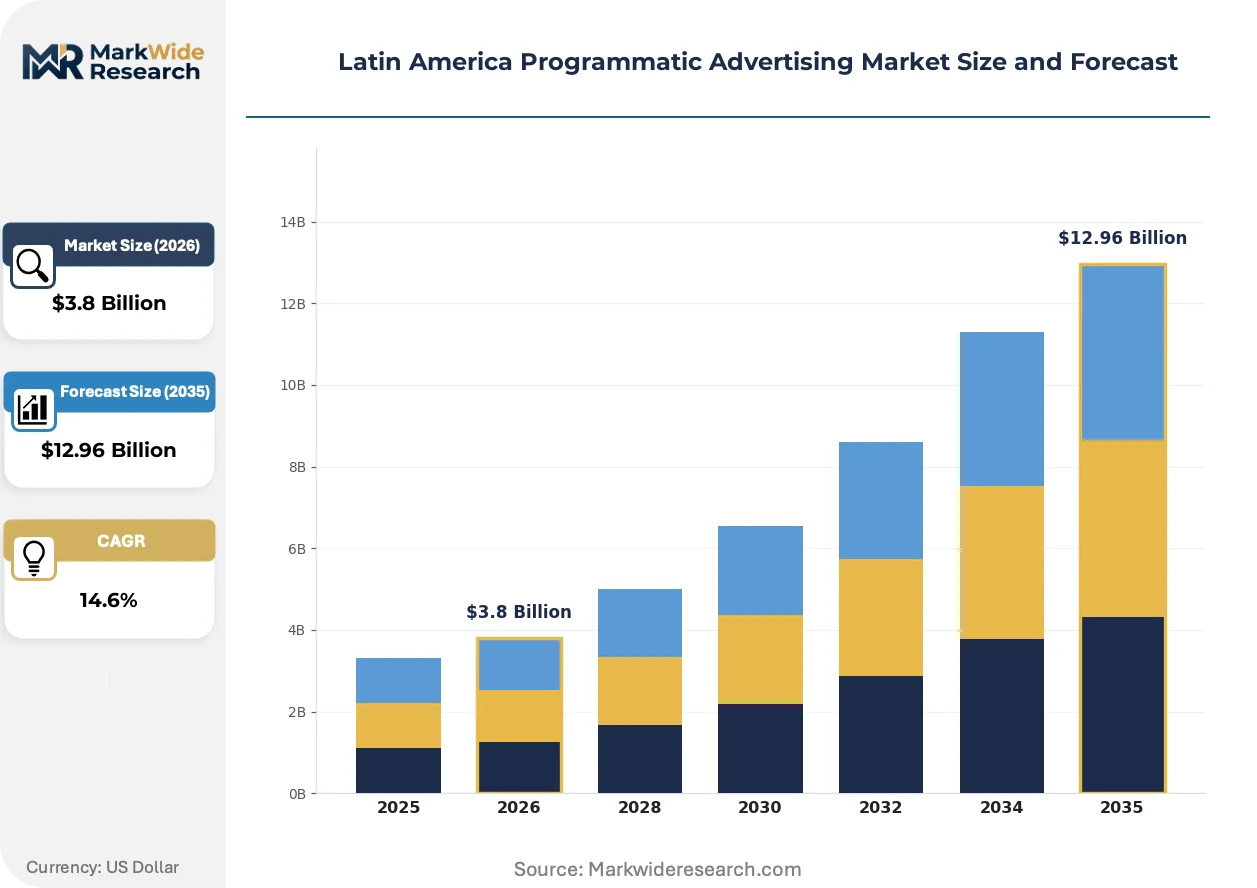
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Display Ads, Video Ads, Native Ads, Audio Ads Technology: Demand-Side Platforms, Supply-Side Platforms, Ad Exchanges, Data Management Platforms Device Type: Mobile Devices, Desktop Computers, Tablets, Smart TVs Sales Channel: Direct Sales, Third-Party Networks, Programmatic Direct, Auction-Based |
| Companies Covered | MediaMath Inc., Adsmovil LLC, Mercado Libre, Google, The Trade Desk, SmartyAds Inc., BidMind by Fiksu, Canela Media, Jampp Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Programmatic Advertising Market Shifts & Advancements
Algorithmic media buying is migrating toward privacy-preserving computation methods that process audience signals without centralizing personal data. Three developments are compressing competitive timelines.
Server-side ad insertion technology is consolidating CTV monetization workflows by embedding spots directly into content streams before device delivery. Brazilian broadcasters and Mexican telcos are adopting SSAI to bypass client-side ad blockers and improve fill rates. This architecture is consolidating measurement standards around publisher-controlled exposure verification.
ANPD in Brazil has aligned enforcement timelines with GDPR adequacy negotiations, creating dual compliance pressure for multinational platforms. The regulator's 2024 guidance on legitimate interest assessments restricts behavioral profiling without explicit consent. DSPs serving Brazilian e-commerce advertisers are pivoting toward contextual targeting and publisher first-party segments.
Buyer consolidation among retail and FMCG conglomerates is compressing RFP cycles and demanding outcome-based guarantees rather than impression volume commitments. Procurement teams in São Paulo and Mexico City now require verified sales lift data before renewing annual platform contracts. This shift is most visible in CPG verticals where retail media networks offer closed-loop purchase validation.
Latin America Programmatic Advertising Market Segmentation
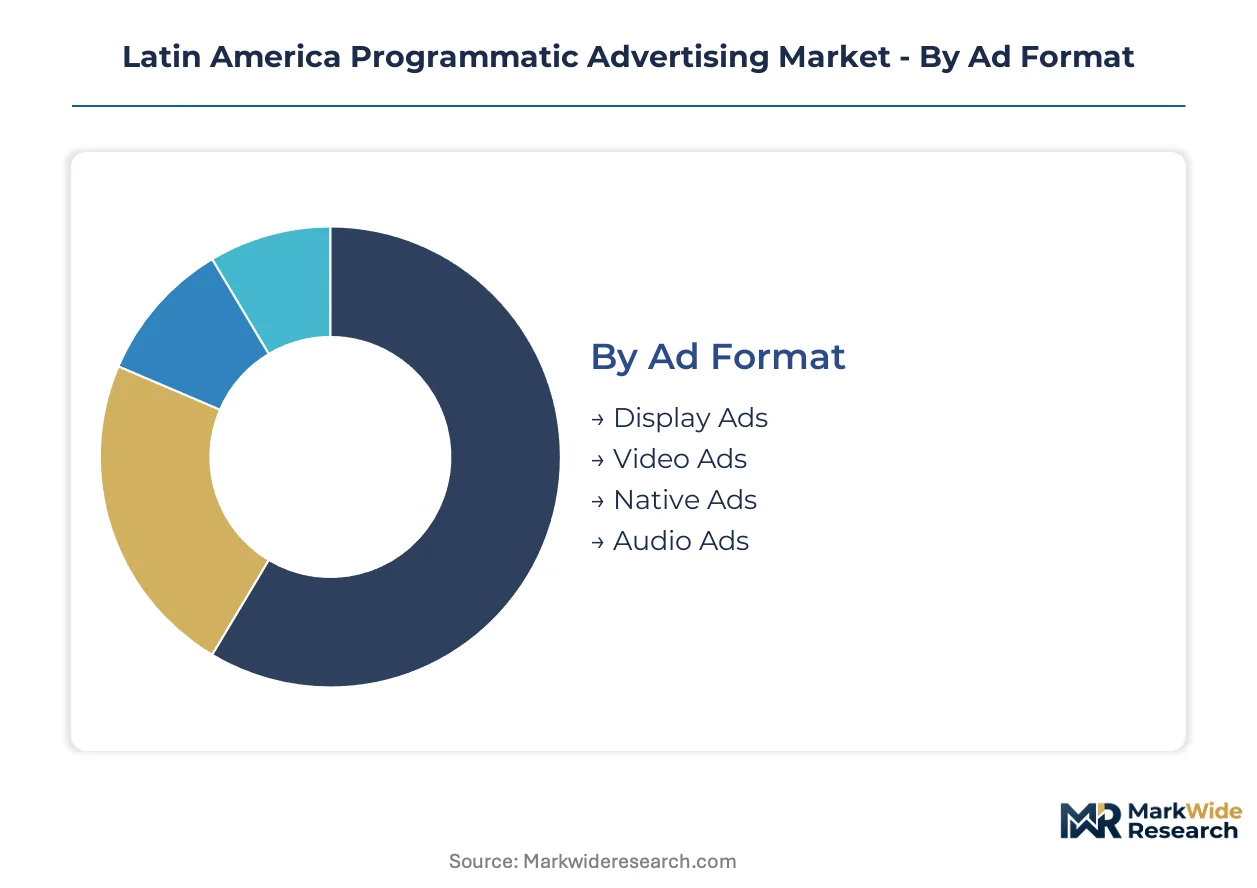
Programmatic advertising in Latin America fragments across four structural dimensions that determine technology stack requirements and margin capture. Advertisers in Brazil and Mexico select formats, platforms, devices, and transaction modes based on inventory access, data governance costs, and audience verification capabilities.
Ad Format:
Standalone creative units operate independently of publisher content management systems, while embedded formats integrate natively into platform environments.
- Display Ads:Standard banner and rich media units execute through real-time bidding protocols with mature measurement standards. Brazilian e-commerce advertisers concentrate demand here for retargeting campaigns, though viewability verification adds cost layers.
- Video Ads:Pre-roll, mid-roll, and outstream formats command premium CPMs through CTV and mobile channels. Mexican streaming platforms and Colombian broadcasters are releasing inventory into programmatic pipes, compressing auction dynamics for quality impressions.
- Native Ads:Sponsored content units match publisher editorial styling for reduced ad blocker interception.
- Audio Ads:Programmatic podcast and streaming music placements leverage first-party listener data from Brazilian and Mexican audio platforms.
Display Ads lead volumes today; Video Ads is gaining share fastest.
Technology:
Platform selection follows advertiser sophistication tiers, with enterprise buyers demanding cross-channel unification while mid-market users prioritize simplified workflow integration.
- Demand-Side Platforms:Automated buying interfaces optimize bid decisions across multiple inventory sources using algorithmic audience targeting. São Paulo-based agencies and direct advertisers in Mexico City concentrate procurement here, though LGPD compliance engineering raises operational costs.
- Supply-Side Platforms:Publisher yield management systems manage floor pricing and auction participation rules. Brazilian media conglomerates operate captive SSP infrastructure, limiting third-party platform penetration.
- Ad Exchanges:Open auction marketplaces match buy-side demand with sell-side supply through second-price or first-price clearing mechanisms.
- Data Management Platforms:Identity unification and audience segmentation engines concentrate first-party signals as third-party cookies deprecate across Latin American markets.
Demand-Side Platforms anchor current spending; Data Management Platforms show steepest expansion trajectory.
Device Type:
Inventory access varies sharply by screen category, with mobile-first strategies dominating Brazilian retail campaigns while CTV captures premium video budgets.
- Mobile Devices:Smartphone and tablet impressions represent the dominant volume channel across Latin American programmatic markets. Brazilian fintech and e-commerce advertisers allocate disproportionate budgets here, leveraging location and app-usage signals for proximity targeting.
- Smart TVs:Connected television endpoints deliver addressable video impressions with linear-comparable viewership metrics. Inventory scarcity among Mexican and Brazilian broadcasters inflates floor prices for guaranteed completions.
- Desktop Computers:Browser-based inventory retains mature volume leadership in B2B verticals and premium publisher direct sales.
- Tablets:Mid-sized screen inventory captures secondary usage moments with reduced competitive density versus smartphone auctions.
Mobile Devices dominates transaction volumes; Smart TVs climbs fastest in value terms.
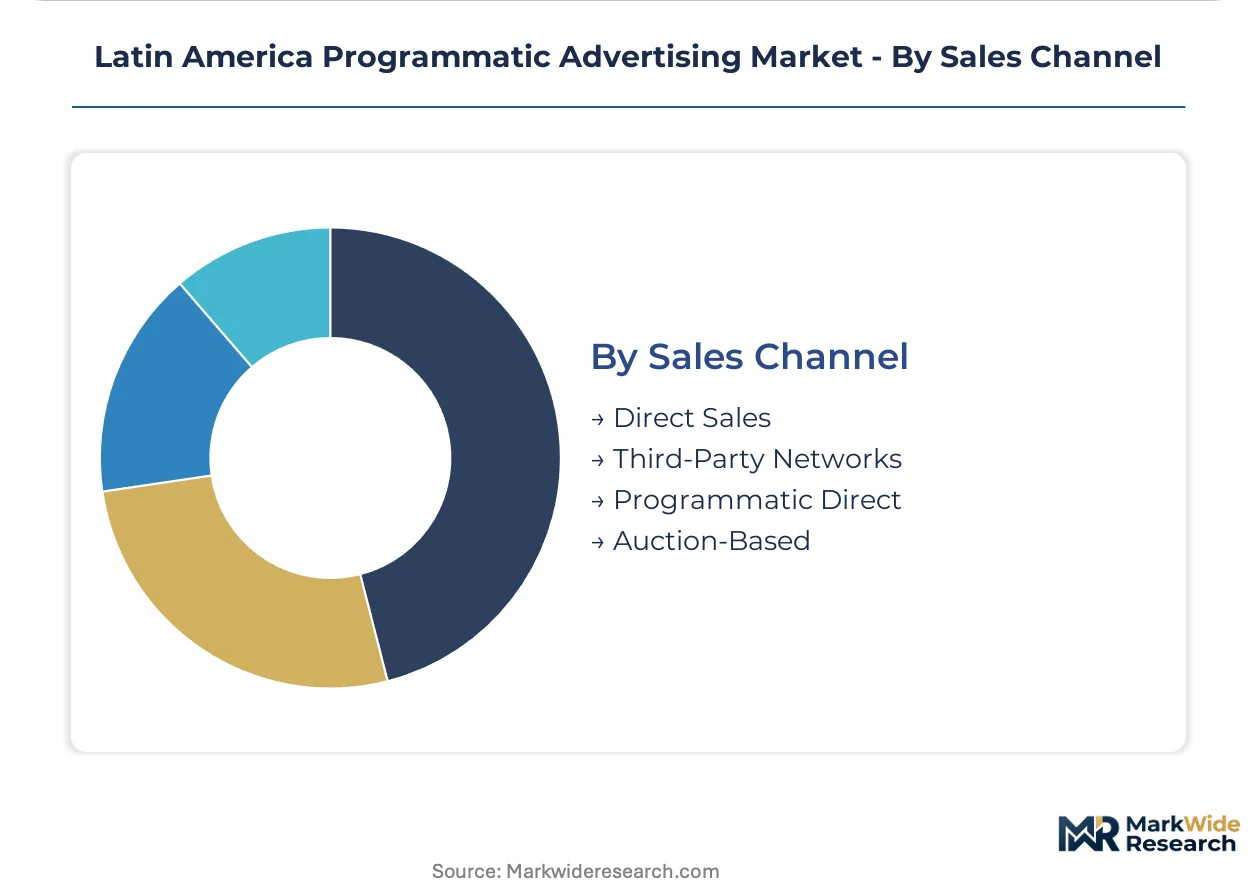
Sales Channel:
Transaction architecture determines price discovery mechanisms and relationship management intensity, with automated channels displacing traditional insertion-order workflows.
- Auction-Based:Open marketplace and private marketplace transactions execute through real-time competitive bidding with dynamic CPM clearing. Colombian and Chilean publishers favor this mode for remnant monetization, though brand safety concerns limit advertiser participation.
- Programmatic Direct:Automated guaranteed deals combine fixed pricing with workflow automation, preserving publisher control over inventory allocation. Mexican retail media networks and Brazilian broadcasters expand this channel for preferred advertiser relationships.
- Direct Sales:Human-negotiated insertion orders persist for premium sponsorship and custom creative executions.
- Third-Party Networks:Aggregator-mediated sales consolidate fragmented publisher supply for simplified buyer access.
Auction-Based channels lead transaction volumes; Programmatic Direct expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's ad-tech workforce concentration anchors Latin America's programmatic infrastructure, with data scientists and algorithmic traders clustering around Brazil's financial capital. Mexico City and Bogotá follow as secondary talent pools, though engineering depth remains thinner. Cross-border campaign execution depends on these three metropolitan nodes.
Brazil
Retail and e-commerce advertisers in São Paulo drive automated media buying volumes, with mobile-first campaigns consuming the majority of DSP budgets. ANPD's 2024 enforcement guidance on legitimate interest assessments restricts behavioral profiling without explicit consent. The São Paulo metro area hosts captive SSP infrastructure operated by domestic media conglomerates, limiting third-party platform penetration.
Mexico
Streaming platforms in Mexico City release premium video impressions into programmatic pipes, compressing auction dynamics for quality CTV inventory. INAI data protection standards reshape audience targeting methodologies and consent architecture for campaigns spanning northern border states. The Bajío Region's manufacturing advertisers are expanding automated guaranteed deals for preferred publisher relationships.
Colombia
FMCG procurement teams in Bogotá demand verified sales lift data before renewing annual platform contracts, shifting spend toward retail media networks with closed-loop attribution. SIC enforcement of data protection standards filters smaller resellers from auction-based sales channels. Publisher consortiums in Medellín pool authenticated user signals as cookieless identity alternatives.
Chile
Santiago's CTV penetration sits above regional averages, attracting early DSP entrants to capture undervalued inventory before competition intensifies. E-commerce marketplaces in the capital open first-party data segments to external demand-side platforms. Proximity targeting bridges online-offline attribution gaps as in-store digitization spreads through Valparaíso metro supermarkets.
Argentina
Fintech advertisers in Buenos Aires allocate disproportionate mobile budgets, leveraging location and app-usage signals for proximity targeting. Mercosur's lack of mutual recognition for data transfer adequacy creates segmentation silos for campaigns spanning Brazil and Argentina. Córdoba's emerging tech cluster supplies mid-market agencies with simplified workflow integration tools.
Latin America Programmatic Advertising Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with cross-border execution capabilities. DSP-SSP consolidation and retail media network expansion define the current phase. Three archetypes dominate: global demand-side platforms with regional data centers, domestic broadcasters operating captive supply-side infrastructure, and retail-ecommerce hybrids monetizing first-party shopper segments. Vertical integration into identity resolution and outcome-based pricing models represent the dominant competitive vectors.
Among global demand-side platforms, MediaMath Inc., The Trade Desk, and Google occupy positions spanning Brazil, Mexico, and Colombia. These firms exemplify the integrated stack archetype, combining algorithmic buying interfaces with data management capabilities. Smaller specialists including Adsmovil LLC and Canela Media sit within the domestic-focused tier, representing regional expertise in mobile and CTV inventory access. Mercado Libre anchors the retail-ecommerce hybrid category, leveraging closed-loop purchase validation to attract FMCG budgets from São Paulo and Mexico City procurement teams.
| Leading Market Players |
|---|
| MediaMath Inc. |
| Adsmovil LLC |
| Mercado Libre |
| The Trade Desk |
| SmartyAds Inc. |
| BidMind by Fiksu |
| Canela Media |
| Jampp Inc. |
| Others |
Supply & Pricing Matrix
FMCG procurement teams in São Paulo and Mexico City anchor demand concentration for programmatic advertising, driving transactional pricing models that reward volume scale and closed-loop attribution capabilities over impression volume guarantees.
Pricing Analysis
Service unbundling separates core platform access from premium data layers and outcome-based measurement modules. SaaS-tiered subscription structures dominate enterprise DSP contracts, while mid-market buyers favor hybrid models blending base fees with performance-linked variable components. Price differentiation rests on data governance certification levels and cross-border execution complexity, with LGPD-compliant platforms commanding premiums. Pricing pressure stems from retail media networks offering closed-loop purchase validation that commoditizes traditional impression-based CPMs. Mid-market agencies show highest price sensitivity, whereas multinational FMCG conglomerates prioritize verified sales lift over unit cost.
Supply Chain Analysis
Return flows of campaign data and audience segments circulate back through publisher consortiums and retail media networks for refinement and reactivation. Supply concentrates in Brazil, Mexico, and Colombia as CTV inventory scales and domestic broadcasters operate captive SSP infrastructure. Raw material dependencies include first-party identity graphs, streaming platform ad slots, and location-triggered mobile impressions. Single-source vulnerability concentrates around Brazilian media conglomerates controlling premium video inventory. Distribution runs through São Paulo-based agencies, Mexico City trading desks, and Bogotá procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America programmatic advertising market functions as a stable compounder, with CTV inventory expansion and retail media network maturation generating recurring revenue pools that deepen platform switching costs.
For Market Incumbents:Acquire first-party data cooperatives and cookieless identity graph assets to fortify audience targeting capabilities as third-party cookies deprecate. Consolidate engineering talent in São Paulo through targeted hiring of data scientists fluent in real-time bidding algorithms. Threats include retail media networks capturing FMCG budgets through closed-loop attribution. Priority levers center on outcome-based pricing models and vertical integration into supply-side infrastructure.
For New Entrants and Emerging Players:Begin with undervalued CTV inventory in Santiago and Lima metro areas before competition intensifies and floor prices inflate. White-space targets include Peruvian streaming platforms and Chilean supermarket digitization projects generating proximity-triggered mobile impressions. Most penetrable segment: mid-market agencies in secondary Colombian cities lacking LGPD compliance engineering. Go-to-market angle: simplified consent management platform integration for smaller resellers filtered from auction channels.
For Investors and Strategic Acquirers:Retail-ecommerce hybrids are the most active acquirer in this space, seeking DSP capabilities to monetize first-party shopper segments. Long-term viability frames around platform consolidation and identity resolution specialization. Target acquisition archetype: domestic-focused mobile and CTV specialists with regional inventory relationships. Signal to watch: ANPD enforcement actions that accelerate compliance cost filtering and create distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Cooperative Formation | Publisher consortiums in Colombia pool authenticated signals as cookieless alternatives. |
| SSAI Technology Deployment | Brazilian broadcasters embed spots directly into streams to bypass ad blockers. |
| Retail Media Network Expansion | Mercado Libre leverages closed-loop purchase validation to attract FMCG budgets. |
| LGPD Compliance Engineering Investment | Consent management platform maintenance raises operational costs that filter smaller resellers. |
| Cross-Border Data Architecture | DSPs reallocate algorithmic bidding capacity to handle Mercosur segmentation silos. |
Research Methodology
Coverage spans Brazil, Mexico, Colombia, Chile, and Argentina, with primary inputs from each market combining interviews with DSP platform engineers, agency trading desk heads, retail media network operators, and ANPD compliance officers. Secondary validation draws from ANPD enforcement guidance, INAI data protection standards, SIC regulatory filings, and streaming platform inventory disclosures. Bottom-up transaction volume modeling and top-down advertiser budget allocation analysis triangulate market sizing.
Rate-of-change decomposition separates volume expansion from value-per-impression growth across the projection horizon. Segmentation dimensions include ad format, technology platform, device type, and sales channel, with additional modeling of data governance cost tiers and cross-border execution complexity. CAGRs derive from algorithmic media buying migration curves and CTV penetration trajectories. Industry-specific forecast inputs incorporate LGPD compliance maturation timelines and retail media network closed-loop attribution adoption.
Several conditions sit outside the modeled scope, including Mercosur data transfer adequacy negotiations and potential ANPD penalties that could reshape platform economics. Forecasts reflect assumptions around CTV inventory release schedules and retail-ecommerce convergence pace. Practitioners should monitor ANPD enforcement intensity and retail media network budget capture rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
North America Advertising Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
US Healthcare Advertising Market