
 Rubus Idaeus (Raspberry) Seed Oil Market | 2026-2036
Rubus Idaeus (Raspberry) Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Rubus Idaeus (Raspberry) Seed Oil Market Analytics
EU REACH is broadening the cost-of-entry calculus for cosmetic ingredient suppliers seeking synthetic-alternative certifications. Aldivia SA leverages its French extraction infrastructure to sustain organic cold-pressed output for European formulators. Botanic Innovations anchors North American supply through supercritical CO2 processing capabilities. O&3 – The Oil Family competes on private-label customization for mid-tier skincare brands.
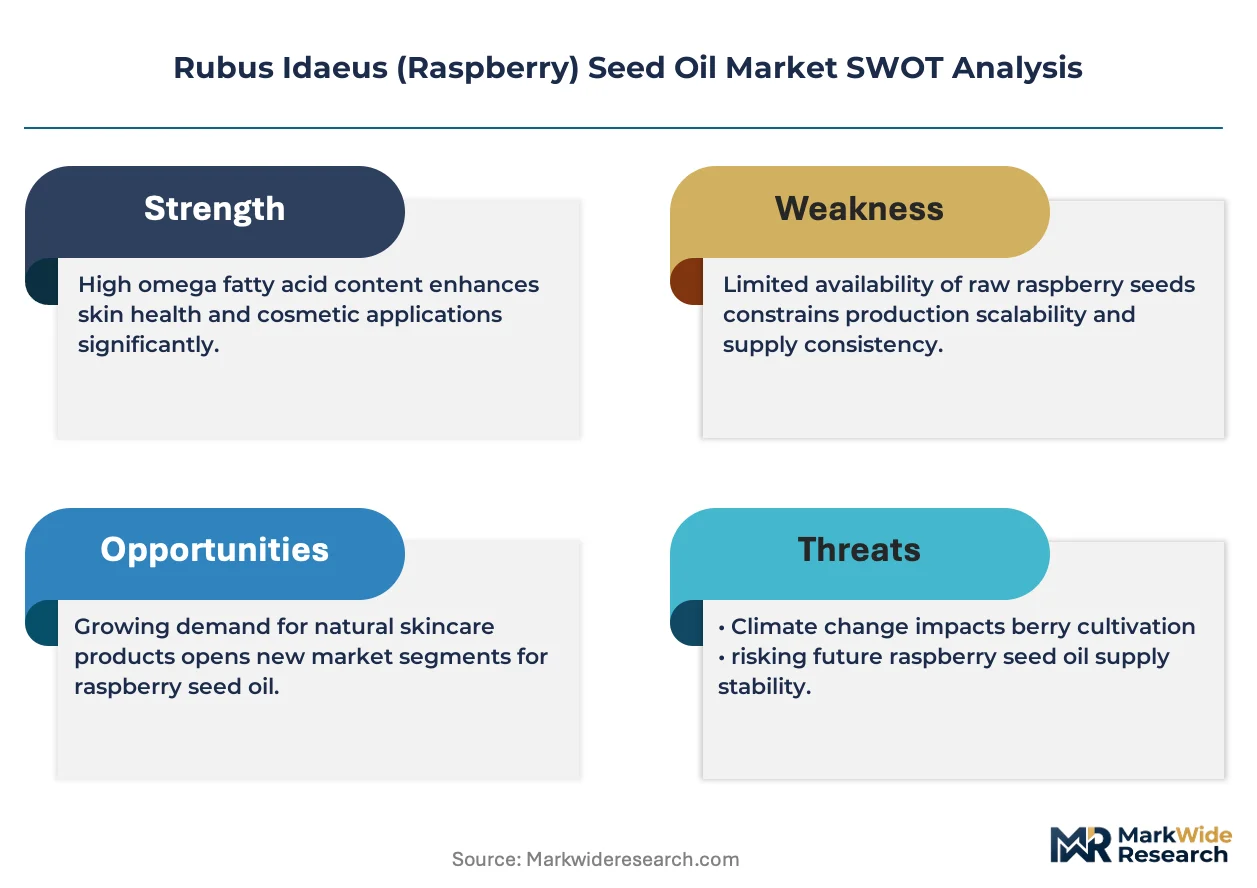
Rubus idaeus seed oil is a triglyceride-rich lipid extracted from raspberry fruit seeds, typically containing 30-35% linoleic acid and notable ellagic acid content, serving primarily as a natural emollient and oxidative-stability agent in topical formulations. Cold-pressed oil commands the premium tier due to retained tocopherol profiles and minimal thermal degradation, while refined oil occupies volume-driven contract manufacturing. Nutraceutical applications represent the fastest-expanding demand pool as softgel manufacturers seek plant-based omega sources beyond flax and chia.
EFSA governs novel food ingredient approvals for raspberry seed oil entering EU nutraceutical channels, while FDA GRAS self-determination shapes US food-grade market access. USDA Organic and Ecocert COSMOS certifications function as de facto gatekeepers for premium cosmetic procurement. Stakeholders must monitor evolving allergen labeling requirements and dual-use pharmaceutical classifications that could redirect supply toward clinical dermatology applications.
Market Dynamics
EU REACH restrictions on synthetic UV filters are redirecting cosmetic formulator procurement toward cold-pressed botanical alternatives with verified SPF-boosting properties. This regulatory compression is concentrating premium supply contracts among certified organic extractors while compressing margins for conventional refined oil processors.
Growth Catalysts
- REACH Annex VI restrictions:The European Chemicals Agency's tightening hazard classifications for oxybenzone and octinoxate are eliminating competing synthetic UV filters from sunscreen formulations.
- Nutraceutical softgel manufacturers:Plant-based omega sourcing beyond flax and chia is accelerating demand for triglyceride-rich raspberry seed oil in dietary supplement channels.
- German cosmetic clusters:Formulation R&D centers in Hamburg and Munich are validating raspberry seed oil for SPF-boosting serum applications through in-vitro UVA/UVB screening protocols.
Market Restraints
- Seed supply concentration:Raspberry pomace availability depends on seasonal fruit processing volumes concentrated in Poland and Serbia, creating raw material volatility.
- Cold-pressed yield limitations:Mechanical extraction without thermal degradation achieves only 8-12% oil recovery versus 18-22% for solvent-refined methods, constraining volume scalability.
- EFSA novel food timelines:European nutraceutical market entry requires 18-24 month safety assessment periods that delay revenue recognition for new suppliers.
Strategic Opportunities
- US GRAS self-determination pathway:FDA's Generally Recognized as Safe notification process allows faster food-grade market access compared to EU novel food requirements.
- Clinical dermatology pivot:Ellagic acid content is attracting pharmaceutical formulators developing topical treatments for UV-induced hyperpigmentation.
- Supercritical CO2 convergence:Combination with tocopherol retention monitoring is enabling premium positioning between cold-pressed and refined quality tiers.
Industry Challenges
- Organic certification lag:Ecocert COSMOS and USDA Organic conversion timelines of 12-18 months mismatch quarterly procurement cycles of major skincare brands.
- Specialized extraction talent:Supercritical CO2 operation requires process engineering expertise scarce in conventional oilseed processing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubus Idaeus (Raspberry) Seed Oil Market |
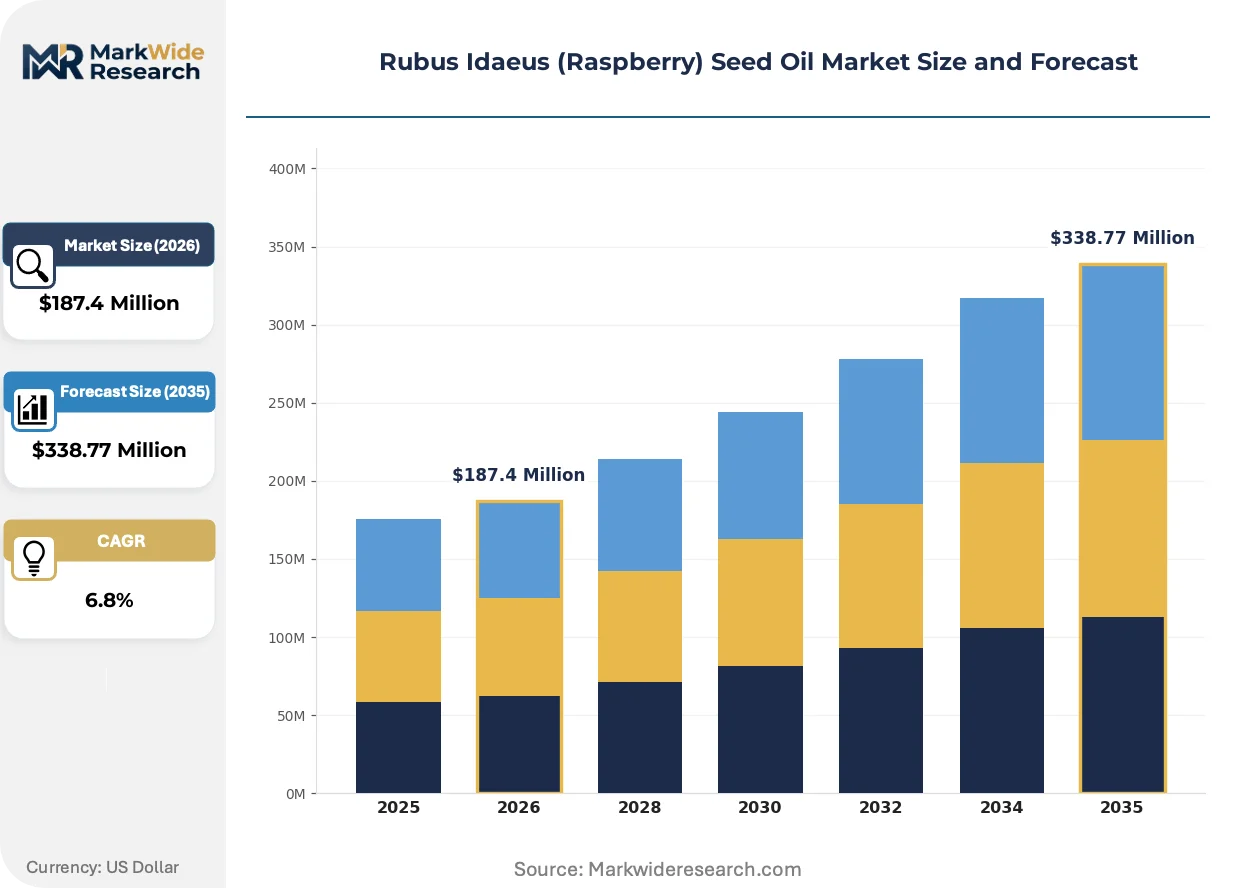
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed Oil, Refined Oil, Unrefined Oil, Extracts Application: Cosmetics, Food Industry, Nutraceuticals, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, Consumers Packaging Type: Bottles, Bulk Containers, Sachets, Jars |
| Companies Covered | Aldivia SA, All Organic Treasures GmbH, Organic Pure Oil, Natural Sourcing, TC USA Inc., Nutrativa Global, O&3 – The Oil Family, Camden-Grey Essential Oils, Botanic Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubus Idaeus (Raspberry) Seed Oil Market Evolving Landscape
Processing technology divergence is fragmenting the supplier base into three distinct capability tiers, each serving different certification and performance requirements. This technological stratification is reshaping competitive positioning without consolidating toward a single dominant method.
Supercritical CO2 extraction is decentralizing quality control from third-party laboratories to processor facilities through integrated tocopherol and ellagic acid real-time monitoring. Mid-tier skincare brands in North America are adopting this technology at accelerated procurement cycles. The structural consequence is compressing reliance on external certification bodies for premium grade verification.
EFSA's 2023 updated guidance on novel food lipid safety assessments is extending toxicological data requirements for botanical oils entering EU nutraceutical channels. Industrial consequence includes mandatory 90-day rodent feeding studies that add €80,000-120,000 to market entry costs. Softgel manufacturers targeting German and French supplement retailers are responding by bifurcating supply chains into EU-compliant and export-only product lines.
Direct-procurement contracts between raspberry seed oil extractors and cosmetic formulators are displacing traditional distributor intermediaries in premium organic channels. German and French skincare brands with dedicated sustainability officers are leading this channel restructuring. The shift is most visible in Western Europe where REACH compliance documentation requirements favor supplier-buyer direct relationships over multi-tier distribution.
Rubus Idaeus (Raspberry) Seed Oil Market Segmentation
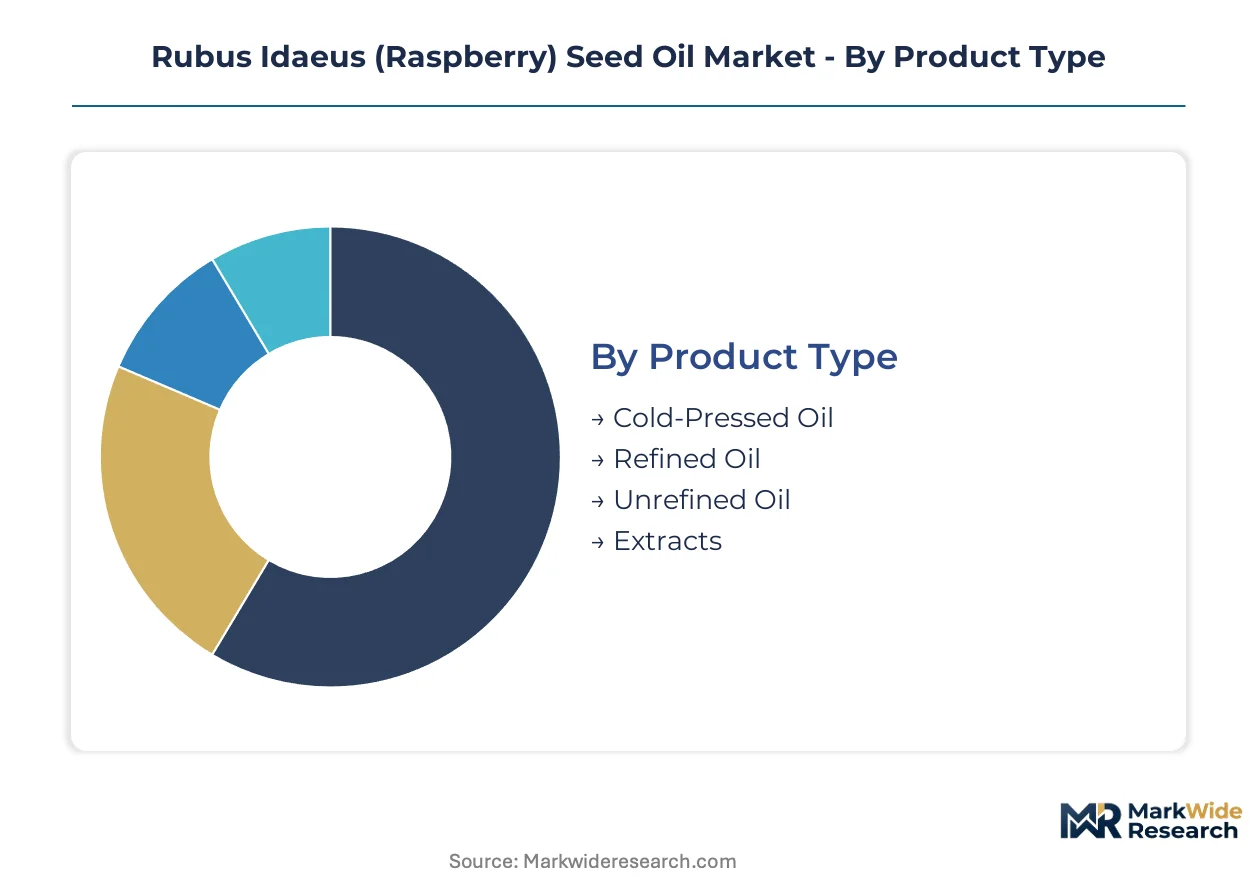
Raspberry seed oil procurement cycles follow distinct upgrade patterns across extraction methods and end-use certifications. Formulators replace conventional refined grades with cold-pressed alternatives as EU REACH compliance tightens, while nutraceutical manufacturers cycle through packaging formats based on softgel line compatibility.
Product Type:
Cold-pressed extraction commands premium positioning as cosmetic formulators replace thermally degraded alternatives with tocopherol-retained grades.
- Cold-Pressed Oil:Mechanical extraction at temperatures below 40°C preserves ellagic acid and vitamin E profiles. German and French serum manufacturers in Hamburg and Munich validation labs are specifying this grade for SPF-boosting formulations as oxybenzone restrictions eliminate synthetic UV filters.
- Refined Oil:Solvent-based processing achieves higher yield but strips bioactive compounds. Volume contracts from contract manufacturers in Poland and Serbia concentrate here, though margin compression intensifies as certified organic alternatives capture premium positioning.
- Unrefined Oil:Minimal processing retains seed particulates and stronger color; niche demand from artisanal skincare producers in Provence and Tuscany.
- Extracts:Standardized ellagic acid concentrates for pharmaceutical formulators developing hyperpigmentation treatments; supercritical CO2 methods enable precise active targeting.
Refined oil sits at the top of the volume ranking, with cold-pressed oil climbing the fastest as REACH-driven substitution accelerates.
Application:
End-use diversification spreads procurement risk across regulatory jurisdictions with divergent approval timelines.
- Cosmetics:SPF-boosting serums and oxidative-stability emollients dominate demand. ECHA's tightening hazard classifications for synthetic UV filters redirect formulator R&D budgets toward botanical alternatives with verified UVA/UVB screening data.
- Nutraceuticals:Plant-based omega softgels represent the steepest expansion trajectory. EFSA novel food requirements impose 18-24 month safety assessments, bifurcating supply chains into EU-compliant and export-only product lines.
- Food Industry:FDA GRAS self-determination enables faster US market entry for culinary-grade oils; bakery and functional food applications in North American premium channels.
- Pharmaceuticals:Clinical dermatology applications leverage ellagic acid content for UV-induced hyperpigmentation protocols; pharmaceutical formulators require GMP-compliant extraction documentation.
Cosmetics maintains the largest revenue share, though nutraceuticals is gaining share fastest as softgel manufacturers diversify beyond flax and chia sourcing.
End User:
Channel restructuring concentrates procurement authority among sustainability-certified manufacturers with direct supplier relationships.
- Manufacturers:Cosmetic and nutraceutical producers with dedicated sustainability officers in Germany and France are eliminating distributor intermediaries. Direct contracts with certified organic extractors satisfy REACH documentation requirements.
- Retailers:Premium organic skincare channels in Western Europe demand Ecocert COSMOS and USDA Organic chain-of-custody verification.
- Distributors:Traditional intermediaries retain relevance in mid-tier and economy segments where certification documentation is less stringent.
- Consumers:Direct-to-consumer brands leverage private-label customization for artisanal positioning; limited volume but highest per-unit margins.
Manufacturers command the largest procurement volumes, with direct-to-consumer channels expanding most quickly through e-commerce specialization.
Packaging Type:
Line compatibility and oxidation protection drive format selection across divergent scale requirements.
- Bulk Containers:Stainless steel totes and drums for contract manufacturers running continuous production; nitrogen flushing preserves tocopherol stability during extended storage.
- Bottles:Amber glass with UV protection for premium cosmetic brands; German and French formulators specify this format for cold-pressed grades.
- Jars:Wide-mouth configurations for balm and mask formulations; secondary packaging with oxygen absorbers extends shelf life.
- Sachets:Single-use pouches for travel-size skincare and sampling programs; growing adoption among direct-to-consumer subscription models.
Bulk containers dominate tonnage shipments, with sachet formats climbing fastest as sampling and subscription economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland pioneered industrial-scale raspberry seed oil extraction during the post-communist agricultural restructuring of the 1990s. Cold-pressing infrastructure developed around fruit processing cooperatives in the Mazovia region established supply chains now serving German cosmetic formulators. Contemporary procurement patterns reflect this historical foundation while diversifying across regulatory jurisdictions.
Poland
Seasonal pomace availability from fruit concentrate processors drives raw material flows. Polish agricultural inspectors enforce EU organic certification standards that govern exports to Western European cosmetic channels. Warsaw and Łódź processing clusters supply refined grades to contract manufacturers facing margin compression from certified organic alternatives.
Germany
Hamburg and Munich R&D centers validate cold-pressed grades for SPF-boosting serum applications through in-vitro UVA/UVB screening protocols. ECHA's REACH Annex VI restrictions on oxybenzone and octinoxate redirect formulator procurement toward botanical UV filter alternatives. Direct contracts between extractors and sustainability-certified manufacturers eliminate traditional distributor intermediaries.
France
Provence artisanal skincare producers sustain niche demand for unrefined grades with seed particulates and stronger color profiles. ANSM cosmetic ingredient oversight aligns with Ecocert COSMOS certification requirements for premium organic channels. Aldivia SA leverages French extraction infrastructure to supply certified organic cold-pressed output meeting REACH documentation standards.
United States
FDA GRAS self-determination enables faster food-grade market entry compared to EU novel food timelines. Supercritical CO2 processing capabilities in North American facilities anchor supply for mid-tier skincare brands seeking tocopherol retention monitoring. Softgel manufacturers diversify plant-based omega sourcing beyond flax and chia through triglyceride-rich raspberry seed oil procurement.
Serbia
Concentrated raspberry cultivation in Šumadija and Western Serbia generates seasonal pomace volumes for solvent-refined oil production. The country's alignment with EU accession processes harmonizes agricultural standards with Western European import requirements. Belgrade-based processors serve volume-driven contract manufacturing segments where certification documentation demands remain less stringent.
Rubus Idaeus (Raspberry) Seed Oil Market Competitive Landscape
The competitive structure tilts toward extraction-technology specialists with certified organic capabilities. Player concentration fragments across three capability tiers defined by processing method and certification status. French and German cold-press operators occupy the premium tier, North American supercritical CO2 processors anchor the mid-market, and Polish solvent-refined facilities serve volume contracts. Dominant competitive moves include direct-procurement contract expansion and supercritical CO2 capacity licensing.
Within the premium-tier extraction segment, Aldivia SA and Botanic Innovations occupy positions defined by geographic certification advantages and processing technology differentiation. O&3 – The Oil Family sits within the private-label customization segment serving mid-tier skincare brands with flexible procurement terms. All Organic Treasures GmbH represents the German organic certification cluster where Ecocert COSMOS compliance creates supply chain preference. These three archetypes—geography-certified premium extractors, technology-differentiated processors, and customization-focused private-label suppliers—structure competitive positioning without consolidating toward single-method dominance.
| Leading Market Players |
|---|
| Aldivia SA |
| All Organic Treasures GmbH |
| Organic Pure Oil |
| Natural Sourcing |
| TC USA Inc. |
| Nutrativa Global |
| O&3 – The Oil Family |
| Camden-Grey Essential Oils |
| Botanic Innovations |
| Others |
Value Network & Pricing Analysis
EU REACH-mandated shifts from synthetic UV filters toward botanical SPF boosters are compressing procurement timelines for certified organic cold-pressed grades, forcing extractors to absorb certification costs or cede volume to solvent-refined competitors in Poland and Serbia.
Pricing Analysis
Bundled certification-and-extraction services command premiums over unbundled commodity supply, with Ecocert COSMOS and USDA Organic tiers separating cold-pressed from refined grades. Price differentiation rests on tocopherol retention verification and supercritical CO2 capability, not volume scale alone. Cost compression in conventional refined tiers intensifies as German and French formulators consolidate direct contracts with certified suppliers. Contract manufacturers running continuous production lines exhibit highest price sensitivity, while prestige skincare brands with dedicated sustainability officers accept premium positioning for documented chain-of-custody.
Supply Chain Analysis
Freight costs from Polish and Serbian processing clusters to Hamburg and Munich formulation centers constrain margin structures for volume-driven refined grades. Raw material flows draw from seasonal raspberry pomace availability concentrated in Mazovia and Šumadija fruit processing cooperatives. Supply chain risk centers on single-source vulnerability during harvest windows, with no viable seed substitutes for triglyceride-rich lipid profiles. Distribution runs through direct-procurement contracts between extractors and sustainability-certified manufacturers, displacing traditional distributor intermediaries in premium channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA GRAS self-determination in the United States and EFSA novel food timelines in the European Union, with the eighteen-to-twenty-four-month differential creating first-mover advantages for North American nutraceutical entrants.
For Market Incumbents: Acquire supercritical CO2 processing capabilities to defend premium positioning against cold-pressed competitors. Backward integration into Polish and Serbian pomace sourcing secures raw material continuity against seasonal volatility. Certification investment in dual USDA Organic and Ecocert COSMOS compliance creates switching costs for German and French formulators facing REACH documentation requirements.
For New Entrants and Emerging Players: Capture the US nutraceutical softgel channel where FDA GRAS self-determination enables faster revenue recognition than EU novel food pathways. Private-label customization for mid-tier skincare brands offers penetrable white-space with flexible procurement terms. Position through tocopherol retention monitoring as a quality verification service, not merely commodity supply.
For Investors and Strategic Acquirers: Asymmetric upside sits with supercritical CO2 processors bridging cold-pressed and refined quality tiers. Long-term viability over the next decade hinges on clinical dermatology pivot potential for ellagic acid concentrates. Watch EFSA novel food approval velocity as the inflection signal for EU nutraceutical supply chain reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables real-time tocopherol monitoring for premium positioning between extraction tiers. |
| Dual Certification Investment | USDA Organic plus Ecocert COSMOS compliance satisfies German and French REACH documentation demands. |
| Backward Integration into Pomace Sourcing | Captive supply from Polish and Serbian fruit processors reduces seasonal raw material volatility. |
| Clinical Dermatology Partnership | Ellagic acid concentrate supply agreements with pharmaceutical formulators open hyperpigmentation treatment channels. |
| Direct-to-Consumer Brand Launch | E-commerce specialization in sachet formats captures highest per-unit margins with subscription economics. |
Research Methodology
Bottom-up softgel manufacturer and cosmetic formulator modeling reconciled against top-down extraction capacity tracking forms the analytical core. Primary interviews with plant managers at Polish and Serbian processing facilities, procurement leads at German and French skincare brands, and regulatory affairs specialists navigating EFSA novel food pathways combined with secondary validation from customs trade data, Ecocert certification registries, and FDA GRAS notification filings. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of cold-pressed versus refined grade procurement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include extraction method, application channel, certification tier, and regional regulatory cluster. CAGRs derive from weighted capacity expansion announcements and substitution elasticity estimates for botanical UV filters replacing synthetic alternatives. Forecast inputs incorporate seasonal pomace availability cycles and supercritical CO2 technology adoption curves.
Underlying measurement precision varies by segment; nutraceutical application forecasts carry tighter precision than pharmaceutical pivot scenarios given established softgel manufacturer demand patterns. Forecasts reflect documented assumptions about EFSA approval timelines and REACH enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
Chile Fruits and Vegetables Market
Fruits and Vegetables
Passion Fruit Extract Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Mulberry Market