
 LPWAN Market | 2026-2036
LPWAN Market Size, Share, and Industry Trends Forecast 2026-2036
LPWAN Market Analytics
REACH is repositioning material compliance costs upward for European module manufacturers. Huawei Technologies leverages captive semiconductor fabrication to control chipset supply for NB-IoT deployments. Qualcomm anchors its position through R&D intensity in integrated baseband architectures for unlicensed spectrum protocols. Vodafone Group dominates wholesale network provisioning across multiple European national markets.
Low-Power Wide-Area Network denotes wireless communication systems operating in sub-gigahertz or licensed cellular bands with payload rates below 50 kbps, battery lifetimes exceeding ten years, and penetration through dense urban infrastructure or underground environments. The technology serves industrial telemetry, utility metering, and agricultural sensing where cellular broadband proves economically unviable. NB-IoT captures the dominant share of operator-led deployments due to 3GPP standardization and licensed spectrum security. LoRaWAN sustains faster growth in private network configurations where enterprises require unlicensed operational autonomy. Smart Cities application clusters concentrate margin pools as municipal procurement bundles connectivity with decade-long maintenance obligations.
The FCC governs unlicensed ISM band power limits in the United States, constraining link budget calculations for Sigfox and LoRaWAN architectures. ETSI harmonizes European spectrum access rules while China's MIIT allocates dedicated NB-IoT carriers through state-coordinated licensing. Stakeholders must monitor evolving national spectrum auctions and 3GPP release timelines to calibrate technology roadmaps against regulatory certainty windows.
Market Dynamics
NB-IoT chipset supply concentration is compressing module vendor margins while state-backed procurement mandates in China accelerate deployment velocity beyond organic enterprise demand curves.
Growth Catalysts
- REACH material compliance:European manufacturers face escalating substitution costs for restricted substances, driving premium module pricing that sustains vendor R&D recovery rates.
- Smart city infrastructure bundling:Municipal procurement in Barcelona, Munich, and Singapore packages decade-long maintenance obligations with initial sensor network capital outlays.
- Industrial telemetry telemetry expansion:Underground mining and agricultural sensing applications exploit sub-gigahertz penetration where cellular broadband economics fail.
Market Restraints
- Semiconductor fabrication concentration:Captive foundry access limits second-source options for NB-IoT baseband silicon, concentrating supply risk with Asian integrated device manufacturers.
- Licensed spectrum auction costs:National carrier spectrum fees inflate operator-led deployment total cost of ownership relative to unlicensed alternatives.
- Payload rate ceiling:Sub-50 kbps throughput constraints exclude video and audio streaming applications from addressable use cases.
Strategic Opportunities
- Private LoRaWAN autonomy:Enterprise unlicensed network configurations bypass carrier dependency for industrial campus and logistics yard coverage.
- EU Green Deal alignment:Carbon accounting mandates create sensor demand for utility metering and building energy management retrofits.
- NB-IoT and satellite convergence:Hybrid terrestrial-satellite architectures extend coverage to maritime and remote terrestrial assets without dedicated ground infrastructure.
Industry Challenges
- RF engineering talent scarcity:Sub-gigahertz antenna design and link budget optimization skills concentrate with legacy cellular equipment vendors.
- Multi-protocol certification backlog:3GPP release timelines and national type approval queues delay product market entry by 12-18 months.
- Legacy SCADA integration friction:Brownfield industrial sites require protocol translation gateways that inflate deployment complexity and hardware BOM costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LPWAN Market |
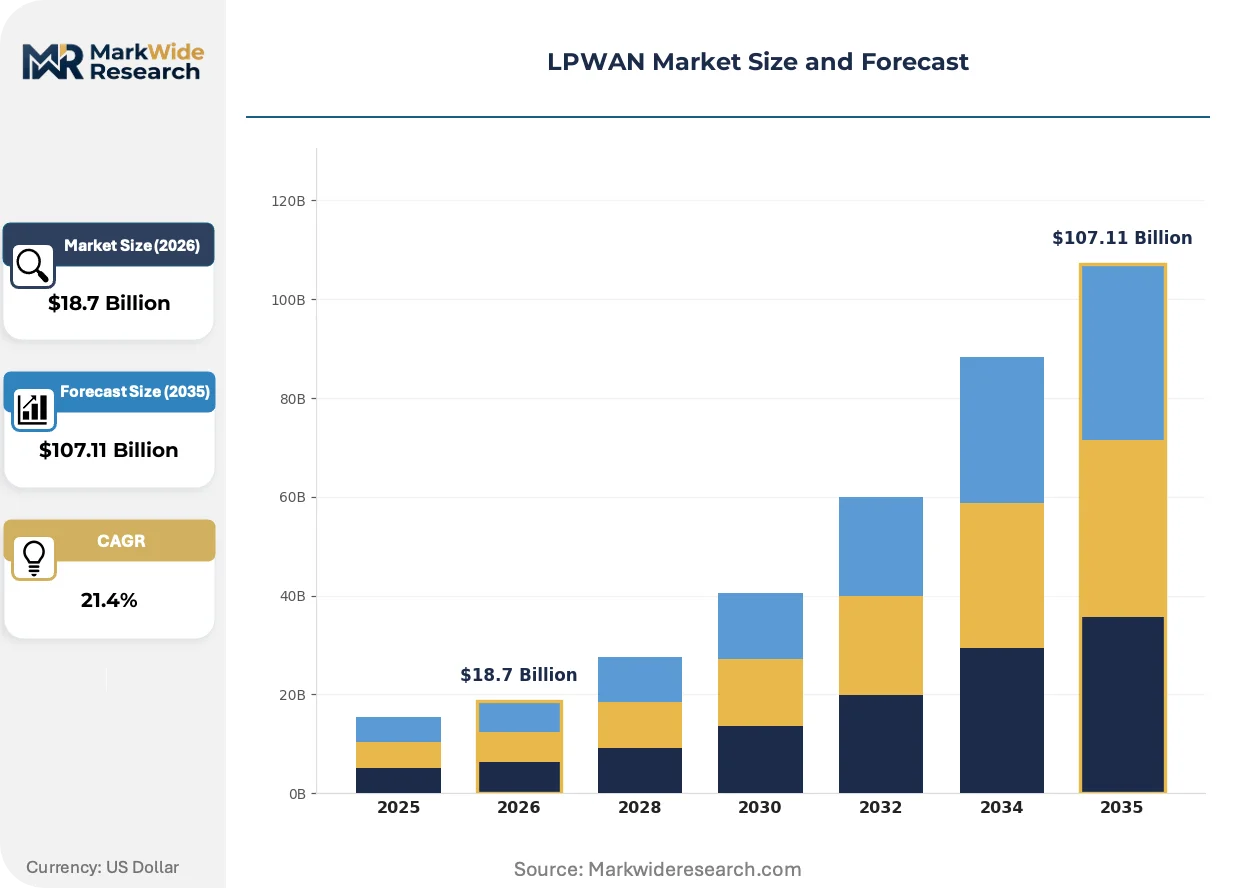
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LoraWAN, Sigfox, NB-IoT, Weightless Application: Smart Cities, Agriculture Monitoring, Asset Tracking, Environmental Monitoring End User: Telecom Providers, Transportation, Utilities, Retail Deployment: Public Network, Private Network, Hybrid Network, Others |
| Companies Covered | Huawei Technologies, Telefónica, Sigfox, Qualcomm, AT&T, Actility, Vodafone Group, Sierra Wireless, Semtech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LPWAN Market Evolving Landscape
Integrated baseband architectures are compressing module form factors while regulatory harmonization accelerates cross-border certification portability.
Multi-protocol system-on-chip designs are consolidating discrete modem, power amplifier, and RF front-end functions into single-die implementations. Agricultural OEMs and smart meter manufacturers are adopting these consolidated platforms to reduce PCB area and simplify antenna matching networks. The structural consequence is margin compression for discrete component suppliers as module vendors internalize subsystem value.
ETSI spectrum harmonization directives are eliminating national derogations for unlicensed sub-gigahertz operation across EU member states. Industrial sensor manufacturers now design once for pan-European deployment without frequency band variants. German logistics operators and Dutch greenhouse automation suppliers are the primary beneficiaries, accelerating cross-border fleet and facility standardization.
Hardware-as-a-service contracting is displacing capital purchase models for municipal sensor networks. Barcelona's infrastructure authority and Singapore's Land Transport Authority now lease connectivity with embedded maintenance and refresh cycles. This shift concentrates vendor balance sheet exposure with European and Asian equipment financiers while transferring obsolescence risk from public sector buyers.
LPWAN Market Segmentation
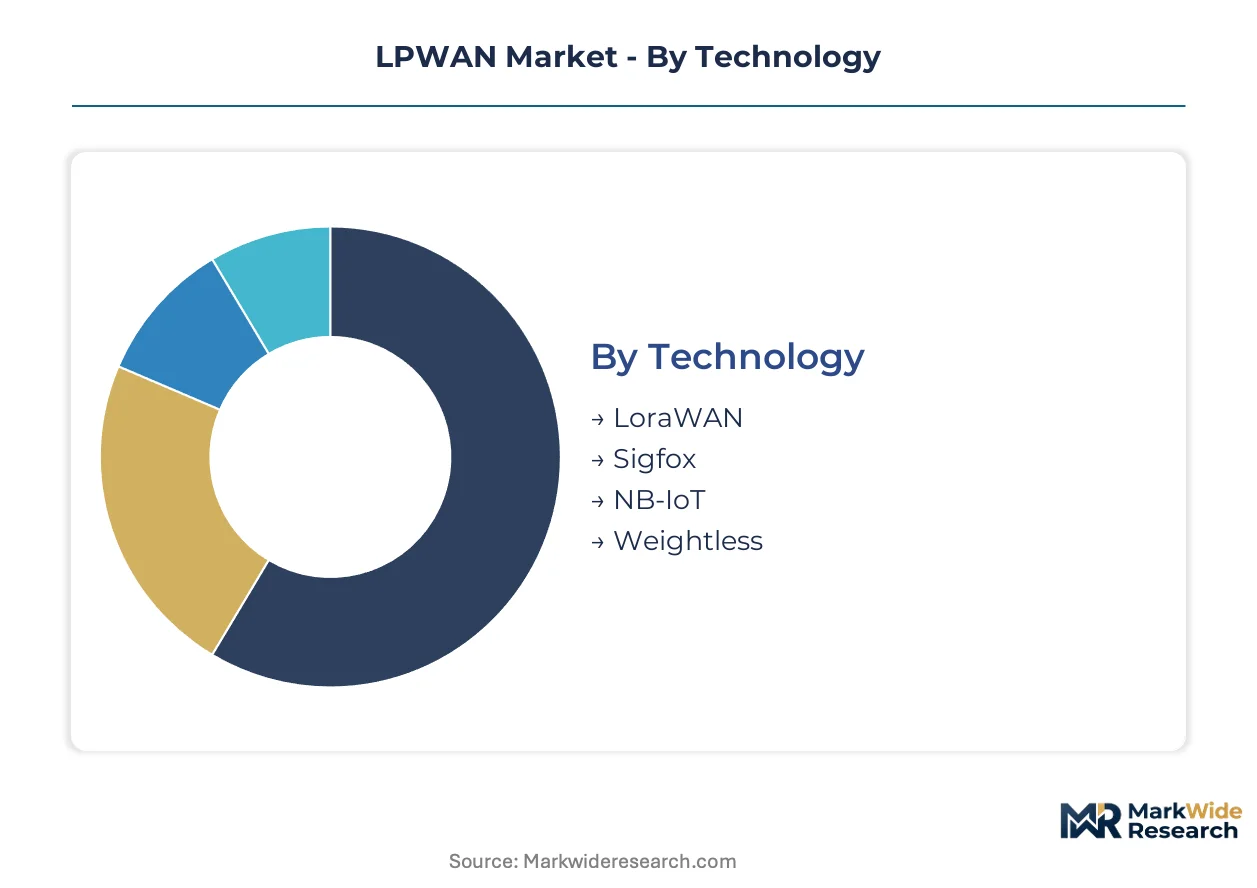
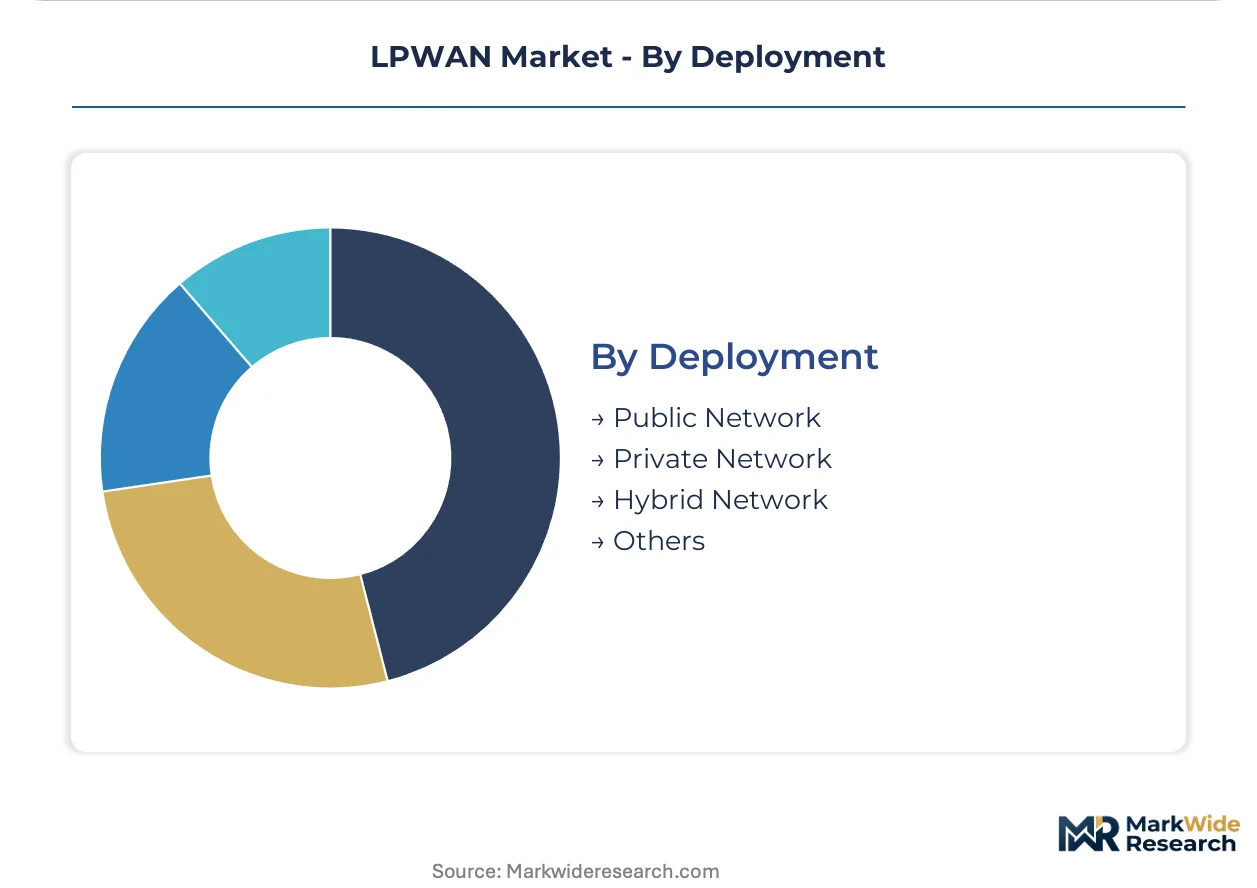
LPWAN procurement patterns diverge sharply across technology standards and deployment models. Supply chain concentration in baseband silicon and spectrum licensing regimes create divergent margin structures that reward precise segment targeting.
Technology:
Foundry capacity for integrated baseband architectures concentrates with Asian semiconductor manufacturers, compressing module vendor margins unevenly across protocol types.
- NB-IoT:Licensed spectrum operation through 3GPP-standardized narrowband cellular delivers guaranteed quality-of-service for carrier-led deployments. China MIIT-coordinated spectrum allocation and state-backed procurement mandates concentrate volume demand in industrial corridor deployments where module integration with existing cellular infrastructure minimizes deployment friction.
- LoRaWAN:Unlicensed sub-gigahertz modulation enables private network autonomy without carrier dependency. Enterprise campus and logistics yard configurations in Germany and the Netherlands exploit ETSI-harmonized spectrum rules to deploy cross-border standardized equipment with single-SKU procurement.
- Sigfox:Ultra-narrowband proprietary protocol optimized for minimal power draw in simple sensor payloads.
- Weightless:Open-standard technology targeting TV white space and sub-gigahertz ISM bands for regional utility deployments.
Today's leader: NB-IoT. Tomorrow's challenger: LoRaWAN.
Application:
Municipal procurement bundling concentrates capital deployment in decade-long maintenance contracts that reshape vendor cash flow profiles.
- Smart Cities:Integrated sensor networks spanning street lighting, waste management, and parking occupancy monitoring. Barcelona and Singapore infrastructure authorities package connectivity with embedded refresh cycles, transferring obsolescence risk to European and Asian equipment financiers.
- Agriculture Monitoring:Soil moisture, microclimate, and livestock tracking sensors exploit sub-gigahertz penetration through dense vegetation. Dutch greenhouse automation suppliers and Australian broadacre farming operations drive demand for decade-battery-life devices in remote coverage gaps.
- Asset Tracking:Container, fleet vehicle, and industrial equipment location monitoring with intermittent payload transmission.
- Environmental Monitoring:Air quality, water table, and seismic sensor networks for regulatory compliance and early warning systems.
Smart Cities commands current procurement volume. Agriculture Monitoring climbs the fastest as carbon accounting mandates expand sensor retrofits.
End User:
Customer procurement sophistication ranges from wholesale network provisioning to discrete equipment purchasing with divergent technical specification depth.
- Telecom Providers:Wholesale network operators provision licensed spectrum connectivity as managed service offerings. Vodafone Group's multi-national European infrastructure anchors operator-led deployment velocity through standardized roaming agreements.
- Utilities:Electricity, water, and gas distribution operators mandate meter-to-cash telemetry with regulatory-grade security. EU Green Deal carbon accounting obligations accelerate smart metering retrofit timelines across member states.
- Transportation:Fleet logistics and infrastructure operators requiring mobile asset visibility.
- Retail:Supply chain and cold-chain monitoring for inventory and perishable goods tracking.
Telecom Providers dominate wholesale revenue. Utilities show steepest expansion trajectory from regulatory compliance mandates.
Deployment:
Network architecture selection determines spectrum access costs, coverage autonomy, and long-term vendor dependency structures.
- Public Network:Carrier-operated licensed spectrum infrastructure with per-device subscription pricing. National spectrum auction costs inflate total cost of ownership relative to alternatives while delivering guaranteed service level agreements for critical infrastructure.
- Private Network:Enterprise-owned unlicensed infrastructure eliminating recurring carrier fees. German manufacturing campuses and Dutch logistics hubs exploit ETSI harmonization to standardize cross-facility equipment procurement.
- Hybrid Network:Terrestrial-satellite convergence architectures extending coverage to maritime and remote terrestrial assets.
- Others:Emerging mesh and community-operated configurations for specialized coverage requirements.
Public Network holds installed base dominance. Private Network gains share fastest as enterprise autonomy requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LPWAN infrastructure originated in European unlicensed spectrum deployments before licensed cellular variants scaled through Asian state-coordinated procurement programs.
China
Industrial corridor sensor networks drive module procurement at massive scale through state-backed IoT integration mandates. MIIT allocates dedicated NB-IoT carriers through coordinated licensing frameworks that accelerate deployment velocity. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta concentrate chipset integration facilities.
Germany
Automotive OEMs and industrial equipment manufacturers mandate private network autonomy for campus and logistics yard coverage. ETSI harmonization eliminates national derogations for unlicensed sub-gigahertz operation across EU member states. Bavarian manufacturing campuses exploit standardized equipment procurement for cross-facility fleet management.
United States
Utility operators and agricultural sensor networks exploit sub-gigahertz penetration through dense vegetation and remote coverage gaps. FCC power limits in ISM bands constrain link budget calculations for unlicensed architectures. California agricultural OEMs and Texas oilfield telemetry providers anchor demand concentration.
Singapore
Land Transport Authority infrastructure deployments package decade-long maintenance obligations with initial sensor network capital outlays. National digital transformation programs accelerate smart city sensor rollouts through bundled procurement. Municipal procurement concentrates margin pools in integrated connectivity contracts.
Netherlands
Greenhouse automation suppliers and logistics operators drive demand for cross-border standardized equipment with single-SKU procurement. EU Green Deal carbon accounting mandates accelerate sensor retrofits for building energy management. Dutch agricultural clusters exploit ETSI-harmonized spectrum rules for pan-European deployment portability.
LPWAN Market Competitive Landscape
The competitive structure tilts toward integrated baseband specialists with captive semiconductor fabrication access. Tiered positioning separates licensed spectrum cellular incumbents from unlicensed protocol pure-plays. Three archetypes dominate: Asian chipset-integrated module vendors, European carrier-affiliated network operators, and North American RF semiconductor specialists. Consolidation pressure concentrates through multi-protocol certification requirements and foundry capacity constraints.
Among Asian integrated device manufacturers, Huawei Technologies exemplifies the captive fabrication archetype through in-house baseband silicon production. Qualcomm anchors the RF semiconductor specialist tier with R&D intensity in integrated architectures. Vodafone Group represents carrier-affiliated network provisioning across multiple European national markets.
| Leading Market Players |
|---|
| Huawei Technologies |
| Telefónica |
| Sigfox |
| Qualcomm |
| AT&T |
| Actility |
| Vodafone Group |
| Sierra Wireless |
| Semtech Corporation |
| Others |
Value Network & Pricing Analysis
Municipal infrastructure authorities in Barcelona, Munich, and Singapore anchor demand concentration through decade-long maintenance-bundled procurement contracts that compress module vendor margins while sustaining premium pricing for integrated connectivity solutions.
Pricing Analysis
Subscription-based hardware-as-a-service contracting dominates municipal and enterprise procurement, displacing capital purchase models across European and Asian smart city deployments. Price differentiation rests on certification grade—REACH-compliant modules command premiums against baseline SKUs—and volume scale with state-backed procurement mandates in China. Cost compression in NB-IoT baseband silicon is intensifying because foundry capacity concentrates with Asian integrated device manufacturers. Utilities exhibit lowest price sensitivity due to regulatory-grade security requirements, while agricultural OEMs drive hardest bargain negotiations for decade-battery-life sensor platforms.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs and Dutch logistics operators mandate multi-supplier qualification for baseband silicon and RF front-end components, fragmenting procurement across qualified vendor lists. Manufacturing gravity centers on China for module integration, Taiwan for foundry capacity, and South Korea for memory components. Raw material dependencies span gallium arsenide substrates, sub-gigahertz crystal oscillators, and REACH-restricted substance substitutes. Single-source vulnerability in captive semiconductor fabrication feeds supply risk concentration. Distribution runs through carrier-affiliated wholesale channels and direct enterprise procurement for private network configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon accounting mandates in Europe against MIIT-coordinated spectrum allocation costs in China create a geographic-arbitrage window for module vendors optimizing regulatory compliance spend against procurement scale economics.
For Market Incumbents: To counter LoRaWAN private network autonomy eroding carrier-led subscription revenue, Qualcomm and Huawei Technologies must deepen captive foundry access for integrated baseband architectures while accelerating multi-protocol certification investment to compress 12-18 month type approval timelines that delay market entry. For New Entrants and Emerging Players: ETSI spectrum harmonization directives in Germany and the Netherlands open a window for unlicensed protocol specialists to exploit single-SKU pan-European deployment portability. Target Dutch greenhouse automation suppliers and Bavarian manufacturing campuses with hardware-as-a-service contracting models that transfer obsolescence risk to equipment financiers. For Investors and Strategic Acquirers: Carrier-affiliated network operators are the most active acquirer in this space, consolidating wholesale provisioning capabilities across national markets. Five-to-ten year viability hinges on satellite-terrestrial hybrid architecture execution. Watch NB-IoT and satellite convergence timelines as inflection indicator for remote coverage asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Investment | Compresses 3GPP release timeline delays that currently stall product launches by 12-18 months. |
| Captive Foundry Capacity Expansion | Secures baseband silicon supply against Asian integrated device manufacturer concentration risk. |
| Hardware-as-a-Service Contracting | Transfers obsolescence risk from Barcelona and Singapore municipal buyers to equipment financiers. |
| Satellite-Terrestrial Hybrid Architecture | Extends NB-IoT coverage to maritime and remote terrestrial assets without ground infrastructure. |
| REACH Compliance Substitution | Sustains premium module pricing for European manufacturers facing escalating material compliance costs. |
Research Methodology
Bottom-up smart city and agricultural sensor deployment modeling reconciled against top-down baseband silicon production tracking forms the analytical core of this study. Primary interviews with municipal procurement officers, carrier network architects, agricultural OEM product managers, and RF engineering directors combined with secondary validation against FCC spectrum allocation records, ETSI harmonization directives, MIIT licensing frameworks, and 3GPP release documentation. Triangulation across supply-side foundry capacity disclosures and demand-side module procurement data ensures segmentation integrity.
Input-output matrix framing maps technology standard adoption curves against application-specific deployment velocity across the analysis window. Segmentation dimensions modeled include technology protocol, deployment architecture, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from unit shipment trajectories calibrated against average selling price erosion curves and maintenance contract renewal rates. Forecast inputs incorporate spectrum auction timing, REACH substance restriction timelines, and state-backed IoT integration mandate velocity.
Revisions become necessary when 3GPP release timelines slip, national spectrum auctions delay, or REACH substance restrictions expand beyond current scope. Deviation in MIIT-coordinated procurement mandate intensity or ETSI harmonization implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Digital Smart Set-Top Box (STB) Market
Telecom Hardware
Commercial Antennas Market
Telecom Hardware
Global FPGA in Telecom Sector Market
Telecom Hardware
Telecom Equipment Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Broadcast Antenna Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Room Cell Module Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
4G Equipment Market
Telecom Hardware
Africa Small Cell Market