
 Mobile Social Networks Market | 2026-2036
Mobile Social Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Social Networks Market Foresight
AI-generated content is repositioning creative production economics across mobile social platforms, reducing marginal costs for personalized feeds and targeted advertising. Meta Platforms leverages its Reality Labs division to sustain hardware-software integration for immersive social experiences. ByteDance anchors its competitive edge through algorithmic content distribution that dominates short-form video engagement. Tencent competes by extending its super-app architecture across messaging, payments, and mini-program ecosystems.
Mobile social networks constitute software platforms enabling user-generated content creation, distribution, and interaction through native smartphone applications operating on iOS and Android operating systems with real-time data synchronization and push notification architectures. Their primary commercial purpose centers on capturing user attention for monetization through advertising and transactional services. The monetization model segment shows advertising remains the dominant revenue pool while in-app purchases represent the fastest-growing structural category driven by virtual gifting and creator economy tipping. User demographics skew heavily toward teenagers and young adults, though professionals represent an emerging margin concentration as B2B networking features expand on established platforms.
The EU Digital Services Act and GDPR impose content moderation and data processing obligations that shape platform operating costs and market access conditions across Europe. In the United States, FCC oversight of broadband infrastructure and Section 230 liability frameworks influence platform business model sustainability and investment priorities. India's IT Rules under MeitY mandate traceability and grievance redressal mechanisms that alter product architecture for platforms serving its massive user base. Stakeholders must monitor evolving interoperability mandates and algorithmic transparency requirements that will determine competitive moats and compliance expenditures across jurisdictions.
Market Dynamics
Algorithmic content distribution systems are compressing attention economics across mobile social platforms, forcing infrastructure investments in GPU clusters and edge computing nodes to sustain real-time personalization at scale.
Growth Catalysts
- India's IT Rules under MeitY:Traceability mandates for encrypted messaging platforms are accelerating compliance architecture investments that strengthen platform legitimacy and user trust in the world's largest emerging market.
- Short-form video consumption:ByteDance's algorithmic recommendation engine has conditioned user expectations for instant gratification content feeds, driving platform R&D budgets toward similar predictive systems.
- Creator economy tipping infrastructure:Virtual gifting mechanisms embedded in livestreaming applications are expanding monetization beyond advertising into direct fan-to-creator value transfer.
Market Restraints
- EU Digital Services Act compliance costs:Content moderation obligations and algorithmic transparency requirements impose operational overhead that compresses margins for platforms serving European member states.
- Data localization mandates:India's directive for domestic storage of sensitive personal information forces redundant infrastructure deployment and fragments cloud architecture economics.
- Attention saturation thresholds:User screen-time plateaus in mature smartphone markets limit organic engagement growth and intensify acquisition cost inflation.
Strategic Opportunities
- Brazil's underpenetrated professional networking segment:LinkedIn's incomplete coverage of Latin American SME ecosystems creates white space for super-app platforms to integrate B2B discovery tools.
- Convergence of social commerce and embedded finance:TikTok Shop and Instagram Checkout are merging content discovery with instant payment settlement, collapsing the purchase funnel.
- Indonesia's rural digital inclusion programs:Government-subsidized 4G expansion into outer islands is activating first-time smartphone users with high content consumption propensity.
Industry Challenges
- Trust and safety engineering talent scarcity:Platforms face acute shortages of machine learning specialists capable of building multilingual content moderation systems at billion-user scale.
- Legacy advertising measurement integration:Apple's ATT framework fragmentation forces reconstruction of attribution models that previously relied on deterministic device-level tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Social Networks Market |
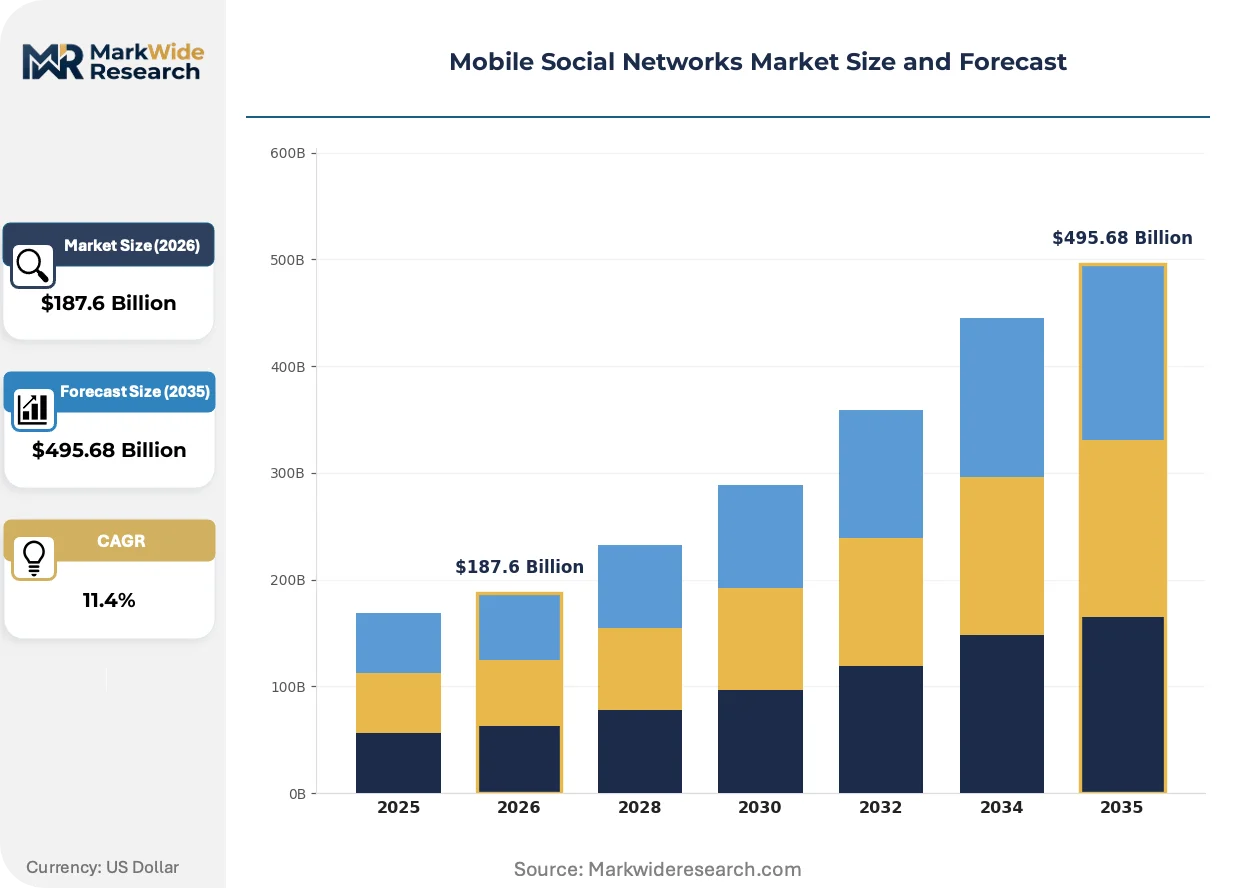
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Messaging, Photo Sharing, Video Streaming, Live Broadcasting User Demographics: Teenagers, Young Adults, Professionals, Seniors Monetization Model: Advertising, Subscription, In-App Purchases, Sponsorship Content Type: Text, Images, Videos, Stories |
| Companies Covered | Meta Platforms, Alphabet Inc., ByteDance, Tencent, Snap Inc., Telegram, Reddit, Microsoft, Discord, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Social Networks Market Shifts & Advancements
Synthetic media production tools are redistributing creative authority from professional studios to individual users, compressing content production timelines from days to minutes and flooding distribution channels with algorithm-optimized material.
Generative AI inference engines are modularizing video editing workflows across mobile social applications. Teenage creators and micro-influencers adopt these tools fastest, generating polished short-form content without professional software licenses. This compression is modularizing the traditional post-production supply chain and collapsing barriers between amateur and professional output quality.
The EU AI Act's transparency obligations for recommender systems are forcing disclosure of ranking parameters and user profiling logic. Platform engineering teams must rebuild proprietary algorithms around auditable decision trees rather than opaque neural weights. Short-form video applications face the steepest compliance curve given their dependence on behavioral prediction models.
Brand procurement of influencer marketing is consolidating around platform-native analytics dashboards that displace third-party measurement vendors. Marketing teams at consumer packaged goods companies now negotiate directly through TikTok Creator Marketplace and Instagram Creator Studio rather than independent talent agencies. This channel shift is most visible in Southeast Asia, where direct platform relationships reduce commission overhead and accelerate campaign deployment cycles.
Mobile Social Networks Market Segmentation
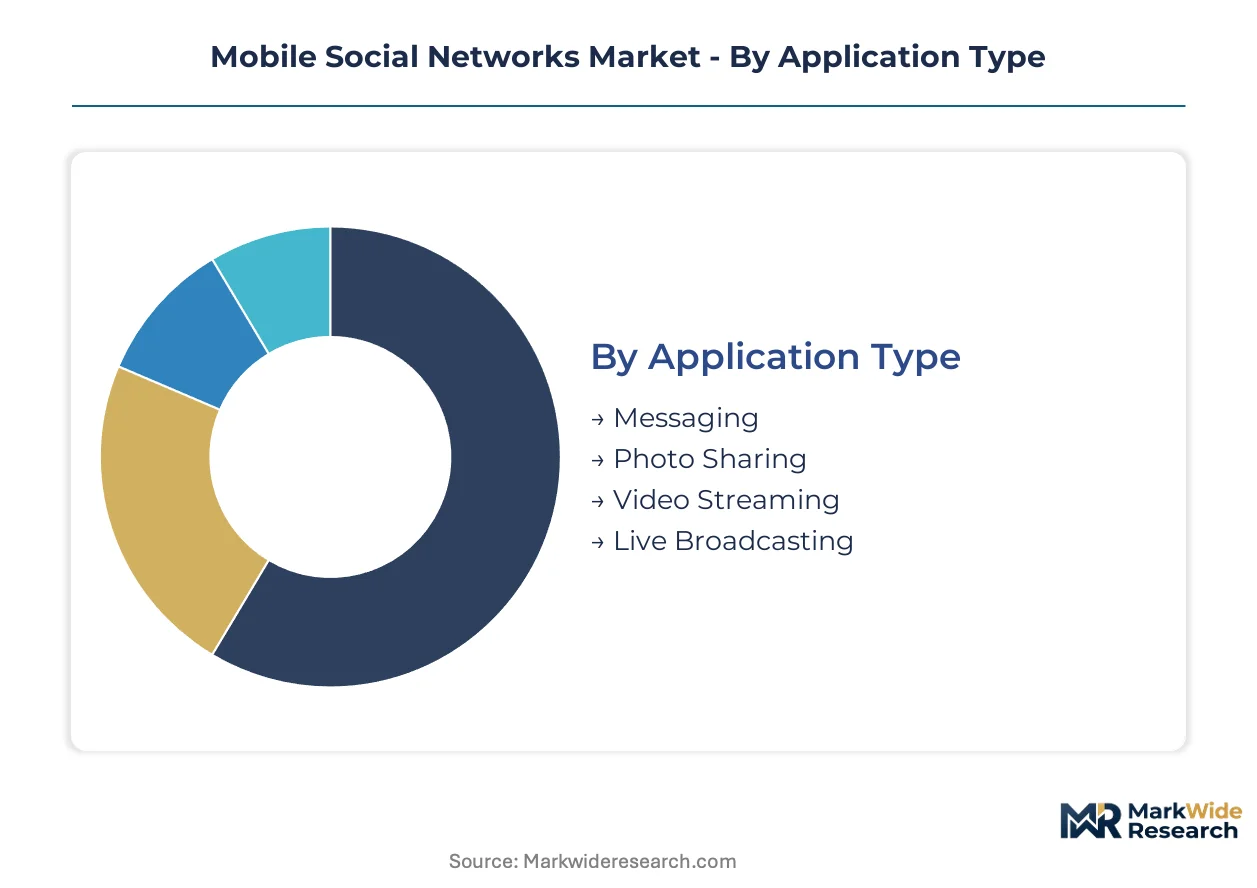
Segmentation in mobile social networks reveals how platform architecture and revenue mechanics diverge across user behaviors and content formats. Distinct monetization models and demographic cohorts command separate infrastructure investments and algorithmic optimization strategies.
Application Type:
User intent intensity drives platform selection, with communication urgency separating messaging from passive entertainment consumption.
- Messaging:End-to-end encrypted protocols dominate user trust architecture. Demand concentrates in India, where WhatsApp serves as the de facto operating system for SME commerce and peer-to-peer payments.
- Photo Sharing:Visual-first interfaces prioritize camera-native workflows and AR filter pipelines. Instagram's Reels integration has shifted engagement toward short-form video, compressing static image monetization rates.
- Video Streaming:On-demand libraries compete for subscription share against platform-agnostic aggregators.
- Live Broadcasting:Real-time interaction mechanics sustain virtual gifting economies and creator tipping infrastructure.
Volume sits with Messaging; growth tilts toward Video Streaming.
User Demographics:
Content consumption velocity varies dramatically across age cohorts, shaping advertising yield and feature development roadmaps.
- Teenagers:Platform migration patterns favor ephemeral content formats and pseudonymous identity systems. TikTok's recommendation engine captures disproportionate screen time through dopamine-optimized scroll mechanics.
- Young Adults:Cross-platform presence requires seamless content syndication tools and unified creator dashboards.
- Professionals:LinkedIn's network effects dominate B2B relationship mapping, though super-app platforms are encroaching with integrated productivity features.
- Seniors:Simplified interfaces and voice-native navigation reduce onboarding friction for first-time smartphone adopters.
Young Adults generate the highest advertising yield; Professionals show the steepest expansion trajectory for subscription monetization.
Monetization Model:
Revenue mix diversification determines platform resilience against advertising cycle volatility and privacy regulation impacts.
- Advertising:Programmatic auction systems and first-party data lakes sustain CPM premiums. Apple's ATT framework has forced reconstruction of attribution models across iOS inventory.
- Subscription:Ad-free tiers and exclusive creator content bundles command recurring revenue commitments.
- In-App Purchases:Virtual currency systems for gifting and cosmetic upgrades drive microtransaction volume in livestreaming environments.
- Sponsorship:Branded content integrations and creator marketplace fees capture marketing budget shifts from traditional media.
Advertising commands current revenue share; In-App Purchases are climbing the fastest as creator economy infrastructure matures.
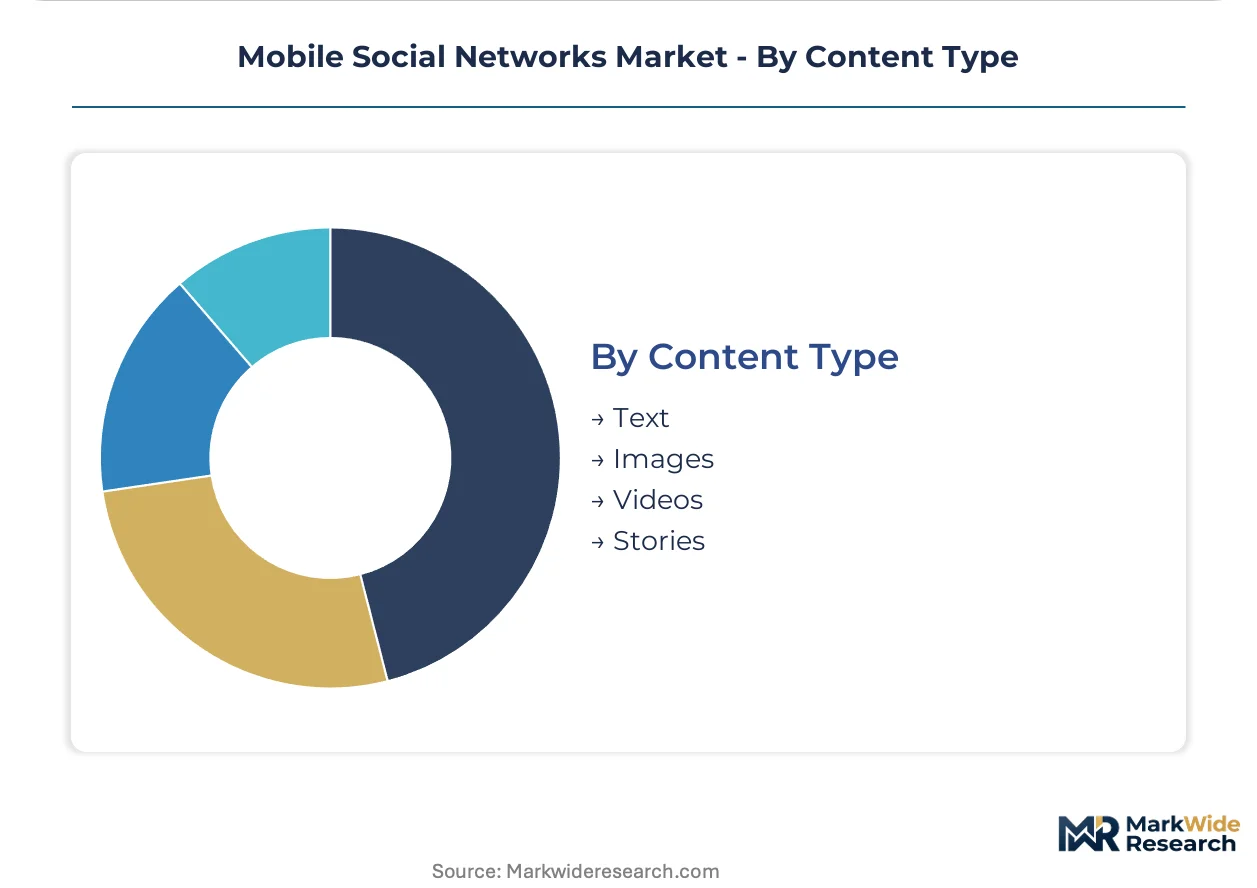
Content Type:
Production cost curves and algorithmic distribution efficiency determine which formats platforms prioritize in feed ranking.
- Text:Lightweight creation tools sustain high-frequency posting behaviors. Twitter's character-limit mechanics and threading systems maintain relevance in real-time discourse despite visual platform dominance.
- Images:Static visual content faces compression from video-first feed algorithms.
- Videos:Short-form vertical formats maximize mobile screen real estate and autoplay engagement metrics.
- Stories:Ephemeral 24-hour content cycles reduce production pressure while sustaining daily active user metrics through FOMO-driven consumption.
Videos dominate consumption minutes; Stories are gaining share fastest as low-friction publishing tools proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the world's most intensive mobile social network usage, where low-cost smartphones and cheap data plans have created one of the largest user bases for short-form video and messaging applications. Platform operators prioritize this market for infrastructure deployment and localized feature development. Regulatory frameworks across major economies are reshaping data governance and content moderation obligations.
United States
Teenage and young adult demographics drive platform engagement velocity, with short-form video consumption dominating screen-time allocation. The FCC oversees broadband infrastructure expansion that underpins mobile application performance, while Section 230 liability frameworks influence platform business model sustainability. Silicon Valley engineering clusters concentrate trust and safety talent development for multilingual content moderation systems.
India
WhatsApp serves as the de facto operating system for SME commerce and peer-to-peer payments, embedding messaging into daily economic transactions. MeitY's IT Rules mandate traceability and grievance redressal mechanisms that alter product architecture for encrypted platforms. Mumbai and Bangalore host platform compliance teams scaling domestic data localization infrastructure.
Germany
Professional networking segments show expansion potential as B2B discovery tools integrate into super-app architectures. The EU Digital Services Act imposes content moderation obligations and algorithmic transparency requirements that compress margins for European operations. Berlin's startup ecosystem incubates privacy-preserving social technologies aligned with GDPR enforcement patterns.
Brazil
Underpenetrated professional networking segments create white space for platforms integrating B2B discovery with existing user bases. ANVISA and national data protection authorities shape consumer-facing application compliance requirements. São Paulo anchors Latin American headquarters for major platforms directing Portuguese-language content moderation and creator economy programs.
Indonesia
Government-subsidized 4G expansion into outer islands activates first-time smartphone users with high content consumption propensity. The Ministry of Communication and Informatics regulates content takedown procedures and platform licensing for domestic operations. Jakarta and Surabaya concentrate influencer marketing agencies negotiating directly through platform-native analytics dashboards.
Mobile Social Networks Market Competitive Landscape
Algorithmic capability investments dominate the current landscape as platforms differentiate through recommendation engine sophistication and real-time personalization infrastructure. The market structure concentrates around a handful of technology conglomerates operating integrated hardware-software ecosystems, with mid-tier specialists occupying niche engagement formats. Two strategic archetypes prevail: algorithm-native short-form video platforms and super-app architects extending messaging into payments and commerce. Competitive intensity manifests through talent acquisition for machine learning engineering and geographic expansion into underpenetrated emerging markets.
Within the super-app architect tier, Meta Platforms and Tencent exemplify divergent regional dominance patterns. ByteDance anchors the algorithm-native category through its short-form video distribution engine. These three entities collectively represent the competitive frontier where hardware-software integration, creator economy infrastructure, and regulatory compliance capabilities determine market position.
| Leading Market Players |
|---|
| Meta Platforms |
| Alphabet Inc. |
| ByteDance |
| Tencent |
| Snap Inc. |
| Telegram |
| Microsoft |
| Discord |
| Others |
Supply & Pricing Matrix
GPU cluster procurement costs cascade through mobile social platform infrastructure tiers, with hyperscale data center investments in the United States, India, and Singapore filtering into advertising auction pricing and creator economy revenue splits downstream. Edge computing node deployment density determines latency-sensitive feature premiums.
Pricing Analysis
Volume sits with advertising inventory traded through programmatic auctions; margins concentrate in creator economy tipping infrastructure. Three-tier pricing structure across premium verified accounts, standard creator tools, and economy ad-supported tiers reflects identity verification investment and API access levels. Pricing pressure stems from Apple's ATT framework fragmentation forcing reconstruction of attribution-dependent CPM models. SME advertisers in India exhibit highest price sensitivity; enterprise brand buyers in the United States tolerate premium rates for first-party data enrichment.
Supply Chain Analysis
Direct-to-platform API channels handle hyperscale developer demand for content moderation and recommendation engine services. Hardware-software integration draws from Taiwan semiconductor foundries, South Korea memory fabrication, and United States GPU design houses. Cloud infrastructure rests on redundant fiber optic submarine cables and terrestrial 5G backhaul networks. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through hyperscaler co-location facilities and regional edge POPs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile social networks occupy a transition phase where generative AI inference engines displace legacy content production workflows. Algorithmic recommendation systems are replacing deterministic feed chronology.
For Market Incumbents: Extend creator economy infrastructure into embedded finance and social commerce to capture transaction margin beyond advertising. Deepen compliance architecture investments for EU Digital Services Act and India's IT Rules to defend market access against regulatory exclusion. Threat substitution from open-source federated protocols demands proprietary data moat reinforcement through exclusive creator contracts. For New Entrants and Emerging Players: Indonesia's government-subsidized 4G expansion into outer islands opens a window for super-app platforms targeting first-time smartphone users with simplified interfaces and voice-native navigation. Brazil's underpenetrated professional networking segment offers white space for B2B discovery tool integration. Go-to-market through direct platform-native analytics dashboards reduces agency commission overhead and accelerates campaign deployment cycles. For Investors and Strategic Acquirers: ByteDance's algorithmic content distribution patent filings are the leading indicator that short-form video engagement mechanics will commoditize across platforms. Long-term viability centers on hardware-software integration capabilities and regulatory compliance infrastructure rather than pure algorithmic sophistication. Acquisition targets should display multilingual trust and safety engineering teams and domestic data localization architecture. Watch for interoperability mandate implementations as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Super-app architectures embedding payments and mini-programs capture transaction margin beyond advertising inventory. |
| Geographic Expansion | India's IT Rules compliance investments strengthen platform legitimacy in the world's largest emerging market user base. |
| Acquisition of Specialist Firm | Trust and safety engineering talent scarcity makes multilingual content moderation teams strategic assets. |
| Product Launch | Generative AI inference engines in mobile applications compress content production timelines from days to minutes. |
| Strategic Partnership | Creator marketplace direct relationships with consumer packaged goods companies displace independent talent agencies. |
Research Methodology
Multi-period observation of user engagement velocity, advertising yield compression, and regulatory implementation timelines anchored the trend analysis, supplemented by interviews with platform engineering directors, trust and safety leads, creator economy program managers, and digital marketing procurement officers. Secondary validation drew from SEC filings, App Annie/Sensor Tower engagement metrics, hyperscaler capex disclosures, and EU regulatory implementation notices. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure deployment records.
Input-output matrix framing connected GPU cluster procurement volumes to advertising inventory pricing elasticity and creator economy revenue share evolution across the projection horizon. Segmentation dimensions modeled include application type, user demographic cohort, monetization model, and content format, with regional regulatory framework as an additional industry-specific dimension. CAGRs derived from fitted growth curves applied to user base expansion and ARPU evolution trajectories. Industry-specific forecast inputs incorporated 5G penetration curves and data localization infrastructure buildout schedules.
The model assumes a particular technology adoption path; alternative pathways for generative AI content production tools would alter the outlook for creator economy tipping infrastructure growth. Forecasts reflect assumptions regarding regulatory enforcement intensity and interoperability mandate implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fabric Based Computing Market
Others
Space Cables Market
Others
Latin America Video Conferencing Hardware Market
Others
Managed Video As a Service Market
Others
Cloud-Based Streaming Services Market
Others
Advanced Combat Helmet Market
Others
Small Office Home Office (SOHO) Servers Market
Others
Global Webinar and Webcast Market
Others
Blockchain in BFSI Market
Others
Wood Stoves Market
Others
Receiving Scales Market
Others
Global Extruded Plastics Market
Others
North America Forklift Truck Market
Others
Content Experience Platforms Market
Others
US Legal Services Market
Others
Global Flexible PVC Films Market