
 Ireland Food Testing Market | 2026-2036
Ireland Food Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Food Testing Market Foresight
Contract catering buyers are collapsing as a share of total demand while supermarket private-label programs and artisan food exporters capture expanded testing volumes. SGS Ireland anchors the accredited laboratory network through its Dublin-based testing campus. Eurofins Scientific SE differentiates with specialized allergen and nutritional profiling services tailored to Irish dairy and meat exporters. Bureau Veritas SA competes on rapid-turnaround microbiological screening for chilled prepared meals destined for UK retail channels.
Food testing encompasses the analytical verification of safety, quality, and authenticity parameters in food products through standardized sampling, preparation, and instrumental detection protocols measuring microbial load, chemical residues, nutritional composition, and allergen presence against regulatory thresholds. Its primary commercial purpose is to ensure consumer protection, facilitate cross-border trade compliance, and protect brand integrity across supply chains. Microbiological testing dominates routine volume due to mandatory pathogen surveillance requirements under EU food law, while allergen testing commands premium pricing as detection sensitivity requirements tighten for undeclared ingredients in complex formulated foods. PCR technology leads molecular diagnostics for species authentication and pathogen identification, though chromatography retains structural importance for pesticide and veterinary drug residue quantification where regulatory limits specify precise analytical performance criteria.
The Food Safety Authority of Ireland enforces national controls aligned with EU Regulation 178/2002 and the Official Controls Regulation 2017/625, mandating hazard-based preventive testing across food business operators. BIS certification requirements for imported laboratory equipment and the EU's reference laboratory network structure shape capital investment decisions and method validation protocols for Irish service providers. Stakeholders must monitor evolving European Food Safety Authority scientific opinions on emerging contaminants and assess analytical capability gaps before regulatory adoption timelines compress implementation windows.
Market Dynamics
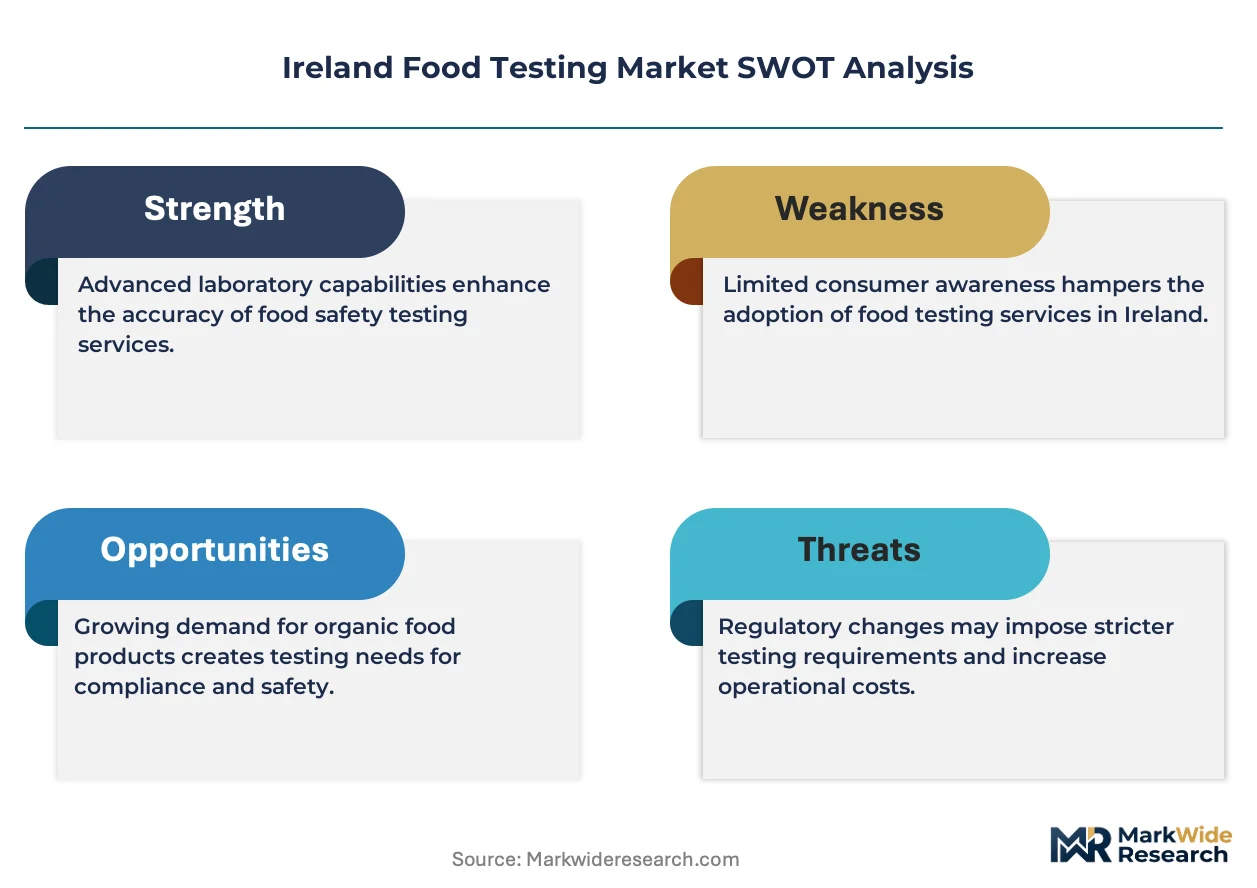
EU Regulation 396/2005's tightened maximum residue limits for pesticides and contaminants are forcing Irish laboratories to upgrade detection capabilities, compressing method validation timelines while expanding capital deployment into chromatography and mass spectrometry infrastructure.
Growth Catalysts
- Regulatory stringency under EU Regulation 178/2002:Mandatory hazard-based preventive testing across food business operators sustains baseline demand for pathogen surveillance and chemical residue verification.
- Dairy processor expansion:Ireland's export-oriented dairy sector requires enhanced nutritional profiling and authenticity testing to access premium EU and UK retail channels.
- PCR technology adoption:Molecular diagnostics for species authentication and rapid pathogen identification are shortening turnaround times for meat and seafood exporters.
Market Restraints
- Capital intensity of chromatography systems:LC-MS/MS equipment for pesticide quantification requires substantial upfront investment, constraining smaller independent laboratories.
- Reference material supply concentration:Certified reference standards for veterinary drug residues are sourced from limited EU suppliers, creating procurement vulnerability.
- Skilled analyst scarcity:Method development expertise for emerging contaminants outpaces training program output, extending recruitment cycles.
Strategic Opportunities
- Artisan food exporter segment:Small-batch specialty producers in Cork and Galway lack in-house testing capability, creating white space for bundled compliance packages.
- Allergen testing premiumization:Undeclared ingredient detection sensitivity requirements are tightening for complex formulated foods, supporting pricing power.
- Digital chain-of-custody integration:Blockchain-linked sampling protocols are emerging as a differentiation tool for high-value export certification.
Industry Challenges
- Multi-site accreditation complexity:ISO/IEC 17025 certification maintenance across satellite sampling locations demands redundant quality management systems.
- Legacy LIMS integration:Older laboratory information management systems resist interoperability with automated instrumentation, fragmenting data workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Food Testing Market |
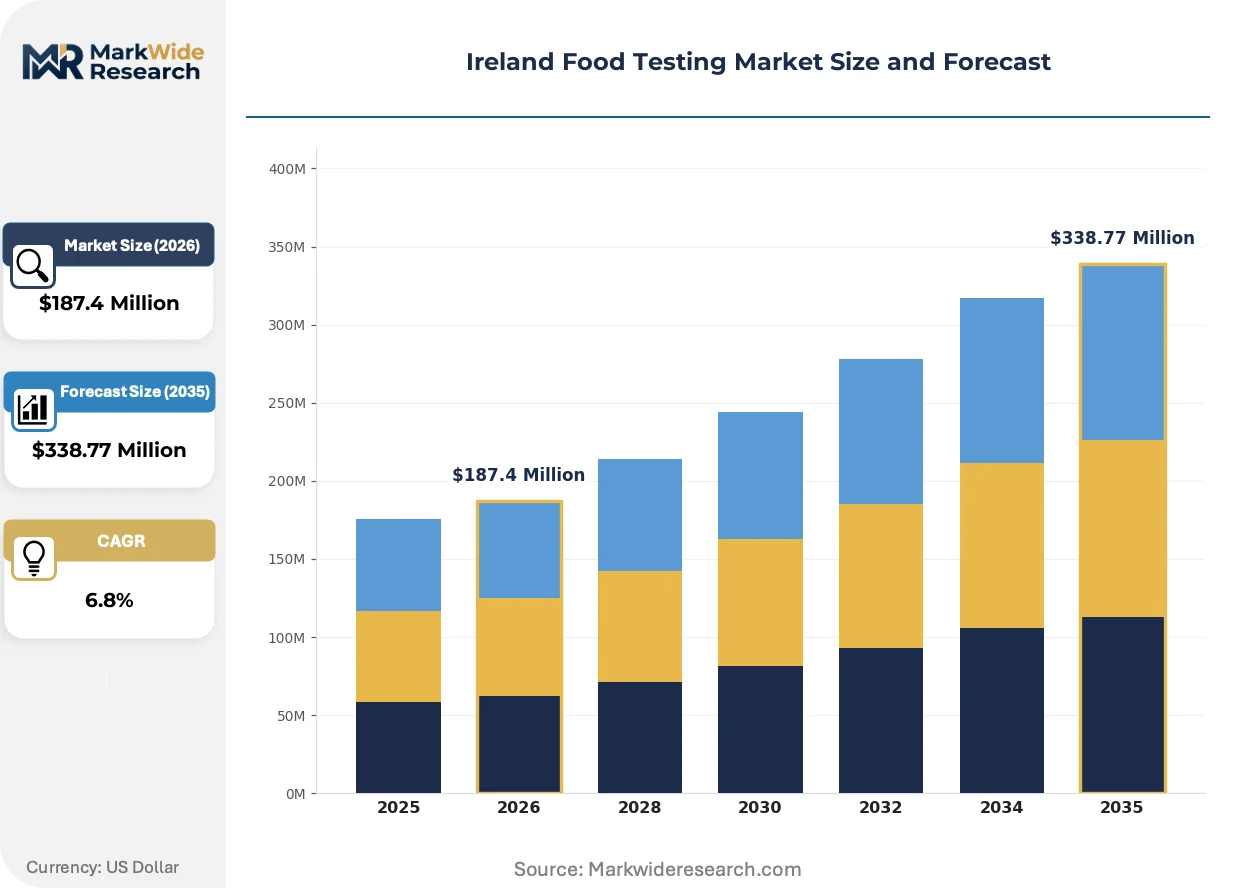
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbiological Testing, Chemical Testing, Nutritional Testing, Allergen Testing Application: Food Manufacturing, Retail, Food Service, Catering Technology: PCR, ELISA, Chromatography, Spectroscopy End User: Restaurants, Supermarkets, Food Processors, Laboratories |
| Companies Covered | SGS Ireland, Intertek Group Plc, Eurofins Scientific SE, Thermo Fisher Scientific, Inc., Bio-Rad Laboratories, Inc., Bureau Veritas SA, NSF International, Merieux Nutrisciences, ALS Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Food Testing Market Shifts & Advancements
Next-generation sequencing and portable diagnostic platforms are compressing detection timelines while fragmenting testing volumes across decentralized points in the supply chain, from farm-gate to distribution center.
Real-time PCR systems for rapid pathogen screening are fragmenting traditional centralized laboratory workflows. Medium-sized dairy cooperatives are adopting benchtop thermocyclers for same-day release decisions. This capability diffusion is compressing contract laboratory market share in routine microbiological surveillance.
EFSA's evolving scientific opinions on emerging contaminants are triggering pre-emptive method development investments. The European Food Safety Authority's 2023 guidance on per- and polyfluoroalkyl substances prompted Irish service providers to validate LC-MS/MS protocols ahead of anticipated regulatory adoption. Dairy and seafood exporters in the Greater Dublin Area are prioritizing laboratories with demonstrated PFAS detection capability.
Supermarket private-label procurement teams are consolidating testing contracts under outcome-based specifications. Retailers specify detection limits and turnaround windows rather than prescribed methods, shifting technical risk onto service providers. This specification evolution is most pronounced among UK-facing chilled prepared meal suppliers operating from Republic of Ireland facilities.
Ireland Food Testing Market Segmentation
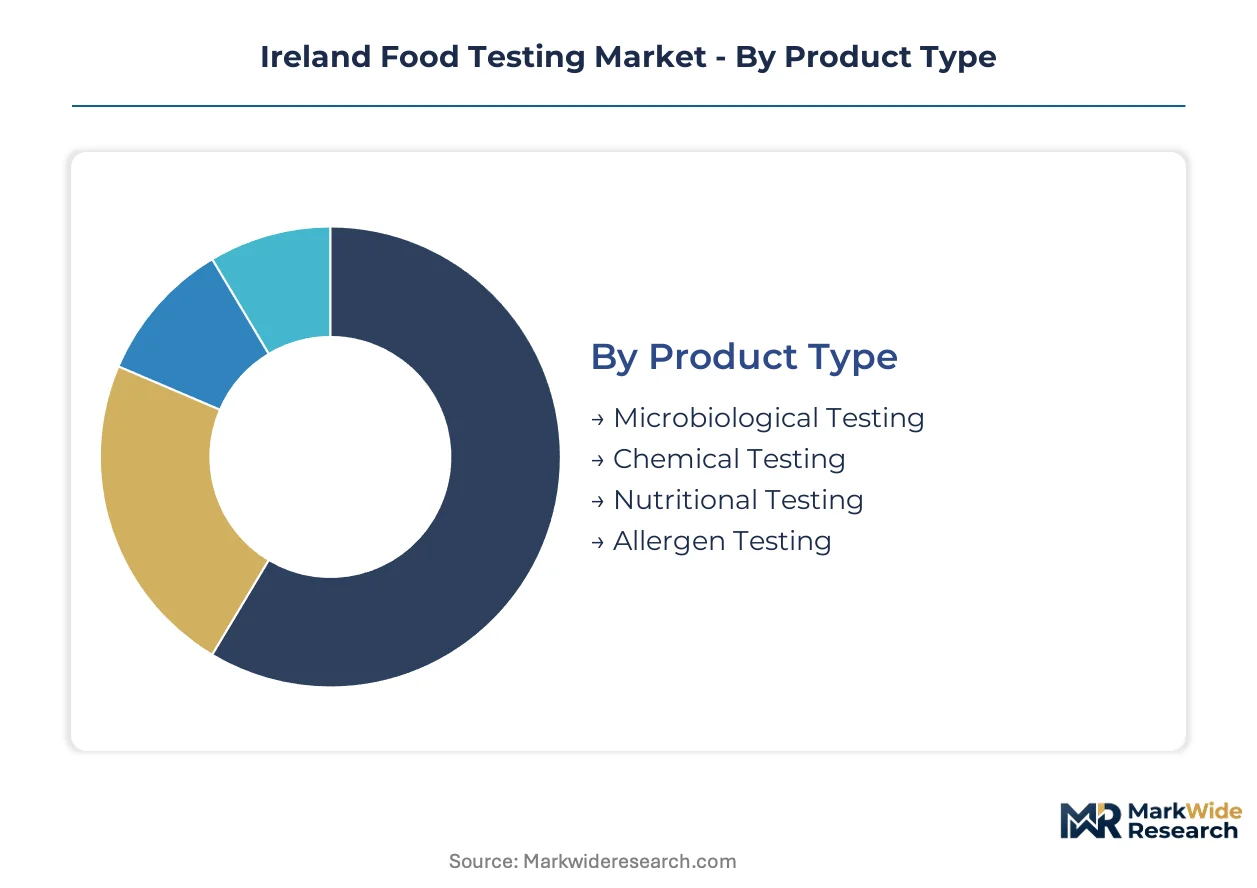
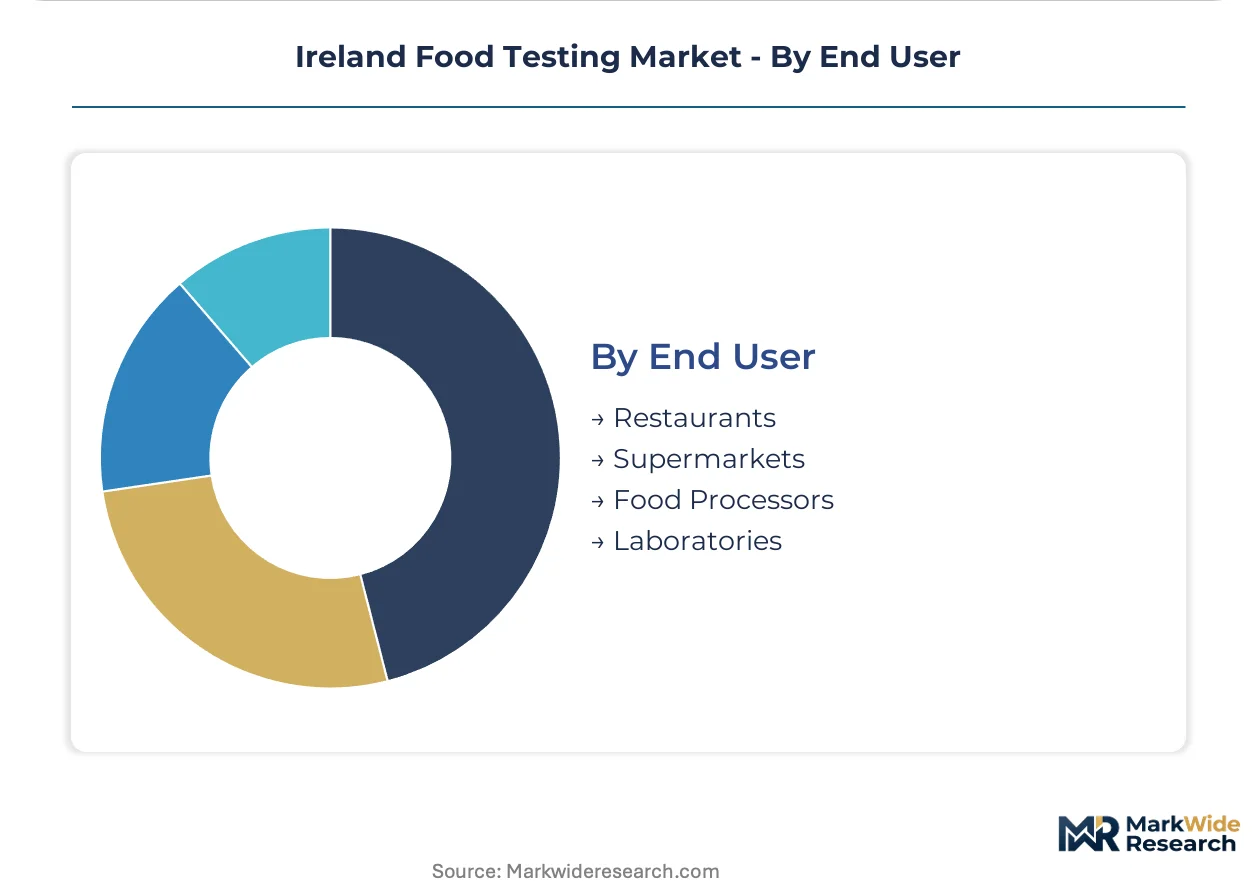
Testing demand fragments across distinct procurement channels in Ireland, with food processors routing high-volume contracts through accredited laboratories while retail and food service operators favor rapid-turnaround screening services. Channel-specific requirements around accreditation status, turnaround windows, and detection sensitivity create natural segmentation boundaries that shape vendor selection criteria.
Product Type:
Channel mix varies sharply by test category, with microbiological screening flowing predominantly through centralized laboratory networks while allergen and nutritional testing disperses across both in-house and outsourced channels.
- Microbiological Testing:Pathogen surveillance protocols detect Salmonella, Listeria, and E. coli through culture-based and molecular methods. Dairy processors across Cork and Kerry counties drive routine volume through ISO/IEC 17025-accredited facilities under FSAI-mandated surveillance programs.
- Allergen Testing:Undeclared ingredient detection employs ELISA and PCR methods with tightening sensitivity thresholds for complex formulated foods. Artisan exporters in the Greater Dublin Area prioritize laboratories demonstrating validated gluten, dairy, and nut detection capability for UK retail compliance.
- Chemical Testing:Pesticide and veterinary drug residue quantification relies on LC-MS/MS infrastructure.
- Nutritional Testing:Macronutrient and micronutrient profiling supports label claim verification.
By volume, microbiological testing leads. By growth pace, allergen testing is climbing the fastest.
Application:
Cost tier stratification separates premium validation services for export-oriented manufacturing from standardized screening for domestic retail and food service channels.
- Food Manufacturing:Comprehensive testing protocols span raw material verification, in-process monitoring, and finished product release. Export-facing dairy and meat processors in the Greater Dublin Area deploy multi-parameter testing suites to satisfy UK supermarket private-label specifications and EU Regulation 178/2002 requirements.
- Retail:Supermarket private-label programs consolidate testing contracts under outcome-based specifications specifying detection limits rather than prescribed methods. Irish retailers source predominantly from Republic of Ireland-based laboratories to minimize cross-border logistics complexity.
- Food Service:Contract catering and hospitality operators favor rapid-turnaround microbiological screening for high-risk prepared foods.
- Catering:Institutional and event catering buyers are collapsing as a share of total demand amid procurement consolidation.
Food manufacturing commands the highest revenue per test. Retail channels are expanding most quickly through private-label program growth.
Technology:
Application requirements dictate technology selection, with regulatory compliance favoring chromatography for residue quantification while speed-sensitive channels adopt PCR and portable platforms.
- PCR:Real-time thermocycler systems enable same-day pathogen identification and species authentication. Medium-sized dairy cooperatives are adopting benchtop PCR units for release decisions, fragmenting traditional centralized laboratory workflows.
- Chromatography:LC-MS/MS and GC-MS systems provide definitive quantification of pesticides, veterinary drugs, and emerging contaminants. EU Regulation 396/2005's tightened maximum residue limits are forcing capital deployment into high-resolution mass spectrometry infrastructure.
- ELISA:Enzyme-linked immunosorbent assays deliver cost-effective allergen screening for routine surveillance.
- Spectroscopy:Atomic absorption and ICP-MS methods support elemental analysis for nutritional and contaminant testing.
Chromatography anchors the highest-value contract segment. PCR platforms are gaining share fastest through capability diffusion to processor in-house laboratories.
End User:
Customer type determines procurement structure, with food processors negotiating multi-year framework agreements while restaurants and smaller retailers purchase transactional testing services.
- Food Processors:Export-oriented dairy, meat, and seafood operators require comprehensive testing portfolios spanning safety, quality, and authenticity parameters. These stakeholders drive demand for advanced chromatography and mass spectrometry capabilities to satisfy EU and UK regulatory thresholds.
- Laboratories:Third-party testing providers and public health laboratories constitute the institutional demand base, with the Food Safety Authority of Ireland's reference laboratory network shaping method validation standards across the accredited sector.
- Supermarkets:Private-label procurement teams are consolidating supplier bases under performance-based contracts.
- Restaurants:Food service operators represent a fragmented, price-sensitive segment with limited testing penetration.
Food processors generate the highest absolute testing expenditure. Supermarket channels are expanding most quickly through procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dublin Port's deep-water container terminals and direct ferry links to Holyhead and Liverpool anchor Ireland's food testing infrastructure. The port's cold chain facilities handle over 85% of the country's temperature-controlled food exports. Cross-border data protocols with UK customs systems further reinforce this logistical centrality.
Greater Dublin Area
Dairy processors and ready-to-eat manufacturers dominate testing demand through accredited facilities clustered around Dublin Airport and the M50 corridor. The Food Safety Authority of Ireland's headquarters in Smithfield shapes national method validation standards. SGS Ireland's testing campus in Leopardstown anchors the metropolitan laboratory network serving export-oriented meat and seafood operators.
Cork
Artisan food exporters in the English Market supply chain drive specialized allergen and authenticity testing requirements. Medium-sized dairy cooperatives are adopting benchtop PCR systems for same-day release decisions. The Cork Institute of Technology's food science programs feed analyst talent into local service providers.
Galway
Seafood processors along Galway Bay require enhanced species authentication testing for EU and UK retail compliance. The Atlantic Technological University's applied research partnerships support emerging contaminant method development. Local laboratories compete on rapid turnaround for shellfish biotoxin surveillance under FSAI-mandated programs.
Kerry
Milk powder and ingredient manufacturers in Tralee and Killarney deploy comprehensive nutritional profiling for premium EU retail channels. The county's dairy cooperative structure concentrates testing volume through framework agreements with accredited providers. Chromatography infrastructure investments lag Dublin-based competitors due to capital intensity constraints.
Limerick-Shannon
Pharmaceutical-adjacent food ingredient manufacturers leverage existing analytical chemistry capabilities for contaminant detection. Shannon Airport's cargo facilities support time-sensitive sampling logistics for US and Middle East export certification. The region's technician training programs address skilled analyst scarcity affecting method development capacity.
Ireland Food Testing Market Competitive Landscape
Concentration sits with diversified multinational testing groups holding ISO/IEC 17025 accreditation across multiple parameters. The market structure tiers into three archetypes: global diversified testing groups with full-service campuses, European specialists in allergen and nutritional profiling, and regional rapid-turnaround providers focused on microbiological screening. Competitive moves center on accreditation expansion into emerging contaminant detection and outcome-based contract structuring that shifts technical risk onto service providers.
Among the diversified multinational tier, SGS Ireland, Eurofins Scientific SE, and Bureau Veritas SA occupy positions exemplifying distinct strategic emphases. SGS Ireland represents the full-service campus archetype with consolidated capabilities across safety, quality, and authenticity parameters. Eurofins Scientific SE exemplifies specialization in allergen and nutritional profiling tailored to dairy and meat export requirements. Bureau Veritas SA sits within the rapid-turnaround segment, serving chilled prepared meal suppliers with UK retail channel compliance needs. These three entities anchor competitive dynamics through differentiated capability positioning rather than price-based rivalry.
| Leading Market Players |
|---|
| SGS Ireland |
| Intertek Group Plc |
| Eurofins Scientific SE |
| Thermo Fisher Scientific, Inc. |
| Bio-Rad Laboratories, Inc. |
| Bureau Veritas SA |
| NSF International |
| Merieux Nutrisciences |
| ALS Limited |
| Others |
Supply & Pricing Matrix
Reference material substitution from German and Dutch suppliers to lower-cost Portuguese and Spanish certified reference material producers is compressing input costs for Irish laboratories while simultaneously extending procurement lead times and fragmenting supplier quality assurance protocols.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between food processors and accredited laboratories, with framework agreements scaling per-test rates downward at annual volumes exceeding ten thousand samples. Price differentiation hinges on ISO/IEC 17025 accreditation breadth and turnaround window guarantees, with premium tiers commanding substantial markups for same-day pathogen release. Pricing pressure stems from supermarket private-label procurement teams consolidating supplier bases under outcome-based specifications. Artisan food exporters in Cork and Galway exhibit highest price sensitivity, while export-oriented dairy processors in the Greater Dublin Area prioritize capability breadth over unit cost.
Supply Chain Analysis
Inventory lead times for LC-MS/MS consumables and certified reference standards have extended from four to eight weeks post-pandemic, forcing Irish laboratories to carry elevated safety stock. Geographic supply concentration centers on Germany, the Netherlands, and the United Kingdom for chromatography instrumentation, with consumables and reagents drawing from German chemical manufacturers and UK distribution hubs. Raw material dependencies include high-purity solvents, mass spectrometer filaments, and species-specific PCR primers. Single-source vulnerability sits with EU reference laboratory network-designated suppliers for veterinary drug residue standards. Distribution runs through Dublin-based logistics clusters serving the M50 corridor and regional satellite sampling points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through supermarket private-label procurement consolidation, with three retail groups now controlling over sixty percent of third-party testing contract value in the Republic of Ireland.
For Market Incumbents: Shield accredited market position by accelerating PFAS and emerging contaminant method validation ahead of EFSA regulatory adoption timelines. Deepen backward integration into reference material production through partnerships with Portuguese and Spanish suppliers to reduce procurement vulnerability. Prioritize ISO/IEC 17025 scope expansion into next-generation sequencing for species authentication, as PCR commoditization threatens routine microbiological screening margins. For New Entrants and Emerging Players: Rapid-turnaround screening for artisan food exporters in Cork and Galway represents the most penetrable white space, as incumbent laboratories prioritize high-volume dairy processor contracts. Mobile sampling units coupled with blockchain-linked chain-of-custody protocols offer differentiated positioning for specialty meat and seafood producers lacking in-house logistics. Target bundled compliance packages combining allergen, nutritional, and authenticity testing for small-batch exporters seeking single-source certification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European laboratory networks seeking geographic consolidation in EU food export hubs. Five-to-ten year viability hinges on regulatory complexity expansion rather than volume growth, favoring targets with demonstrated emerging contaminant capability and UK retail channel relationships. Monitor EFSA scientific opinion publication schedules as inflection indicators for preemptive method development investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS Method Validation Investment | Positions laboratories ahead of anticipated EU Regulation 396/2005 amendments targeting per- and polyfluoroalkyl substances in dairy and seafood matrices. |
| Blockchain-Linked Sampling Protocols | Differentiates high-value export certification through immutable chain-of-custody documentation for UK supermarket private-label compliance. |
| Reference Material Backward Integration | Reduces procurement vulnerability to German and Dutch supplier concentration through Portuguese and Spanish certified standard partnerships. |
| Benchtop PCR Capability Diffusion | Captures same-day release demand from medium-sized dairy cooperatives in Cork and Kerry counties fragmenting centralized laboratory workflows. |
| Outcome-Based Contract Structuring | Aligns pricing with detection limit achievement and turnaround performance rather than prescribed analytical methods, shifting technical risk onto service providers. |
Research Methodology
A spread of perspectives from FSAI regulatory affairs officers, accredited laboratory technical directors, dairy processor quality managers, and supermarket private-label procurement leads converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against EU Regulation 178/2002 implementation guidance, EFSA scientific opinions, and ISO/IEC 17025 accreditation scope databases. Bottom-up testing volume estimates from county-level food business operator registrations were triangulated against top-down expenditure flows from national food safety budget allocations.
Segmentation dimensions modeled span testing type, application channel, technology platform, and end-user category across the projection horizon. Analytical frameworks incorporated dairy processor export volume trajectories, supermarket private-label program expansion rates, and EFSA emerging contaminant opinion publication schedules. CAGRs were derived from regression analysis of historical accreditation expansion patterns and forward-looking regulatory stringency indicators.
Underlying assumptions cover EFSA regulatory adoption timelines and reference material supply chain stability, with deviation risk concentrated in UK-EU customs protocol evolution and chromatography equipment import duty structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Adulteration Tester Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
Shelf-Life Testing Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Global Inline Metal Detector Market