
 Water Quality Testing Market | 2026-2036
Water Quality Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Water Quality Testing Market Analysis
Remote monitoring subscriptions is realigning how vendors monetize water quality testing, shifting capital expenditure into recurring revenue streams. Thermo Fisher Scientific Inc. leverages its chromatography software ecosystem to lock in laboratory clients. SGS SA anchors its competitiveness through geographic density in European environmental compliance networks. Eurofins Scientific SE differentiates by specializing in emerging contaminant panels for pharmaceutical runoff detection.
Water quality testing encompasses the analytical determination of chemical, biological, and physical parameters in water matrices using methods with detection thresholds ranging from parts-per-million to parts-per-trillion for trace contaminants. The practice serves industrial discharge compliance, public health protection, and ecosystem management through standardized protocols such as EPA Method 8260 for volatile organics. Test kits and sensors capture the bulk of near-term volume as utilities prioritize field-deployable screening over laboratory send-outs. Electrochemical technology leads in installed base for pH and dissolved oxygen measurement, while spectroscopic methods gain share in multi-parameter contaminant identification. Drinking water applications command premium pricing due to regulatory enforcement density, whereas environmental monitoring segments compete on throughput scale.
The EPA enforces Safe Drinking Water Act amendments that mandate expanded testing for per- and polyfluoroalkyl substances, directly expanding analyzer demand from municipal laboratories. The EU Drinking Water Directive, enforced by member state environmental agencies, harmonizes quality standards that cross-border testing providers must meet for market access. ISO 17025 accreditation requirements shape competitive barriers by certifying laboratory competence for specific analyte classes. Stakeholders must weigh capital intensity against subscription flexibility when configuring service portfolios for tightening contaminant schedules.
Market Dynamics
The transition from laboratory-based analysis to field-deployable sensor networks is compressing testing cycles and reconfiguring vendor revenue models toward recurring service contracts.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Municipal drinking water systems face accelerated compliance timelines, forcing procurement of real-time lead detection analyzers and automated sampling infrastructure.
- EU Drinking Water Directive harmonization:Cross-border utilities in Germany and neighboring states must upgrade testing protocols for emerging contaminants, expanding demand for multi-parameter sensor platforms.
- Per- and polyfluoroalkyl substances mandates:The EPA's Safe Drinking Water Act amendments require expanded PFAS monitoring, directly increasing analyzer deployments at municipal laboratories nationwide.
Market Restraints
- Precious metal input volatility:Electrochemical sensors rely on platinum and iridium electrodes, exposing manufacturers to price swings in rare earth supply chains concentrated in South African and Russian extraction.
- ISO 17025 certification barriers:Laboratory accreditation requirements for specific analyte classes create multi-year approval timelines that lock out smaller testing providers from regulated municipal contracts.
- Optical spectroscopy cost premiums:Multi-parameter contaminant identification systems carry capital expenditure thresholds that exclude smaller utilities from upgrading beyond electrochemical pH and dissolved oxygen measurement.
Strategic Opportunities
- Pharmaceutical runoff detection panels:Specialized testing protocols for active pharmaceutical ingredients in wastewater streams remain underdeveloped, creating white space for differentiated service offerings.
- Remote monitoring subscription models:Sensor-as-a-service platforms convert capital expenditure into recurring revenue, improving vendor cash flow predictability while lowering utility entry barriers.
- Chromatography software ecosystems:Integrated data platforms that lock laboratory clients into vendor-specific analytical workflows create defensive moats against equipment commoditization.
Industry Challenges
- Analytical chemist talent scarcity:Specialized expertise in parts-per-trillion detection methodologies remains concentrated in aging workforce cohorts, constraining laboratory expansion timelines.
- Legacy SCADA integration friction:New sensor networks must interface with decades-old municipal control systems, requiring costly middleware development and extended deployment cycles.
- Emerging contaminant schedule volatility:Regulatory bodies add new analytes faster than validation protocols can standardize, forcing laboratories to maintain redundant testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Quality Testing Market |
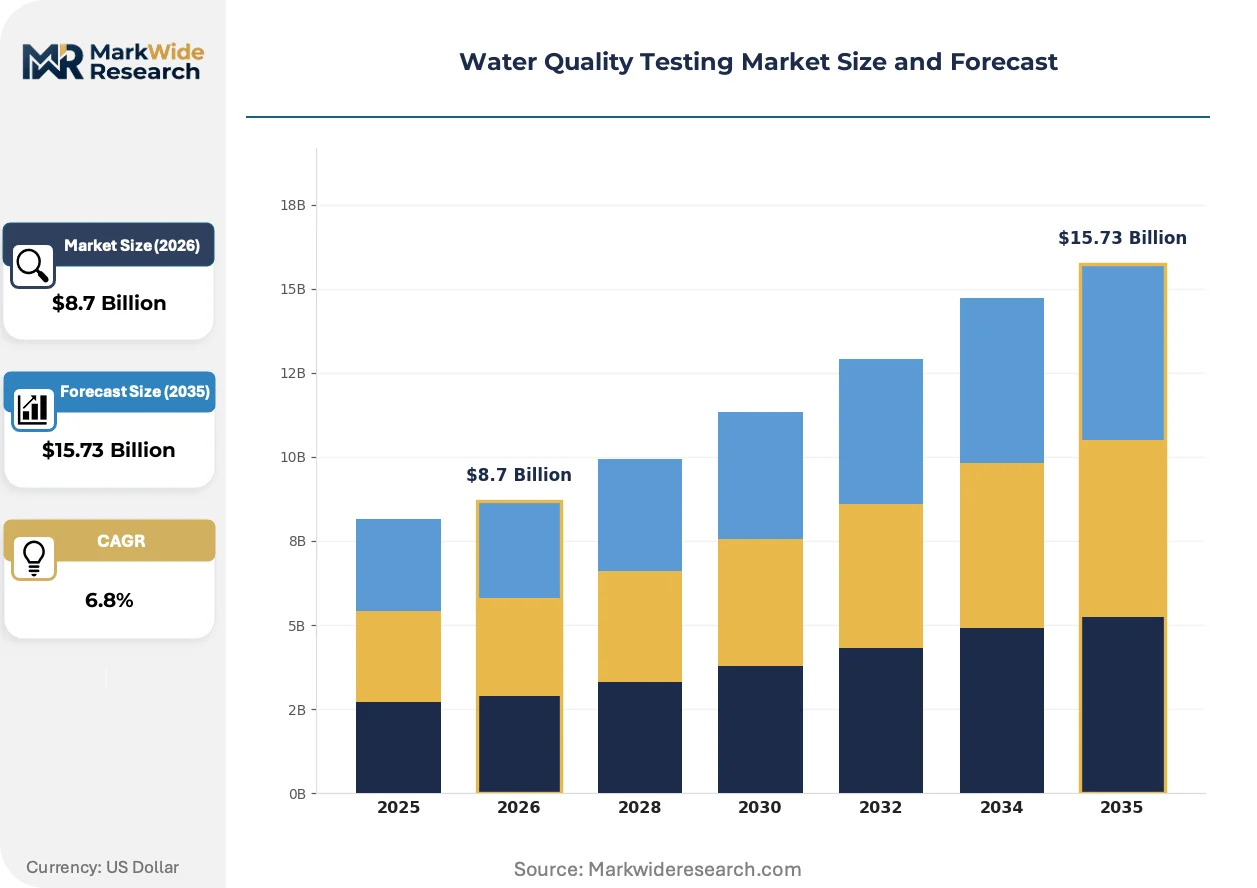
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Sensors, Sampling Equipment, Analyzers Technology: Electrochemical, Spectroscopic, chromatographic, Optical Application: Industrial, Environmental Monitoring, Aquaculture, Drinking Water End User: Laboratories, Municipalities, Industries, Research Institutions |
| Companies Covered | Eurofins Scientific SE, SGS SA, Thermo Fisher Scientific Inc., Intertek Group plc, Bureau Veritas SA, Xylem Inc., ALS Limited, Hach Company, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Quality Testing Market Emerging Trajectories
Water quality testing is pivoting from reactive laboratory analysis toward predictive, network-connected monitoring systems that embed compliance into continuous operational workflows.
Spectroscopic multi-parameter analyzers are expanding into municipal distribution networks as utilities abandon single-point sampling. These platforms simultaneously detect volatile organics, heavy metals, and disinfection byproducts at parts-per-billion thresholds. German utilities under EU Drinking Water Directive pressure now deploy these systems at treatment plant outflows and critical network nodes, compressing incident response from days to minutes.
REACH chemical registration requirements in Europe are tightening disclosure obligations for industrial discharge permits. Manufacturers must now quantify trace contaminant loads in effluent streams with greater precision, driving demand for automated sampling and flow-proportional compositing systems. Chemical processors in the Rhine basin are responding by consolidating testing contracts with accredited laboratories capable of multi-matrix analysis.
Subscription-based sensor maintenance contracts are displacing traditional equipment ownership models among budget-constrained municipalities. Under this arrangement, vendors retain asset ownership and guarantee uptime, while utilities convert capital reserves into operational expenditures. This pattern concentrates in the United States, where EPA enforcement timelines pressure smaller systems to deploy monitoring technology without upfront infrastructure investment.
Water Quality Testing Market Segmentation
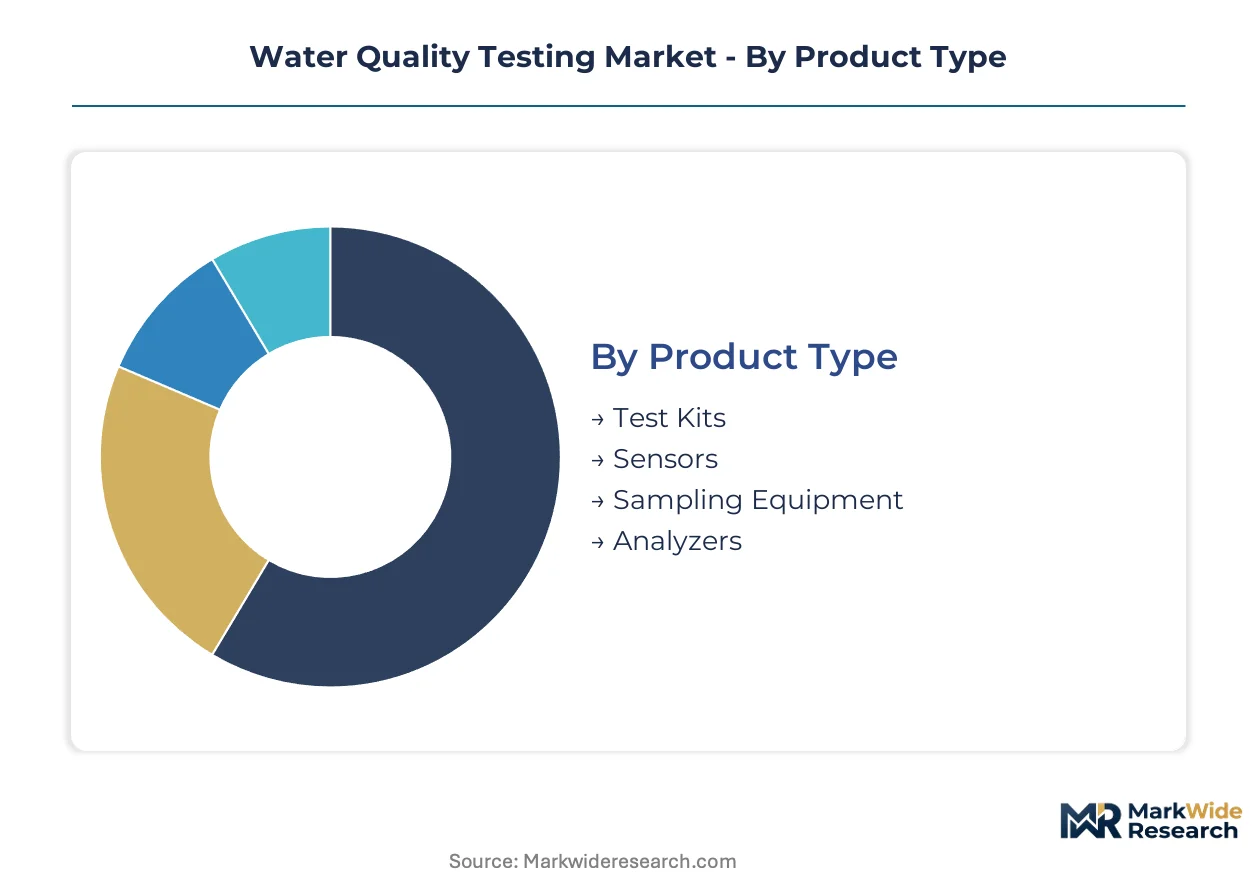
Water quality testing vendors configure product portfolios around distinct procurement rhythms. Municipal utilities favor capital-intensive analyzer installations with decade-long replacement cycles, while industrial operators prioritize disposable test kits for spot-check compliance.
Product Type:
Replacement cycles vary sharply across hardware categories, forcing vendors to balance annuity revenue against upfront equipment sales.
- Test Kits:Single-use colorimetric and titration assays deliver immediate field results without calibration infrastructure. German municipalities under EU Drinking Water Directive pressure deploy these for rapid chlorine residual and pH screening at distribution network nodes.
- Sensors:Electrochemical probes for dissolved oxygen, conductivity, and turbidity integrate into SCADA networks for continuous telemetry. US municipalities facing EPA Lead and Copper Rule deadlines are prioritizing these for real-time distribution system monitoring over laboratory send-outs.
- Sampling Equipment:Automated composite samplers with flow-proportional triggering capture representative effluent loads for regulatory reporting.
- Analyzers:Benchtop and portable systems for multi-parameter contaminant identification require substantial capital outlay and certified operator training.
Volume placements concentrate in Test Kits; the faster expansion belongs to Sensors.
Technology:
Cost tiers separate mature electrochemical platforms from emerging spectroscopic systems with superior multi-analyte capability.
- Electrochemical:Proven potentiometric and amperometric methods dominate pH, dissolved oxygen, and heavy metal detection with minimal maintenance requirements. Rhine basin chemical processors rely on these for discharge compliance given their tolerance for harsh industrial effluent matrices.
- Spectroscopic:UV-Vis and atomic absorption systems achieve parts-per-billion detection thresholds for volatile organics and trace metals. German utilities accelerating testing mandates under the EU Drinking Water Directive are displacing single-parameter electrochemical units with these multi-analyte platforms.
- Chromatographic:Gas and liquid chromatography with mass spectrometry detection delivers definitive identification of complex organic contaminant mixtures.
- Optical:Turbidimetry and fluorometry methods serve specialized applications including bacterial enumeration and algal biomass quantification.
Commercial penetration is deepest for Electrochemical; the steepest expansion trajectory is Spectroscopic.
Application:
Regulatory enforcement density varies dramatically across use cases, with drinking water commanding premium pricing and environmental monitoring competing on throughput scale.
- Drinking Water:Distribution system compliance testing for lead, copper, disinfection byproducts, and emerging contaminants carries the highest analytical rigor requirements. US municipal laboratories facing Safe Drinking Water Act PFAS mandates are expanding analyzer capacity for parts-per-trillion detection.
- Environmental Monitoring:Surface water, groundwater, and sediment assessment protocols prioritize sample throughput over detection sensitivity. German environmental agencies under EU Water Framework Directive obligations are consolidating contracts with high-volume accredited laboratories.
- Industrial:Process water and effluent discharge testing supports manufacturing quality control and permit compliance.
- Aquaculture:Dissolved oxygen, ammonia, and nitrite monitoring maintains stock health in intensive farming operations.
Revenue concentration sits with Drinking Water; Environmental Monitoring is climbing the fastest.
End User:
Customer type determines procurement authority, with municipalities bound by public tender rules and industries negotiating direct vendor relationships.
- Municipalities:Public water systems must satisfy EPA and state-level regulatory timelines with budget-constrained capital programs. Subscription-based sensor-as-a-service models are gaining traction among smaller US systems avoiding upfront infrastructure investment.
- Laboratories:Commercial and municipal analytical facilities require ISO 17025 accreditation for regulated analyte classes, creating multi-year competitive barriers. German utilities are outsourcing complex emerging contaminant panels to these accredited providers.
- Industries:Chemical, pharmaceutical, and food processing operators conduct in-house testing for process optimization and discharge permitting.
- Research Institutions:Academic and government research programs drive methodological innovation and reference standard development.
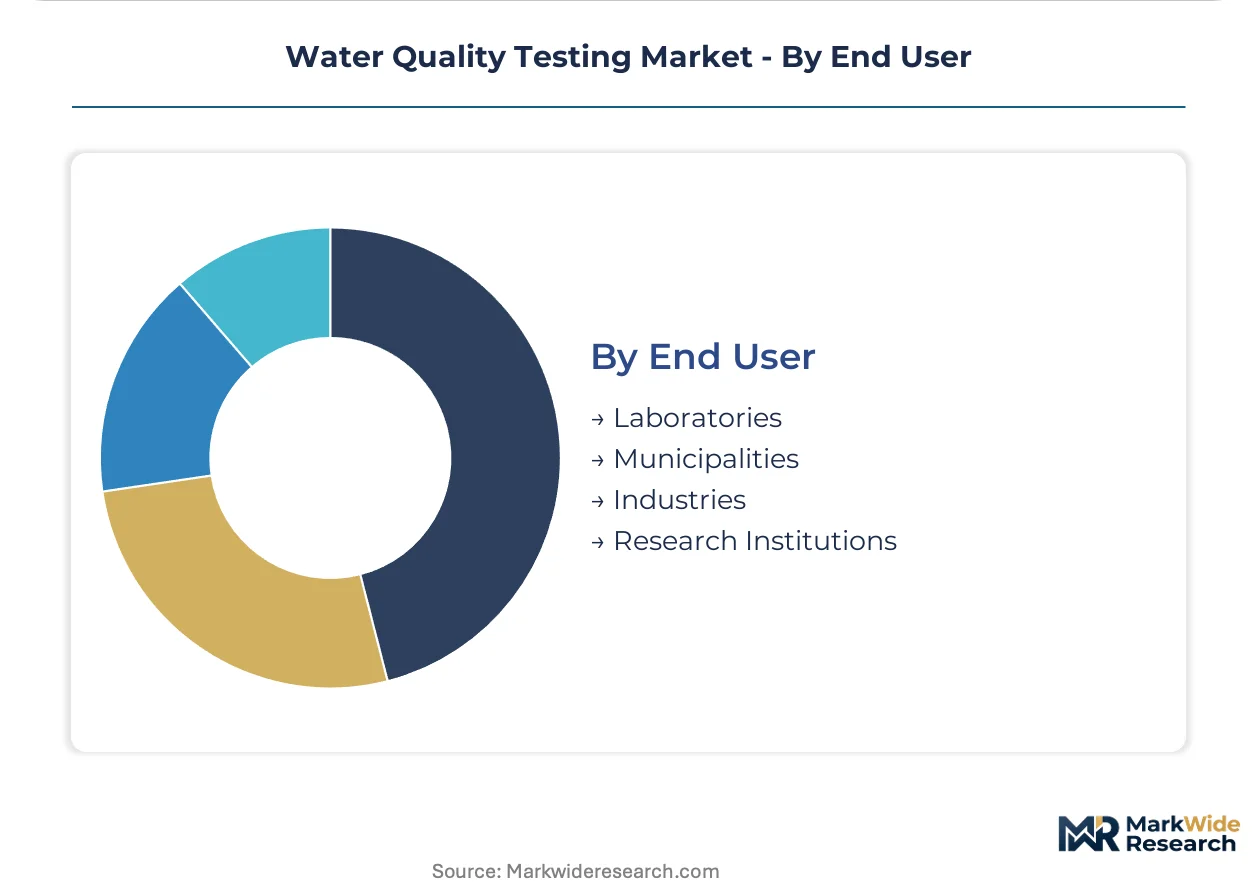
Procurement volume aggregates at Municipalities; the fastest share gain belongs to Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in Germany and the United States supply sensor networks to utilities worldwide, while testing service demand concentrates in jurisdictions with the most stringent contaminant schedules. Consumption patterns diverge sharply between mature markets replacing legacy infrastructure and emerging systems building first-generation monitoring capacity.
United States
Municipal utilities under EPA Safe Drinking Water Act pressure are deploying real-time lead detection analyzers across distribution networks. The revised Lead and Copper Rule accelerates compliance timelines for drinking water systems serving populations under 50,000. California's Central Valley agricultural districts are expanding nitrate monitoring programs to satisfy state groundwater quality mandates.
Germany
Cross-border utilities face accelerated testing mandates under the EU Drinking Water Directive harmonization process. The country's environmental regulator enforces expanded emerging contaminant panels for pharmaceutical runoff detection. Rhine basin chemical processors in North Rhine-Westphalia are consolidating testing contracts with accredited laboratories capable of multi-matrix analysis.
China
Industrial discharge compliance programs under MEE supervision are driving analyzer procurement from municipal environmental monitoring stations. The country's dual carbon goals pressure chemical manufacturers to quantify trace contaminant loads with greater precision. Yangtze River Delta industrial clusters are adopting automated sampling infrastructure for flow-proportional compositing systems.
Japan
Metropolitan water bureaus under METI guidance are upgrading legacy SCADA networks to accommodate multi-parameter sensor platforms. The country's pharmaceutical manufacturers face tightening effluent disclosure requirements for active pharmaceutical ingredients. Osaka Bay industrial corridors are deploying spectroscopic analyzers for simultaneous volatile organic and heavy metal detection.
India
Central Pollution Control Board mandates are expanding laboratory accreditation requirements for industrial discharge monitoring. The country's national water quality regulator is harmonizing testing protocols across state pollution control boards. Gujarat's chemical manufacturing belt is importing electrochemical sensor networks for real-time effluent compliance verification.
Water Quality Testing Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the testing equipment landscape, creating a tiered competitive structure. Laboratory service networks and sensor manufacturers operate on fundamentally different capital cycles, with the former scaling through geographic density and the latter through R&D amortization. Three archetypes dominate: diversified analytical conglomerates, specialized environmental testing laboratories, and precision instrumentation specialists. Consolidation pressure favors acquisition of regional testing networks by global service providers, while technology licensing agreements proliferate among sensor developers seeking utility market access.
Among European-based testing service providers, SGS SA, Bureau Veritas SA, and Eurofins Scientific SE exemplify the geographic density archetype, anchoring competitiveness through proximity to regulated industrial clusters. Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions within the precision instrumentation tier, representing the capital-intensive equipment supply vector. Xylem Inc. and Hach Company exemplify the integrated water technology model, spanning both sensor manufacturing and utility service relationships.
| Leading Market Players |
|---|
| Eurofins Scientific SE |
| SGS SA |
| Thermo Fisher Scientific Inc. |
| Intertek Group plc |
| Bureau Veritas SA |
| Xylem Inc. |
| ALS Limited |
| Hach Company |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Spectroscopic multi-parameter analyzer production is displacing legacy electrochemical manufacturing, simultaneously compressing unit economics and concentrating component sourcing around German and Japanese precision optics suppliers. This technology transition forces vendors to absorb upfront R&D amortization while utilities shift procurement toward subscription models that defer capital recognition.
Pricing Analysis
Margin tightening in municipal sensor deployments reflects EPA Lead and Copper Rule compliance deadlines compressing procurement cycles. Three-tier pricing structure across premium chromatography systems, standard multi-parameter sensors, and economy electrochemical probes dominates, with ISO 17025 certification tier and after-sales service bundling as primary differentiation drivers. Cost-down pressure on standard-tier units accelerates because South African platinum electrode volatility feeds into bill-of-materials uncertainty. Small utilities serving populations under 50,000 exhibit highest price sensitivity, while accredited municipal laboratories demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Freight cost escalation on precision optical components from Germany and Japan elevates landed costs for spectroscopic analyzer assemblies. Manufacturing concentrates in Germany, the United States, and China, with rare earth electrode materials drawing from South African and Russian extraction nodes. Single-source vulnerability in iridium supply chains for electrochemical sensors poses structural risk. Distribution runs through authorized service networks that retain asset ownership under sensor-as-a-service contracts, displacing traditional equipment resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water quality testing sits in a technology-transition phase where predictive sensor networks replace reactive laboratory workflows, with real-time telemetry infrastructure displacing decade-old SCADA integration points.
For Market Incumbents: Cement defensive positioning through chromatography software ecosystem lock-in and backward integration into precision electrode manufacturing. Emerging entrant pressure from asset-light sensor designers threatens equipment commoditization, making captive supply of platinum-group components a critical margin defense lever.
For New Entrants and Emerging Players: The mid-tier price gap between premium spectroscopic platforms and economy electrochemical probes creates white-space opportunity in pharmaceutical runoff detection panels for Rhine basin chemical processors. Target underpenetrated industrial discharge compliance in India's Gujarat chemical belt with portable multi-parameter test kits bundled with ISO 17025 accreditation support.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional testing networks by global service providers seeking geographic density. Long-term viability hinges on recurring revenue predictability from subscription-based sensor maintenance contracts. Watch EPA emerging contaminant schedule acceleration as the inflection signal for analyzer capacity expansion demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Chromatography Software Ecosystem Integration | Thermo Fisher's platform approach locks laboratory clients into vendor-specific analytical workflows against commoditization. |
| Sensor-as-a-Service Platform Launch | Xylem's subscription model converts municipal capital expenditure into recurring revenue while lowering utility entry barriers. |
| Accredited Laboratory Network Acquisition | Eurofins' geographic density strategy captures EU Drinking Water Directive compliance outsourcing from German utilities. |
| Backward Integration into Electrode Manufacturing | Hach's captive supply of platinum-group components insulates margins from South African extraction volatility. |
| Pharmaceutical Runoff Detection Panel Development | SGS's specialized service offering addresses REACH tightening on Rhine basin chemical processor discharge permits. |
Methodological Framework
Independent corroboration across municipal water utility procurement officers, analytical laboratory directors, and environmental compliance consultants underwrites the qualitative findings. Primary interviews with SCADA integration specialists, aftermarket service heads at sensor manufacturers, and EPA regulatory affairs leads combined with secondary validation from EPA enforcement guidance documents, EU Drinking Water Directive implementation reports, and ISO 17025 accreditation databases. Bottom-up equipment shipment analysis and top-down utility capital expenditure tracking triangulate market sizing.
Rate-of-change decomposition across product type, technology platform, application segment, and end-user archetype structures the analytical framework. Segmentation dimensions modeled include hardware category replacement cycles, detection methodology migration patterns, regulatory enforcement density tiers, and procurement authority distribution. CAGRs derive from utility capital program trajectories and subscription revenue conversion rates, with PFAS monitoring mandate expansion and EU harmonization timelines as water-quality-specific forecast inputs.
Inputs from EPA regulatory guidance and EU member state implementation reports were available through the study window; gaps in real-time utility procurement data introduce uncertainty bands around near-term sensor deployment forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Food Safety Testing Services Market