
 Marketing Analytics Market | 2026-2036
Marketing Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Marketing Analytics Market Outlook
Multi-source data integration is expanding as enterprises abandon siloed marketing databases for unified customer data platforms. Oracle Corporation leverages its enterprise cloud infrastructure to anchor large-scale attribution modeling deployments across Fortune 500 accounts. Adobe Inc. competes through creative-to-analytics workflow integration that sustains premium pricing in media-intensive verticals. SAS Institute Inc. specializes in advanced statistical methodologies that dominate regulated industries requiring auditable predictive outputs.
Marketing analytics encompasses the systematic computational analysis of consumer behavior data, campaign performance metrics, and market dynamics to inform resource allocation decisions across digital and physical channels. Platforms typically ingest structured and unstructured data streams, apply machine learning algorithms for propensity scoring, and render actionable intelligence through interactive visualization layers designed to reduce decision latency from weeks to hours. Cloud-based deployment now leads solution architecture as enterprises prioritize elastic compute capacity for seasonal campaign spikes, while predictive analytics commands the fastest expansion trajectory due to its direct linkage with revenue forecasting and churn prevention. The on-premise segment retains residual strength among financial services end users bound by stringent data residency protocols.
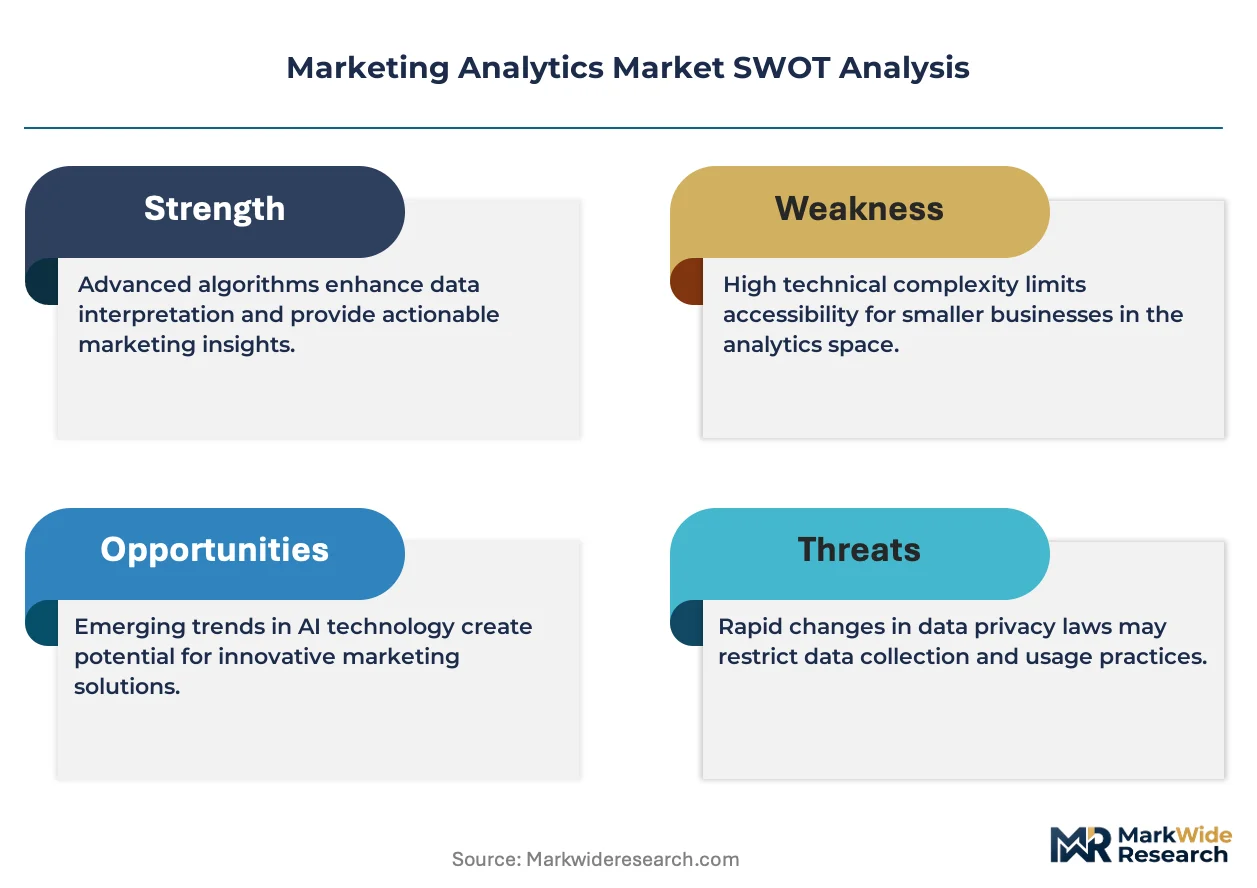
The Federal Trade Commission scrutinizes cross-platform consumer tracking practices, while the European Union's GDPR and AI Act impose algorithmic transparency obligations that reshape platform development roadmaps. Healthcare vertical adoption faces additional constraints from HIPAA's minimum necessary standard, which limits the granularity of patient data permissible for marketing optimization. Stakeholders must weigh jurisdictional compliance complexity against the performance advantages of centralized global data lakes when architecting their analytics infrastructure investments.
Market Dynamics
Cloud migration pressure from GDPR-aligned data governance frameworks in Europe is forcing enterprise martech stack refreshes while predictive analytics capabilities reshape vendor competitive positioning across attribution modeling deployments.
Growth Catalysts
- GDPR and AI Act compliance:European algorithmic transparency obligations accelerate platform replacement cycles as enterprises abandon legacy systems lacking auditable lineage.
- Retail predictive analytics:Customer lifetime value optimization drives Fortune 500 deployment of elastic compute infrastructure for seasonal campaign spikes.
- Healthcare data granularity:HIPAA's minimum necessary standard creates specialized demand for privacy-preserving analytics architectures in pharmaceutical marketing.
Market Restraints
- Data residency protocols:Financial services end users in Switzerland and Germany require on-premise deployment, limiting cloud vendor addressable market.
- Cross-platform tracking scrutiny:FTC enforcement actions against consumer surveillance practices increase compliance costs for attribution modeling.
- Elastic compute cost volatility:Seasonal campaign spikes create unpredictable infrastructure expenditure for mid-market enterprises.
Strategic Opportunities
- Unified customer data platforms:Siloed database consolidation creates white space for vendors offering multi-source integration without rip-and-replace.
- CSRD reporting convergence:European sustainability disclosure mandates create demand for marketing emissions attribution tools.
- Creative-to-analytics workflow:Media-intensive verticals seek seamless asset performance feedback loops currently fragmented across point solutions.
Industry Challenges
- Machine learning operations talent:Propensity scoring deployment requires scarce data engineering expertise that commands premium compensation.
- Interactive visualization latency:Decision compression from weeks to hours demands sub-second query performance that strains legacy data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marketing Analytics Market |
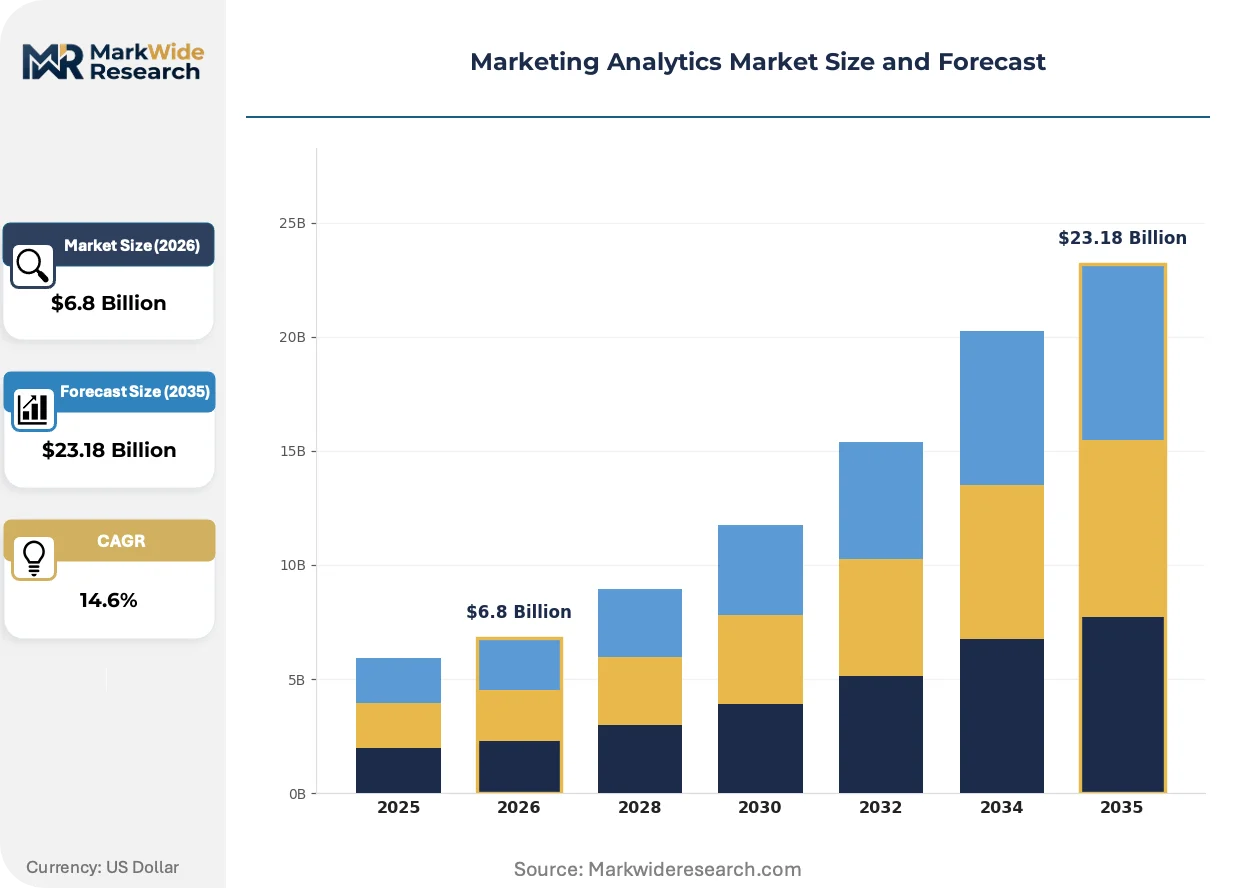
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Dashboard, Reporting, Data Mining, Predictive Analytics Deployment: On-Premise, Cloud-Based, Hybrid, Software as a Service End User: Retail, E-Commerce, Telecommunications, Financial Services Industry Vertical: Healthcare, Education, Travel, Entertainment |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, Salesforce.com Inc., Adobe Inc., Accenture PLC, Google LLC, SAS Institute Inc., HubSpot Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marketing Analytics Market Strategic Shifts
Machine learning algorithm deployment patterns are reshaping how enterprises consume marketing intelligence, with three forces compressing decision cycles and redefining vendor value propositions.
Natural language processing engines are integrating unstructured social media streams into structured attribution models. Consumer packaged goods manufacturers adopt these tools fastest, compressing insight-to-action cycles from campaign concept to execution. Real-time sentiment analysis is integrating with programmatic buying platforms to enable intraday budget reallocation.
The EU AI Act's risk classification framework imposes documentation burdens on high-stakes customer scoring applications. Marketing automation vendors must now maintain algorithmic audit trails previously absent from product roadmaps. Healthcare and financial services verticals face the steepest compliance ramps, driving consolidation toward vendors with pre-built governance modules.
Enterprise buying committees now mandate proof-of-concept validation before platform commitment, displacing traditional pilot-to-production timelines. Procurement functions centralize martech evaluation under chief data officer oversight, reducing marketing department autonomy. This pattern concentrates most visibly in United States Fortune 500 accounts where stack complexity demands federated governance.
Marketing Analytics Market Segmentation
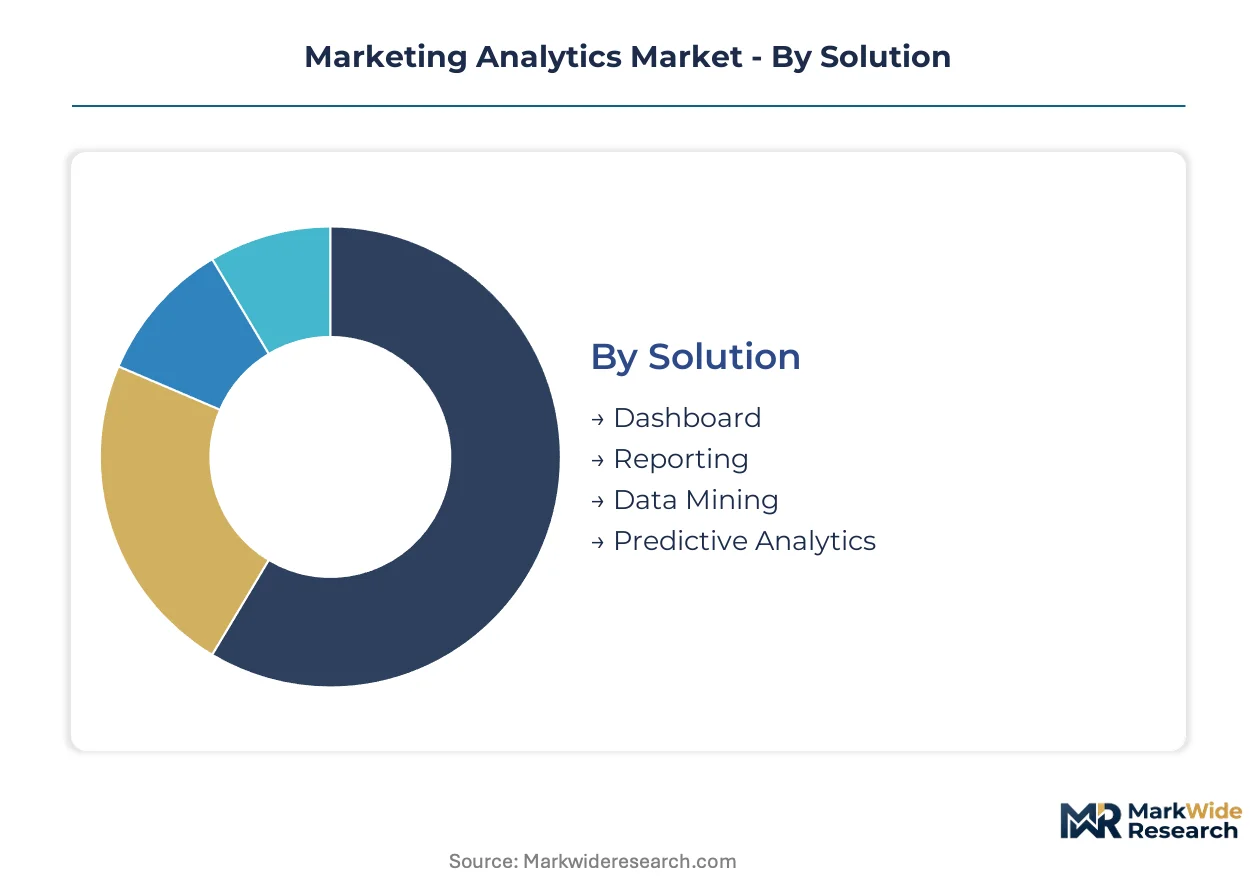
Marketing analytics segmentation reveals how solution architecture, infrastructure choices, and end-user requirements fragment purchasing patterns across enterprise tiers. Vendors must align product roadmaps with distinct deployment constraints and vertical compliance obligations rather than pursuing uniform platform strategies.
Solution:
Platform refresh cycles accelerate as enterprises abandon legacy reporting tools lacking real-time ingestion capabilities and AI-native architectures.
- Predictive Analytics:Machine learning algorithms for propensity scoring and churn prevention now anchor enterprise martech investments. Financial services and telecommunications sectors in the United States deploy these tools for revenue forecasting with direct P&L linkage, though EU AI Act documentation burdens slow adoption in regulated European markets.
- Dashboard:Interactive visualization layers compress decision latency from weeks to hours through sub-second query performance. Retail chains prioritize these solutions for intraday campaign budget reallocation during seasonal demand spikes.
- Reporting:Static output formats persist in mid-market accounts with limited data engineering resources. These deployments satisfy baseline compliance reporting without advanced segmentation capabilities.
- Data Mining:Unstructured social media stream processing integrates with attribution models for consumer packaged goods manufacturers. Natural language processing engines extract sentiment signals that feed programmatic buying platforms.
Predictive analytics sits at the top of the volume ranking, with dashboard solutions climbing the fastest as procurement functions centralize martech evaluation under chief data officer oversight.
Deployment:
Infrastructure expenditure patterns bifurcate between elastic cloud consumption for campaign volatility and captive on-premise systems for data residency mandates.
- Cloud-Based:Elastic compute capacity accommodates seasonal campaign spikes without capital-intensive hardware procurement. GDPR-aligned data governance frameworks in Europe accelerate platform refreshes toward these architectures.
- On-Premise:Residual strength concentrates in Swiss and German financial services bound by stringent data residency protocols. HIPAA's minimum necessary standard also drives healthcare provider preference for localized patient data processing.
- Software as a Service:Subscription pricing lowers barrier to entry for mid-market enterprises facing unpredictable infrastructure expenditure. Vendor-managed maintenance reduces scarce MLOps talent requirements.
- Hybrid:Federated governance architectures partition sensitive customer data on-premise while leveraging cloud elasticity for anonymized aggregate analytics. Fortune 500 buying committees increasingly mandate this configuration.
Cloud-based deployment captures the dominant revenue share, with hybrid architectures expanding most rapidly as jurisdictional compliance complexity collides with performance demands.
End User:
Customer lifetime value optimization intensity varies sharply across sectors, with retail and telecommunications leading algorithmic investment while financial services navigate regulatory friction.
- Retail:Fortune 500 chains deploy predictive analytics across physical and digital touchpoints to optimize inventory allocation and personalized promotion delivery. Elastic infrastructure investments spike ahead of holiday seasons.
- Telecommunications:Churn prevention algorithms process real-time usage patterns to trigger retention interventions. These deployments require sub-second latency that strains legacy data architectures.
- E-Commerce:Cross-platform consumer tracking faces FTC scrutiny that increases compliance costs for attribution modeling. First-party data strategies displace third-party cookie dependencies.
- Financial Services:Algorithmic transparency obligations under GDPR and the EU AI Act reshape platform development roadmaps. Auditable predictive outputs dominate vendor selection criteria.
Retail commands the largest absolute spend, with telecommunications showing the steepest expansion trajectory as 5G deployment generates granular behavioral data streams.
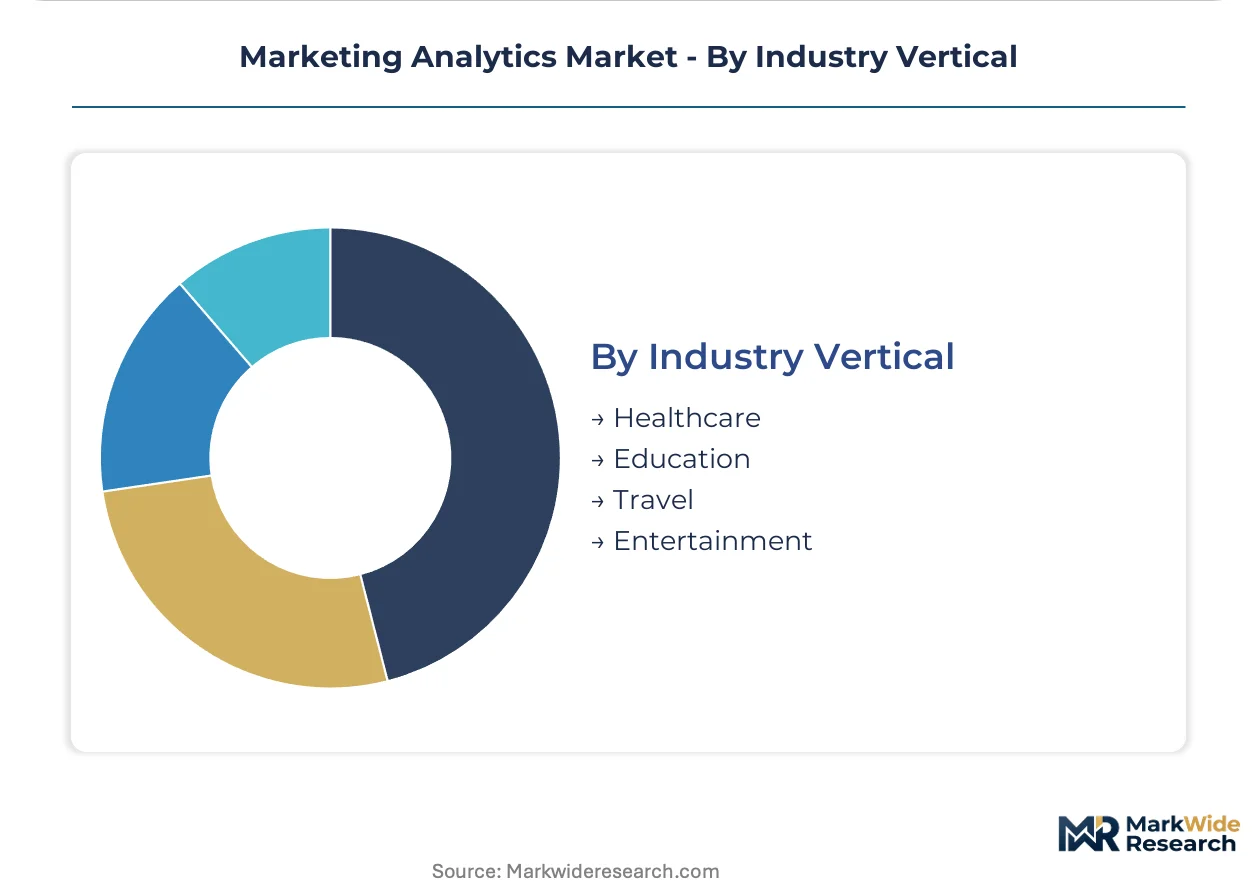
Industry Vertical:
Regulatory overlay density determines analytics granularity permissible for marketing optimization, creating specialized demand for privacy-preserving architectures.
- Healthcare:HIPAA constraints limit patient data permissible for pharmaceutical marketing. Privacy-preserving analytics architectures command premium pricing in this vertical.
- Education:Student information system integrations enable enrollment funnel optimization. Public institution procurement cycles extend deployment timelines.
- Travel:Dynamic pricing engines consume real-time demand signals across booking platforms. Seasonal volatility drives cloud infrastructure preference.
- Entertainment:Content performance feedback loops require creative-to-analytics workflow integration currently fragmented across point solutions.
Healthcare generates the highest solution customization revenue, with entertainment verticals gaining share fastest as streaming wars intensify content investment decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting marketing analytics procurement toward jurisdictions with clearer algorithmic governance frameworks. Enterprises in high-compliance-cost environments are consolidating vendor relationships with platforms pre-certified for multi-territory deployment.
United States
Fortune 500 enterprises maintain the deepest martech stacks globally, driving concentrated demand for predictive analytics with direct P&L linkage. FTC enforcement actions against cross-platform consumer tracking are increasing compliance costs for attribution modeling vendors. New York and San Francisco anchor the largest clusters of marketing analytics deployment, with financial services and technology sectors leading algorithmic investment intensity.
Germany
Stringent data residency protocols in financial services sustain residual on-premise deployment preference, limiting cloud vendor addressable market. GDPR-aligned data governance frameworks are accelerating platform replacement cycles as enterprises abandon legacy systems lacking auditable lineage. Frankfurt and Munich concentrate the highest density of healthcare and automotive vertical deployments requiring privacy-preserving architectures.
United Kingdom
Creative-to-analytics workflow integration commands premium pricing in media-intensive verticals concentrated in London. The Information Commissioner's Office maintains active oversight of algorithmic decision-making systems used in consumer scoring. The Thames Valley corridor hosts significant clusters of telecommunications and retail headquarters deploying churn prevention and customer lifetime value optimization tools.
India
Mid-market enterprises are adopting software-as-a-service pricing models to reduce scarce MLOps talent requirements and unpredictable infrastructure expenditure. The Digital Personal Data Protection Act is reshaping vendor selection criteria toward platforms with built-in consent management architectures. Bangalore and Hyderabad anchor the fastest-growing clusters of marketing analytics implementation, with e-commerce and telecommunications sectors driving expansion.
Japan
Enterprise buying committees mandate proof-of-concept validation before platform commitment, displacing traditional pilot-to-production timelines. METI guidelines on AI utilization are influencing procurement standards for algorithmic transparency in customer-facing applications. Tokyo and Osaka concentrate the highest deployment density, with consumer packaged goods manufacturers leading adoption of real-time sentiment analysis integrated with programmatic buying platforms.
Marketing Analytics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized vertical applications and privacy-preserving architectures. The vendor landscape fragments across three maturity tiers: global cloud infrastructure providers anchoring enterprise-scale deployments, specialized statistical software vendors dominating regulated industries, and workflow-integrated creative platforms capturing media-intensive verticals. Dominant competitive moves include strategic partnerships between cloud infrastructure and specialized analytics vendors, plus portfolio diversification into governance and compliance modules.
Within the enterprise cloud tier, IBM Corporation and Microsoft Corporation exemplify the scale-driven archetype, anchoring large-scale attribution modeling deployments through extensive enterprise relationships. Oracle Corporation occupies a position bridging infrastructure and application layers, while Adobe Inc. represents the creative-to-analytics workflow integration specialist commanding premium positioning in media-intensive verticals. SAS Institute Inc. sits within the regulated-industry specialist tier, with its advanced statistical methodologies dominating verticals requiring auditable predictive outputs.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Salesforce.com Inc. |
| Adobe Inc. |
| Accenture PLC |
| Google LLC |
| SAS Institute Inc. |
| HubSpot Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure providers backed by sovereign wealth and private-equity consolidation have reshaped supply discipline across marketing analytics, concentrating platform development capacity among vertically integrated hyperscalers while enforcing subscription pricing rigor through multi-year enterprise commitments.
Pricing Analysis
Direct-to-enterprise discounts dominate cloud-based deployments, with subscription tiers stratifying across premium attribution modeling, standard dashboarding, and economy reporting modules. Price differentiation rests on GDPR compliance certification and elastic compute allocation guarantees. Cost compression in mid-market SaaS tiers intensifies as vendor-managed maintenance displaces scarce MLOps talent requirements. Financial services buyers exhibit lowest price sensitivity due to regulatory non-negotiability, while education and mid-market retail segments drive hardest bargain.
Supply Chain Analysis
Regional distribution centers in Ireland, Germany, and Singapore anchor data residency-compliant infrastructure delivery to regulated European and Asia-Pacific markets. Raw material dependencies center on GPU compute clusters, proprietary machine learning frameworks, and specialized visualization rendering engines. Single-source vulnerability concentrates in NVIDIA's dominance of training-grade silicon, exposing vendors to allocation constraints. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with embedded solutions architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marketing analytics functions as a stable compounder, with enterprise cloud migration and regulatory compliance mandates providing durable demand visibility across economic cycles.
For Market Incumbents: Deploy pre-certified governance modules as competitive moats against emerging privacy-preserving specialists. Fortify position through backward integration into specialized silicon for model training workloads. Counter cloud hyperscaler encroachment by deepening vertical-specific algorithmic audit trails for EU AI Act readiness. For New Entrants and Emerging Players: Launch via healthcare-focused privacy-preserving architectures where HIPAA constraints limit incumbent platform suitability. Target pharmaceutical marketing analytics as the most penetrable vertical, exploiting gap between legacy statistical vendors and cloud-native workflow integration. Pursue channel partnerships with hospital GPOs and academic medical centers rather than direct enterprise sales buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among regulated-industry statistical specialists with pre-built compliance modules but limited cloud-native architecture. Long-term viability favors vendors bridging creative-to-analytics workflow fragmentation in media-intensive verticals. Watch FDA guidance on AI-enabled patient engagement tools as inflection signal for healthcare marketing analytics expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented creative-to-analytics workflows that Adobe and Oracle currently dominate separately. |
| Acquisition of Specialist Firm | Consolidates privacy-preserving computation expertise for HIPAA-constrained healthcare deployments. |
| Strategic Partnership | Secures GPU allocation commitments with NVIDIA for training-grade infrastructure amid silicon constraints. |
| Geographic Expansion | Establishes Irish and German data centers to satisfy GDPR data residency and EU AI Act audit requirements. |
| Product Launch | Introduces real-time sentiment analysis engines for CPG manufacturers seeking intraday programmatic budget shifts. |
Study Parameters
Multiple input streams — chief data officer interviews, martech procurement officer surveys, and cloud infrastructure spend disclosures — were reconciled against secondary validation from SEC 10-K filings, hyperscaler capex reports, and EU regulatory compliance databases. Primary fieldwork captured perspectives from platform engineers, integration specialists, and channel partners at Fortune 500 deployments. Bottom-up segment sizing triangulated against top-down enterprise IT spend allocation models.
Data-stream reconciliation anchored volume and value projections across the modeling period, with segmentation dimensions spanning deployment architecture, solution type, end-user vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating GDPR enforcement intensity and cloud migration velocity. Industry-specific inputs included FTC enforcement action frequency and EU AI Act implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FTC privacy enforcement or semiconductor export restriction scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Online Analytical Processing Market
Analytics
APAC Retail Analytics Market
Analytics
Lead Intelligence Software Market
Analytics
Global Recommendation Engine Market
Analytics
Regression Analysis Tool Market
Analytics
Speech and Voice Analytics Market
Analytics
Cloud Performance Management Market
Analytics
Sales Intelligence Market
Analytics
App Analytics Market
Analytics
Service Analytics Market
Analytics
Contact Center Intelligence Market
Analytics
Big Data Analytics Market
Analytics
Self Service Analytics Market
Analytics
Product Analytics Market
Analytics
Greece ICT Market
Analytics
Business Value Dashboard Market