
 Labeling Software Market | 2026-2036
Labeling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Labeling Software Market Outlook
Aftermarket compliance service revenue is reconfiguring how labeling software vendors capture lifetime value from enterprise accounts. Labelbox, Inc. leverages its annotation infrastructure to extend into regulated industries requiring audit-ready label provenance. Encord competes through specialized computer-vision workflows that anchor pharmaceutical and autonomous vehicle development pipelines. Scale AI dominates data-labeling scale operations, sustaining platform stickiness through API-integrated quality assurance layers.
Labeling software comprises applications that generate, manage, and output machine-readable identifiers, human-readable text, and graphics onto physical substrates or digital assets, typically supporting variable data printing, barcode symbologies, and RFID encoding for supply chain traceability. Its primary commercial purpose is ensuring product identity, regulatory compliance, and logistics visibility across manufacturing, distribution, and retail endpoints. Cloud-based solutions are capturing the fastest expansion as pharmaceutical and food producers migrate serialization workloads away from rigid on-premises installations. Desktop software retains entrenched positions in small-batch manufacturing settings where offline operation and minimal IT overhead anchor purchasing decisions. The hybrid deployment segment is maturing among large enterprises seeking to bridge legacy plant-floor systems with centralized cloud governance.
FDA 21 CFR Part 11 shapes demand by mandating electronic records and signatures in pharmaceutical labeling, forcing vendors to embed audit trails and access controls. The EU Medical Device Regulation and REACH labeling requirements from ECHA impose multilingual hazard communication standards that expand functional scope for European deployments. Stakeholders must monitor how FDA digital transformation initiatives and emerging EU AI Act documentation rules will redefine label-data governance requirements for algorithm-trained systems.
Market Dynamics
Cloud-native serialization platforms are displacing rigid on-premises installations as pharmaceutical manufacturers confront FDA 21 CFR Part 11 audit requirements and EU MDR traceability mandates. This infrastructure migration compresses deployment timelines while elevating cybersecurity and validation burdens.
Growth Catalysts
- EU MDR serialization mandates:Medical device manufacturers must implement unique device identification systems by regulatory deadlines, forcing wholesale replacement of legacy label management systems with audit-ready cloud infrastructure.
- Pharmaceutical track-and-trace expansion:DSCSA compliance deadlines in the United States and equivalent frameworks in Brazil and South Korea drive demand for enterprise-grade labeling platforms with real-time verification capabilities.
- Industrial automation clusters:Germany's chemical-pharma export corridors require multilingual, regulation-ready labeling infrastructure that integrates directly with MES and ERP systems.
Market Restraints
- Validation cost escalation:FDA 21 CFR Part 11 compliance demands extensive IQ/OQ/PQ documentation and third-party audit costs that disproportionately burden mid-tier pharmaceutical contract manufacturers.
- Legacy system entrenchment:Small-batch manufacturers in North American and European craft food sectors retain desktop software due to minimal IT overhead and offline operation requirements.
- Substitution by ERP-native modules:SAP, Oracle, and Microsoft embed labeling functionality within broader manufacturing suites, compressing standalone software addressable market.
Strategic Opportunities
- AI-Act documentation readiness:The EU AI Act's algorithmic transparency requirements create demand for label-data provenance systems that track training-set lineage and model versioning.
- Cell and gene therapy cold-chain:Biologics manufacturers require temperature-conditional labeling with real-time environmental monitoring integration, opening premium solution segments.
- Direct-to-patient pharmacy models:E-pharmacy fulfillment networks in India and Southeast Asia need cloud-based label generation for serialized unit-dose packaging at distributed micro-fulfillment centers.
Industry Challenges
- CSV talent scarcity:Computer system validation specialists with combined GxP and cloud-security expertise command premium compensation, constraining vendor implementation capacity.
- Multi-tenant isolation complexity:Cloud providers must demonstrate logical separation of pharmaceutical client data to satisfy FDA data-integrity expectations during pre-approval inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Labeling Software Market |
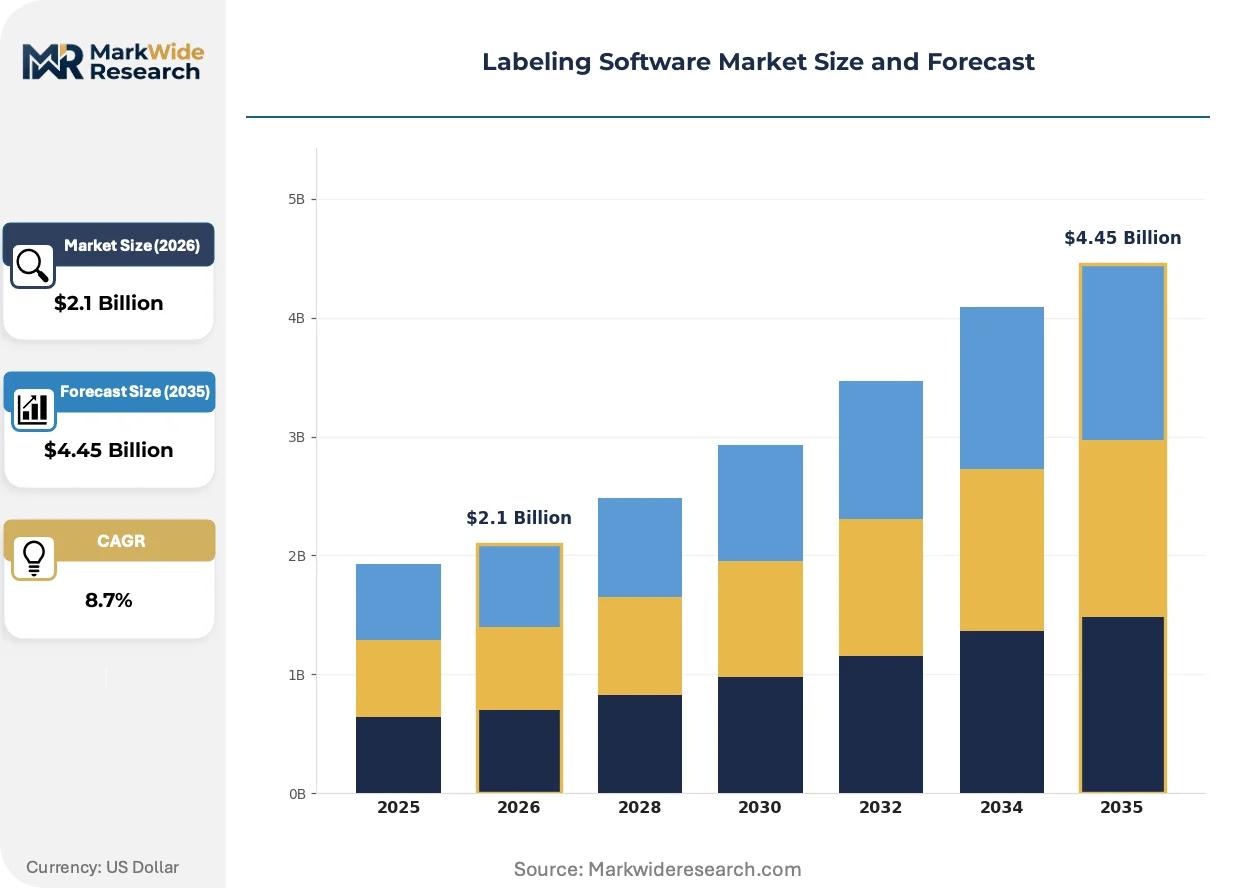
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Cloud-Based Solutions, Web Applications, Mobile Applications Industry Vertical: Healthcare, Retail, Manufacturing, Food & Beverage Deployment: On-Premises, Software as a Service, Hybrid, Enterprise End User: Small Businesses, Large Enterprises, Non-Profits, Government Agencies |
| Companies Covered | Amazon Web Services, Cogito Tech, Appen Limited, V7 Labs, SuperAnnotate, Scale AI, Encord, Alegion, Labelbox, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Labeling Software Market Strategic Shifts
Labeling infrastructure is converging with quality management and manufacturing execution systems, collapsing previously siloed workflows into unified data platforms. This integration eliminates redundant master-data management while introducing new vendor consolidation risks.
Blockchain-anchored label provenance is migrating from pilot deployments to production environments in pharmaceutical supply chains. The technology generates immutable audit trails for serialization events. European and North American manufacturers are adopting it to satisfy DSCSA and Falsified Medicines Directive verification requirements. This migration from experimental to operational status is compressing competitive differentiation timelines for compliance-focused vendors.
REACH labeling expansions under ECHA guidance are forcing chemical manufacturers to recalibrate hazard communication templates for multilingual, multi-jurisdiction distribution. The regulation now requires digital label extensions linking to extended safety data sheets. German and Dutch chemical exporters are most affected, accelerating investment in template automation that localizes content without manual re-engineering.
Subscription pricing for labeling software is displacing perpetual-license models among mid-market manufacturers. Buyers prefer operational expenditure treatment and embedded upgrade paths over capital-intensive on-premises deployments. This preference shift is most visible in United States contract packaging organizations serving pharmaceutical and nutraceutical clients with variable production volumes.
Labeling Software Market Segmentation
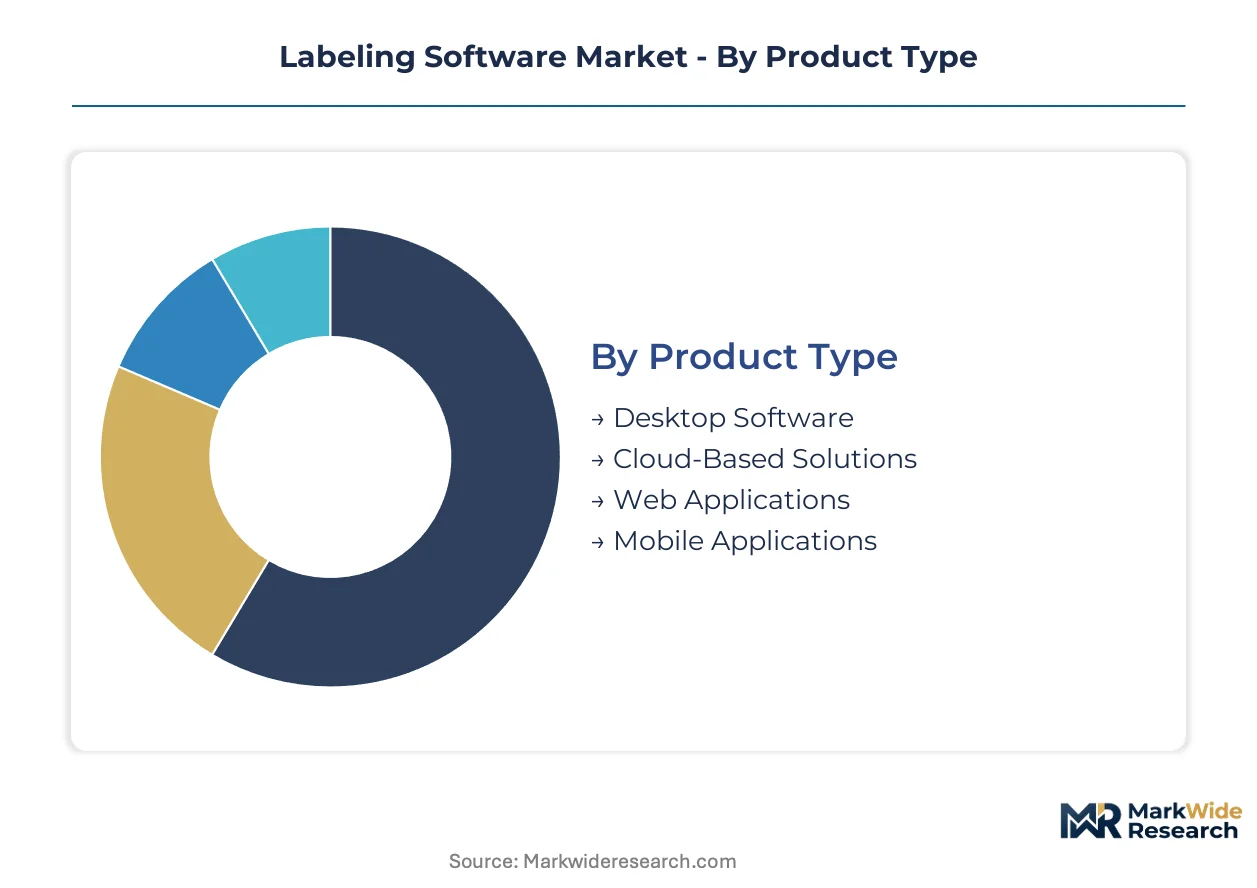
Segmentation in labeling software reveals how infrastructure choices map to regulatory pressure and operational scale. Pharmaceutical manufacturers drive premium cloud adoption while craft producers anchor legacy desktop retention. Understanding these splits clarifies where compliance costs concentrate versus where minimal IT overhead dominates purchasing logic.
Product Type:
Cloud-based solutions turn over fastest as FDA validation cycles compress deployment timelines, while desktop software retains the longest replacement cycles among offline-dependent small-batch operations.
- Cloud-Based Solutions:Multi-tenant architectures with embedded audit trails and API-first integration layers support real-time serialization for DSCSA and EU MDR compliance. Demand concentrates among pharmaceutical contract manufacturers in Germany and the United States where pre-approval inspection readiness elevates cybersecurity and validation documentation requirements.
- Desktop Software:Offline-capable installations with minimal IT infrastructure requirements serve small-batch food and craft beverage producers. North American and European artisan manufacturers retain these systems due to zero cloud dependency and low total cost of ownership despite limited regulatory automation.
- Web Applications:Browser-based label design tools with template libraries target mid-market manufacturers seeking centralized template governance without full cloud migration.
- Mobile Applications:Field-deployed label generation for warehouse floor operations and direct-store-delivery verification in retail distribution networks.
Desktop software anchors the volume base across installed legacy systems while cloud-based solutions gain share at the steepest rate under pharmaceutical serialization mandates.
Industry Vertical:
Cost tier stratification separates verticals: healthcare commands premium validation-ready platforms while food and beverage operates on leaner template-automation budgets.
- Healthcare:Medical device and pharmaceutical manufacturers require UDI-compliant labeling with full electronic records and signature capabilities under FDA 21 CFR Part 11. German and Dutch exporters to EU MDR jurisdictions drive template automation for multilingual hazard communication.
- Manufacturing:Industrial automation clusters integrate labeling directly with MES and ERP systems for chemical-pharma export corridors requiring REACH-compliant hazard communication.
- Retail:Omnichannel fulfillment networks need dynamic label generation for serialized unit-dose packaging at distributed micro-fulfillment centers.
- Food & Beverage:Cold-chain biologics and temperature-conditional labeling with environmental monitoring integration serve cell and gene therapy supply chains.
Healthcare commands the highest per-seat pricing while retail is expanding most quickly through e-pharmacy fulfillment networks in India and Southeast Asia.
Deployment:
Customer type determines deployment architecture: large enterprises demand hybrid governance bridges while small businesses prioritize SaaS operational expenditure treatment.
- Software as a Service:Subscription pricing with embedded upgrade paths attracts United States contract packaging organizations serving variable-volume pharmaceutical and nutraceutical clients. Operational expenditure preference displaces perpetual-license models among mid-market manufacturers.
- Hybrid:Large enterprises bridge legacy plant-floor systems with centralized cloud governance to satisfy multi-tenant data isolation requirements during FDA pre-approval inspections.
- On-Premises:Rigid legacy installations persist where offline operation and minimal IT overhead anchor purchasing decisions in small-batch settings.
- Enterprise:Dedicated single-tenant deployments with custom validation documentation for the most stringent GxP environments.
SaaS deployment anchors current new-logo acquisition while hybrid configurations climb the fastest among Fortune 500 pharmaceutical manufacturers.
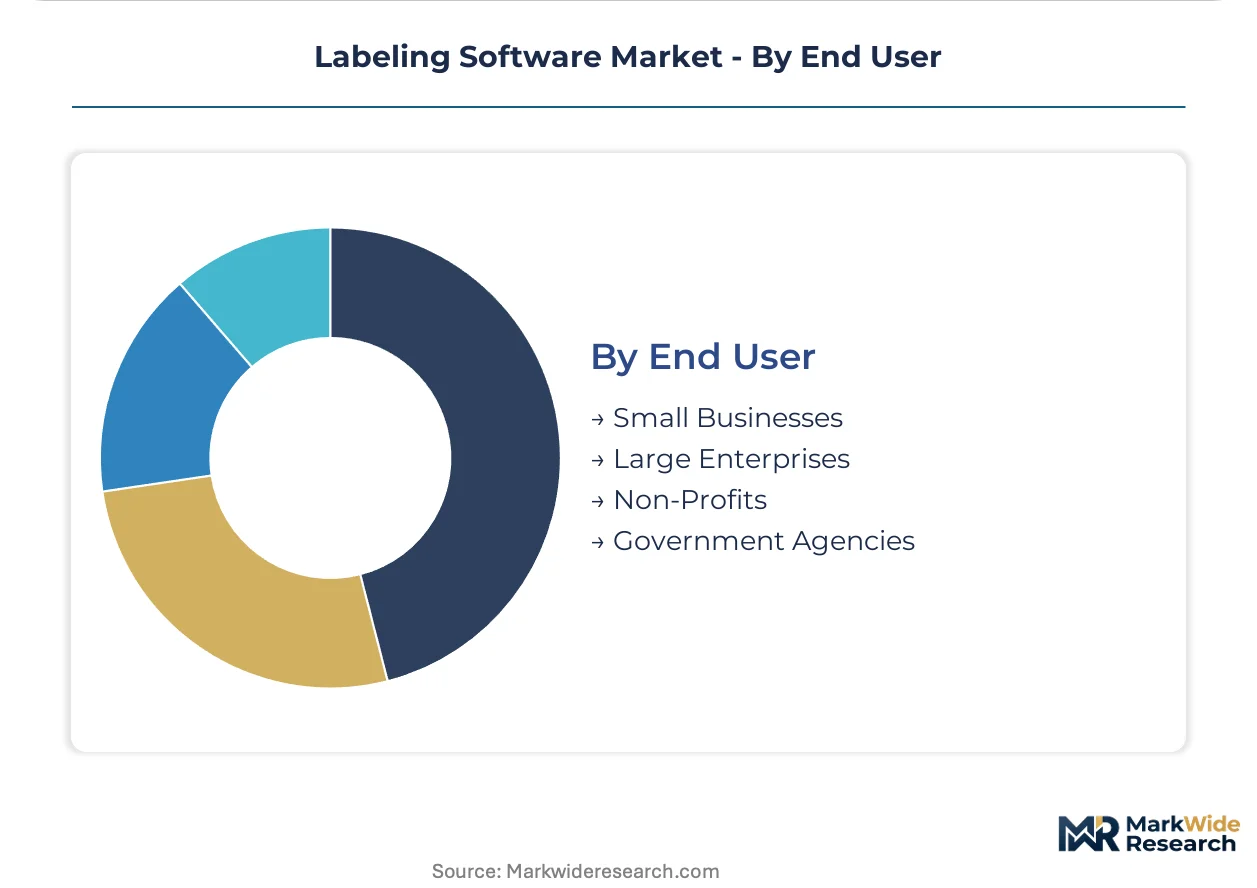
End User:
Volume scale separates end users: large enterprises drive platform consolidation while small businesses fragment across point solutions.
- Large Enterprises:Multi-site manufacturers with unified master-data management requirements and redundant system elimination mandates. SAP, Oracle, and Microsoft embedding labeling functionality within manufacturing suites compress standalone software addressable market for this segment.
- Small Businesses:Minimal IT overhead requirements and offline operation preferences sustain desktop software retention in craft food and beverage sectors.
- Government Agencies:Public health distribution networks requiring serialized unit-dose tracking for pharmaceutical security programs.
- Non-Profits:Humanitarian supply chains with multilingual label requirements for international aid distribution.
Large enterprises anchor platform revenue concentration while small businesses represent the most fragmented and price-sensitive demand pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical exporters deploy labeling infrastructure for multilingual EU MDR compliance, while United States manufacturers prioritize FDA 21 CFR Part 11 validation documentation. Indian e-pharmacy networks and Japanese precision manufacturers represent contrasting adoption profiles.
Germany
Chemical-pharma export corridors in North Rhine-Westphalia and Bavaria drive demand for REACH-compliant hazard communication templates. ECHA regulations mandate digital label extensions linking to extended safety data sheets. Industrial automation clusters around Frankfurt and Stuttgart integrate labeling directly with MES systems for real-time serialization.
United States
Pharmaceutical contract manufacturers concentrate DSCSA compliance investments in New Jersey and Massachusetts biotech corridors. FDA 21 CFR Part 11 mandates electronic records and signatures, elevating cybersecurity documentation requirements. Cloud-native serialization platforms displace legacy installations as pre-approval inspection readiness becomes critical.
India
E-pharmacy fulfillment networks in Maharashtra and Karnataka require cloud-based label generation for serialized unit-dose packaging. CDSCO track-and-trace frameworks align with DSCSA-equivalent mandates. Distributed micro-fulfillment centers in Delhi-NCR and Hyderabad anchor subscription pricing adoption among mid-market manufacturers.
Japan
Precision medical device manufacturers in Kanto and Kansai regions implement UDI-compliant labeling under PMDA guidance. METI industrial digitization programs accelerate replacement of legacy on-premises systems. Osaka-based pharmaceutical exporters prioritize multilingual template automation for EU market access.
Switzerland
Swissmedic-regulated biologics manufacturers in Basel and Zurich require temperature-conditional labeling for cell and gene therapy cold-chains. REACH alignment obligations for chemical exports to EU member states expand functional scope. Pharmaceutical headquarters clusters leverage hybrid deployment architectures to bridge legacy validation with cloud governance.
Labeling Software Market Competitive Environment
Capability concentration sits with specialized annotation platforms; scale advantage sits with infrastructure-integrated providers. The vendor base separates into three tiers: cloud-native compliance specialists, data-labeling scale operators, and ERP-embedded module providers. Strategic moves center on API-first integration layers and multi-tenant validation documentation. M&A activity targets computer-vision workflow capabilities and pharmaceutical audit-trail expertise.
Within the cloud-native tier, Labelbox, Inc. and Encord exemplify archetypes bridging annotation infrastructure with regulated industry requirements. Scale AI occupies a position at the scale-driven end of data-labeling operations. These three anchors represent divergent competitive vectors: compliance documentation depth, specialized computer-vision workflows, and API-integrated quality assurance at volume.
| Leading Market Players |
|---|
| Amazon Web Services |
| Cogito Tech |
| Appen Limited |
| V7 Labs |
| SuperAnnotate |
| Scale AI |
| Encord |
| Alegion |
| Labelbox, Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR Part 11 validation chokepoints determine both SaaS subscription tier spreads and supply chain configuration, compressing margins for mid-tier pharmaceutical contract manufacturers while concentrating premium pricing power with audit-ready cloud providers.
Pricing Analysis
Long-term subscription contracts anchor pharmaceutical manufacturer relationships, displacing perpetual-license models among United States contract packaging organizations. Pricing stratifies across FDA validation-ready premium tiers, mid-market SaaS with embedded upgrade paths, and economy desktop licenses for offline-dependent craft producers. Cost compression in mid-market SaaS intensifies because ERP-native modules from SAP and Oracle embed labeling functionality at marginal cost. Small-batch food and beverage manufacturers exhibit highest price sensitivity, while German chemical-pharma exporters show lowest sensitivity due to REACH compliance penalties for template errors.
Supply Chain Analysis
Export-control restrictions on cryptographic modules for electronic signature capabilities limit software component flows from United States developers to certain jurisdictions. Development talent concentrates in Germany, the United States, and India, with cloud infrastructure sourcing from hyperscaler regions in Ireland, Singapore, and Virginia. Raw material dependencies include API integration frameworks, barcode symbology libraries, and RFID encoding modules. Single-source vulnerability sits with specialized computer system validation consultants commanding premium compensation. Distribution runs through direct enterprise sales teams for large pharmaceutical accounts and channel partners for mid-market manufacturing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Labeling software sits in early-cycle expansion as pharmaceutical serialization mandates drive wholesale replacement of legacy on-premises installations with cloud-native platforms.
For Market Incumbents: Harden multi-tenant data isolation documentation to satisfy FDA pre-approval inspection expectations, addressing the threat of ERP-native module substitution by embedding deeper MES integration layers. Prioritize certification investment in EU AI Act documentation readiness to capture algorithmic transparency requirements before specialized annotation platforms extend into regulated label provenance. For New Entrants and Emerging Players: Build out computer-vision workflow capabilities targeting pharmaceutical training-set lineage tracking, the most penetrable white-space segment before Scale AI and Encord consolidate anchor positions. Pursue direct-to-patient pharmacy models in Indian e-pharmacy fulfillment networks as the fastest-adopting geography for serialized unit-dose micro-fulfillment. For Investors and Strategic Acquirers: EU MDR serialization deadlines reshape the acquisition landscape toward audit-trail expertise and pharmaceutical validation documentation depth. Five-to-ten year viability favors targets with captive GxP consulting capacity and hybrid deployment architectures bridging legacy plant-floor systems. Watch CDSCO track-and-trace framework alignment with DSCSA-equivalent mandates as the signal for Indian market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with MES/ERP | Eliminates redundant master-data management for German chemical-pharma export corridors. |
| Acquisition of CSV Specialist Firm | Captures scarce computer system validation talent with combined GxP and cloud-security expertise. |
| EU AI Act Documentation Readiness | Positions label-data provenance systems for algorithmic transparency requirements. |
| Geographic Expansion to India | Targets e-pharmacy fulfillment networks in Maharashtra and Karnataka for serialized packaging. |
| Blockchain-Anchored Label Provenance | Generates immutable audit trails satisfying DSCSA and Falsified Medicines Directive verification. |
Study Parameters
A standing panel of pharmaceutical IT directors, regulatory affairs leads, MES integration specialists, and contract manufacturing quality heads provided ongoing calibration across primary interview rounds and secondary validation. FDA 21 CFR Part 11 guidance documents, EMA MDR implementation reports, CDSCO track-and-trace notifications, and hyperscaler cloud compliance disclosures anchored secondary sourcing. Bottom-up deployment model sizing triangulated against top-down pharmaceutical serialization mandate timelines.
Scenario-bracketing framed optimistic, baseline, and constrained adoption paths across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical regulatory intensity, integration complexity with legacy plant-floor systems, and regional compliance framework cluster. CAGRs derived from validated installation base replacement cycles and new-logo acquisition velocity in cloud-native serialization platforms. Forecast inputs incorporated DSCSA compliance deadline enforcement patterns and EU MDR unique device identification system implementation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ERP-embedded module providers or specialized annotation platforms would shift outcomes. Material shifts in FDA digital transformation initiative timelines or EU AI Act documentation rule finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Campaign Management Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Global Plumbing Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Mobile Application Development Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Petcare Software Market
Software & Services
Software Repository Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Business Rules Management System Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Virtual Studio Software Market
Software & Services
Engineering Software Market
Software & Services
Enterprise Application Market
Software & Services
Freight Management Software Market
Software & Services
Global Reference Check Software Market