
 Spend Analysis Software Market | 2026-2036
Spend Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Spend Analysis Software Market Outlook
North American cloud infrastructure expansion is reconfiguring how procurement technology vendors distribute their platforms. GEP leverages native AI capabilities to anchor enterprise sourcing workflows. SAP Ariba dominates network-based supplier discovery through its embedded commerce layer. Ivalua specializes in configurable spend taxonomy engines that sustain complex multi-entity deployments.
Spend analysis software comprises data ingestion pipelines, classification algorithms, and visualization dashboards that normalize procurement transactions across ERP systems, supplier networks, and payment platforms. The technology employs machine learning models to auto-classify spend categories against UNSPSC or custom taxonomies at classification rates exceeding rule-based systems. Cloud-based deployments now lead adoption curves among mid-market buyers seeking faster implementation cycles without dedicated infrastructure teams. On-premises installations persist in defense and financial services segments where data residency requirements override total-cost considerations. Government end users represent a concentrated margin pool given lengthy procurement cycles and compliance-driven renewal rates.
The EU CSRD and GDPR frameworks mandate granular spend disclosure and supplier data governance across European operations, compelling platform upgrades for multinational registrants. In the United States, the DATA Act and FAR procurement regulations enforce standardized spend reporting that drives federal agency demand for dedicated analytics modules. Stakeholders must monitor how emerging AI procurement guidelines from the EU AI Act reshape algorithmic sourcing transparency requirements.
Market Dynamics
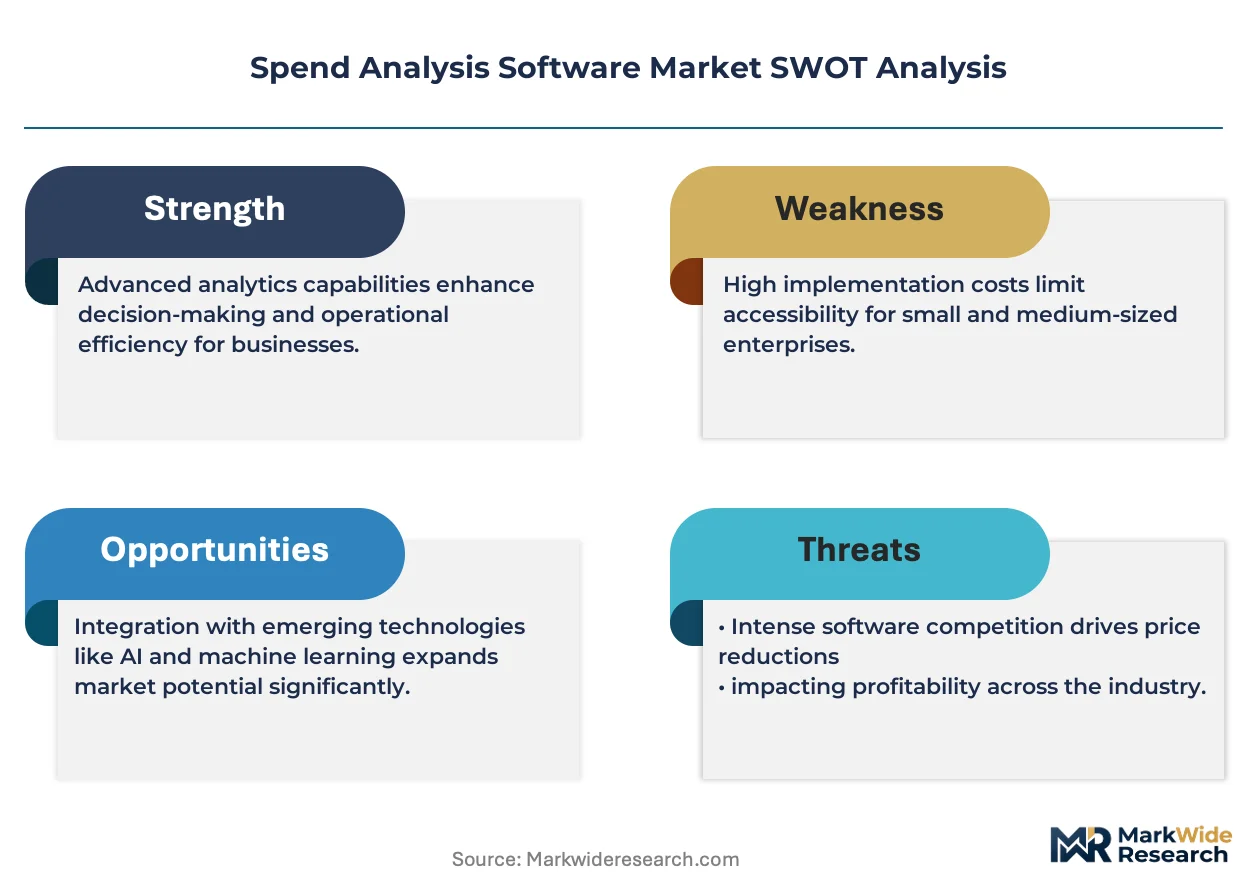
Machine learning classification engines are compressing implementation timelines for spend analysis deployments, forcing vendors to restructure professional services margins around automated onboarding rather than manual taxonomy configuration.
Growth Catalysts
- EU CSRD Mandate:Germany's manufacturing base accelerates procurement analytics adoption to satisfy granular supplier disclosure requirements under the Corporate Sustainability Reporting Directive.
- Cloud Infrastructure Maturation:Mid-market enterprises in the United States leverage serverless architectures to deploy spend visibility platforms without dedicated infrastructure teams.
- Federal Transparency Requirements:The DATA Act compels US agencies to standardize procurement reporting, creating concentrated demand for analytics modules with built-in government accounting compliance.
Market Restraints
- Data Residency Compliance:Defense and financial services segments in France and Germany maintain on-premises installations due to GDPR localization requirements, inflating total cost of ownership versus cloud alternatives.
- Supplier Network Concentration:Critical data ingestion pipelines depend on a narrow set of ERP integration specialists, creating single-point-of-failure exposure during platform migrations.
- Legacy System Inertia:Enterprises running decades-old procurement databases face extraction complexity that delays classification engine training and degrades initial auto-categorization accuracy.
Strategic Opportunities
- EU AI Act Alignment:Algorithmic sourcing transparency requirements create opening for vendors offering explainable AI modules that document classification decision paths for audit defense.
- SMB Channel Expansion:Partner ecosystems targeting sub-500-employee manufacturers in Italy and Spain represent underpenetrated territory where pre-configured industry taxonomies accelerate time-to-value.
- Carbon Accounting Convergence:Integration of spend data with Scope 3 emissions tracking enables platform extensions into sustainability reporting suites for multinational registrants.
Industry Challenges
- Taxonomy Engineering Talent Scarcity:UNSPSC and custom classification schema development requires hybrid procurement-data science expertise that commands premium compensation and extends hiring cycles.
- Multi-Entity Integration Complexity:Conglomerates with dozens of operating subsidiaries face harmonization friction when consolidating disparate chart-of-accounts structures into unified spend visibility layers.
- Certification Timeline Compression:FedRAMP and SOC 2 Type II attestation processes stretch 12-18 months, delaying federal and regulated industry market entry for emerging vendors.
Report Scope
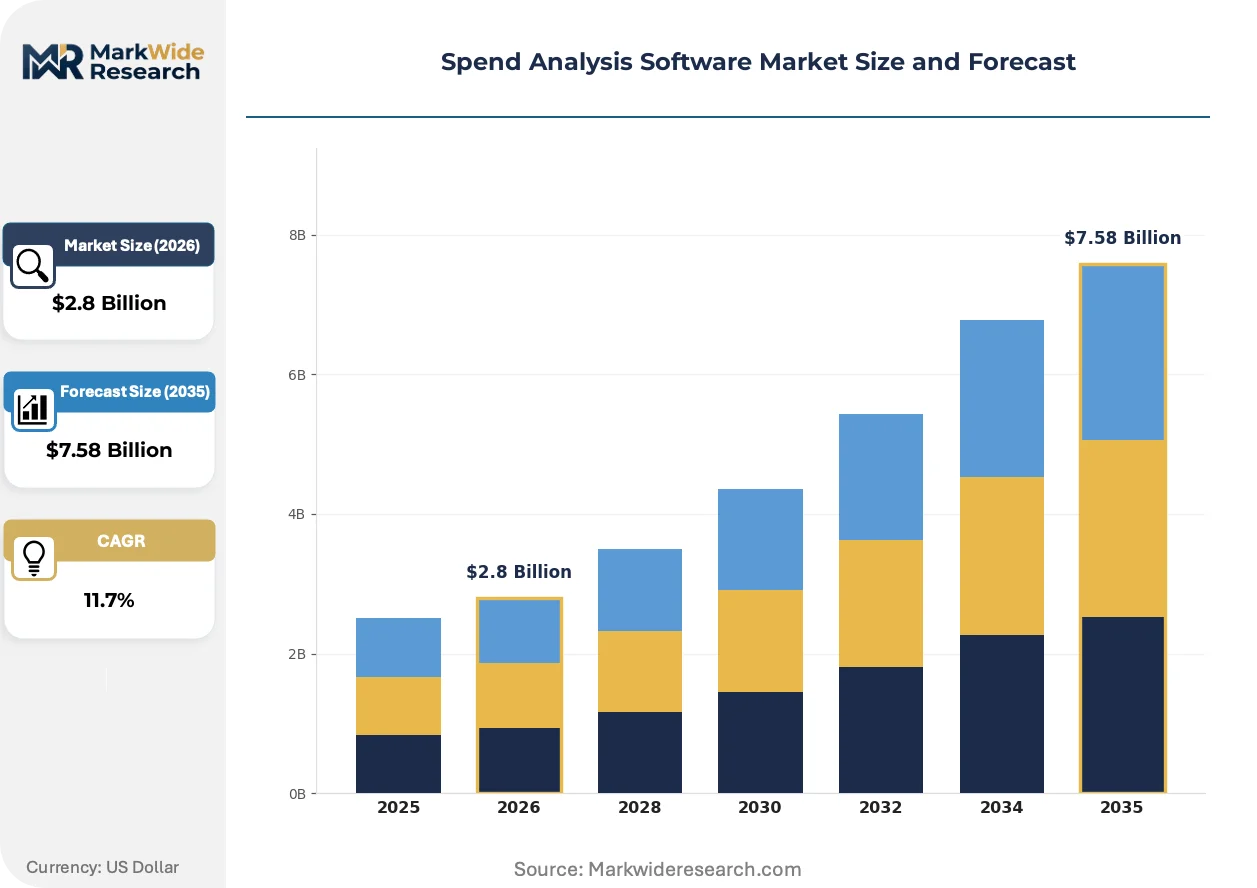
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spend Analysis Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, SaaS End User: Corporates, SMEs, Government, Non-Profit Deployment: Public Cloud, Private Cloud, Managed Services, Dedicated Servers Functionality: Data Visualization, Reporting, Budgeting, Forecasting |
| Companies Covered | GEP, Zycus, Tropic, IBM Emptoris, Sievo, SAP Ariba, Ivalua, Suplari, Coupa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spend Analysis Software Market Strategic Shifts
Generative AI capabilities are restructuring how procurement organizations interact with spend data, shifting from static dashboard consumption to conversational query interfaces that democratize analytics access beyond specialized analysts.
Large language models fine-tuned on procurement terminology are rendering obsolete the traditional services-heavy implementation model where consultants manually mapped supplier names to category hierarchies. Mid-market buyers in the United States now expect 30-day deployment cycles with auto-generated taxonomy suggestions. This compression is collapsing professional services revenue pools and forcing vendors to reprice subscriptions to capture value previously extracted through configuration fees.
REACH substance-of-concern tracking requirements are extending spend analysis scope into chemical composition verification for EU-based manufacturers. The regulation mandates supplier disclosure of SVHC content above threshold limits, compelling platform upgrades that link procurement transactions to material safety data sheets. Automotive and electronics assemblers in Germany and France represent the most affected segments, with procurement teams now requiring real-time compliance scoring alongside cost metrics.
Chief procurement officers are consolidating vendor relationships around integrated source-to-pay suites rather than standalone analytics point solutions. This concentration preference disadvantages specialized spend visibility vendors unless they demonstrate seamless API connectivity with adjacent contracting and supplier management modules. The behavior shift is most pronounced among Fortune 500 industrials in the United States, where procurement leadership seeks to reduce integration maintenance burdens and unify data models across the sourcing lifecycle.
Spend Analysis Software Market Segmentation
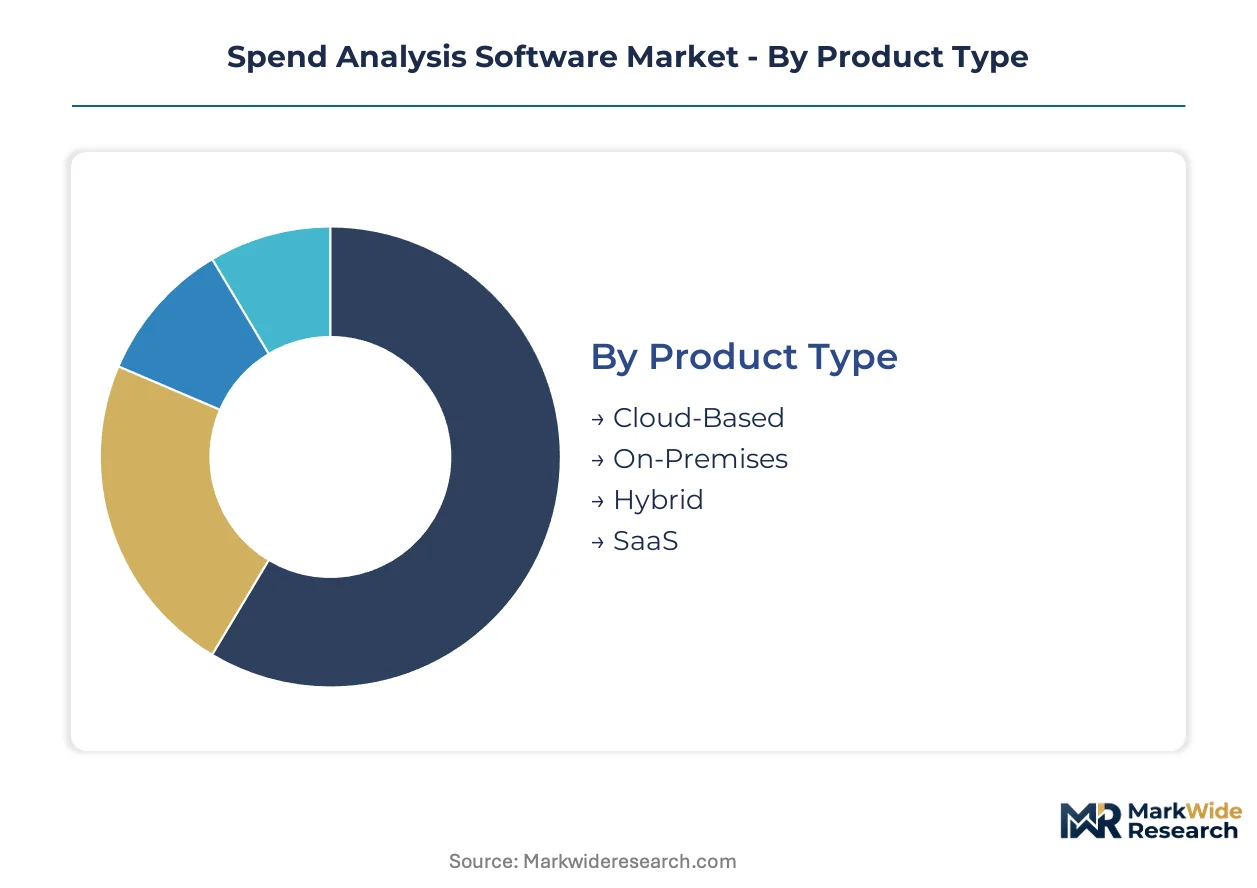
Spend analysis software vendors structure their portfolios across deployment architectures, customer scale, and functional depth to capture divergent buyer requirements. Segmentation discipline separates high-velocity cloud subscriptions from compliance-bound on-premises installations and distinguishes federal procurement workflows from commercial sourcing operations.
Product Type:
Cost tier separates how buyers acquire platform capabilities, with infrastructure ownership models dictating capital allocation patterns and implementation timelines.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute resources eliminate infrastructure procurement cycles. United States mid-market manufacturers favor this tier for 30-day deployment windows without dedicated DevOps staffing.
- On-Premises:Single-tenant installations within buyer-controlled data centers satisfy GDPR localization mandates and defense-sector security protocols. German automotive suppliers and French financial institutions maintain this tier despite elevated total cost of ownership.
- Hybrid:Split configurations route sensitive supplier data through on-premises nodes while pushing analytics workloads to elastic cloud infrastructure. Conglomerates with mixed regulatory exposure across operating subsidiaries deploy this architecture.
- SaaS:Fully managed subscription models with standardized taxonomy templates accelerate time-to-value for procurement teams lacking data science resources. Italian and Spanish manufacturers under 500 employees represent concentrated adoption.
Cloud-Based holds installed capacity. SaaS is rotating up the share rankings.
End User:
Customer type determines functional complexity requirements, integration scope, and procurement cycle length across the buyer base.
- Corporates:Fortune 500 industrials demand multi-entity consolidation across dozens of ERP instances and custom chart-of-accounts harmonization. These buyers generate the highest professional services attach rates due to taxonomy engineering complexity.
- SMEs:Sub-500-employee organizations prioritize pre-configured industry templates and rapid implementation over customization. Partner ecosystems targeting manufacturers in Italy and Spain concentrate demand generation for this segment.
- Government:Federal agencies require FedRAMP-authorized platforms with built-in compliance for DATA Act reporting and FAR procurement regulations. Renewal rates exceed commercial benchmarks given lengthy certification cycles and switching costs.
- Non-Profit:Grant-funded organizations with constrained IT budgets favor lightweight visualization modules over comprehensive sourcing suites. Donor transparency requirements drive basic spend visibility adoption without advanced predictive capabilities.
Corporates command the revenue concentration. SMEs are expanding most quickly through channel partnerships.
Deployment:
Infrastructure control level shapes security posture, operational overhead, and geographic data placement for regulated industries.
- Public Cloud:Shared infrastructure pools from hyperscale providers deliver cost efficiency for non-sensitive procurement analytics. United States technology and retail sectors dominate consumption with serverless architectures.
- Private Cloud:Dedicated virtual environments within buyer-managed or colocation facilities balance elasticity with data residency. German manufacturers responding to CSRD supplier disclosure mandates favor this deployment for audit trail isolation.
- Managed Services:Third-party operations teams handle platform maintenance, security patching, and taxonomy updates under outcome-based contracts. Buyers lacking procurement-IT hybrid expertise outsource operational complexity.
- Dedicated Servers:Physical hardware assignments satisfy air-gapped requirements for defense contractors and intelligence community procurement systems. France maintains this tier for military supplier networks under national security protocols.
Public Cloud holds installed capacity. Private Cloud is gaining share fastest through EU regulatory pressure.
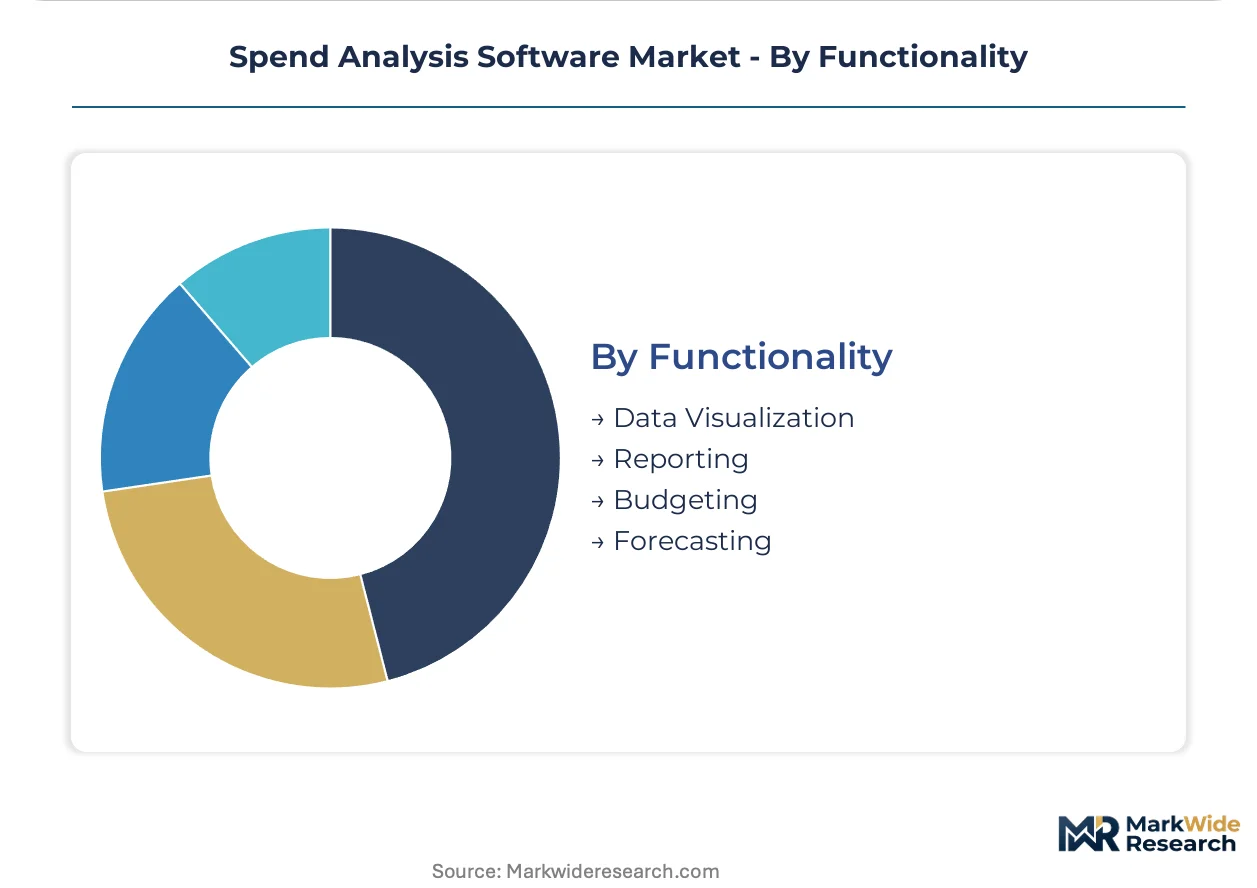
Functionality:
Application depth distinguishes visualization-centric buyers from those requiring predictive and prescriptive procurement capabilities.
- Data Visualization:Interactive dashboards with drill-down supplier hierarchies and commodity-level spend heat maps form the baseline capability. Most SME and non-profit implementations terminate at this functional layer.
- Reporting:Automated generation of compliance documentation for CSRD, DATA Act, and internal audit requirements. Government and corporate buyers mandate standardized report templates with scheduled distribution.
- Budgeting:Integration of historical spend patterns with procurement planning cycles to enforce category-level spending guardrails. Manufacturing enterprises with material cost volatility prioritize this module.
- Forecasting:Machine learning models projecting supplier pricing trends, currency exposure, and demand fluctuations. Advanced corporate buyers and financial services procurement teams deploy predictive capabilities for hedging decisions.
Data Visualization holds installed capacity. Forecasting is rotating up the share rankings through generative AI integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal agencies deploy spend analysis platforms primarily for DATA Act compliance, while German manufacturers prioritize supplier carbon disclosure under CSRD—revealing a transatlantic split between transparency mandates and sustainability integration.
United States
Mid-market manufacturers in Michigan and Ohio accelerate cloud-based procurement analytics adoption to compress implementation timelines. The DATA Act and FAR procurement regulations enforce standardized federal spend reporting, creating concentrated demand for government-compliant analytics modules. Chicago-based industrial conglomerates consolidate multi-entity ERP instances through private cloud deployments to satisfy data residency requirements while maintaining analytics elasticity.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg upgrade platforms to capture granular supplier emissions data for CSRD disclosures. The EU AI Act's emerging algorithmic sourcing guidelines prompt procurement teams to demand explainable classification engines. Stuttgart's manufacturing clusters integrate REACH substance tracking into spend analysis workflows, linking procurement transactions to material safety documentation.
France
Defense contractors and financial institutions in Paris and Île-de-France maintain on-premises installations under strict GDPR localization protocols. The CNIL enforces supplier data governance standards that extend platform compliance requirements beyond procurement analytics into vendor risk management. Lyon-based aerospace suppliers deploy hybrid architectures to isolate sensitive military supplier networks while pushing cost analytics to cloud infrastructure.
United Kingdom
London-headquartered financial services firms adopt spend visibility platforms to streamline post-Brexit supplier due diligence across divergent regulatory regimes. The UK Competition and Markets Authority's procurement transparency guidelines pressure public sector bodies to upgrade legacy reporting systems. Manchester's public sector technology clusters demonstrate concentrated adoption of FedRAMP-equivalent cloud security frameworks for government analytics deployments.
India
IT services exporters in Bengaluru and Hyderabad deploy spend analysis tools to manage distributed global delivery center procurement across multiple currencies and tax jurisdictions. The RBI's data localization requirements for financial transaction records influence hybrid deployment decisions among Mumbai-based banking procurement teams. Pune's manufacturing SMEs access pre-configured industry taxonomies through channel partner ecosystems, accelerating time-to-value without dedicated data science staffing.
Spend Analysis Software Market Competitive Environment
Capability concentration sits with specialized taxonomy engineering vendors; scale advantage sits with integrated source-to-pay suite providers. The vendor landscape organizes into three functional tiers: native AI platforms, network-centric commerce layers, and configurable multi-entity engines. Consolidation pressure intensifies as procurement leaders prioritize unified data models over standalone analytics point solutions. Strategic moves center on API connectivity investments and pre-built ERP connector libraries that reduce implementation friction.
Within the native AI tier, GEP and Sievo exemplify vendors compressing professional services margins through automated classification onboarding. SAP Ariba occupies a position anchoring network-based supplier discovery through embedded commerce infrastructure. Ivalua represents the configurable engine archetype, sustaining complex deployments across conglomerates with disparate chart-of-accounts structures. Zycus and Coupa sit within the expanding mid-market channel, targeting rapid-deployment subscriptions for procurement teams lacking dedicated taxonomy engineering resources.
| Leading Market Players |
|---|
| GEP |
| Zycus |
| Tropic |
| IBM Emptoris |
| Sievo |
| SAP Ariba |
| Ivalua |
| Suplari |
| Coupa |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure concentration in the United States anchors margin pools for hyperscale compute providers, compressing downstream pricing flexibility for SaaS vendors serving mid-market procurement teams. This upstream control forces spend analysis platforms to absorb infrastructure cost volatility through subscription repricing rather than pass-through mechanisms.
Pricing Analysis
Contract structures stratify across annual subscriptions, multi-year enterprise agreements, and consumption-based usage tiers. Pricing differentiation rests on deployment complexity and taxonomy customization depth, with Fortune 500 buyers accepting premium tiers for multi-entity harmonization while sub-500-employee manufacturers gravitate toward standardized SaaS packages. Cost compression in the mid-market segment intensifies as generative AI collapses implementation timelines and eliminates professional services attach revenue. Government end users exhibit lowest price sensitivity given FedRAMP certification barriers and compliance-driven renewal mandates.
Supply Chain Analysis
Upstream feedstock for spend analysis platforms draws from cloud compute services concentrated in the United States, Ireland, and Singapore, with data center capacity expansion in Frankfurt and Amsterdam serving EU data residency requirements. Critical dependencies include GPU clusters for machine learning training, ERP connector libraries for data ingestion, and pre-trained language models for auto-classification. Single-source vulnerability runs through narrow sets of systems integration specialists capable of SAP and Oracle ERP extraction. Distribution runs through direct enterprise sales teams for large accounts and channel partner networks for SME penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI integration is disrupting competitive positioning across the spend analysis landscape, compressing implementation timelines and collapsing traditional services revenue pools. The EU AI Act's emerging algorithmic transparency mandates add regulatory velocity to this technological inflection.
For Market Incumbents: Build data moats through proprietary supplier network graphs that accumulate relationship intelligence beyond raw transaction records. Incumbents must consolidate API connectivity investments to defend against suite providers absorbing standalone analytics into source-to-pay platforms. SAP Ariba's embedded commerce infrastructure and Ivalua's multi-entity deployment expertise represent defensible positions against mid-market challengers. Taxonomy engineering talent retention becomes critical as automated classification erodes implementation service margins. For New Entrants and Emerging Players: Establish a beachhead in the Italian and Spanish manufacturing SME segment where pre-configured industry taxonomies accelerate time-to-value without dedicated data science staffing. REACH compliance tracking for chemical substance verification offers white-space expansion as EU manufacturers link procurement transactions to material safety documentation. Channel partnership strategies with regional ERP implementers reduce customer acquisition costs versus direct field sales investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed spend visibility specialists that have plateaued at mid-market scale without clear path to enterprise consolidation. Long-term viability in this market hinges on platform extension into adjacent supplier risk management and carbon accounting modules. The signal to watch is FedRAMP authorization timelines, as certification compression indicates vendor readiness for government procurement cycles with above-average renewal rates.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Module Integration | Conversational query interfaces from GEP and Sievo democratize analytics access beyond specialized procurement analysts. |
| EU AI Act Compliance Layer | Explainable classification engines document decision paths for audit defense under emerging algorithmic sourcing guidelines. |
| Carbon Accounting Convergence | Scope 3 emissions tracking extensions capture CSRD-driven platform upgrades among German automotive suppliers. |
| ERP Connector Library Expansion | Pre-built SAP and Oracle integrations reduce implementation friction for conglomerates consolidating multi-entity deployments. |
| FedRAMP Authorization Acceleration | Government-compliant modules unlock concentrated demand from US federal agencies under DATA Act transparency mandates. |
Study Parameters
Cross-validation between primary interviews with procurement technology vendors and secondary analysis of hyperscaler capex disclosures anchors the qualitative findings. Chief procurement officers, platform engineering leads, ERP integration specialists, and channel partner managers contributed structured input across the United States, Germany, France, and India. Secondary sources include SEC 10-K filings, EU regulatory impact assessments, cloud infrastructure expenditure reports, and government procurement databases. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates.
Calibration against historical adoption curves for cloud-based procurement technology shapes the projection framework across the analysis window. Segmentation dimensions include deployment architecture, organization scale, functional depth, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for compliance mandate timing and AI capability maturation. Forecast inputs incorporate FedRAMP certification pipeline visibility and CSRD implementation phase transitions.
Macroeconomic conditions sit as an overlay; deviation in cloud infrastructure pricing or enterprise software procurement cycles would shift the trajectory. Forecasts reflect documented assumptions about generative AI adoption velocity and regulatory enforcement intensity. Cross-checking against hyperscaler revenue disclosures and government IT spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Harbor and Marina Management Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Global Student Information System Market
Software & Services
Compositing Software Market
Software & Services
Change Control Management Software Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
BFSI Software Market
Software & Services
Embroidery Design Software Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Data Exchange Platform Services Market
Software & Services
Sports League Management Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
Shift Planning Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Global AI Writing Assistant Software Market
Software & Services
Client Virtualization Software Market