
 Innerspring Mattresses Market | 2026-2036
Innerspring Mattresses Market Size, Share, and Industry Trends Forecast 2026-2036
Innerspring Mattresses Market Foresight
The EU Green Deal is rebalancing material sourcing priorities across European bedding supply chains. Serta leverages captive foam and coil production networks to stabilize input costs across North American plants. Tempur-Sealy International anchors its competitive position through hybrid innerspring-memory foam architectures that command premium placement. Saatva differentiates via direct-to-consumer logistics infrastructure that compresses delivery timelines for coil-based products.
An innerspring mattress employs a core support system of steel coils—typically tempered carbon steel wire ranging from 12 to 18 gauge—arranged in open, pocketed, continuous, or offset configurations, topped with comfort layers of polyurethane foam, fiber, or latex to distribute body weight and maintain spinal alignment during sleep. Pocketed coil assemblies isolate motion transfer more effectively than continuous wire systems, positioning them as the fastest-growing product type for couples and light sleepers. Queen size dominates volume throughput across wholesale and retail channels, while firm and medium comfort levels capture the widest demographic overlap between aging consumers seeking orthopedic support and younger buyers prioritizing value positioning.
The US Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability standards, while the EPA monitors volatile organic compound emissions from polyurethane foam adhesives used in coil-to-comfort-layer bonding; both frameworks elevate compliance costs for imports and domestic manufacturers alike. California's Bureau of Household Goods and Services maintains additional labeling requirements that shape product disclosure obligations for brands selling into the state. Stakeholders must monitor evolving state-level chemical restriction bills and third-party certifier influence over retailer shelf access decisions.
Market Dynamics
Replacement cycle compression in the hospitality sector is accelerating demand volatility, as mid-scale hotel chains stretch innerspring mattress refresh intervals from five to seven years while premium properties compress theirs to three years.
Growth Catalysts
- Hospitality refurbishment cycles:Mid-scale hotel chains in the United States are accelerating room renovation programs, driving bulk procurement of queen-size pocketed coil units.
- 16 CFR Part 1633 compliance infrastructure:Certified barrier fabric technologies are becoming mandatory for domestic manufacturing and import clearance, creating pull-through demand for compliant coil assemblies.
- Hybrid comfort architectures:Pocketed coil systems layered with memory foam or latex are capturing preference share among couples prioritizing motion isolation.
Market Restraints
- Steel wire input volatility:Tempered carbon steel coil stock fluctuates with scrap metal and energy pricing, compressing margin predictability for coil manufacturers.
- Polyurethane foam adhesive emissions:EPA volatile organic compound monitoring adds compliance overhead to coil-to-comfort-layer bonding operations.
- Compressed foam mattress substitution:All-foam bed-in-a-box products are displacing coil-based units in entry-level price tiers among urban millennials.
Strategic Opportunities
- EU Green Deal material sourcing:European bedding supply chains are rebalancing toward recycled steel and bio-based comfort layers, opening certification-driven premium positioning.
- Direct-to-consumer logistics compression:Coil-based products are penetrating online channels through vacuum-compression packaging innovations that reduce last-mile costs.
- California Bureau of Household Goods labeling:Enhanced disclosure requirements are creating first-mover advantage for brands investing in supply chain transparency infrastructure.
Industry Challenges
- Flammability certification timelines:Third-party laboratory testing for 16 CFR Part 1633 compliance extends new product development cycles by eight to fourteen weeks.
- Coil gauge standardization friction:Inconsistent regional preferences between 12-gauge firm support and 15-gauge plush configurations complicate inventory pooling across distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Innerspring Mattresses Market |
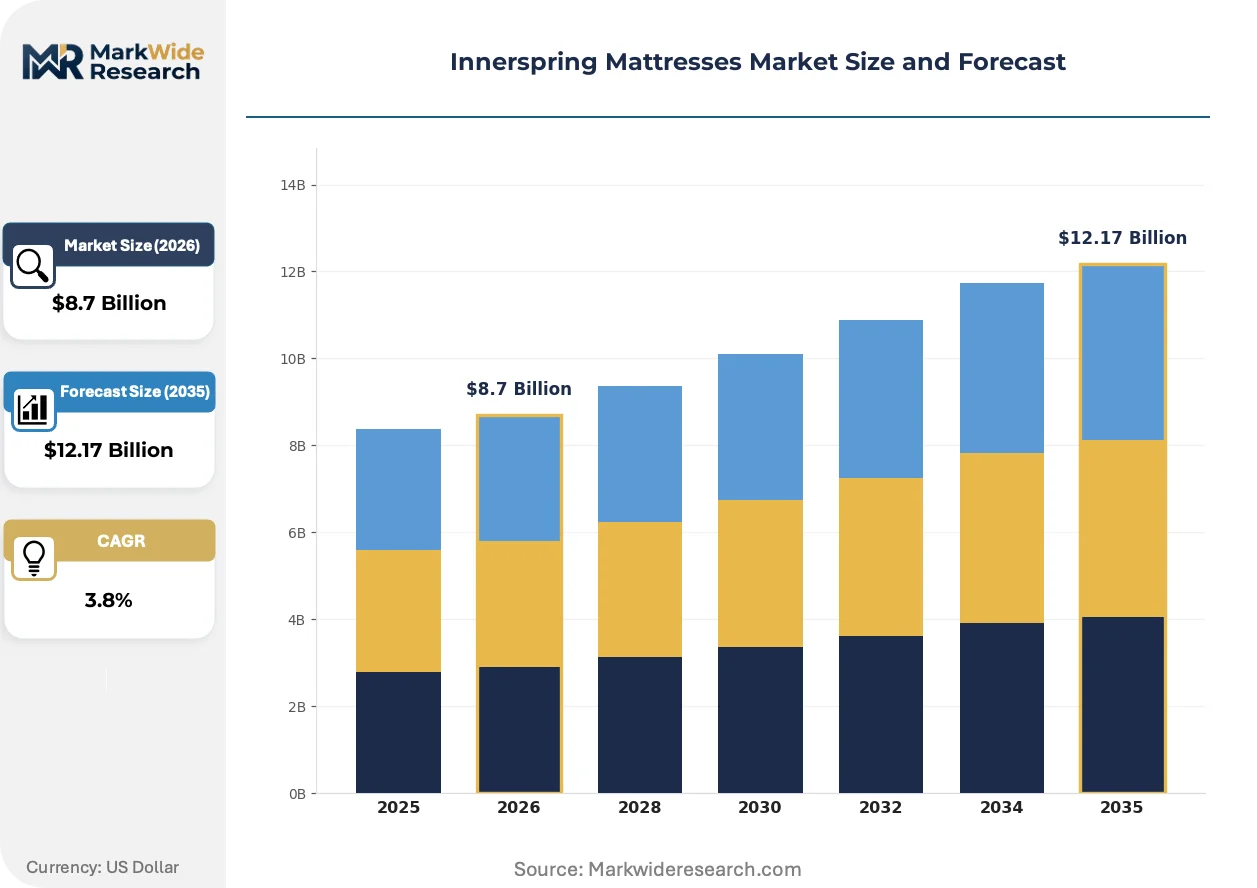
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Pocketed Coil, Continuous Wire, Offset Coil Size: Twin, Full, Queen, King Comfort Level: Firm, Medium, Plush, Extra Firm Distribution Channel: Online Retail, Brick-and-Mortar, Wholesalers, Direct-to-Consumer |
| Companies Covered | Serta, Tempur-Sealy International, Saatva, Brooklyn Bedding, Serta Simmons Holdings, Stearns & Foster, Sealy, WinkBeds, Beautyrest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Innerspring Mattresses Market Shifts & Advancements
Material convergence and regulatory disclosure requirements are restructuring how coil systems are specified, sourced, and sold across wholesale and direct channels.
Pocketed coil assemblies are integrating zoned support geometries that vary wire gauge across lumbar, shoulder, and hip regions. Hospitality procurement teams specify these architectures for extended-stay properties where guest retention correlates with sleep quality scores. The technology is integrating orthopedic segmentation into mid-market price tiers previously served by uniform continuous-coil designs.
California's Bureau of Household Goods and Services maintains labeling mandates that exceed federal baseline disclosure, requiring component origin documentation and recycled content percentages. Manufacturers selling into the state must reconfigure supply chain traceability systems or forfeit shelf access at major retail partnerships. Private-label distributors are consolidating supplier bases to reduce compliance fragmentation.
Hotel asset managers are unbundling mattress procurement from furniture packages, issuing standalone RFPs for sleep surfaces with specified durability testing. This purchasing pattern shift is compressing vendor selection timelines while elevating technical specification weighting in award decisions. Procurement teams in the southeastern United States are piloting outcome-based contracts tying payment to guest satisfaction score thresholds.
Innerspring Mattresses Market Segmentation
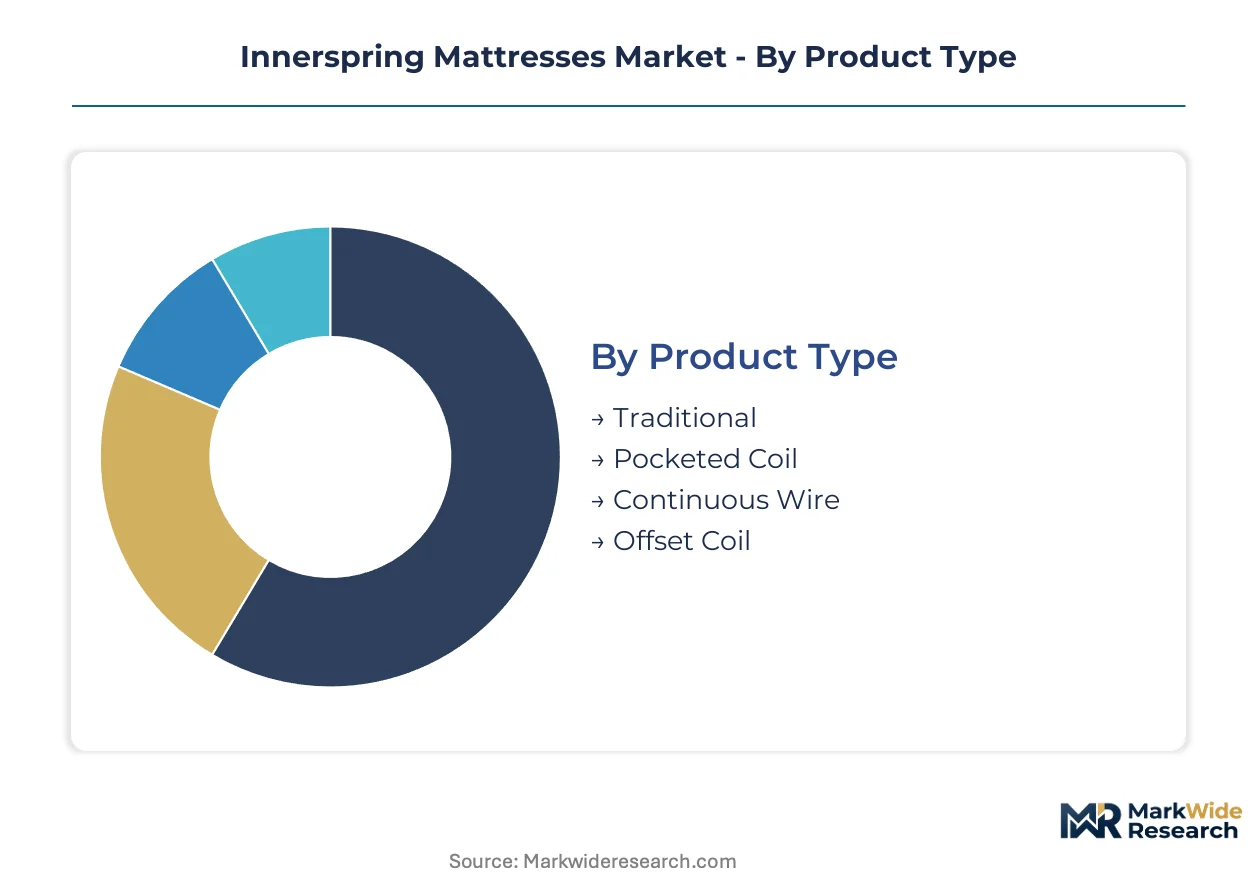
Coil architecture and comfort calibration determine margin structure across wholesale and direct channels. Procurement patterns diverge sharply between hospitality volume buyers and retail consumers prioritizing individualized sleep surfaces.
Product Type:
Volume throughput concentrates in legacy continuous-wire configurations, while premium positioning shifts toward motion-isolating assemblies.
- Pocketed Coil:Individual fabric-wrapped springs operate independently to dampen partner disturbance. Hospitality procurement teams at extended-stay properties specify these units for guest retention metrics. The architecture commands placement in hybrid mattress lines combining steel support with memory foam comfort layers.
- Continuous Wire:A single helical wire snakes through the entire support matrix, reducing manufacturing complexity and material waste. Bulk contracts with mid-scale hotel chains in the southeastern United States favor this construction for five-to-seven-year replacement cycles. The design sacrifices motion isolation for cost efficiency at entry price tiers.
- Traditional:Open coil systems with hourglass-shaped springs wired together at the top and bottom represent the historical baseline. Rural markets and value-oriented furniture retailers maintain stocking positions for price-sensitive demographics.
- Offset Coil:Hinged wire segments conform to body contours while preserving edge support integrity. Specialty orthopedic retailers specify these configurations for customers seeking targeted lumbar reinforcement.
Mature deployment sits with Continuous Wire. Newer deployment is concentrated in Pocketed Coil.
Size:
Hospitality standardization drives volume concentration in mid-range dimensions, while residential trade-up patterns favor expansive sleeping surfaces.
- Queen:The dominant throughput dimension across wholesale distribution and retail furniture galleries. Hotel asset managers specify queen units for standardized room configurations, compressing vendor selection timelines through volume commitments.
- King:Split and standard configurations capture residential master bedroom renovations. California's Bureau of Household Goods and Services labeling mandates apply to these higher-ticket units, elevating supply chain transparency requirements for brands selling into the state.
- Twin:Narrow dimensions serve institutional contracts for university housing and military barracks. Procurement runs through specialized contract furniture distributors rather than consumer-facing retail.
- Full:Transitional sizing for adolescent bedrooms and guest room applications. Inventory pooling challenges arise from regional preference variation between this dimension and queen upgrades.
Volume leadership rests with Queen. Margin expansion concentrates in King.
Comfort Level:
Demographic overlap between aging consumers and younger buyers creates bifurcated demand across support gradients.
- Medium:The widest addressable range, balancing pressure relief with spinal alignment for average-weight sleepers. Private-label retail partnerships with regional distributors deepen around this specification as a safe default recommendation.
- Firm:Orthopedic positioning captures aging consumers seeking structural support. The 16 CFR Part 1633 flammability compliance infrastructure applies uniformly across comfort gradients, though firmer constructions with denser foam layers face elevated adhesive emission monitoring from the EPA.
- Plush:Thicker comfort layer stacks prioritize pressure point cushioning. Urban millennials exploring innerspring alternatives to compressed foam mattresses trial this specification through direct-to-consumer channels.
- Extra Firm:Minimal comfort layer depth serves specific medical recommendations and back-sleeping preferences. Distribution concentrates through healthcare-adjacent retailers and chiropractic clinic partnerships.
Mass-market penetration peaks with Medium. Differentiation investment flows toward Firm.
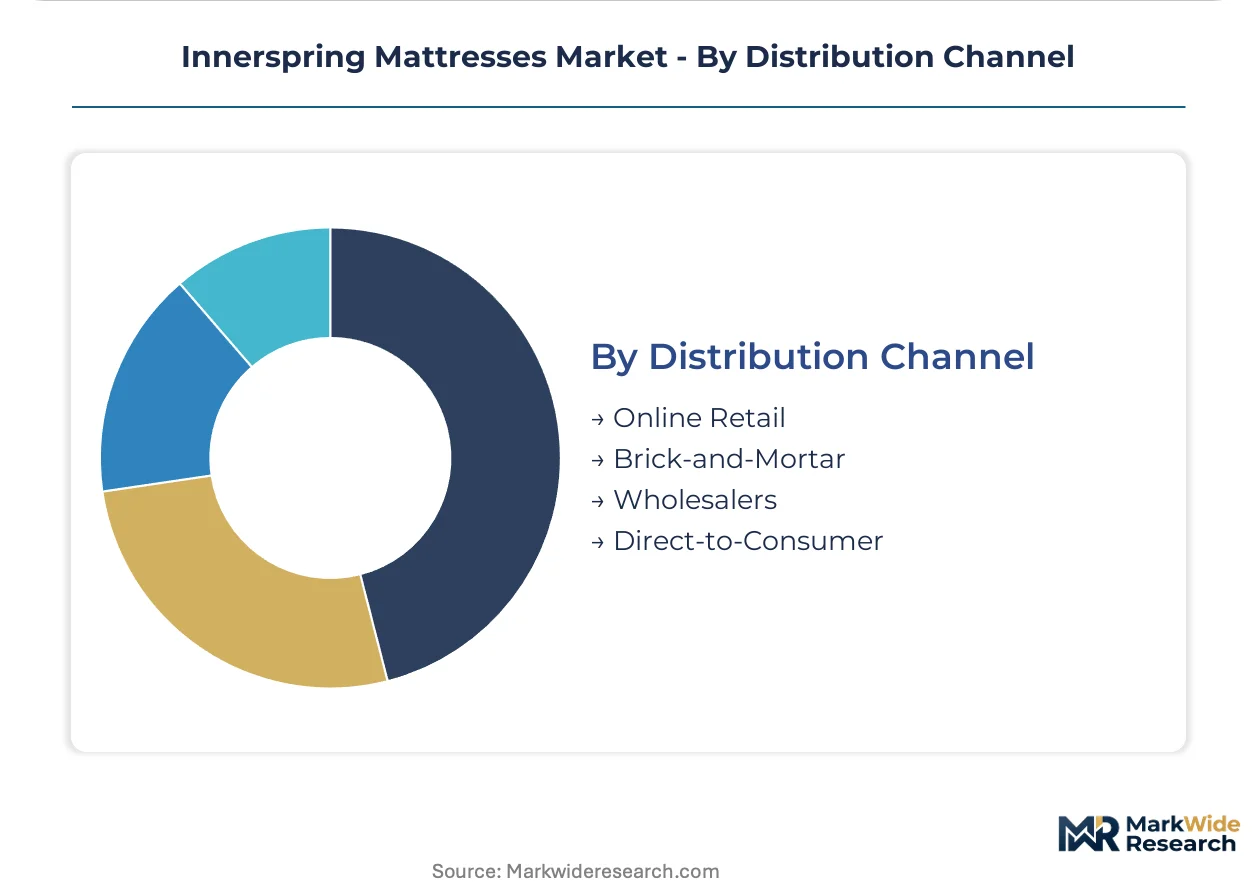
Distribution Channel:
Logistics compression and regulatory disclosure requirements are restructuring how coil systems reach end users.
- Brick-and-Mortar:Furniture galleries and mattress specialty stores maintain tactile trial infrastructure. The channel bears compliance overhead from California's Bureau of Household Goods and Services labeling mandates that shape product disclosure obligations.
- Direct-to-Consumer:Vacuum-compression packaging innovations reduce last-mile freight costs for coil-based products previously excluded from e-commerce. Saatva's logistics infrastructure demonstrates delivery timeline compression for this category.
- Wholesalers:Hospitality procurement teams unbundle mattress selection from furniture packages, issuing standalone RFPs through this channel. Outcome-based contracts tying payment to guest satisfaction scores are piloting in the southeastern United States.
- Online Retail:Marketplace platforms aggregate comparison shopping for standardized specifications. The channel faces substitution pressure from compressed all-foam bed-in-a-box products at entry price tiers.
Established volume flows through Brick-and-Mortar. Channel expansion is accelerating fastest in Direct-to-Consumer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States while consumption spreads across developed economies with distinct regulatory frameworks. Production tilts toward coil fabrication and foam layering in North American plants, with distribution networks extending to hospitality and retail channels worldwide.
United States
Mid-scale hotel chains in the southeastern states stretch replacement cycles to seven years, compressing bulk procurement volumes. The US Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability standards that elevate barrier fabric costs for domestic and imported units alike. Charlotte, North Carolina hosts concentrated coil assembly operations serving hospitality RFPs with standardized queen configurations.
Germany
EU Green Deal mandates are redirecting material sourcing toward recycled steel and bio-based comfort layers for premium positioning. ECHA REACH compliance adds documentation overhead to polyurethane foam adhesive imports used in coil-to-comfort-layer bonding. The North Rhine-Westphalia industrial corridor maintains specialized machinery fabrication for pocketed coil assembly equipment.
China
Domestic mattress demand from urban middle-class households is shifting toward hybrid architectures combining steel support with memory foam. SAMR quality supervision and GB standards for furniture flammability shape export-ready production lines. The Yangtze River Delta concentration serves as the primary coil wire and foam chemical supply hub for Asia-Pacific bedding manufacturers.
Canada
Health Canada and PMRA monitoring of volatile organic compound emissions from foam adhesives parallels EPA frameworks, creating compliance alignment with US suppliers. Private-label retail partnerships with regional distributors are deepening in Ontario and Quebec markets. The Toronto-Waterloo corridor hosts compressed packaging logistics innovations for direct-to-consumer coil mattress delivery.
United Kingdom
Post-renovation residential demand in London and the Southeast is driving trade-up patterns toward king-size hybrid units. The UK's national furniture flammability regulations, derived from EU legacy frameworks, maintain stringent barrier requirements for domestic sale. Midlands manufacturing clusters specialize in offset coil configurations for orthopedic specialty retailers.
Innerspring Mattresses Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive coil and foam production networks. Tiered positioning separates premium hybrid architects from value-oriented continuous-coil suppliers serving hospitality bulk contracts. Two dominant archetypes occupy the landscape: vertically integrated specialists controlling upstream wire and foam inputs, and direct-to-consumer brands compressing delivery logistics through vacuum-compression packaging. Competitive moves concentrate on M&A consolidation of regional distributors and strategic partnerships with third-party certifiers for flammability compliance.
Among North American integrated manufacturers, Serta and Tempur-Sealy International exemplify the captive production archetype with in-house coil and foam operations stabilizing input costs. Saatva occupies a position within the direct-to-consumer logistics tier, demonstrating delivery timeline compression for coil-based products through specialized fulfillment infrastructure. These three anchors illustrate how scale-driven supply control and channel-specific operational excellence define sustainable positioning in a market facing steel volatility and regulatory compliance pressures.
| Leading Market Players |
|---|
| Serta |
| Tempur-Sealy International |
| Saatva |
| Brooklyn Bedding |
| Serta Simmons Holdings |
| Stearns & Foster |
| Sealy |
| WinkBeds |
| Beautyrest |
| Others |
Supply & Pricing Matrix
Captive coil and foam production networks anchor both supply resilience and pricing power for integrated manufacturers serving North American hospitality and retail channels. Serta's in-house wire tempering and polyurethane foam operations insulate margin structures from steel scrap volatility and adhesive emission compliance costs that compress independent assemblers.
Pricing Analysis
Margin tightening in continuous-wire configurations reflects stretched replacement cycles among mid-scale hotel chains extending refresh intervals to seven years. Three-tier pricing structure across premium hybrid, standard pocketed coil, and economy continuous-wire levels segments buyer sensitivity, with hospitality procurement teams most price-responsive and direct-to-consumer shoppers least. Certification grade for 16 CFR Part 1633 flammability compliance and volume scale in bulk queen-size contracts drive price differentiation across tiers.
Supply Chain Analysis
Workforce availability in coil fabrication clusters Charlotte, North Carolina and the Yangtze River Delta against emerging assembly operations in Mexico's northern border states. Tempered carbon steel wire, polyurethane foam chemicals, and certified barrier fabrics constitute critical input dependencies. Single-source vulnerability in pocketed coil assembly equipment from Germany's North Rhine-Westphalia corridor elevates supply risk. Distribution runs through hospitality-focused wholesalers, furniture gallery retail networks, and compressed-logistics direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated manufacturers with captive input production as steel volatility and flammability compliance costs force out independent assemblers lacking scale.
For Market Incumbents: Anticipate compressed foam mattress substitution by securing hybrid architecture patents and expanding captive foam production capacity. Defend hospitality relationships through outcome-based contract pilots tying payment to guest satisfaction thresholds. Certification investment in California Bureau of Household Goods labeling infrastructure creates shelf-access moats against regional distributors consolidating supplier bases. For New Entrants and Emerging Players: Begin with orthopedic specialty retail channels where offset coil configurations for lumbar support command premium positioning absent from mass-market saturation. Target extended-stay hospitality properties specifying zoned pocketed coil geometries for guest retention metrics. Direct-to-consumer logistics compression through vacuum-packaging partnerships offers the most penetrable go-to-market angle against established wholesale relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated manufacturers seeking regional distributor consolidation and flammability certification assets. Long-term viability favors vertically integrated specialists with captive steel wire and foam operations over pure-play assemblers exposed to input volatility. Watch for SAMR quality supervision tightening in China as inflection signal for export-ready production line reconfiguration costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Wire Production | Captive tempering operations insulate Serta and Tempur-Sealy from scrap metal volatility compressing coil assembler margins. |
| Flammability Certification Infrastructure Investment | 16 CFR Part 1633 barrier fabric testing capabilities extend new product development cycles by eight to fourteen weeks, favoring scaled laboratories. |
| Direct-to-Consumer Logistics Compression | Saatva's vacuum-compression packaging innovations reduce last-mile freight costs for coil-based products previously excluded from e-commerce channels. |
| Hybrid Architecture Patent Development | Pocketed coil-memory foam combinations command premium placement as couples prioritize motion isolation in master bedroom renovations. |
| Hospitality Outcome-Based Contracting | Southeastern United States asset managers pilot payment structures tied to guest satisfaction score thresholds, elevating technical specification weighting. |
Research Methodology
Independent corroboration across hospitality procurement directors, foam chemical supply managers, and flammability testing laboratory executives underwrites the qualitative findings in this study. Primary interviews with mattress specialty retail buyers, regional distributor operations heads, and coil assembly plant managers combined with secondary validation from US Consumer Product Safety Commission guidance documents, EPA volatile organic compound monitoring reports, and California Bureau of Household Goods labeling mandates. Bottom-up shipment data from furniture gallery channels and top-down steel wire consumption estimates triangulate volume figures.
Rate-of-change decomposition across coil architecture type, comfort level calibration, size dimension, and distribution channel structure models expansion trajectories throughout the forecast period. CAGRs derive from regression analysis against hospitality renovation spending indices and residential furniture replacement cycle surveys. Industry-specific forecast inputs include mid-scale hotel chain capital expenditure patterns and direct-to-consumer mattress category penetration rates in urban millennial demographics.
Steel scrap price volatility, state-level chemical restriction legislation, and compressed foam mattress substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding flammability certification timeline stability and hospitality unbundling trends. Material deviation in named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Car Air Freshener Market
Household Items
Sleeping Pods Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Middle East and Africa Robotic Vacuum Cleaner Market
Household Items
Portable Steam Cleaners Market
Household Items
Thermos Drinkware Market
Household Items
Pet Safe Cleaners Market
Household Items
Toilet Deodorant Market
Household Items
Flatware Market
Household Items
Europe Handheld Fans Market
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Latex Mattress Market
Household Items
Europe Digital Showers Market
Household Items
Europe Handheld Vacuum Cleaners Market