
 Europe Coin-Operated Laundries Market | 2026-2036
Europe Coin-Operated Laundries Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coin-Operated Laundries Market Intelligence
Revenue from digital payment solutions and subscription-based services is tilting the profit pool away from traditional coin-only machine sales. Major equipment manufacturers like Girbau are integrating advanced digital interfaces into their new machine lines. Meanwhile, specialized service operators such as Johnson Service Group PLC leverage network density and full-service offerings to capture recurring revenue streams in the UK market. Elis positions itself as a multi-service provider, embedding laundry within a broader facilities management context, particularly in France.
Europe's coin-operated laundries encompass self-service facilities equipped with commercial-grade washing machines and dryers activated by physical currency or digital payments. These machines are engineered for high-usage cycles, often featuring stainless steel drums and heavy-duty motors to withstand continuous operation. While self-service laundromats remain the dominant end-user segment, on-demand and subscription service types are gaining traction among urban professionals. The technology segment shows a clear shift, with new installations heavily favoring energy-efficient models and those with integrated digital payment solutions over purely electromechanical systems.
Equipment sold within the European Union must conform to CE marking standards, ensuring safety and operational compliance. The EU's Ecodesign Directive and energy labeling regulations are pushing manufacturers toward producing more water- and energy-efficient washing machines and dryers. Facility operators must decide whether to invest in retrofitting existing locations with digital payment systems or focus on expanding into underserved residential areas in secondary European cities.
Market Dynamics
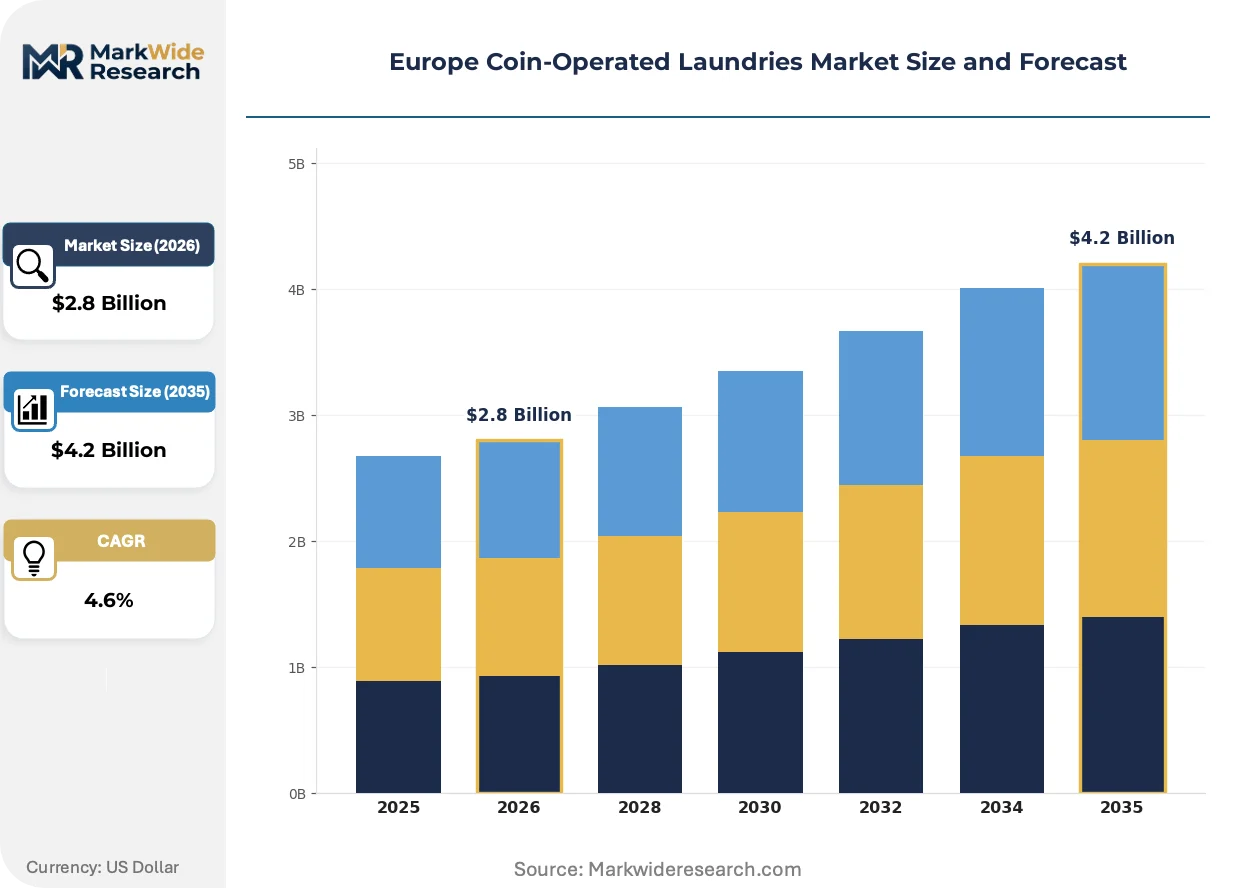
The central force is the convergence of digital payment technology with demand for convenience in high-density urban housing. This transition redefines the laundromat from a coin-operated utility to a digitally managed service, altering revenue models and operational priorities.
Growth Catalysts
- Urbanization Patterns:High-density multi-family residential units and student housing complexes in cities like Berlin and Paris create concentrated clusters of demand, making new laundromat installations economically viable.
- Digital Payment Proliferation:The widespread adoption of contactless and mobile payment solutions meets consumer expectations for convenience and enables operators to implement dynamic pricing and remote management.
- Ecodesign Directive:EU regulations mandating higher energy and water efficiency for appliances create a compelling replacement cycle, pushing operators to invest in modern, compliant machinery.
Market Restraints
- High Capital Outlay:The initial investment for commercial-grade, energy-efficient washing machines and dryers represents a significant financial barrier for independent operators entering the market.
- Prime Real Estate Scarcity:Securing affordable and properly zoned locations in densely populated urban centers across Europe is a major constraint on network expansion for operators.
- Utility Cost Volatility:Unpredictable fluctuations in electricity and water tariffs across the EU directly impact the operational profitability of laundromats, complicating financial planning.
Strategic Opportunities
- Subscription Service Models:Developing recurring revenue plans for residents in build-to-rent properties or student accommodations provides a stable and predictable income stream outside of pay-per-use.
- Secondary City Expansion:Targeting underserved residential areas in growing secondary cities in countries like Poland and Portugal offers new growth frontiers away from saturated metropolitan markets.
- Ancillary Service Bundling:Integrating laundry services with complementary offerings such as package lockers or dry cleaning drop-offs can enhance customer value and increase revenue per site.
Industry Challenges
- Retrofitting Complexity:Upgrading existing facilities with modern digital payment systems and IoT connectivity presents significant technical and financial challenges for operators with large portfolios of legacy equipment.
- Fragmented Service Networks:Establishing a consistent and skilled maintenance technician network to ensure machine uptime across various countries and municipalities is a persistent operational difficulty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coin-Operated Laundries Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Coin Changers, Detergent Dispensers Service Type: Self-Service, Full-Service, On-Demand, Subscription End User: Commercial Establishments, Residential Units, Colleges, Laundromats Technology: Electromechanical, Digital Payment Solutions, IoT Enabled, Energy Efficient |
| Companies Covered | Miele, Johnson Service Group PLC, Girbau, Wash.ME, WASH' N DRY (LAVERIE LIBRE SERVICE), Elis, Fagor, LAVISA SRL, Electrolux, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coin-Operated Laundries Market Strategic Shifts & Innovations
The European market is evolving from a hardware-centric business to a service-oriented ecosystem. Connectivity and data analytics are becoming fundamental, prioritizing seamless user experiences and optimized operational management over simple machine transactions.
IoT-enabled laundry machines integrate sensors and network connectivity, facilitating remote diagnostics, usage monitoring, and mobile app-based control. Facility managers in student housing and multi-family residential complexes are adopting these systems to improve operational oversight. This advanced connectivity is rendering obsolete the traditional break-fix maintenance model and the use of unmonitored, purely electromechanical equipment.
Enforcement of the EU's Ecodesign Directive and energy labeling regulations sets stringent efficiency standards for new commercial laundry appliances. This compels manufacturers to innovate with high-efficiency motors, advanced water management, and optimized heat-pump drying systems. The heavy-duty washer segment is particularly affected, with operators in Germany and the UK prioritizing machines with top energy ratings to manage long-term operational costs.
Consumer preferences in dense urban centers are shifting toward all-inclusive, subscription-based access to laundry facilities. This model replaces traditional pay-per-use transactions with fixed monthly fees, appealing to residents in co-living spaces and large apartment buildings. This behavioral shift is most pronounced in markets like the UK and France, allowing operators to secure predictable revenue.
Europe Coin-Operated Laundries Market Segmentation
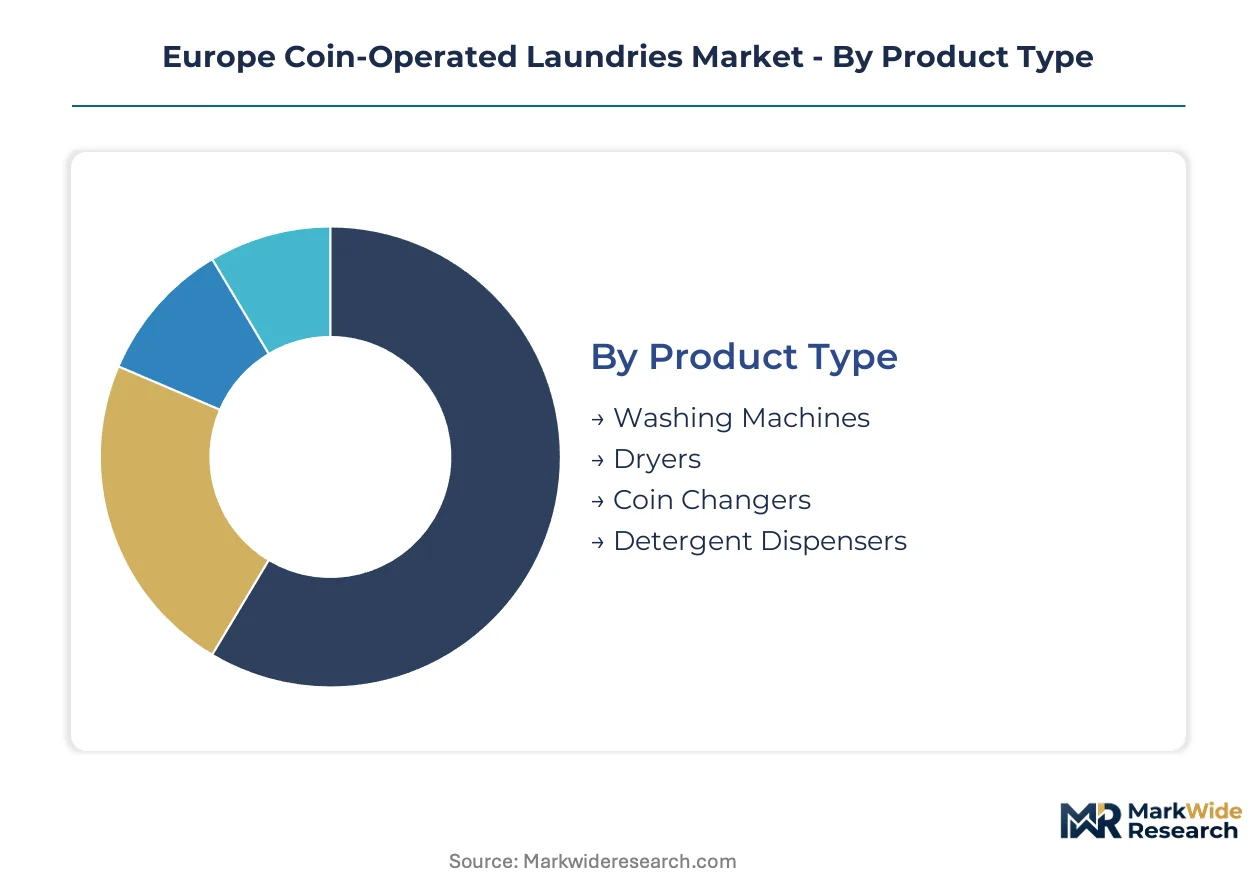
Understanding the Europe coin-operated laundries market through segmentation reveals distinct operational models and user preferences. Each segment offers unique revenue opportunities and operational challenges for facility operators and equipment manufacturers. Analyzing these segments helps stakeholders identify specific areas for investment and service development across European cities.
Product Type:
The product type segments exhibit varying replacement cycles and maintenance frequencies across the European market.
- Washing Machines:These commercial-grade units are engineered for high-volume use, featuring durable components like stainless steel drums and heavy-duty motors. Demand concentrates in multi-family residential units and student housing complexes in Germany, driven by the need for reliable, continuous operation.
- Dryers:Commercial dryers utilize robust heating elements and airflow systems to handle large loads efficiently and quickly. European operators in the UK increasingly prioritize energy-efficient heat-pump models to manage fluctuating utility costs.
- Coin Changers:These machines convert banknotes into coins, providing a necessary physical payment option for traditional laundromats. Their usage is declining as digital payment solutions gain wider acceptance across the EU.
- Detergent Dispensers:Automated dispensers provide single-use portions of laundry detergent, enhancing convenience for users in self-service facilities. These are common in busy urban laundromats in France.
Washing machines dominate the installed base. Dryers are where expansion concentrates, particularly with advanced energy-efficient models.
Service Type:
Service types vary significantly in their operational cost structures and customer engagement models within the European market.
- Self-Service:This model allows customers to operate machines independently, typically activated by coins or digital payments. Laundromats across Europe, especially in Italy and Spain, primarily offer self-service options due to lower overhead.
- Subscription:This service provides unlimited or fixed-allowance laundry access for a recurring monthly fee, appealing to residents in co-living spaces and large apartment buildings. This model is expanding in the UK and France, offering predictable revenue streams.
- Full-Service:Operators handle the entire laundry process, including washing, drying, and folding, for customers. This premium service caters to niche markets and businesses requiring professional laundry care.
- On-Demand:Mobile app-based services allow users to schedule laundry pickups and deliveries, offering maximum convenience for urban professionals. This type is gaining traction in densely populated European cities.
Self-service facilities generate consistent revenue. Subscription models are expanding most quickly, particularly in urban residential settings.
End User:
End-user segments reflect distinct application requirements and usage volumes across the European continent.
- Laundromats:Dedicated commercial establishments offer self-service or full-service laundry facilities to the general public. These remain a primary end-user segment, especially in areas with high renter populations in France and Spain.
- Residential Units:Multi-family dwellings and apartment complexes integrate shared laundry facilities for their tenants. Demand for modern, connected machines is high in new build-to-rent developments across Germany.
- Commercial Establishments:Businesses like hotels, restaurants, and small healthcare facilities utilize coin-operated or commercial laundry equipment for their operational needs. These users prioritize durability and efficiency.
- Colleges:Student housing and university dormitories provide on-site laundry services for students, often integrating digital payment and mobile app solutions. Student housing complexes in the UK are a key market for these systems.
Laundromats generate consistent revenue. Residential units represent a significant growth area for new installations.
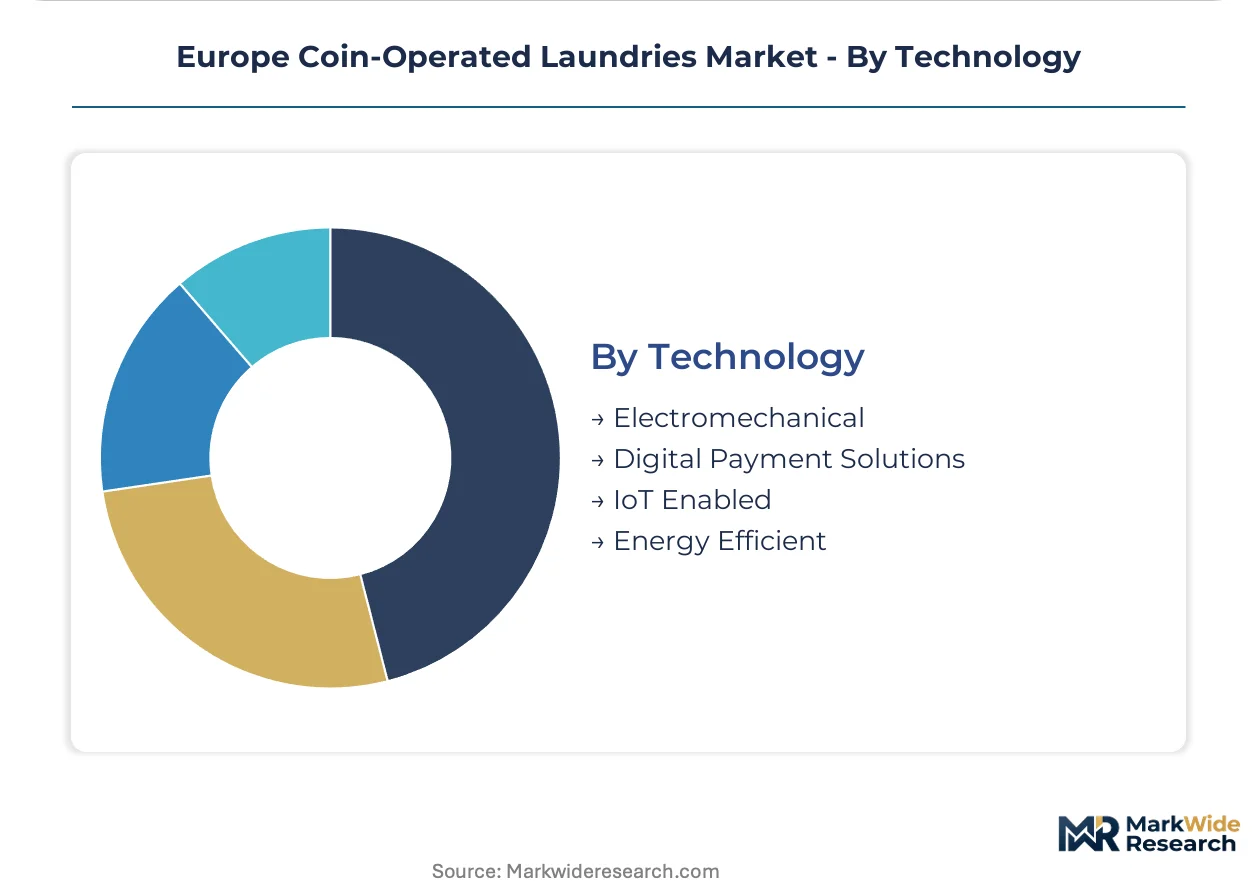
Technology:
Technology segments range from mature, widely deployed systems to rapidly evolving, specialized solutions across the European market.
- IoT Enabled:These machines integrate sensors and network connectivity, enabling remote diagnostics, usage monitoring, and mobile app control. Facility managers in student housing in the Netherlands adopt these systems for improved operational oversight.
- Energy Efficient:Appliances designed to minimize water and electricity consumption, often complying with EU Ecodesign Directive standards. Operators in Germany prioritize these models to reduce long-term utility costs.
- Electromechanical:Traditional machines rely on mechanical controls and coin mechanisms, representing an older generation of laundry equipment. These systems are being phased out in favor of more advanced solutions.
- Digital Payment Solutions:Systems that allow users to pay via contactless cards, mobile apps, or other digital methods, replacing traditional coin-based transactions. These are becoming standard in new installations across Europe.
IoT-enabled solutions are gaining share fastest. Energy-efficient models are becoming standard across new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European coin-operated laundries market exhibits varied demand elasticity across its key geographies, with some urban centers prioritizing convenience and digital integration over pure cost savings, while other regions emphasize accessibility and basic utility. High-density multi-family residential units and student housing complexes drive concentrated demand clusters, particularly in Western European metropolitan areas. EU regulations, such as the Ecodesign Directive, consistently influence equipment choices and operational investments across the continent.
Germany
Demand for modern laundry solutions in Germany stems from a growing number of multi-family residential units and new build-to-rent developments in major cities. The EU's Ecodesign Directive mandates high energy efficiency standards, pushing operators to invest in compliant, modern machinery. Operators in Berlin and Munich prioritize IoT-enabled machines for improved operational oversight and reduced long-term utility costs.
France
France experiences strong demand from densely populated urban centers and areas with high renter populations, particularly for convenient self-service facilities. Equipment sold within France must conform to CE marking standards, ensuring safety and operational compliance. Busy urban laundromats in Paris and Lyon frequently integrate automated detergent dispensers and digital payment solutions for enhanced user experience.
United Kingdom
The United Kingdom market sees significant traction from student housing complexes and co-living spaces, which increasingly adopt subscription-based laundry models. While no longer an EU member, UK regulations often align with or adapt principles from the EU's Ecodesign Directive for appliance efficiency. London and Manchester are key markets where specialized service operators like Johnson Service Group PLC leverage network density to capture recurring revenue streams.
Italy
Italy's coin-operated laundries market is largely characterized by self-service facilities, especially in regions with high renter populations and traditional urban living structures. CE marking standards are essential for all commercial laundry equipment imported or sold within Italy. Cities like Rome and Milan show consistent demand for accessible, independent laundry options, often activated by traditional coins or basic digital payments.
Poland
Poland represents a strategic opportunity for market expansion, with growing secondary cities offering underserved residential areas for new laundromat installations. The EU's Ecodesign Directive applies, encouraging investment in energy-efficient models to manage operational costs effectively. Operators in Warsaw and Krakow are exploring modern, connected laundry solutions to meet evolving consumer expectations in these developing urban markets.
Europe Coin-Operated Laundries Market Key Industry Players
Capability concentration sits with one tier of the European coin-operated laundries market, primarily advanced equipment manufacturers, while scale advantage sits with another, often large service operators with extensive networks. The market exhibits a tiered structure, segmenting between hardware providers, full-service laundry operators, and technology solution integrators. Dominant competitive moves include the integration of digital payment solutions and strategic expansion into underserved urban residential areas.
Diverse operational models define the competitive landscape, where companies like Girbau, an equipment manufacturer, exemplify the shift towards integrating advanced digital interfaces into new machine lines. Specialized service operators, such as Johnson Service Group PLC, anchor the UK market through network density and comprehensive service offerings. Elis, positioning itself as a multi-service provider, embeds laundry within broader facilities management contexts, particularly across France and other European countries.
| Leading Market Players |
|---|
| Miele |
| Johnson Service Group PLC |
| Girbau |
| Wash.ME |
| WASH' N DRY (LAVERIE LIBRE SERVICE) |
| Elis |
| Fagor |
| LAVISA SRL |
| Electrolux |
| Others |
Cost & Logistics Intelligence
The Central European freight corridor's logistical costs directly influence the pricing of commercial laundry equipment across the region, shaping both supply concentration and downstream service price differentiation. This dynamic impacts both initial machine acquisition costs and the ongoing operational expenses for laundromat operators.
Pricing Analysis
After-sales service contracts for commercial laundry machines drive significant lifetime value for equipment manufacturers. The dominant pricing model for new equipment remains transactional, though subscription-based access for end-users is expanding. Price differentiation stems from energy efficiency ratings mandated by the EU Ecodesign Directive and the integration of advanced digital payment solutions. Pricing softness for purely electromechanical units reflects a regulatory push toward modern, compliant machinery. Independent laundromat operators exhibit higher price sensitivity compared to large multi-family residential developers.
Supply Chain Analysis
Extended payment terms offered by major equipment manufacturers to facility operators mitigate initial capital outlay for new installations. Geographic supply concentration for high-quality commercial laundry components and finished goods centers primarily in Germany and Italy, with some sub-assembly sourcing from Eastern Europe. Raw material dependencies include stainless steel for durable drums, heavy-duty motors, and sophisticated electronic control units. Commodity price volatility, particularly for metals and energy, represents a structural supply chain risk. Distribution runs through a dual model of direct sales from manufacturers to large corporate operators and regional distributors serving independent laundromat businesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European coin-operated laundries market is undergoing a platform-economics inflection, driven by the integration of IoT-enabled machines into smart building management ecosystems.
For Market Incumbents: Pre-empt the erosion of traditional coin-based revenue by aggressively migrating existing machine portfolios to digital payment systems. Invest in retrofitting legacy equipment with IoT connectivity to enable remote diagnostics, mitigating the threat from tech-forward startups offering advanced operational oversight. Leverage internal R&D capabilities for predictive maintenance algorithms to reduce downtime.
For New Entrants and Emerging Players: Underserved secondary cities in Poland and Portugal present penetrable entry points for modern laundromat services. Target build-to-rent properties and student housing complexes lacking integrated on-site laundry solutions as the most penetrable segment. Bundle laundry services with complementary offerings like package lockers or dry cleaning drop-offs to enhance customer value and differentiate from existing operators.
For Investors and Strategic Acquirers: Regional service operators with strong network density and established digital payment infrastructure represent attractive acquisition targets. The market offers stable, recurring revenue streams over a 5-10 year window, particularly from urban residential segments and subscription models. Increased M&A activity among smaller, digitally advanced laundromat chains would signal an inflection point for consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Model Launch | Secures predictable revenue from urban residents in co-living spaces and multi-family units. |
| IoT Retrofit Program | Extends the life of existing assets and enables remote operational oversight for facility managers. |
| Digital Payment Integration | Enhances user experience and allows dynamic pricing in busy French and German laundromats. |
| Expansion into Secondary Cities | Captures new demand in Poland and Portugal away from saturated Western European markets. |
| Ecodesign Compliance Upgrade | Reduces long-term utility costs for operators and ensures adherence to EU regulations. |
Research Approach
A spread of perspectives from commercial laundromat owners, equipment manufacturers' sales leads, multi-family residential property managers, and digital payment solution providers converged on the working assumptions for this study. Primary interviews with these industry stakeholders across key European markets were triangulated with extensive secondary validation. Secondary sources included EU Commission reports on the Ecodesign Directive, company financial filings, national statistics office data for urbanization trends, and industry association publications. Both bottom-up analysis from individual market segments and top-down validation from macro-economic trends informed the data.
Demand-supply-balance modeling formed the core of the quantitative framework across the analysis window. The analytical framework analyzed market dynamics through segmentation dimensions including product type, service type, end-user, technology, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market shifts over the projection horizon. Urbanization rates in European cities and digital payment adoption trends served as key forecast inputs throughout the modeling period.
Macroeconomic conditions sit as an overlay; deviation in energy prices or interest rates would shift the trajectory of capital investments. Forecasts reflect documented assumptions regarding regulatory stability and technological adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
France Digital Showers Market
Household Items
Replacement Sheets Market
Household Items
India Digital Showers Market
Household Items
Book Light Market
Household Items
Smart Bathtub Market
Household Items
Car Air Freshener Market
Household Items
Global Tableware Market
Household Items
Umbrella Market
Household Items
Drinkware Accessories Market
Household Items
Russia Residential Water Heaters Market
Household Items
Laundry Detergent Sheets Market
Household Items
Home Use Air Purifiers Market
Household Items
Asean Cookware Market
Household Items
Global Laptop Tables Market
Household Items
Smart Fridge Market