
 Smart Tourism Market | 2026-2036
Smart Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Tourism Market Analysis
Subscription-based software-defined booking services is consolidating revenue streams across the Smart Tourism landscape. ImmersiVision leverages proprietary AR rendering to anchor premium virtual tour offerings. DoROAD competes through integrated IoT navigation layers that extend its platform reach into destination management systems.
Smart tourism denotes the application of digital technologies including IoT sensors, geospatial positioning systems, and machine-learning recommendation engines to optimize visitor experiences, resource allocation, and real-time service delivery across hospitality ecosystems. Mobile Applications currently dominate technology adoption, while Virtual Tours within Service Type represent the fastest-expanding margin pool as post-pandemic behavioral shifts persist. Augmented Reality remains technically demanding but occupies the highest-value experiential tier for cultural heritage sites.
The EU AI Act and GDPR impose strict algorithmic transparency and data minimization requirements on European smart tourism platforms processing traveler biometrics and location histories. China's SAMR enforces GB standards for IoT device interoperability in connected destination infrastructure. Stakeholders must monitor evolving compliance scopes across multiple jurisdictions to secure platform access and avoid service localization penalties.
Market Dynamics
Mobile-first service delivery is compressing booking cycles and forcing legacy destination management systems into real-time API architectures. The EU AI Act's algorithmic transparency mandates are creating compliance moats that favor well-capitalized platform operators over fragmented local vendors.
Growth Catalysts
- EU AI Act Compliance:GDPR-aligned data governance frameworks are unlocking enterprise procurement channels for certified smart tourism platforms across European heritage sites and municipal visitor bureaus.
- China's GB Standards:Mandatory IoT interoperability protocols under SAMR supervision are accelerating connected infrastructure deployment in Hangzhou, Suzhou, and Chengdu smart city clusters.
- Geofenced AR Rendering:Proprietary spatial computing engines are enabling museums and archaeological parks to deploy location-locked immersive content without dedicated hardware.
Market Restraints
- Silicon Supply Concentration:Edge AI chip fabrication for on-device computer vision depends on Taiwan and South Korea foundry capacity, exposing AR tour operators to allocation volatility.
- Biometric Data Friction:France's CNIL and Germany's state data protection authorities are imposing case-by-case authorization requirements for facial recognition in visitor analytics.
- Technical Talent Scarcity:The intersection of geospatial systems, machine learning operations, and hospitality UX design commands premium compensation in Amsterdam, Barcelona, and Singapore labor markets.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for semiconductor assembly and IoT device manufacturing are lowering entry costs for smart tourism hardware providers targeting domestic pilgrimage circuits.
- Digital Twin Convergence:The fusion of BIM models with real-time sensor feeds is creating new revenue streams for engineering consultancies repurposing infrastructure data for visitor experience platforms.
- Subscription Channel Innovation:Enterprise SaaS marketplaces operated by AWS, Azure, and Google Cloud are displacing direct sales cycles for mid-sized destination management software vendors.
Industry Challenges
- Legacy PMS Integration:Property management systems deployed during the 2010s lack open APIs, forcing smart tourism platforms to maintain expensive middleware layers for hotel connectivity.
- Multijurisdictional Certification:Simultaneous compliance with EU AI Act algorithmic impact assessments, GDPR data protection impact assessments, and sector-specific heritage site regulations extends go-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Tourism Market |
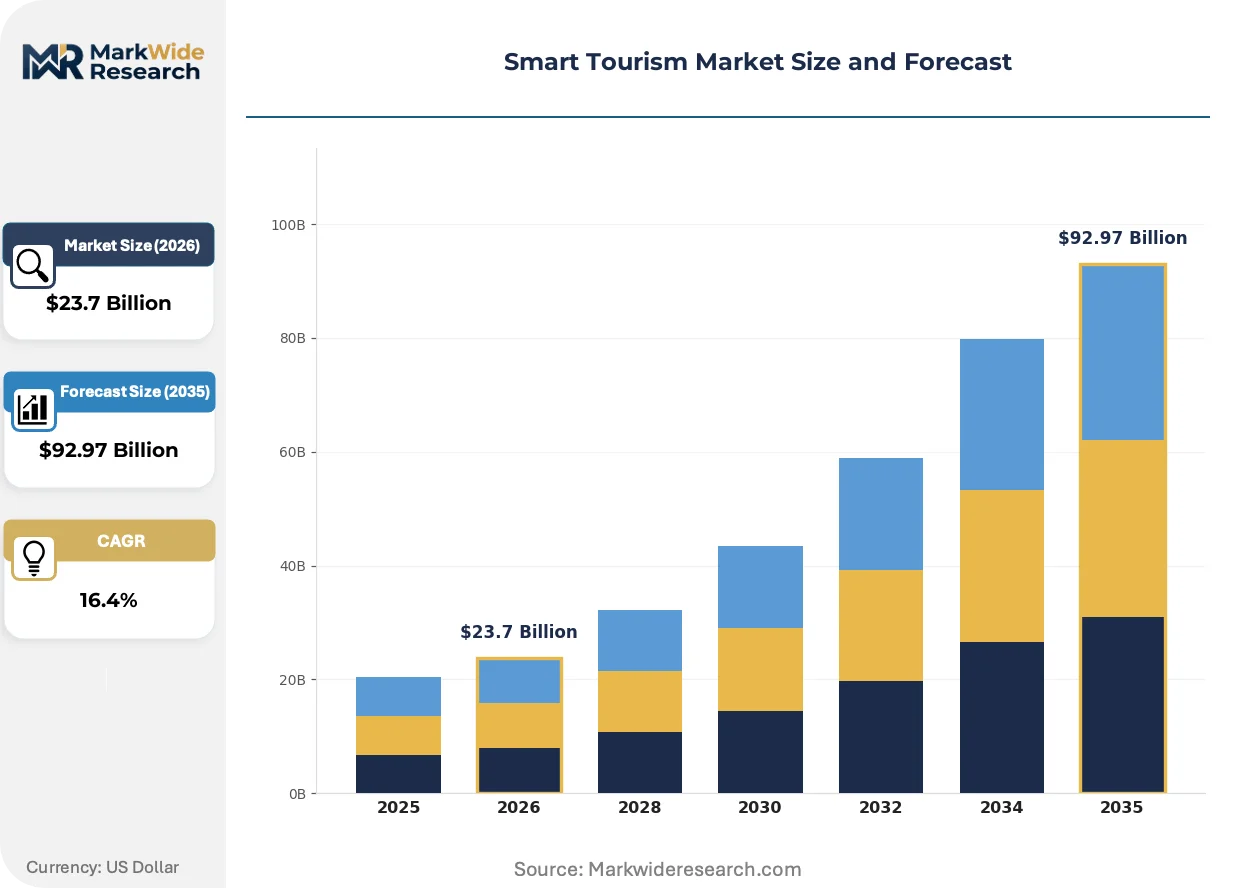
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $92.97 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mobile Applications, Smart Wearables, IoT Devices, Augmented Reality Service Type: Guided Tours, Booking Services, Concierge Services, Virtual Tours End User: Travelers, Tour Operators, Hotels, Local Governments Application: Travel Planning, Navigation Assistance, Experience Enhancements, Customer Engagement |
| Companies Covered | ImmersiVision, DoROAD, iWander, Navan, Videreo, Otto, Axai, Amex GBT, Placeaa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Tourism Market Emerging Trajectories
Distributed ledger architectures and federated learning frameworks are eroding centralized data monopolies in traveler identity and preference management. Platform operators are racing to deploy edge-native applications that function without persistent cloud connectivity.
Edge computing infrastructure is decentralizing real-time personalization in smart tourism deployments. Heritage sites in Italy and Greece are adopting on-premise recommendation engines to process visitor biometrics without cross-border data transfer. This architecture compresses latency for AR overlay rendering while satisfying EU data localization requirements.
The EU AI Act's risk-based classification system is mandating algorithmic audit trails for high-stakes tourism applications. Automated decision systems governing dynamic pricing and crowd flow management now require conformity assessments under notified body supervision. German and Austrian ski resort operators are front-loading compliance investments to secure early-mover certification advantages.
Travelers are fragmenting booking behavior across specialized vertical applications rather than consolidating through legacy online travel agencies. Corporate incentive travel planners in the United States and United Kingdom are bypassing traditional intermediaries to contract directly with experience platforms offering API-first inventory access. This disintermediation pressures incumbent aggregators to unbundle commission structures and expose raw supplier contracts.
Smart Tourism Market Segmentation
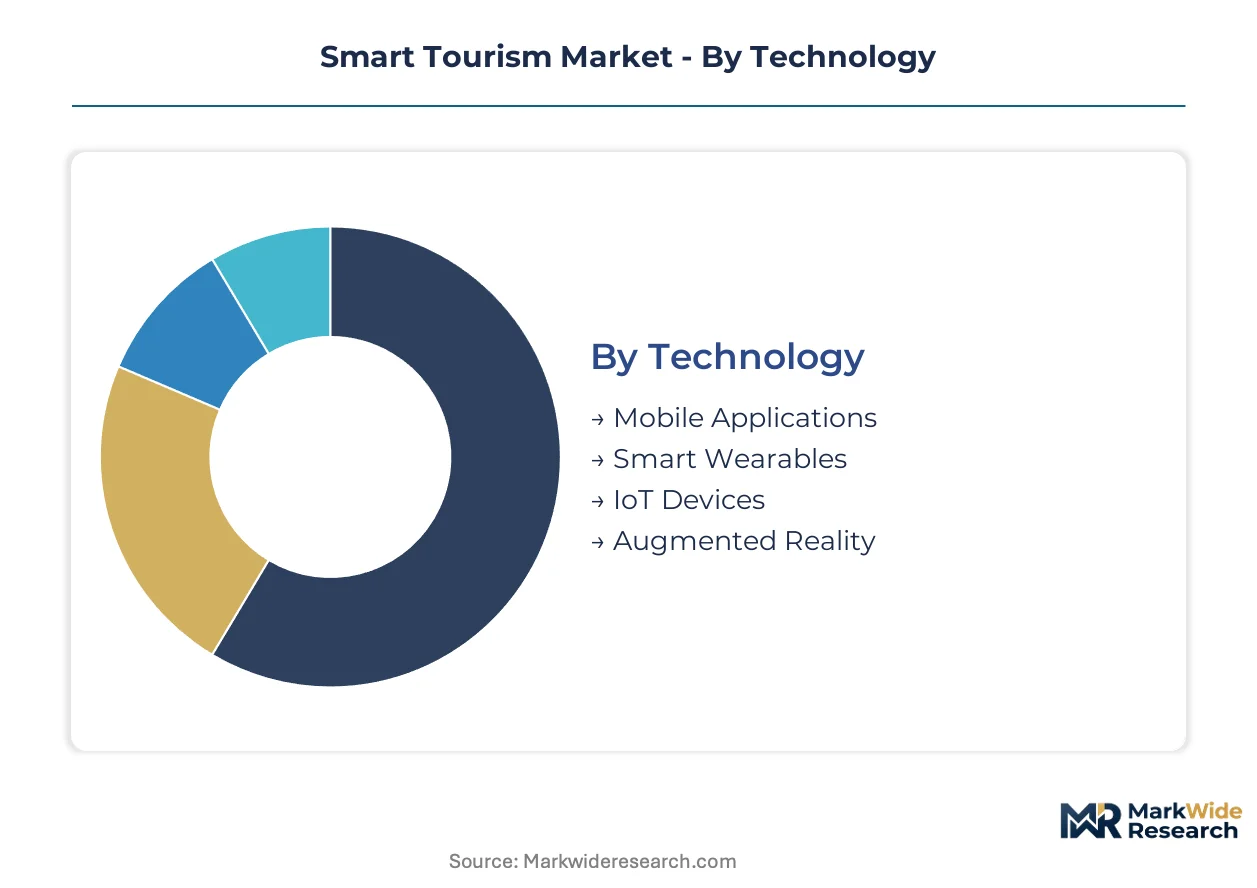
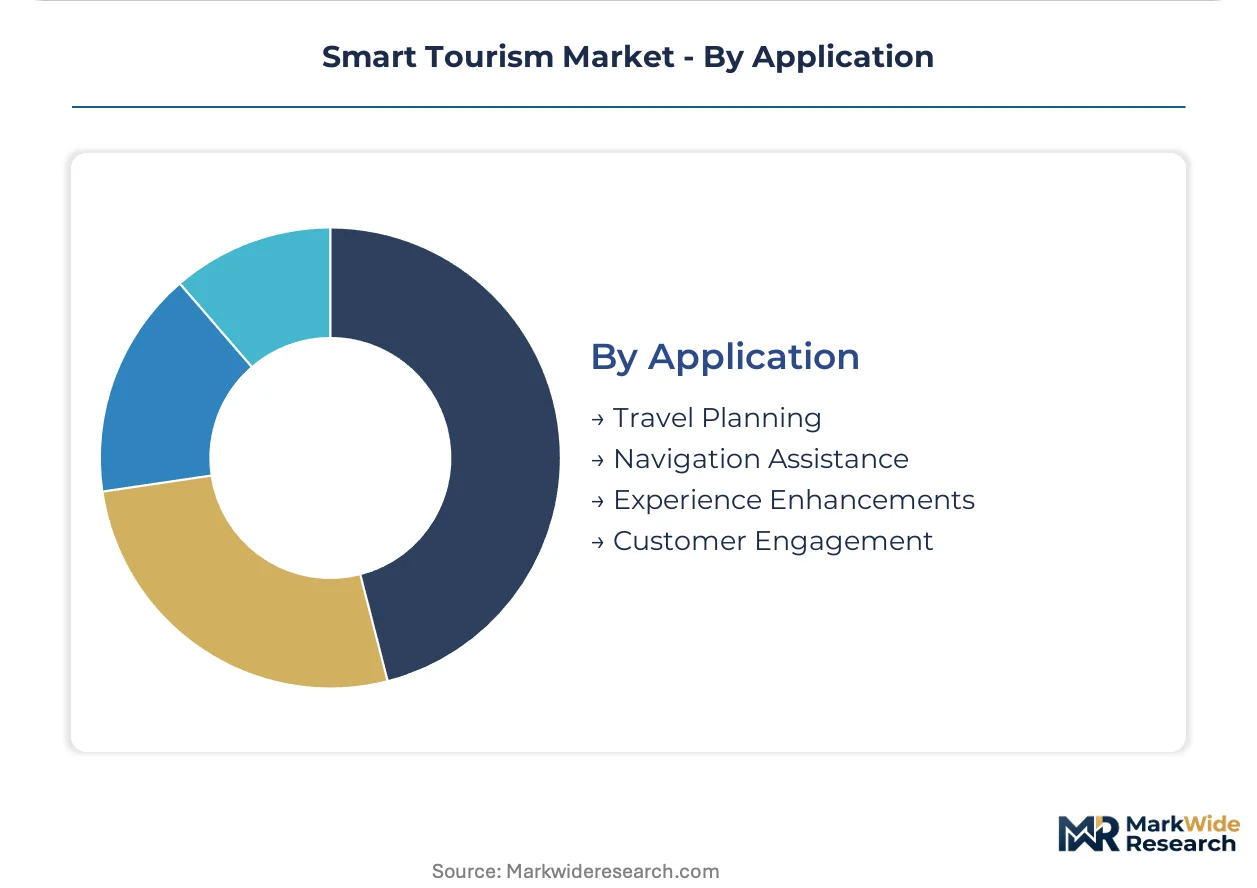
Smart tourism platforms must align technology architecture with distinct buyer workflows across hardware procurement, software licensing, and managed service contracts. Segmentation reveals where margin pools concentrate and which integration pathways dominate purchasing decisions.
Technology:
Procurement teams prioritize interoperability certification and total cost of ownership when selecting enabling hardware and software layers.
- Mobile Applications:Native and progressive web apps deliver itinerary management, real-time translation, and contactless payment orchestration through smartphone ecosystems. Demand concentrates among independent travelers in Chinese smart city corridors where super-app integration is mandatory.
- Augmented Reality:Spatial computing engines overlay historical reconstructions and navigational waypoints onto physical environments through camera feeds and LiDAR sensors. Museums in Italy and Greece deploy location-locked content to satisfy GDPR data localization requirements while eliminating dedicated hardware procurement.
- Smart Wearables:Biometric-enabled wristbands and headsets enable hands-free access control and physiological stress monitoring during immersive experiences.
- IoT Devices:Environmental sensors and beacon networks feed occupancy and air quality data into centralized destination management dashboards.
Mobile Applications lead on scale; Augmented Reality leads on momentum.
Service Type:
Revenue model selection—transactional commission versus recurring subscription—shapes platform architecture and customer lifetime value calculations.
- Virtual Tours:Photorealistic 3D reconstructions and 360-degree video streams enable remote exploration of heritage sites and hospitality venues. Post-pandemic behavioral shifts persist in corporate incentive travel procurement across the United States and United Kingdom.
- Booking Services:API-first inventory aggregation connects travelers directly with accommodation and experience suppliers, compressing legacy online travel agency margins.
- Guided Tours:Human-led itineraries enhanced by real-time translation and geofenced content delivery.
- Concierge Services:AI-powered recommendation engines and automated reservation management for high-touch hospitality segments.
Booking Services anchor current revenue; Virtual Tours climb the fastest.
End User:
Budget authority and implementation complexity vary sharply between individual consumers and institutional procurement functions.
- Travelers:Individual consumers demand seamless cross-platform synchronization and offline functionality during international roaming.
- Hotels:Property management system integration requirements dominate vendor selection, with legacy PMS lacking open APIs forcing expensive middleware investments.
- Tour Operators:Mid-sized experience providers seek white-label platform capabilities to bypass aggregator commission structures.
- Local Governments:Municipal visitor bureaus mandate EU AI Act conformity assessments and algorithmic audit trails for public procurement eligibility.
Hotels concentrate procurement volume; Local Governments impose the steepest compliance barriers.
Application:
Use case specificity determines sensor deployment density and edge computing architecture requirements.
- Experience Enhancements:AR overlays, haptic feedback installations, and personalized content curation elevate visitor engagement at cultural heritage sites.
- Travel Planning:Machine-learning recommendation engines synthesize historical preferences with real-time availability and pricing signals.
- Navigation Assistance:Indoor positioning systems and crowd flow optimization reduce congestion at high-density attractions.
- Customer Engagement:Biometric-enabled loyalty programs and predictive service recovery mechanisms.
Travel Planning captures the broadest addressable base; Experience Enhancements command premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's smart city infrastructure investment dwarfs Italy's cultural heritage digitization budgets, yet both markets concentrate procurement volume in markedly different technology stacks.
China
SAMR-mandated GB standards for IoT interoperability accelerate connected infrastructure deployment across Hangzhou, Suzhou, and Chengdu smart city clusters. Municipal tourism bureaus in these cities integrate environmental sensors and beacon networks into unified destination management dashboards. The Yangtze River Delta and Pearl River Delta regions anchor domestic platform development for mobile-first service delivery.
Germany
EU AI Act algorithmic transparency mandates create compliance moats favoring well-capitalized platform operators over fragmented local vendors. KBA and state-level data protection authorities impose strict authorization requirements for biometric visitor analytics at Bavarian ski resorts. Berlin-Brandenburg and Baden-Württemberg concentrate early-mover certification investments for automated decision systems governing dynamic pricing.
United States
Corporate incentive travel planners bypass traditional intermediaries to contract directly with API-first experience platforms. FAA and FTC oversight shapes biometric data handling for airport-adjacent hospitality deployments. The Southeast and Pacific Northwest regions host the densest concentrations of edge AI chip procurement for on-device computer vision applications.
Italy
Heritage sites in Rome and Florence deploy location-locked AR content to satisfy GDPR data localization requirements while eliminating dedicated hardware procurement. EMA-aligned data governance frameworks influence municipal procurement eligibility for smart tourism platforms. Lombardy and Lazio anchor museum consortium investments in geofenced spatial computing engines.
India
Production-linked incentives for semiconductor assembly lower entry costs for smart tourism hardware providers targeting domestic pilgrimage circuits. BIS certification requirements shape IoT device interoperability for connected destination infrastructure. Maharashtra and Karnataka concentrate platform development for itinerary management and real-time translation applications.
Smart Tourism Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform operators capturing recurring revenue streams while hardware vendors compete on unit economics. The vendor base organizes into three tiers: capitalized incumbents with certification advantages, mid-scale specialists with vertical integration into sensor manufacturing, and regional integrators serving single-destination contracts. Dominant competitive moves include strategic partnerships with cloud hyperscalers and geographic expansion through white-label licensing agreements.
Within the immersive content tier, ImmersiVision and Videreo exemplify proprietary AR rendering specialists competing on experiential differentiation. DoROAD anchors the integrated navigation segment with IoT-layer platform architecture. These three entities occupy positions spanning premium virtual tour offerings and destination management system integration, representing distinct strategic archetypes for technology stack deployment.
| Leading Market Players |
|---|
| ImmersiVision |
| DoROAD |
| iWander |
| Navan |
| Videreo |
| Otto |
| Axai |
| Amex GBT |
| Placeaa |
| Others |
Supply Flow & Price Mechanics
Cloud hyperscaler-backed platform operators and sovereign wealth-funded smart city integrators anchor supply-side financing, compressing procurement timelines for municipal destination management contracts while enforcing subscription-based pricing discipline across European heritage sites and Chinese smart city clusters.
Pricing Analysis
Capacity additions in India's PLI-subsidized semiconductor assembly corridors are reshaping price floors for IoT-enabled tourism hardware. Three-tier pricing structure across premium AR rendering, standard mobile application suites, and economy-tier booking APIs separates experiential differentiation from commodity middleware. Cost compression in middleware layers intensifies because legacy PMS integration demands expensive custom development. Mid-sized tour operators exhibit highest price sensitivity; municipal visitor bureaus with EU AI Act certification mandates show lowest.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs to European deployment sites compresses hardware margins for beacon networks and environmental sensors. Edge AI chip fabrication draws from Taiwan and South Korea foundry capacity; IoT sensor assembly rests on China's Yangtze River Delta electronics corridor. Single-source vulnerability in EU-certified algorithmic audit providers exposes AR platform operators to certification bottlenecks. Distribution runs through AWS, Azure, and Google Cloud enterprise SaaS marketplaces for mid-sized software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in smart tourism hinges on algorithmic compliance investments unlocking premium municipal procurement tiers, while edge-native architectures reduce hyperscaler compute dependencies.
For Market Incumbents: Deploy EU AI Act conformity assessment capabilities as defensive moats against fragmented local vendors. Secure early-mover certification advantages in German and Austrian ski resort clusters where KBA and state data protection authorities impose strict biometric authorization requirements. Channel control through direct API-first inventory relationships with corporate incentive travel planners displaces legacy online travel agency intermediation. For New Entrants and Emerging Players: The premium-to-economy pricing gap in AR-enabled heritage experiences offers white-space entry for specialized spatial computing engines. Target India's domestic pilgrimage circuits where PLI-subsidized hardware assembly lowers IoT device procurement barriers. White-label platform capabilities for mid-sized tour operators seeking commission bypass provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialists with captive sensor manufacturing and vertical integration into geospatial data processing. Long-term viability over the next decade favors platform operators with algorithmic audit trail capabilities and edge-native deployment architectures. Monitor EU AI Act notified body certification timelines as the critical inflection signal for procurement eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Unlocks municipal procurement channels across German and Italian heritage sites under notified body supervision. |
| Edge-Native Architecture Deployment | Satisfies GDPR data localization requirements for Italian and Greek museums processing visitor biometrics. |
| API-First Inventory Integration | Compresses legacy online travel agency margins by connecting US corporate planners directly with experience suppliers. |
| PLI-Aligned Hardware Assembly | Reduces IoT device entry costs for smart tourism providers targeting India's domestic pilgrimage circuits. |
| Spatial Computing Engine Acquisition | Consolidates proprietary AR rendering capabilities for premium virtual tour differentiation in cultural heritage segments. |
Methodological Framework
Coverage spans China, Germany, the United States, Italy, and India, with primary inputs from each regional cluster combining interviews with destination management system vendors, municipal tourism bureau procurement officers, heritage site operations directors, and cloud platform enterprise sales leads. Secondary validation draws from SAMR GB standard filings, EU AI Act impact assessment documentation, FAA biometric handling guidance, and hyperscaler capex disclosures. Bottom-up segment sizing triangulates against top-down smart city infrastructure investment tracking.
Granularity-level modeling disaggregates technology adoption by deployment complexity, service type by revenue model architecture, end user by procurement authority tier, and application by sensor density requirements across the projection horizon. CAGRs derive from fitted growth curves applied to mobile application penetration benchmarks, AR hardware cost decline trajectories, and IoT interoperability standard adoption rates. Edge computing deployment velocity and federated learning framework maturity serve as industry-specific forecast sensitivity inputs.
Caveats apply where EU AI Act enforcement intensity, Taiwan foundry allocation volatility, or India's PLI scheme revision could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization timelines and hardware cost decline trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Music Tourism Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
Japan Faith-Based Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
Europe Destination Wedding Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Germany Culinary Tourism Market
Destination Management and Attractions
Amusement Parks Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
Wildlife Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
SAVE Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market