
 Italy Tourism Market | 2026-2036
Italy Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Tourism Market Foresight
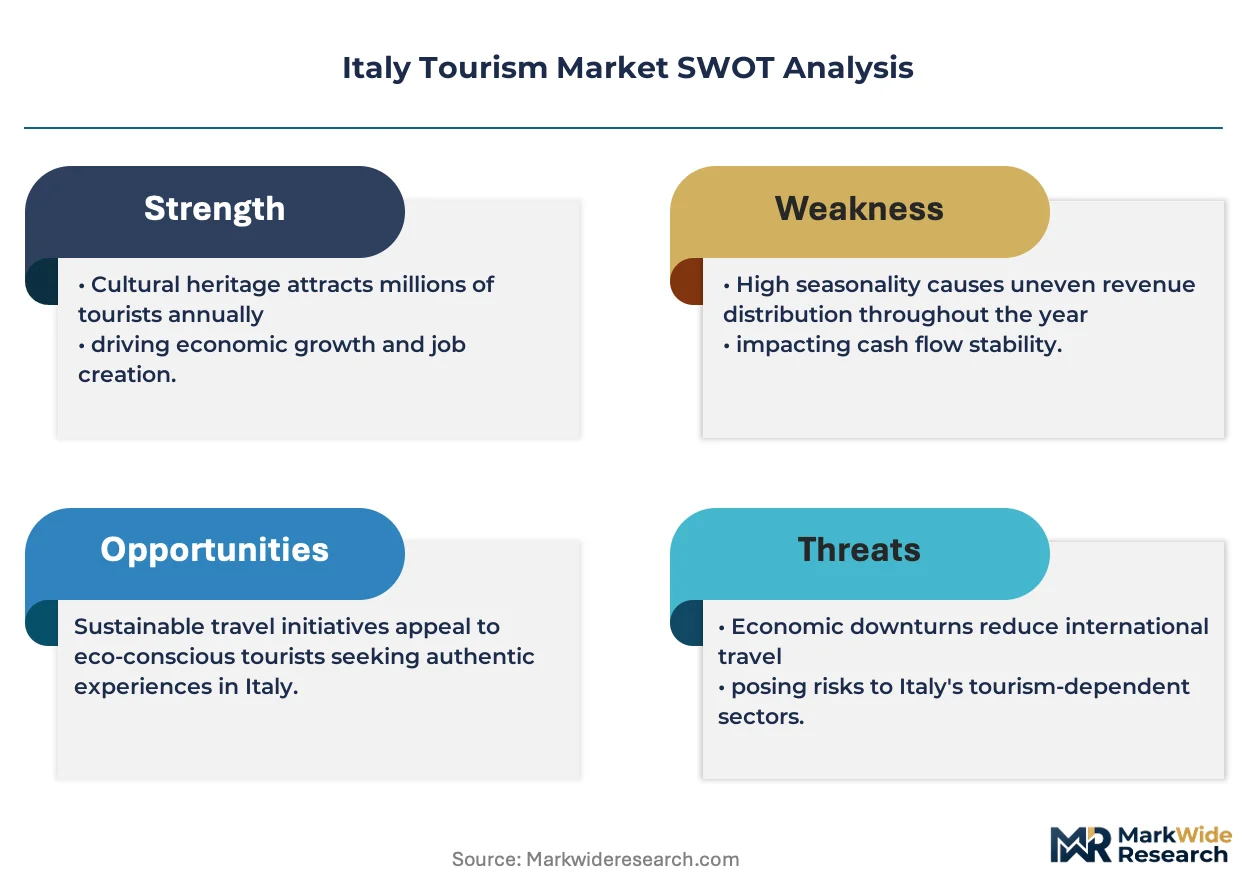
Buyer concentration across the Italian hospitality sector is restructuring as independent travelers fragment demand while corporate booking platforms consolidate procurement power. Marriott International leverages its loyalty ecosystem to capture premium urban segments in Milan and Rome. NH Hotel Group anchors its position through dense coverage of Italy's business corridor from Turin to Naples. Rocco Forte Hotels differentiates via hyper-localized design properties in Florence and Sicily.
Italy tourism encompasses the commercial ecosystem of visitor services, accommodation provisioning, guided experiences, and destination management operating across UNESCO World Heritage Sites, Alpine resorts, and Mediterranean coastline with seasonal occupancy fluctuations between 35% and 85%. Cultural Tourism commands the deepest margin pools through high-spending repeat visitors attracted to archaeological and Renaissance assets. Adventure Tourism competes for investment in the Dolomites and Sardinia where infrastructure gaps limit capacity expansion. Accommodation services dominate revenue capture, though Guided Tours generate superior per-visitor profitability through experiential premiumization.
Italy's Ministry of Tourism coordinates with the EU Green Deal compliance framework and national CSRD reporting obligations to mandate sustainability certification for properties above fifty rooms. The country's central bank and regional development agencies enforce NRRP fund disbursement tied to decarbonization benchmarks for hospitality operators. Stakeholders must monitor how EU AI Act provisions on automated booking systems reshape platform economics and direct channel strategies.
Market Dynamics
Italy's tourism sector is restructuring around sustainability mandates from the EU Green Deal and the National Recovery and Resilience Plan, which tie public infrastructure funding to decarbonization benchmarks for hospitality operators.
Growth Catalysts
- EU Green Deal compliance framework:Properties above fifty rooms must achieve sustainability certification, creating upgrade demand for energy-efficient systems and renewable integration.
- Millennial cultural heritage travel:Experience-seeking visitors from North America and Asia are extending average stays in Tuscany's agriturismo sector and Rome's boutique accommodation market.
- NRRP infrastructure disbursement:Regional development agencies channel capital toward sustainable tourism infrastructure, accelerating broadband and transport connectivity in secondary destinations.
Market Restraints
- Seasonal occupancy volatility:Alpine resorts and Mediterranean coastline properties face 35% to 85% occupancy swings, compressing revenue predictability and debt service capacity.
- Dolomites infrastructure gaps:Adventure tourism capacity expansion is constrained by limited mountain access roads and utility grid extensions in protected UNESCO zones.
- CSRD reporting obligations:Mandatory sustainability disclosure requirements impose compliance costs on small and mid-sized hospitality operators lacking dedicated ESG functions.
Strategic Opportunities
- Sicily's underdeveloped experiential inventory:Rocco Forte Hotels has demonstrated demand for hyper-localized design properties, yet supply remains sparse outside Palermo and Taormina.
- EU AI Act automated booking provisions:Platform economics are shifting as direct channel strategies gain regulatory protection against algorithmic pricing manipulation by dominant intermediaries.
- Tuscany agriturismo premiumization:Guided tour integration with farm-stay accommodation is generating superior per-visitor profitability through experiential bundling.
Industry Challenges
- Hospitality decarbonization skill scarcity:Properties struggle to source energy auditors and retrofit project managers capable of meeting NRRP technical benchmarks.
- Legacy property management system integration:Boutique operators in Florence and Rome face friction connecting sustainability monitoring tools to fragmented reservation and accounting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Tourism Market |
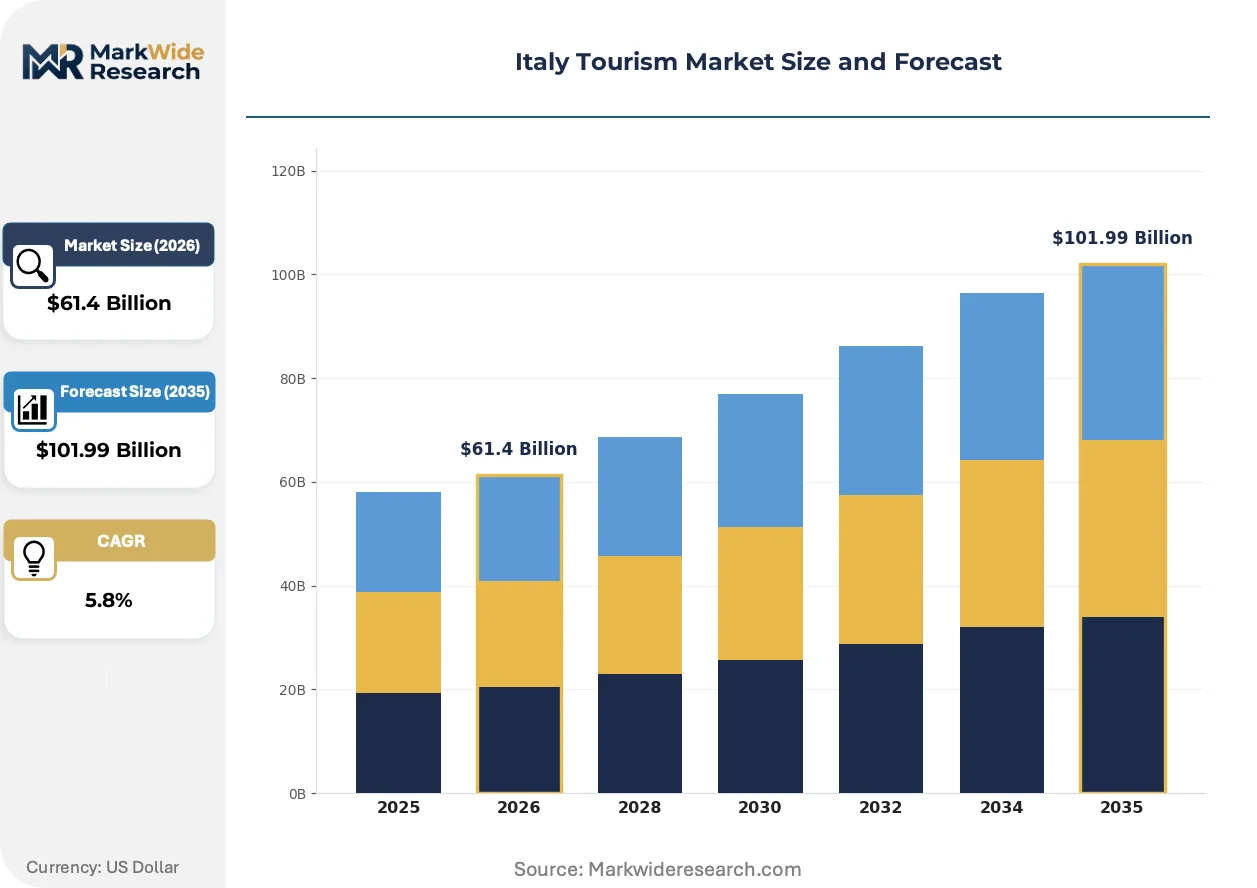
| Market Size in 2026 | $61.4 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tourism Type: Cultural Tourism, Adventure Tourism, Eco Tourism, Medical Tourism Travel Purpose: Leisure, Business, Culinary, Religious Visitor Demographics: International Tourists, Domestic Travelers, Millennials, Families Service Type: Accommodation, Guided Tours, Transportation, Dining |
| Companies Covered | Marriott International, Hilton Worldwide, Accor SA, IHG Hotels & Resorts, Best Western Hotels & Resorts, NH Hotel Group, Rocco Forte Hotels, Starhotels SpA, Gruppo UNA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Tourism Market Shifts & Advancements
Digital infrastructure and regulatory technology are reshaping how Italian hospitality operators manage compliance, distribution, and guest experience delivery.
Smart building management systems are electrifying operational efficiency across Italy's accommodation sector. Mid-sized properties in Milan and Rome are deploying IoT-enabled energy monitoring to automate HVAC and lighting controls. This technology is electrifying cost structures by reducing utility exposure and generating audit-ready data streams for CSRD submissions.
Italy's Ministry of Tourism coordinates with the EU AI Act to impose algorithmic transparency requirements on automated booking systems. Properties must now receive explainable pricing logic from platform intermediaries. Urban boutique operators in Rome are responding by accelerating direct booking channel investment to reduce platform dependency.
Experience-driven travelers are fragmenting demand away from standardized package tours toward modular itinerary assembly. Independent travelers now curate multi-region trips combining Tuscany agriturismo, Dolomites trekking, and Sicily cultural immersion through direct supplier relationships. This pattern is most visible among North American millennials booking through specialized experiential travel advisors rather than traditional tour operators.
Italy Tourism Market Segmentation
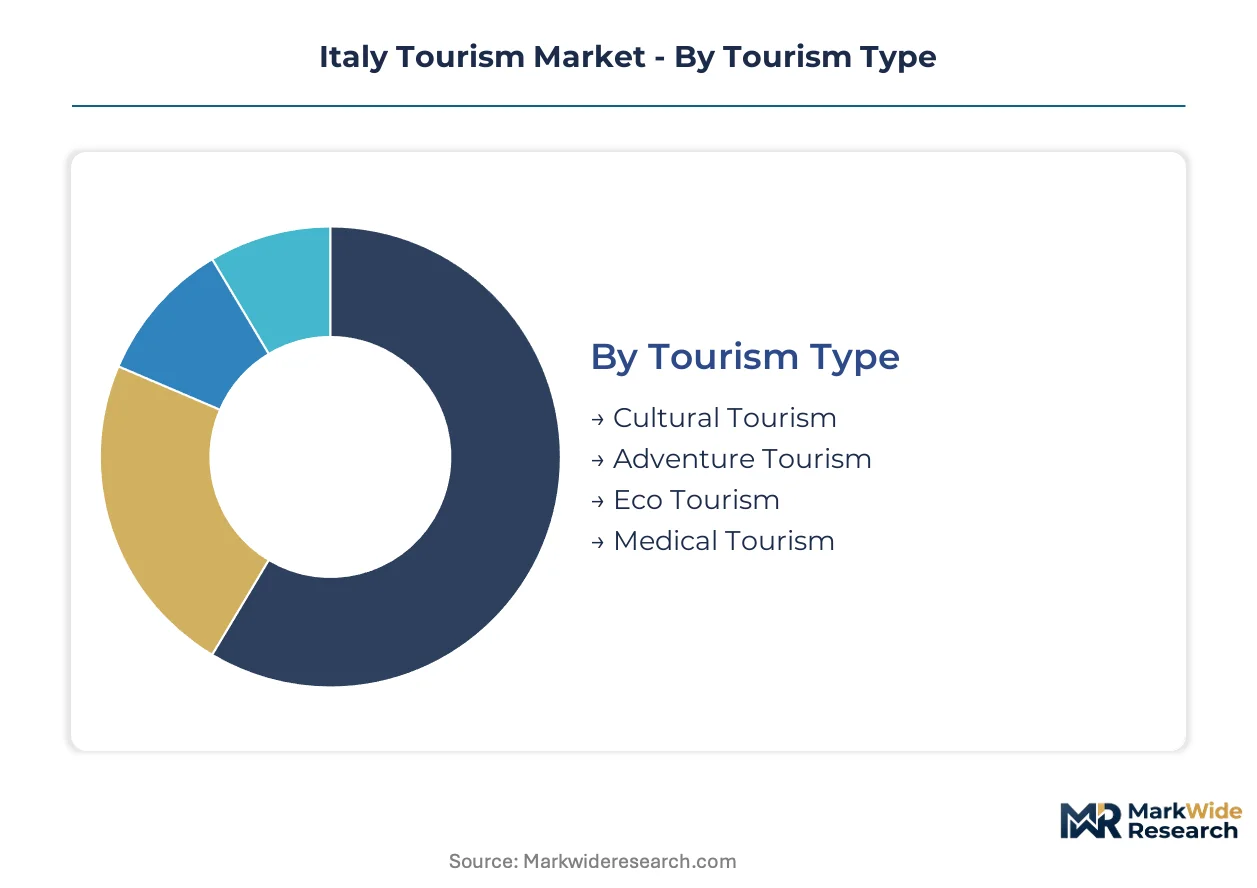
Italy's tourism market fragments along four distinct dimensions that shape investment allocation and operational strategy. Tourism type determines infrastructure requirements and margin profiles. Travel purpose and visitor demographics govern pricing power and seasonality patterns.
Tourism Type:
Standalone cultural experiences dominate revenue capture, while adventure and eco-tourism operate as embedded extensions requiring integrated transport and lodging systems.
- Cultural Tourism:Archaeological sites, Renaissance art collections, and UNESCO heritage properties generate the deepest margin pools through high-spending repeat visitation. Demand concentrates in Rome's boutique accommodation market and Florence's museum corridor, where EU Green Deal certification mandates are accelerating property upgrades.
- Adventure Tourism:Dolomites trekking, Sardinia climbing, and Alpine skiing depend on embedded logistics chains linking remote terrain to urban gateways. Infrastructure gaps in protected mountain zones constrain capacity expansion despite climbing North American millennial demand.
- Eco Tourism:Tuscany's agriturismo sector anchors this segment through farm-stay accommodation integrated with regional food systems. NRRP disbursement for sustainable tourism infrastructure is expanding broadband connectivity to secondary rural destinations.
- Medical Tourism:Thermal spa treatments and elective procedures in Lombardy and Emilia-Romagna draw German and Swiss visitors seeking specialized wellness services outside domestic reimbursement constraints.
Volume placements concentrate in Cultural Tourism; the faster expansion belongs to Eco Tourism.
Travel Purpose:
Cost tier stratification separates premium experiential travel from standardized corporate procurement, with culinary and religious purposes occupying distinct margin architectures.
- Leisure:Extended-stay visitors seeking multi-region itineraries through Tuscany, Sicily, and the Amalfi Coast generate superior per-trip expenditure. Independent travelers now fragment demand away from package tours toward modular trip assembly.
- Business:Corporate booking platforms consolidate procurement power across Milan-Turin-Naples corridor properties. NH Hotel Group anchors this segment through dense urban coverage.
- Culinary:Wine tourism and gastronomic education in Piedmont and Emilia-Romagna command premium pricing through small-group experiential formats. Farm-to-table dining integration with agriturismo stays deepens visitor spend.
- Religious:Pilgrimage traffic to Vatican City, Assisi, and Loreto operates on fixed seasonal calendars with limited pricing elasticity. Accommodation demand clusters in institutional properties and faith-affiliated guesthouses.
Business travel dominates volume placements; culinary tourism claims the steepest expansion trajectory.
Visitor Demographics:
Customer type segmentation separates high-frequency domestic short-break travel from capital-intensive international acquisition.
- International Tourists:North American and Asian millennials extend average stays in experiential inventory. CSRD reporting obligations and EU AI Act transparency requirements reshape how properties engage this digitally native segment.
- Domestic Travelers:Italian residents drive shoulder-season occupancy through regional short breaks and family reunion travel. Domestic demand provides revenue predictability during international market volatility.
- Millennials:Experience-seeking visitors prioritize authenticity and sustainability certification in booking decisions. This cohort books through specialized experiential advisors rather than traditional tour operators.
- Families:Multi-generational travel concentrates in coastal resorts and agriturismo properties with activity programming. Seasonal occupancy swings compress revenue predictability for operators dependent on this segment.
International Tourists anchor volume placements; Millennials are gaining share fastest.
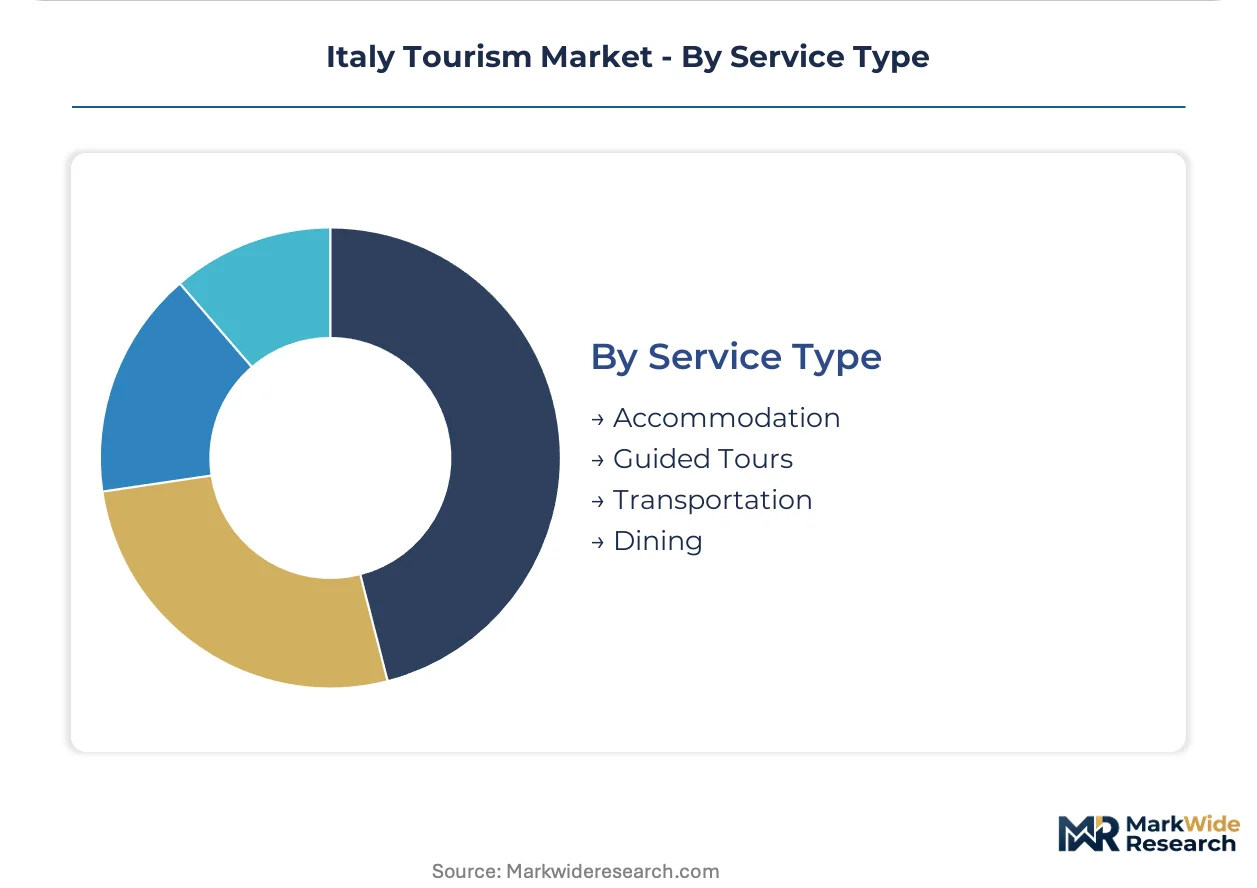
Service Type:
Supply concentration separates capital-intensive accommodation from labor-dependent guided experiences, with transportation and dining occupying intermediary positions.
- Accommodation:Properties above fifty rooms face mandatory sustainability certification under EU Green Deal compliance frameworks. Smart building management systems and IoT-enabled energy monitoring are electrifying operational efficiency in Milan and Rome.
- Guided Tours:Experiential premiumization generates superior per-visitor profitability through archaeological and Renaissance asset interpretation. Direct supplier relationships are displacing traditional tour operator intermediation.
- Transportation:NRRP infrastructure disbursement accelerates rail and road connectivity to secondary destinations. Alpine and island access constraints limit adventure tourism capacity expansion.
- Dining:Regional cuisine integration with farm-stay and cultural programming deepens visitor expenditure. Tuscany's wine tourism corridor demonstrates bundling economics.
Accommodation services dominate volume placements; Guided Tours show the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in Tuscany's agriturismo sector and Rome's boutique accommodation market, with secondary destinations gaining connectivity through NRRP infrastructure disbursement.
Lombardy
Business travel anchors occupancy across Milan's corporate hotel corridor, where NH Hotel Group maintains dense coverage. The region enforces EU Green Deal certification mandates for properties above fifty rooms. Smart building management systems are electrifying operational efficiency in Milan's mid-sized urban properties.
Lazio
Cultural heritage travel drives extended stays among North American millennials visiting archaeological assets. CSRD reporting obligations impose compliance costs on boutique operators lacking dedicated ESG functions. Rome's boutique accommodation market is accelerating direct booking channel investment to reduce platform dependency.
Tuscany
Eco-tourism demand concentrates in the agriturismo sector through farm-stay accommodation integrated with regional food systems. NRRP disbursement for sustainable tourism infrastructure is expanding broadband connectivity to secondary rural destinations. Guided tour integration with farm-stay properties is generating superior per-visitor profitability.
Veneto
Alpine resorts face seasonal occupancy volatility between thirty-five and eighty-five percent, compressing revenue predictability. The EU AI Act's algorithmic transparency requirements are reshaping how properties engage digitally native international segments. Dolomites trekking operations depend on embedded logistics chains linking remote terrain to urban gateways.
Sicily
Hyper-localized design properties demonstrate unmet demand for experiential inventory outside Palermo and Taormina. The country's Ministry of Tourism coordinates sustainability certification with regional development agencies. Infrastructure gaps in protected UNESCO zones constrain adventure tourism capacity expansion despite climbing visitor interest.
Italy Tourism Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue experiential premiumization through hyper-localized design properties. The sector structures around three tiers: global loyalty ecosystems capturing premium urban segments, dense regional coverage anchoring business corridors, and boutique specialists differentiating through localized design. Competitive moves concentrate on direct channel acceleration and sustainability certification upgrades.
Among global hospitality conglomerates, Marriott International and Hilton Worldwide occupy positions within the loyalty-driven premium tier, leveraging ecosystem scale to capture repeat visitation in Milan and Rome. NH Hotel Group anchors the business corridor segment through dense coverage from Turin to Naples. Rocco Forte Hotels exemplifies the boutique specialist archetype, demonstrating demand for hyper-localized properties in Florence and Sicily.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide |
| Accor SA |
| IHG Hotels & Resorts |
| Best Western Hotels & Resorts |
| NH Hotel Group |
| Rocco Forte Hotels |
| Starhotels SpA |
| Gruppo UNA |
| Others |
Supply & Pricing Matrix
Family-owned agriturismo operators and boutique hotel proprietors across Tuscany and Sicily anchor supply-side discipline through multi-generational asset stewardship that resists price-based commodification. Their financing patterns—rooted in regional banking relationships rather than institutional capital—preserve margin integrity even as platform intermediaries compress urban pricing in Rome and Milan.
Pricing Analysis
Volume placements concentrate in standardized accommodation services while margin pools deepen in experiential guided tours and culinary programming. Three-tier pricing structure across heritage-luxury, design-boutique, and economy-lodging levels separates EU Green Deal-certified properties from uncertified competitors. Pricing pressure stems from algorithmic pricing manipulation by dominant booking platforms, intensifying direct-channel investment among urban boutique operators. Corporate procurement through consolidated platforms exhibits highest price sensitivity; independent experiential travelers demonstrate lowest sensitivity to rate fluctuations.
Supply Chain Analysis
Regional distribution centers in Milan and Rome feed hub-and-spoke patterns extending to secondary destinations through NRRP-funded broadband and transport corridors. Supply concentration draws from domestic agricultural networks for farm-stay provisioning, German engineering for smart building systems, and Spanish renewable energy equipment for decarbonization retrofits. Single-source vulnerability sits with platform-dependent channel access controlled by two dominant intermediaries. Distribution runs through direct supplier relationships, specialized experiential travel advisors, and corporate booking platforms in descending margin priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures as a vertical-integration race where backward control over experiential content creation—archaeological guiding expertise, farm-to-table culinary programming, heritage interpretation—determines pricing power against platform intermediaries.
For Market Incumbents: Extend sustainability certification coverage to properties below fifty rooms ahead of anticipated EU Green Deal expansion. Consolidate fragmented agriturismo supply through equity partnerships with family operators in Tuscany's wine corridor. Platform dependency in Rome's boutique segment threatens margin compression; direct-booking channel investment anchors defensive positioning. For New Entrants and Emerging Players: Begin with Sicily's experiential inventory gap outside Palermo and Taormina, where hyper-localized design properties demonstrate unmet demand. Target secondary Alpine destinations with embedded logistics chains linking remote trekking terrain to urban gateways. Go-to-market positioning through specialized experiential travel advisors bypasses platform economics entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor boutique specialists with EU Green Deal certification progress in Lombardy and Lazio, where CSRD compliance costs strain undercapitalized operators. Long-term viability across the projection horizon hinges on experiential content ownership rather than asset-heavy accommodation. Monitor NRRP disbursement velocity as inflection signal for secondary destination connectivity upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Booking Channel Acceleration | Reduces platform dependency for Rome boutique operators under EU AI Act transparency provisions. |
| Sustainability Certification Upgrade | Positions properties above fifty rooms for NRRP fund access and millennial traveler preference. |
| Experiential Content Integration | Bundles guided archaeological interpretation with farm-stay accommodation for margin expansion. |
| Secondary Destination Connectivity Investment | Leverages NRRP infrastructure disbursement to unlock Alpine and rural Sicilian capacity. |
| Smart Building Management Deployment | Automates HVAC and lighting controls for CSRD audit-ready data streams in Milan properties. |
Research Methodology
Independent corroboration across property development executives, regional tourism board officials, sustainability certification auditors, and experiential travel advisors underwrites the qualitative findings. Secondary validation draws from EU Green Deal implementation reports, NRRP disbursement disclosures, CSRD regulatory filings, and Italian National Institute of Statistics tourism flow data. Bottom-up property-level capacity assessments triangulate against top-down regional expenditure estimates.
Rate-of-change decomposition across tourism type, travel purpose, visitor demographic, and service type dimensions structures the analytical framework. CAGRs derive from segment-specific growth trajectories weighted by revenue contribution and margin profile. Forecast inputs incorporate EU AI Act implementation timelines and NRRP infrastructure completion schedules without year-specific anchoring.
Underlying measurement precision varies by segment; accommodation services carry tighter precision than emerging experiential categories. Forecasts reflect documented assumptions around regulatory enforcement velocity and platform economics evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
Literary Tourism Market
Destination Management and Attractions
India Faith Based Tourism Market
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Italy Culinary Tourism Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
India Culinary Tourism Market
Destination Management and Attractions
Destination Wedding Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Film Tourism Market
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
Germany Casino Tourism Market