
 Europe Winter Tourism Market | 2026-2036
Europe Winter Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Winter Tourism Market Foresight
REACH compliance is expanding operational requirements for ski resort chemical management and slope maintenance inputs across European Alpine jurisdictions. Nordic Visitor leverages its Nordic itinerary specialization to anchor premium Northern Lights and Arctic circle packages. ICEHOTEL differentiates through its permanent and seasonal ice-structure hospitality concept in Swedish Lapland. Exodus Adventure Travels competes on small-group adventure formats across snowshoeing and cross-country skiing segments.
Europe winter tourism encompasses seasonal travel activity centered on cold-climate recreation, snow-dependent sports infrastructure, and thermal hospitality services operating typically between November and April at latitudes above 40 degrees north. Alpine skiing infrastructure demands groomed piste surfaces exceeding 30 kilometers per major resort, with snowmaking systems compensating for natural precipitation variability. Leisure travelers dominate volume across family-oriented Alpine destinations, while adventure seekers generate the fastest expansion in heli-skiing, ice climbing, and backcountry touring categories. Luxury resorts capture concentrated margin pools through bundled ski-in/ski-out access, spa thermal services, and gourmet mountain dining propositions.
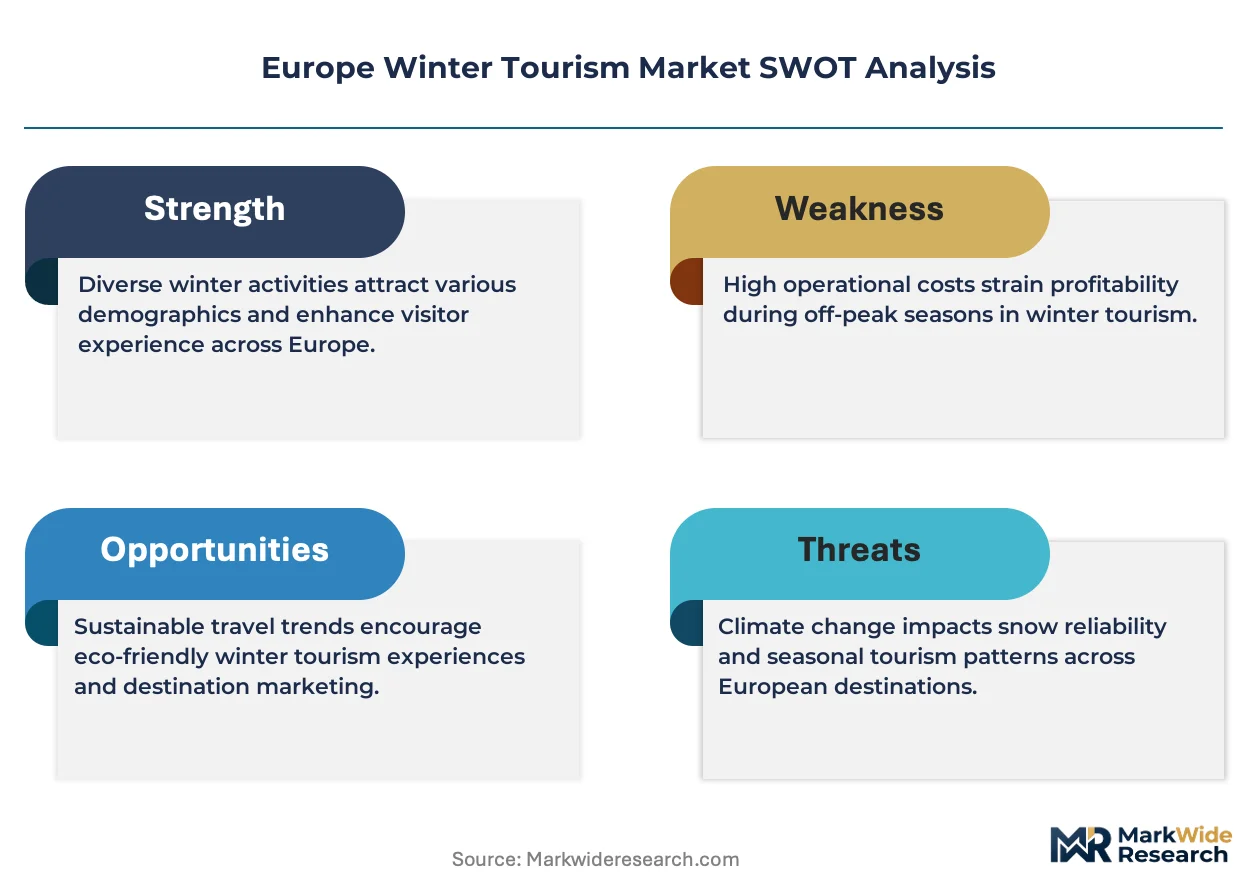
EMA climate-health monitoring intersects with ECHA chemical restrictions on slope treatments, while EU Green Deal carbon-border adjustments pressure aviation and ground transport providers serving mountain destinations. CE marking governs ski lift and cable car safety standards under the Machinery Directive, conditioning capital investment cycles for resort operators. Stakeholders must weigh decarbonization compliance costs against traveler willingness-to-pay premiums for certified sustainable winter experiences.
Market Dynamics
The EU Green Deal is compressing operational margins across Alpine hospitality clusters while simultaneously unlocking premium pricing for certified sustainable winter experiences. REACH compliance and carbon-border adjustments now condition capital allocation decisions for resort operators, transport providers, and slope maintenance contractors from the Pyrenees to the Scandinavian Arctic.
Growth Catalysts
- EU Green Deal carbon thresholds:Mandatory emission caps for ground transport and accommodation are accelerating fleet electrification and building retrofits across French, Austrian, and Swiss Alpine corridors.
- Adventure tourism infrastructure:Heli-skiing and backcountry touring operators are expanding guided access zones in response to documented demand surges from experience-seeking travelers.
- Nordic thermal hospitality:Finnish and Swedish Lapland properties are scaling ice-structure and Aurora-focused concepts to capture extended-season revenue beyond traditional ski calendars.
Market Restraints
- Energy input volatility:Snowmaking systems consume 30-50% of resort electricity budgets, exposing operators to wholesale power price swings across Alpine grid interconnections.
- CE marking compliance cycles:The Machinery Directive governs ski lift and cable car safety recertification, imposing multi-year capital lockup periods for infrastructure refresh programs.
- Natural precipitation variability:Declining snow reliability at elevations below 1,500 meters is compressing viable operating windows for lower-altitude French and Italian resorts.
Strategic Opportunities
- Romanian and Bulgarian Carpathians:Underdeveloped piste infrastructure and lower labor costs position these markets for mid-market positioning against saturated Western Alpine destinations.
- EU CSRD disclosure mandates:Mandatory sustainability reporting is creating first-mover advantage for early-certified operators to capture corporate travel procurement channels.
- Digital-physical convergence:Real-time snow condition apps integrated with dynamic booking platforms are compressing reservation lead times and yield management precision.
Industry Challenges
- Specialized mountain engineering talent:Shortages of certified lift mechanics and avalanche control specialists are constraining expansion timelines across multi-resort portfolios.
- REACH chemical substitution timelines:Slope maintenance crews face compressed windows to reformulate de-icing and grooming compounds before phased restrictions take effect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Winter Tourism Market |
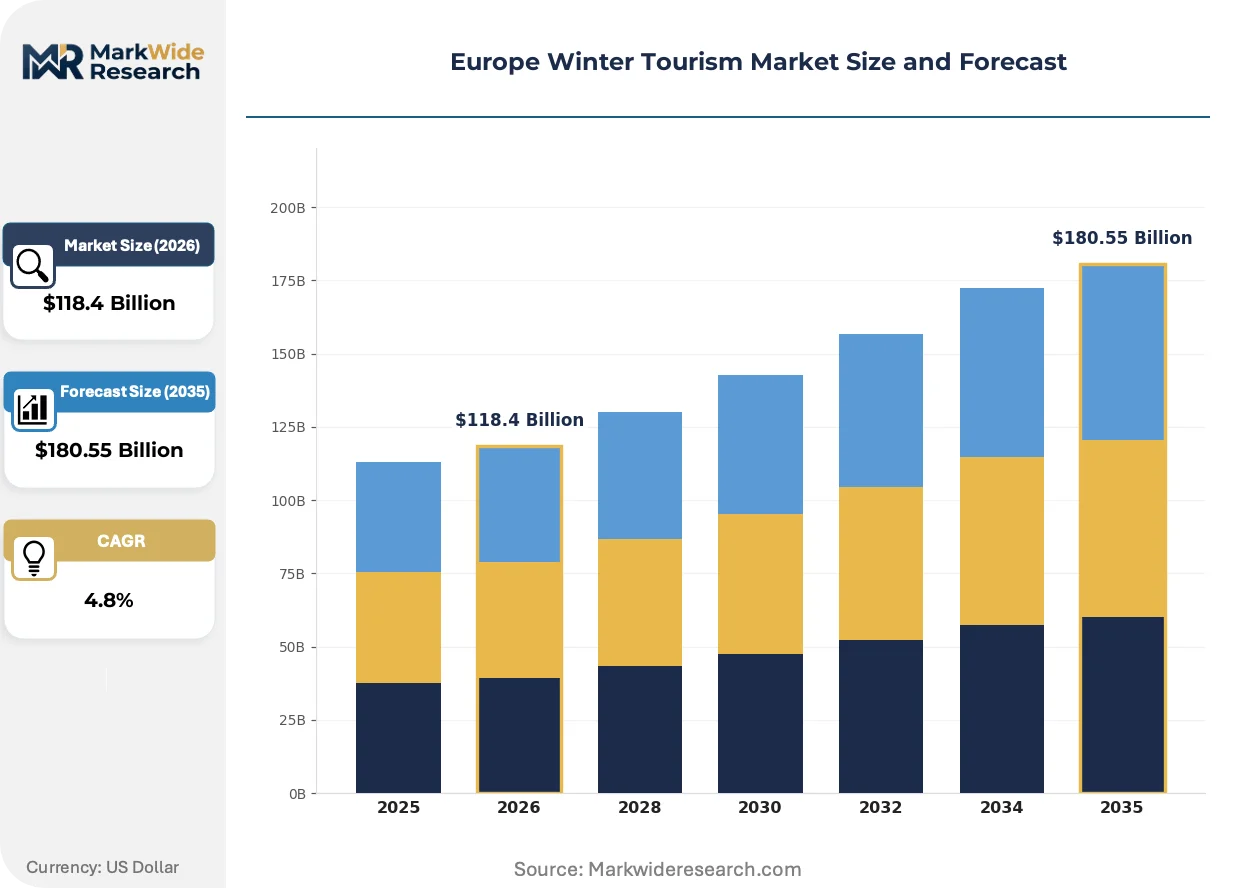
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $180.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tourist Type: Leisure Travelers, Adventure Seekers, Family Vacations, Couples Retreats Activity Type: Skiing, Snowboarding, Winter Hiking, Ice Skating Accommodation Type: Luxury Resorts, Budget Hotels, Lodges, Chalets Transport Mode: Air Travel, Train Services, Car Rentals, Shuttle Services |
| Companies Covered | Firebird Tours, Rick Steves, Nordic Visitor, TourRadar, Intrepid Travel, Contiki, Insight Vacations, ICEHOTEL, Exodus Adventure Travels, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Winter Tourism Market Shifts & Advancements
Digital infrastructure is rewiring how travelers discover, book, and experience winter destinations across European latitudes. Three converging forces—propulsion technology, regulatory disclosure, and service unbundling—are restructuring competitive positioning for resort operators and transport providers.
Battery-electric snow groomers and shuttle fleets are electrifying overnight slope preparation and guest transport across Austrian and Swiss test sites. Lech Zürs and St. Moritz pilot programs demonstrate 8-hour operational endurance on single charges. This transition is compressing diesel supply chain dependencies while requiring grid infrastructure investments that smaller resorts cannot self-finance.
REACH chemical restrictions intersect with EMA climate-health monitoring to impose layered compliance burdens on slope maintenance operations. The F-Gas Regulation phases down hydrofluorocarbon use in snowmaking refrigeration, forcing equipment replacement cycles. Alpine operators in France and Italy are consolidating procurement to spread compliance costs across multi-property portfolios.
Travelers are fragmenting package purchases into component bookings—separating accommodation, lift passes, equipment rental, and instruction. Online travel agencies and direct-to-consumer resort apps are disintermediating traditional tour operators. This unbundling is most pronounced among German and Dutch source markets, where price transparency tools have compressed booking windows to under 14 days pre-departure.
Europe Winter Tourism Market Segmentation
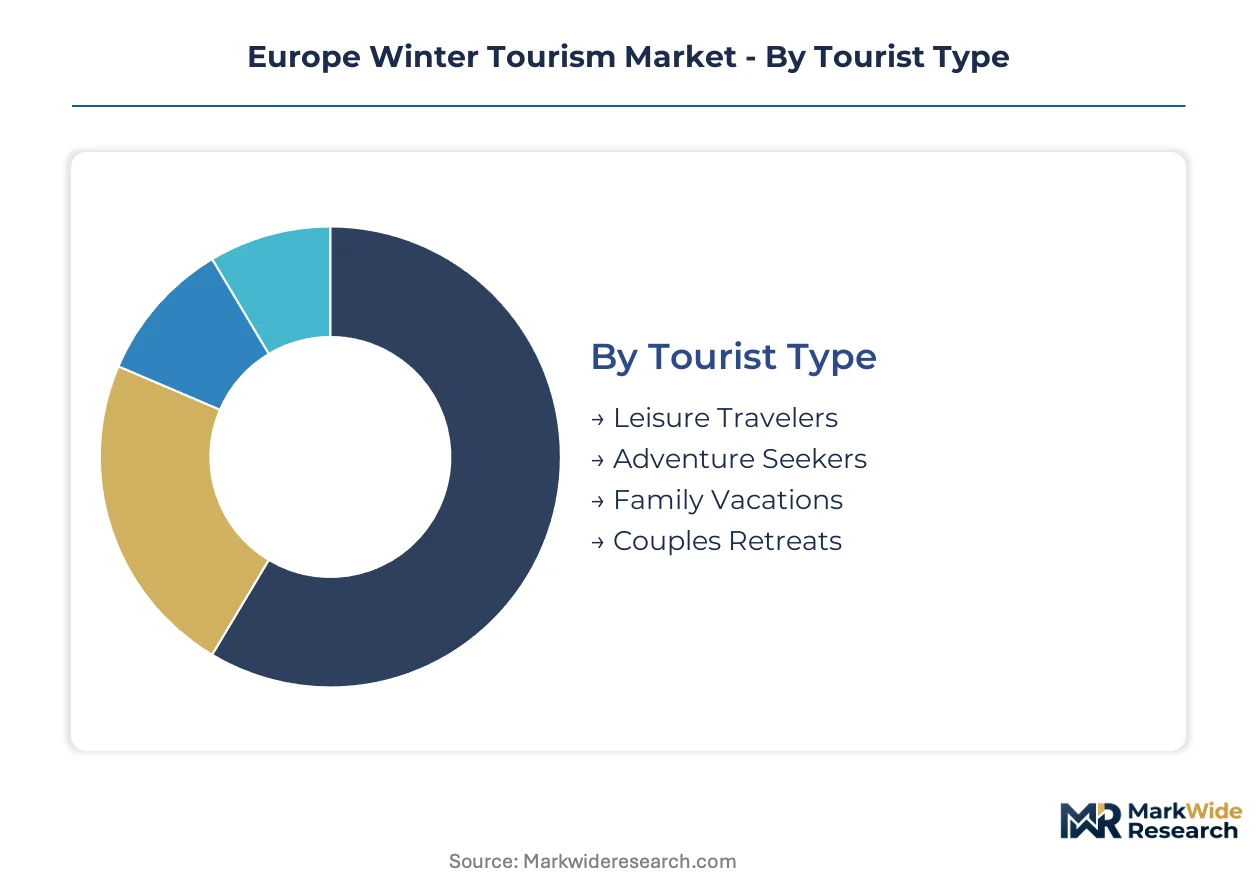
Winter tourism operators in Europe deploy differentiated service architectures to capture value across traveler psychographics, activity preferences, and accommodation tiers. Supply concentration varies sharply by segment, with Alpine corridor infrastructure dominating snow-dependent categories while Nordic thermal concepts anchor alternative winter experiences.
Tourist Type:
Operator investment concentrates disproportionately on high-yield traveler profiles that justify premium infrastructure spend across French, Austrian, and Swiss Alpine clusters.
- Leisure Travelers:This segment encompasses general vacationers prioritizing relaxation, scenic value, and accessible recreation over technical skill requirements. Demand concentrates across family-oriented Alpine destinations in France and Austria, where bundled ski-school and childcare services justify extended stays. Property developers in Chamonix and Kitzbühel optimize lift capacity and piste grooming to capture this volume base.
- Adventure Seekers:Experience-focused travelers pursuing heli-skiing, ice climbing, backcountry touring, and Arctic circle expeditions. Norwegian and Swedish Lapland operators scale guided access zones and ice-structure hospitality to serve this expanding cohort. EU Green Deal transport constraints are redirecting some demand toward rail-accessible adventure corridors.
- Family Vacations:Multi-generational groups requiring integrated childcare, beginner terrain, and non-ski activities. Swiss resorts in Valais and Graubünden concentrate dedicated family infrastructure.
- Couples Retreats:Adult pairs prioritizing thermal spa services, gourmet dining, and ski-in/ski-out convenience. Austrian Tyrol properties capture premium positioning through bundled wellness propositions.
Leisure travelers absorb the bulk of installed lift capacity; adventure seekers are expanding most quickly.
Activity Type:
Capital deployment patterns across European winter destinations reflect snow reliability gradients and equipment replacement cycles governed by CE marking requirements.
- Skiing:Alpine skiing infrastructure demands groomed piste surfaces exceeding 30 kilometers per major resort, with snowmaking systems compensating for precipitation variability. French Savoie and Haute-Savoie departments concentrate the highest density of premium groomed terrain. F-Gas Regulation compliance is accelerating snowmaking equipment refresh timelines.
- Snowboarding:Terrain park and halfpipe investments target younger demographics across Austrian and Swiss test sites. Demand clusters in purpose-built freestyle zones at Laax and Mayrhofen.
- Winter Hiking:Low-skill, equipment-light activity expanding across snow-reliable Nordic destinations. Finnish Lapland operators extend seasonality through marked trail networks.
- Ice Skating:Urban and resort-based rinks serving non-skiing companions and evening entertainment segments. Natural ice offerings in Alpine lake regions face climate volatility constraints.
Skiing retains dominant capital allocation; snowboarding shows steepest expansion trajectory among technical disciplines.
Accommodation Type:
Margin capture potential stratifies sharply across certification tiers, with EU CSRD disclosure mandates creating procurement advantages for early-certified sustainable properties.
- Luxury Resorts:Premium properties bundling ski-in/ski-out access, spa thermal services, and gourmet mountain dining. Swiss operators in St. Moritz and Zermatt command pricing premiums through exclusive piste access arrangements. Battery-electric shuttle pilots at Lech Zürs demonstrate decarbonization pathways for this tier.
- Budget Hotels:Price-sensitive lodging serving cost-conscious German and Dutch source markets. Properties cluster in lower-altitude French and Italian zones facing compressed snow windows.
- Lodges:Mid-market properties emphasizing authentic mountain character and regional cuisine. Romanian and Bulgarian Carpathians position against saturated Western Alpine alternatives.
- Chalets:Private rental inventory disintermediating traditional hospitality through direct-to-consumer platforms. Booking windows have compressed to under 14 days across this segment.
Luxury resorts capture concentrated margin pools; chalets are gaining share fastest through platform-enabled unbundling.
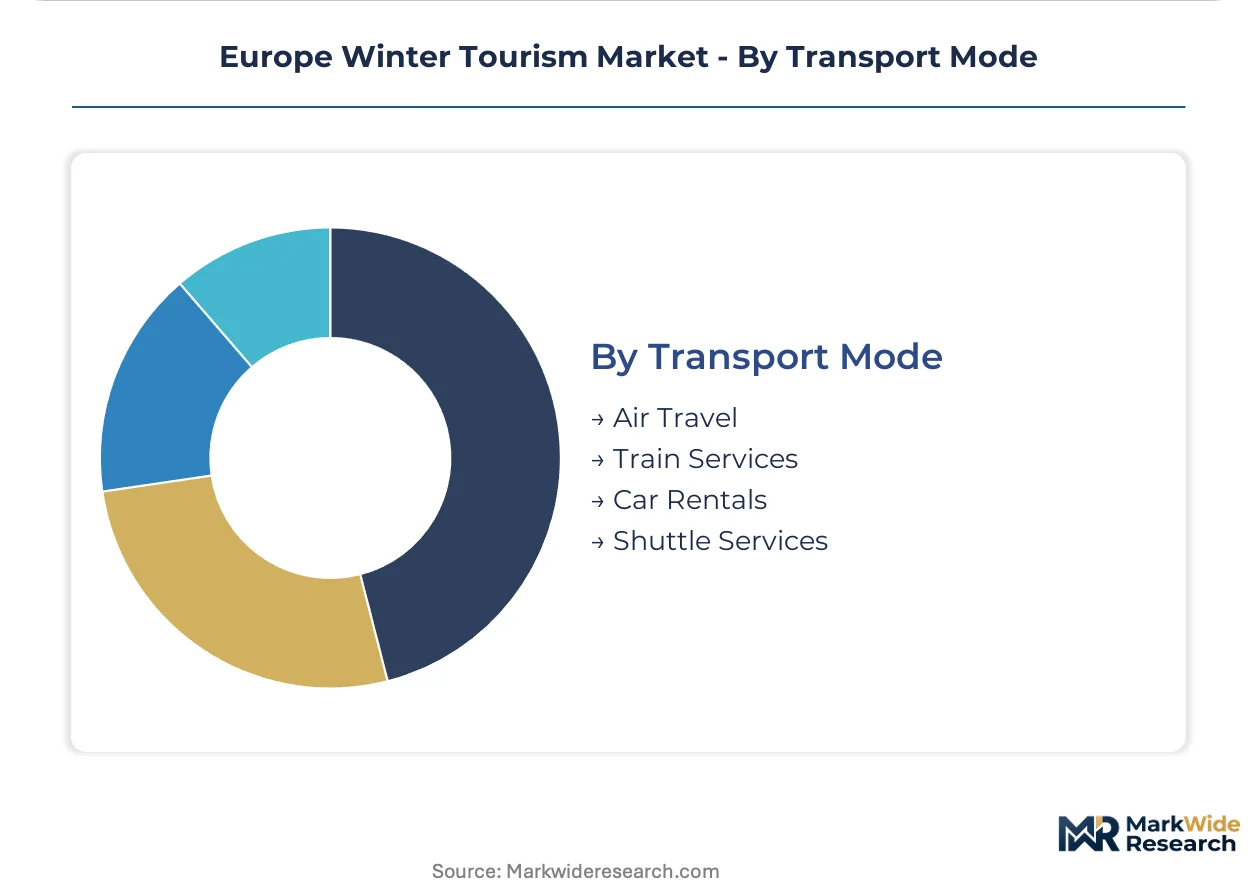
Transport Mode:
Carbon-border adjustments and fleet electrification mandates are restructuring ground transport economics across Alpine access corridors.
- Air Travel:Aviation serving long-haul and time-constrained travelers to Geneva, Innsbruck, and Salzburg gateways. EU Green Deal emission caps pressure route economics for secondary mountain airports.
- Train Services:Rail connectivity expanding through Alpine base tunnel projects and night-train restoration. Austrian Federal Railways and Swiss Federal Railways capture modal shift from short-haul aviation.
- Car Rentals:Flexible ground access for equipment-laden groups and multi-resort itineraries. Fleet electrification timelines lag due to charging infrastructure gaps in remote Alpine valleys.
- Shuttle Services:Dedicated resort transfers optimizing load factors and route efficiency. Battery-electric pilots demonstrate operational viability for flat-terrain airport corridors.
Air travel retains volume leadership for intercontinental arrivals; train services are climbing the fastest on intra-European routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpine special economic zones and mountain development districts concentrate winter tourism infrastructure investment across French, Austrian, and Swiss corridors. EU cohesion funds and national tourism development programs channel capital toward snow-reliable elevations above 1,500 meters. This geographic clustering reflects deliberate policy choices to concentrate lift infrastructure, thermal hospitality, and transport interconnections.
France
Leisure travelers from Paris and London drive volume across Savoie and Haute-Savoie departments. The EU Green Deal carbon thresholds accelerate building retrofit programs in Chamonix and Courchevel. Battery-electric shuttle pilots at Lech Zürs demonstrate operational pathways for premium Alpine properties seeking decarbonization certification.
Austria
Family vacation demand concentrates in Tyrol and Salzburg provinces with integrated childcare and beginner terrain. REACH compliance expands chemical management requirements for slope maintenance contractors serving Kitzbühel and St. Anton. Austrian Federal Railways captures modal shift through expanded night-train connectivity to Innsbruck gateways.
Switzerland
Luxury resort margins concentrate in Valais and Graubünden cantons through bundled ski-in/ski-out access and thermal spa services. CE marking under the Machinery Directive governs lift safety recertification cycles across Zermatt and St. Moritz infrastructure. Swiss Federal Railways integrates dynamic booking platforms with real-time snow condition apps.
Sweden
Adventure seekers generate fastest expansion for Northern Lights and Arctic circle expeditions in Swedish Lapland. EMA climate-health monitoring intersects with ECHA chemical restrictions on ice-structure hospitality operations. ICEHOTEL anchors premium positioning through permanent and seasonal ice-construction concepts near Kiruna.
Romania
Mid-market positioning opportunities emerge in Carpathian Mountain corridors with underdeveloped piste infrastructure and lower labor costs. EU CSRD disclosure mandates create first-mover advantage for early-certified operators in Brașov and Sinaia clusters. Private capital flows toward lodge-format properties competing against saturated Western Alpine alternatives.
Europe Winter Tourism Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across packaged tour, accommodation, and guided experience segments. Market structure shows moderate consolidation at the premium tier alongside fragmentation among regional itinerary operators and single-property hospitality concepts. Three archetypes dominate: integrated tour operators bundling transport and lodging, specialized Nordic and Arctic experience providers, and single-concept hospitality developers. Competitive moves center on geographic expansion into underdeveloped Eastern Alpine corridors and technology partnerships for dynamic yield management platforms.
Among Nordic-specialized operators, Nordic Visitor and ICEHOTEL exemplify contrasting approaches to Arctic winter tourism—one scaling itinerary breadth across Northern Lights packages, the other anchoring destination-specific ice-structure hospitality. Exodus Adventure Travels occupies a position within the small-group adventure archetype, competing on guided formats across snowshoeing and backcountry touring segments. These three represent strategic positioning options available to capital deploying into European winter tourism: itinerary specialization, concept hospitality, or activity-focused guided experiences.
| Leading Market Players |
|---|
| Firebird Tours |
| Rick Steves |
| Nordic Visitor |
| TourRadar |
| Intrepid Travel |
| Contiki |
| Insight Vacations |
| ICEHOTEL |
| Exodus Adventure Travels |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon thresholds gate both qualified supply and premium-tier pricing access across European winter tourism. Operators achieving certified sustainable status capture pricing premiums from corporate travel procurement channels, while non-compliant properties face margin compression from retrofit mandates and exclusion from preferred supplier lists.
Pricing Analysis
Short lead-time bookings command premium rates across Alpine and Nordic corridors, while extended inventory availability triggers discounting. Three-tier pricing structure across premium, standard, and economy levels stratifies by CSRD certification status and thermal amenity bundling. Price differentiation stems from EU Green Deal compliance tier and snow reliability elevation. Pricing pressure stems from energy input volatility affecting snowmaking operations. Budget-conscious German and Dutch source markets exhibit highest price sensitivity; luxury Swiss properties serving ultra-high-net-worth travelers show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Austrian and Swiss lift manufacturers dominating CE-marked cable car systems. France, Austria, and Switzerland concentrate snow groomer and snowmaking equipment production. Raw material dependencies include specialized steel alloys for lift cables, hydrofluorocarbon refrigerants for snowmaking, and lithium-ion cells for electric shuttle pilots. Supply chain risk centers on F-Gas Regulation phase-down timelines forcing accelerated equipment replacement. Distribution runs through multi-resort procurement consortia and direct OEM relationships with Alpine hospitality groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European winter tourism is transitioning from diesel-dependent slope operations to battery-electric infrastructure. Battery-electric snow groomers and shuttle fleets are displacing legacy diesel equipment across Austrian and Swiss test sites.
For Market Incumbents: Lock in snow-reliable elevation advantages above 1,500 meters through strategic terrain lease extensions. Consolidate procurement across multi-property portfolios to spread REACH compliance and F-Gas equipment replacement costs. Battery-electric infrastructure investment represents the critical lever for maintaining premium-tier pricing access against emerging Carpathian competitors. For New Entrants and Emerging Players: EU CSRD disclosure mandates in Romania and Bulgaria open a window for first-mover sustainability certification in underdeveloped Carpathian corridors. Target mid-market lodge formats in Brașov and Sinaia clusters where Western Alpine saturation redirects price-sensitive demand. Direct-to-consumer platform strategies bypass incumbent tour operator intermediation. For Investors and Strategic Acquirers: Night-train service restoration announcements between German source markets and Austrian gateways are the leading indicator that rail-modal shift is accelerating. Acquire properties with integrated thermal spa assets and existing grid infrastructure for electric fleet conversion. Watch battery-electric groomer endurance benchmarks as the signal for viable large-scale capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Fleet Conversion | Lech Zürs pilots demonstrate 8-hour operational endurance, validating overnight slope preparation without diesel dependency. |
| CSRD Early Certification Program | First-mover operators capture corporate travel procurement channels ahead of mandatory disclosure timelines. |
| Multi-Resort Procurement Consortium | Consolidated buying power spreads REACH chemical substitution and F-Gas equipment compliance costs across portfolios. |
| Rail-Modal Shift Partnership | Austrian Federal Railways night-train expansion captures German and Dutch source market demand from short-haul aviation. |
| Ice-Structure Hospitality Expansion | ICEHOTEL's permanent and seasonal concepts anchor premium positioning in Swedish Lapland's Aurora expedition segment. |
Research Methodology
EU statistical databases, national tourism board filings, and Alpine resort operator disclosures formed the secondary backbone of this analysis. Primary interviews with resort operations directors, lift maintenance engineers, slope grooming contractors, and sustainability compliance officers supplemented secondary validation. Bottom-up property-level capacity data and top-down national tourism expenditure statistics were triangulated to construct market estimates.
Bottom-up modeling aggregated individual resort capacity, pricing, and utilization assumptions across the projection horizon. Segmentation dimensions included tourist type, activity category, accommodation tier, and transport mode. CAGRs were derived from slope infrastructure investment cycles, snow reliability trends, and regulatory compliance cost trajectories. Forecast inputs incorporated EU Green Deal implementation schedules and F-Gas Regulation phase-down timelines.
The model assumes a particular technology adoption path for battery-electric slope equipment; alternative pathways for hydrogen fuel cell groomers would alter the outlook. Forecasts reflect assumptions about snow reliability persistence, energy price volatility, and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
South Africa Faith-Based Tourism Market
Destination Management and Attractions
SAVE Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
Europe Theme Park Market
Destination Management and Attractions
Amusement Parks Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
South Africa Casino Tourism Market
Destination Management and Attractions
Germany Culinary Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
Thailand Sustainable Tourism Market