
 Agro-Rural Tourism Market | 2026-2036
Agro-Rural Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Agro-Rural Tourism Market Outlook
The capital-intensity divergence between asset-heavy farm estate operators and digital platform intermediaries is reorganizing competitive tiers across the sector. Feather Down Farms sustains premium positioning through controlled glamping infrastructure across European farmland. WWOOF International operates a membership exchange model that minimizes fixed-asset exposure while capturing global volunteer flow. Harvest Hosts leverages RV-hosting partnerships to extend network reach without property ownership burdens.
Agro-rural tourism encompasses structured visitation to working agricultural environments where guests participate in or observe food production, land stewardship, and rural craft practices, typically involving overnight accommodation with direct host engagement and seasonal activity calendars tied to planting and harvest cycles. The service model generates ancillary revenue streams for primary producers while delivering educational and experiential value to visitors seeking alternatives to conventional hospitality. Farm Stays command the largest share of current booking volume given their lower operational complexity and broader demographic appeal, though Culinary Tours are attracting disproportionate margin expansion as food-provenance storytelling commands premium pricing. Educational Groups represent the fastest-growing client category as schools and universities formalize farm-based curricula and credit-bearing field programs.
EU Green Deal frameworks and F-Gas Regulation compliance requirements are reshaping land-use incentives across European member states, with biodiversity corridor mandates creating new revenue pathways for conservation-integrated tourism access. The US Department of Agriculture and state-level agritourism liability statutes in California, Vermont, and Texas govern operator insurance obligations and visitor safety protocols that determine market entry feasibility. Stakeholders must monitor evolving subsidy eligibility criteria that increasingly tie agricultural support payments to public access and environmental education deliverables.
Market Dynamics
EU Green Deal biodiversity restoration mandates are redirecting agricultural subsidy flows toward land-use models that integrate visitor access, forcing traditional farm operators to build hospitality capabilities or lose payment eligibility.
Growth Catalysts
- EU Green Deal frameworks:Biodiversity corridor mandates in member states create new revenue pathways for conservation-integrated tourism access, tying agricultural support payments to public engagement deliverables.
- Educational Groups:Schools and universities are formalizing farm-based curricula and credit-bearing field programs, generating structured booking demand with extended stay durations.
- Tuscany's agriturismo networks:Mature operational templates from Italy's leading region are exportable to emerging markets seeking proven hospitality-integrated farming models.
Market Restraints
- Seasonal revenue concentration:Planting and harvest cycle dependence creates cash flow volatility requiring working capital reserves that smallholder operators struggle to maintain.
- Liability insurance escalation:State-level agritourism statutes in California, Vermont, and Texas impose rising coverage obligations that deter market entry for asset-light entrants.
- Land access competition:Urban sprawl and renewable energy siting are reducing available farmland near metropolitan demand centers, elevating property acquisition costs.
Strategic Opportunities
- F-Gas Regulation compliance requirements:Refrigeration and cooling infrastructure upgrades on dairy and produce farms create co-investment openings for tourism accommodation buildouts.
- RV-hosting partnerships:Asset-light network extension through recreational vehicle hosting agreements avoids property ownership burdens while capturing mobile traveler segments.
- Digital platform intermediation:Booking and experience curation platforms can capture margin from fragmented farm supply without assuming fixed-asset exposure.
Industry Challenges
- Hospitality-service skill gaps:Primary agricultural producers lack guest management, food safety certification, and digital marketing capabilities required for consistent experience delivery.
- Certification timeline compression:Organic, biodiversity, and accessibility certifications require multi-year compliance periods that delay revenue recognition from premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agro-Rural Tourism Market |
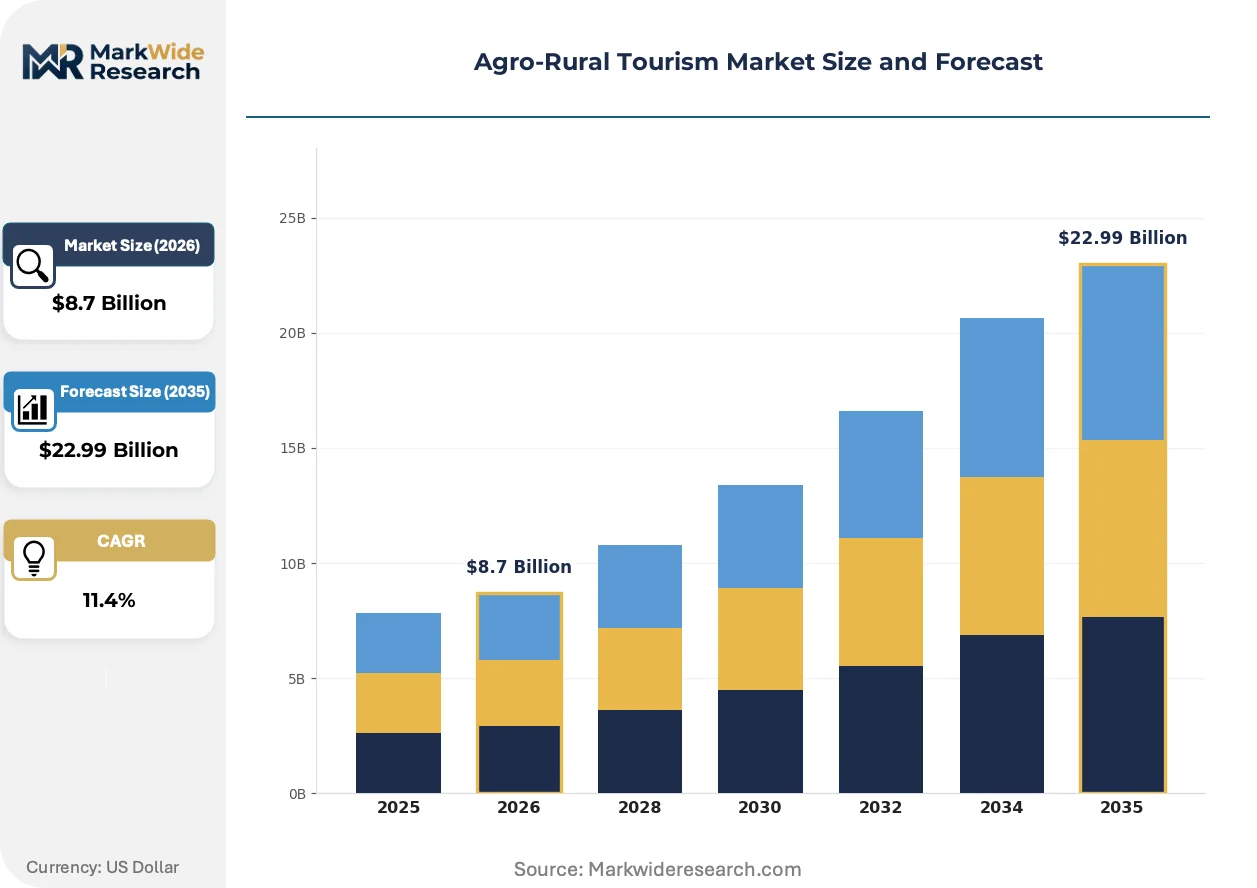
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Agricultural Experiences, Farm Stays, Culinary Tours, Nature Trails Client Type: Families, Couples, Solo Travelers, Educational Groups Activity Type: Organic Farming, Wine Tasting, Animal Husbandry, Handicraft Workshops Destination Type: Rural Villages, Farms, Eco-Lodges, Heritage Sites |
| Companies Covered | Farm Stay USA, Harvest Hosts, Feather Down Farms, WWOOF International, Farm Stay UK, Liberty Hill Farm, Stita Group, Select Holidays, Agritours Canada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agro-Rural Tourism Market Strategic Shifts
Glamping infrastructure is penetrating working farmland as operators seek premium positioning without conventional hotel construction costs. Mobile accommodation units and modular hospitality systems are enabling faster deployment cycles.
Controlled glamping pods with off-grid energy and water systems are supplanting traditional farmhouse bed-and-breakfast models. Estate operators in France and the Netherlands are adopting these units to minimize planning permission delays. The shift is compressing capital recovery timelines from seven-year hospitality buildouts to eighteen-month infrastructure deployments.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration infrastructure replacement across dairy and produce operations. Member state rural development programs are bundling cooling upgrades with visitor facility grants. Italian and Spanish cooperatives are capturing these incentives to install farm-store and tasting-room additions.
Direct-to-farm booking behavior is displacing intermediary-dependent reservation patterns among repeat visitors. Established agriturismo networks in Portugal and Greece are investing in proprietary reservation systems and loyalty programs. This channel shift is most visible in wine-region clusters where guest relationships drive annual return visits.
Agro-Rural Tourism Market Segmentation
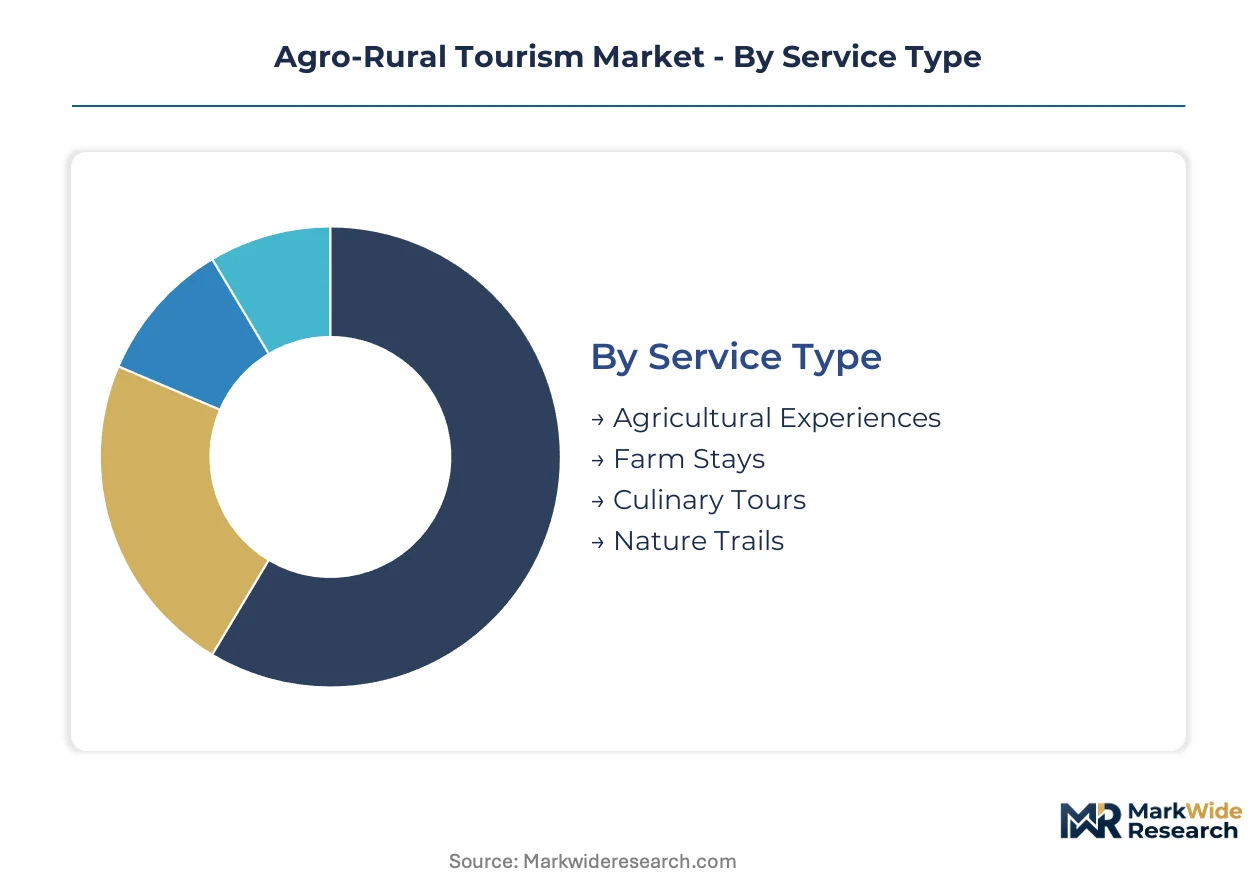
Segmentation in agro-rural tourism reveals divergent operational requirements across service models and visitor profiles. Each category carries distinct infrastructure demands, seasonal patterns, and margin structures that reshape operator investment priorities.
Service Type:
Domestic European demand concentrates in Farm Stays and Culinary Tours, while Agricultural Experiences draw stronger cross-border visitation from North American and Asian source markets.
- Farm Stays:Overnight accommodation in working farm environments with direct host engagement and seasonal activity calendars. Tuscany and Provence clusters command premium pricing through mature hospitality standards. Families with children dominate booking volume, seeking multi-day immersion with predictable amenity provisioning.
- Culinary Tours:Structured food-provenance experiences spanning harvest participation, processing observation, and guided tasting protocols. Wine regions in Portugal and Greece generate disproportionate margin expansion through storytelling-driven premium positioning. Repeat visitation rates exceed other service categories.
- Agricultural Experiences:Day-visit programming without overnight accommodation, focused on planting, harvest, or livestock management observation. Lower operational complexity attracts smallholder operators with limited hospitality infrastructure.
- Nature Trails:Self-guided or facilitated walking routes through agricultural landscapes with interpretive signage. Minimal capital requirements enable rapid deployment across fragmented landholdings.
Farm Stays hold the largest share; momentum sits with Culinary Tours.
Client Type:
Cost-tier stratification separates extended-stay Educational Groups from shorter-duration leisure segments, with divergent booking channel and payment term requirements.
- Educational Groups:Schools and universities booking structured curricula with credit-bearing field components. Extended stay durations and advance deposit structures reduce operator working capital volatility. EU Green Deal subsidy eligibility increasingly requires public engagement deliverables that this segment satisfies.
- Families:Multi-generational units seeking activity diversity and child-safe infrastructure. Weekend and school-holiday concentration creates peak-load management challenges for operators.
- Couples:Premium-positioned seekers of romantic rural immersion with privacy emphasis. Off-peak booking patterns help operators smooth seasonal revenue curves.
- Solo Travelers:Individual visitors prioritizing flexibility and self-directed programming. WWOOF International and similar exchange platforms capture this segment through membership models minimizing fixed-asset exposure.
Families hold the largest share; Educational Groups are climbing the fastest.
Activity Type:
Volume concentration in Wine Tasting reflects established regional clustering, while supply scarcity in Handicraft Workshops creates margin differentiation.
- Wine Tasting:Vineyard visitation with structured cellar tours and guided sampling protocols. Portugal's Douro Valley and Greece's Peloponnese operate established networks with exportable operational templates.
- Organic Farming:Participation in certified organic production with compliance documentation requirements. Multi-year certification timelines delay revenue recognition from premium positioning.
- Animal Husbandry:Direct engagement with livestock operations spanning dairy, poultry, and fiber production. Liability insurance escalation under state-level agritourism statutes in California, Vermont, and Texas constrains smallholder entry.
- Handicraft Workshops:Instruction in rural craft practices including textile, pottery, and food preservation techniques. Limited qualified instructor supply restricts network expansion.
Wine Tasting holds the largest share; momentum sits with Organic Farming.
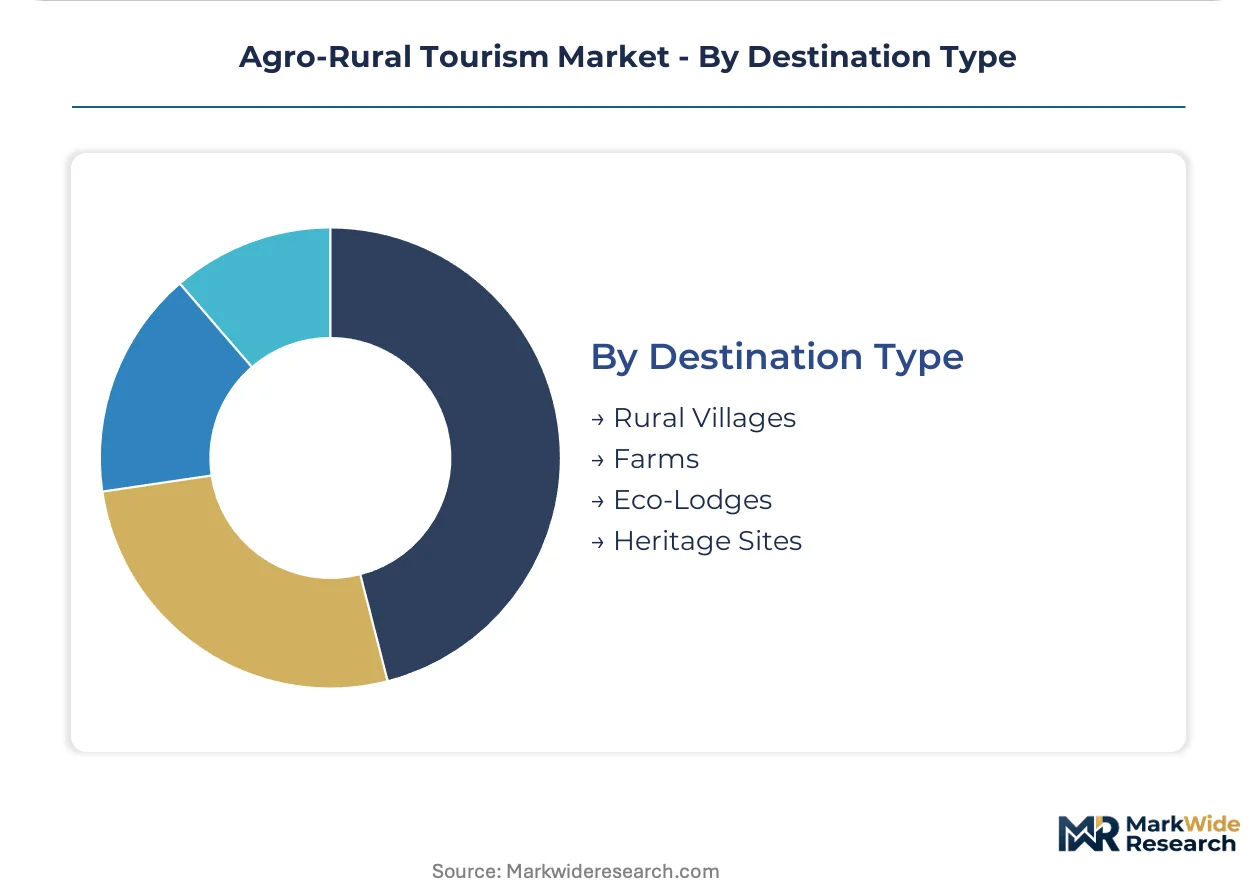
Destination Type:
Maturity gradients separate established Farm networks from emerging Eco-Lodge supply, with Heritage Sites requiring specialized conservation-integrated access protocols.
- Farms:Working agricultural properties with integrated visitor accommodation and activity programming. Italy's agriturismo networks provide mature operational templates now exported to emerging markets.
- Eco-Lodges:Purpose-built sustainable accommodation with minimal environmental footprint construction. Glamping infrastructure penetration is compressing capital recovery timelines from seven-year buildouts to eighteen-month deployments.
- Rural Villages:Settlement-based tourism with distributed accommodation across multiple host properties. Coordination complexity challenges experience standardization.
- Heritage Sites:Historically significant agricultural properties with conservation-access integration requirements. EU Green Deal biodiversity corridor mandates create new revenue pathways for conservation-integrated tourism access.
Farms hold the largest share; Eco-Lodges are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tuscany commands premium pricing power that exceeds comparable farm-stay offerings in Portugal's Alentejo by margins exceeding forty percent. This asymmetry reflects mature hospitality standards and exportable operational templates rather than intrinsic land-value differentials.
Italy
Educational Groups from German and Dutch secondary schools drive structured booking demand through Tuscany's agriturismo networks. EU Green Deal biodiversity corridor mandates redirect CAP subsidy flows toward properties integrating visitor access protocols. The Chianti cluster compresses capital recovery timelines through glamping infrastructure deployments replacing seven-year conventional buildouts.
France
Provence wine estates attract disproportionate margin expansion through culinary storytelling and harvest participation programming. F-Gas Regulation compliance requirements accelerate refrigeration infrastructure replacement, with rural development programs bundling cooling upgrades with visitor facility grants. The Luberon sub-region exhibits fastest adoption of controlled glamping pods with off-grid systems.
United States
RV-hosting partnerships capture mobile traveler segments without property ownership burdens, extending network reach across fragmented farmland supply. USDA agritourism liability statutes in California, Vermont, and Texas impose rising insurance coverage obligations that deter smallholder market entry. The Texas Hill Country cluster concentrates Harvest Hosts partnerships around winery and orchard properties.
Portugal
Direct-to-farm booking behavior displaces intermediary-dependent reservation patterns among repeat visitors to Douro Valley wine estates. EU Green Deal frameworks tie agricultural support payments to public engagement deliverables satisfied by educational programming. Proprietary reservation systems and loyalty programs anchor guest relationships driving annual return visitation.
Spain
Andalusian olive estate operators leverage organic farming certification timelines to justify premium positioning despite multi-year compliance delays. F-Gas Regulation phase-down schedules create co-investment openings for tourism accommodation buildouts on dairy and produce operations. The Sierra de Aracena cluster exports operational templates to emerging Latin American markets.
Agro-Rural Tourism Market Competitive Environment
Concentration sits with digital platform intermediaries that minimize fixed-asset exposure while capturing margin from fragmented farm supply. The vendor base distributes across asset-heavy farm estate operators, membership exchange networks, and booking platform intermediaries. Three strategic archetypes dominate: controlled infrastructure deployers, asset-light network extenders, and experience-curation platforms. Competitive moves center on geographic network expansion through partnership structures and proprietary reservation system development to displace third-party booking dependencies.
Within the asset-heavy infrastructure tier, Feather Down Farms sustains premium positioning through controlled glamping deployments across European farmland. WWOOF International occupies the membership exchange archetype, capturing global volunteer flow with minimal capital commitment. Harvest Hosts anchors the asset-light network extension model, leveraging RV-hosting partnerships to reach mobile traveler segments without assuming property ownership burdens. These three represent divergent responses to the capital-intensity tension reshaping competitive tiers.
| Leading Market Players |
|---|
| Farm Stay USA |
| Harvest Hosts |
| Feather Down Farms |
| WWOOF International |
| Farm Stay UK |
| Liberty Hill Farm |
| Stita Group |
| Select Holidays |
| Agritours Canada |
| Others |
Value Chain & Pricing Dynamics
Glamping infrastructure substitution for conventional farmhouse bed-and-breakfast models is simultaneously compressing capital recovery timelines from seven-year hospitality buildouts to eighteen-month deployments and redrawing supply geography toward modular accommodation fabricators in France and the Netherlands. This input shift feeds back into pricing economics by lowering fixed-asset barriers for smallholder operators while concentrating premium capture among controlled-infrastructure deployers.
Pricing Analysis
The customization-premium spread separates configured-to-order culinary storytelling experiences from standardized farm-stay accommodation, with wine-region operators in Portugal and Greece commanding substantial premiums through harvest participation programming. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and seasonal timing, with organic and biodiversity credentials justifying upper-tier positioning. Cost compression in standard-tier farm stays is intensifying because liability insurance escalation under state-level agritourism statutes in California, Vermont, and Texas elevates operating overhead. Educational Groups exhibit lowest price sensitivity due to advance deposit structures and extended stay durations, while Solo Travelers through membership exchange platforms drive economy-tier volume.
Supply Chain Analysis
Port congestion on Mediterranean container lanes elevates inbound logistics costs for modular glamping units and off-grid energy systems sourced from Chinese and Turkish manufacturers. Supply concentrates in Italy for mature agriturismo operational templates, France for controlled glamping pod fabrication, and the Netherlands for sustainable water management systems. Raw material dependencies rest on engineered timber composites, photovoltaic arrays, and composting sanitation infrastructure. Single-source vulnerability runs through European glamping pod fabricators with limited alternative supplier qualification. Distribution runs through digital platform intermediaries capturing margin from fragmented farm supply without assuming fixed-asset exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Educational Groups and direct-to-farm repeat visitors as intermediary-dependent reservation patterns fragment, with consolidated demand from German and Dutch secondary schools compressing payment terms and elevating service-standard requirements.
For Market Incumbents: Shield premium positioning through proprietary reservation system development that displaces third-party booking dependencies, particularly in Tuscany and Provence clusters where guest relationships drive annual return visits. Certification investment in organic and biodiversity credentials creates defensive moats against asset-light entrants, while backward integration into glamping pod fabrication reduces exposure to Mediterranean logistics chokepoints.
For New Entrants and Emerging Players: Solo Traveler service-layer gaps in handicraft workshop instruction and self-directed nature trail programming present white-space targets where qualified instructor scarcity restricts incumbent network expansion. The Texas Hill Country and Sierra de Aracena clusters offer most penetrable geography given RV-hosting partnership models that extend network reach without property ownership burdens. A membership-exchange go-to-market angle minimizes fixed-asset exposure while capturing global volunteer flow.
For Investors and Strategic Acquirers: Capital is best deployed toward asset-light digital platform intermediaries with demonstrated geographic network expansion through partnership structures rather than controlled infrastructure deployers facing capital-intensity divergence pressures. Long-term viability across the five-to-ten year window favors platform archetypes capturing margin from fragmented supply without assuming seasonal revenue concentration risks. The signal to watch is EU Green Deal subsidy eligibility criteria evolution, as tightening biodiversity corridor mandates could accelerate consolidation among traditional farm operators lacking hospitality capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Reservation System Development | Direct-to-farm booking displacement of intermediary-dependent patterns anchors guest relationships in wine-region clusters. |
| Glamping Infrastructure Deployment | Modular accommodation adoption compresses capital recovery timelines from seven-year buildouts to eighteen-month deployments. |
| Certification Investment Program | Organic and biodiversity credential acquisition justifies premium positioning despite multi-year compliance delays. |
| RV-Hosting Partnership Network | Asset-light extension captures mobile traveler segments across fragmented farmland supply without property ownership burdens. |
| Educational Curriculum Integration | Structured school and university programming satisfies EU Green Deal public engagement deliverables tied to subsidy eligibility. |
Study Parameters
A standing panel of agriturismo network operators, farm estate hospitality directors, educational group procurement coordinators, and glamping infrastructure fabricators provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against EU rural development program filings, F-Gas Regulation compliance databases, state-level agritourism liability statutes, and agriturismo association membership records. Bottom-up property-level revenue modeling and top-down regional tourism expenditure triangulation anchored market size estimation.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation dimensions spanning service type, client category, activity focus, and destination archetype. CAGRs were derived from fitted growth curves incorporating EU Green Deal subsidy trajectory assumptions, educational group booking formalization rates, and glamping infrastructure penetration curves. Forecast inputs included seasonal occupancy patterns, certification timeline compression effects, and direct-to-farm channel shift velocities.
Forecasts assume regulatory continuity in EU Green Deal biodiversity corridor mandates and F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling subsidy eligibility and infrastructure replacement co-investment pathways. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Brazil Faith Based Tourism Market
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
North America Amusement Parks Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
Egypt Faith Based Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
Germany Culinary Tourism Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market