
 India Faith Based Tourism Market | 2026-2036
India Faith Based Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
India Faith Based Tourism Market Foresight
Millennial pilgrims is bifurcating the traditional faith-based traveler base as younger Indians blend spiritual objectives with experiential travel expectations. MakeMyTrip leverages its digital platform dominance to capture this demographic through app-based pilgrimage bookings. Thomas Cook (India) Limited anchors its competitive position with curated heritage circuits that integrate guided temple visits. Yatra Online Pvt Ltd differentiates via regional language interfaces that penetrate Tier-2 and Tier-3 departure cities.
India faith based tourism encompasses organized travel to sacred destinations for worship, ritual participation, or spiritual enrichment, typically involving multi-day itineraries with accommodation, transport, and guided services at temples, shrines, and historical religious sites. The segment operates through a booking infrastructure that combines offline agent networks with rapidly scaling mobile-first reservation platforms. Pilgrimage packages command the largest current revenue pool due to high-frequency repeat visitation patterns at sites like Tirupati and Vaishno Devi. Spiritual retreats represent the fastest-expanding category as wellness-oriented consumers seek monastery stays and meditation programs. Luxury experiences within tour packages capture disproportionate margins through premium accommodation and personalized darshan arrangements.
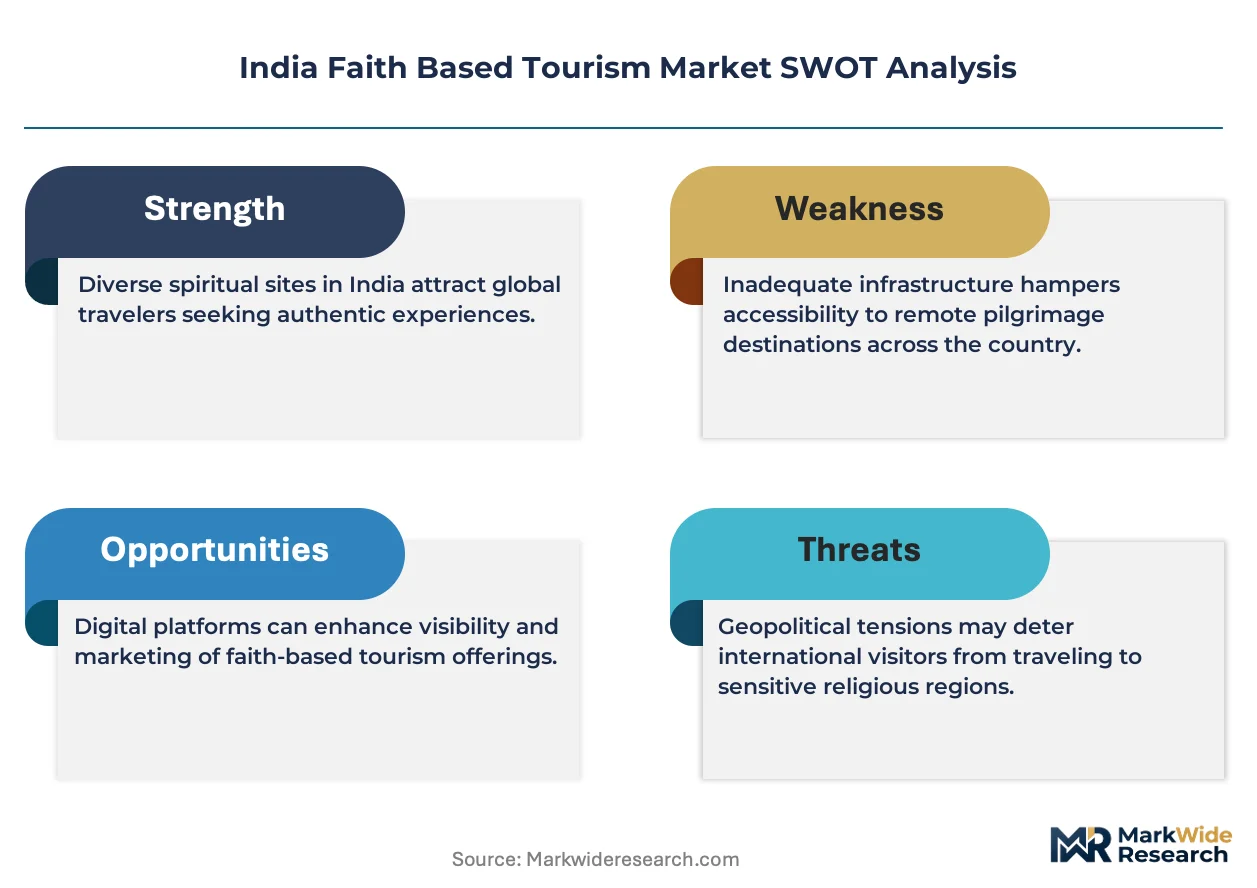
The Ministry of Tourism's PRASAD scheme and state-level temple development boards shape infrastructure investment priorities around designated sacred circuits. BIS hospitality standards and state tourism department licensing requirements govern accommodation quality and guide certification near major religious destinations. Stakeholders must monitor how Swadesh Darshan 2.0 fund allocations redirect visitor flows toward emerging sacred corridors and away from overcrowded legacy sites.
Market Dynamics
The PRASAD scheme's infrastructure investments are concentrating visitor flows around designated sacred circuits while digital booking platforms fragment the traditional offline agent network across Tier-2 and Tier-3 departure cities.
Growth Catalysts
- Millennial spiritual travel:Younger Indian travelers blend pilgrimage objectives with experiential expectations, expanding demand for curated heritage circuits with guided temple visits and wellness integration.
- PRASAD scheme infrastructure:The Ministry of Tourism's designated sacred corridors receive upgraded accommodation, transport connectivity, and sanitation facilities that expand site capacity.
- Regional language digitization:Vernacular mobile interfaces penetrate non-urban origin markets, converting first-time digital bookers into recurring pilgrimage customers.
Market Restraints
- Seasonal demand compression:Religious calendars concentrate 70% of annual footfall into narrow festival windows, straining fixed infrastructure investments and yielding low annual utilization rates.
- Accommodation supply bottlenecks:Heritage preservation restrictions around core temple zones limit new hotel construction, capping room inventory expansion at high-demand sites like Varanasi and Tirupati.
- State-level regulatory fragmentation:Divergent licensing requirements across Uttar Pradesh, Tamil Nadu, and Maharashtra temple boards create compliance complexity for multi-circuit operators.
Strategic Opportunities
- Emerging sacred corridors:Swadesh Darshan 2.0 fund allocations redirect infrastructure toward underdeveloped circuits in Madhya Pradesh and Gujarat, creating first-mover positioning for package operators.
- Spiritual retreat expansion:Monastery stays and meditation programs attract wellness-oriented consumers seeking extended-duration bookings with higher per-traveler yields than conventional pilgrimage.
- Luxury experience tier:Premium accommodation and personalized darshan arrangements capture disproportionate margins from high-net-worth devotees seeking queue bypass and exclusive access.
Industry Challenges
- Guide certification gaps:State tourism departments lack standardized training protocols for religious site interpreters, producing variable service quality that damages repeat booking rates.
- Legacy system integration:Offline agent networks resist platform onboarding due to commission structure disputes, slowing the shift toward unified inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Faith Based Tourism Market |
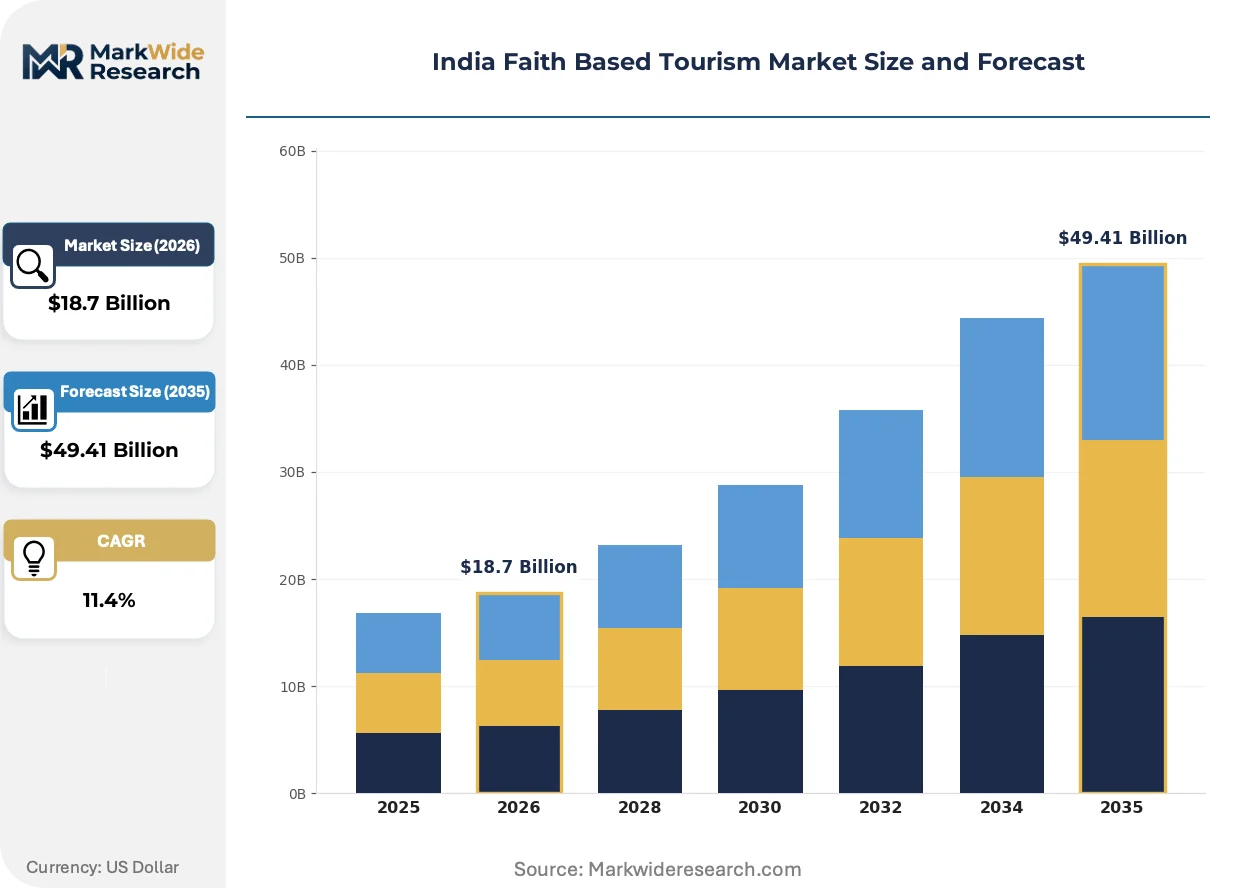
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Pilgrimage, Spiritual Retreats, Cultural Tours, Religious Festivals Destination: Temples, Shrines, Historical Sites, Sacred Cities Travel Purpose: Religion, Spiritual Growth, Cultural Experience, Community Engagement Tour Package: Group Tours, Customized Packages, Budget Options, Luxury Experiences |
| Companies Covered | MakeMyTrip, Thomas Cook (India) Limited, Cox & Kings Ltd, Mahindra Holidays & Resorts India Limited, Yatra Online Pvt Ltd, Cleartrip Private Limited, Expedia, SOTC Travel Limited, Kesari Tours, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Faith Based Tourism Market Shifts & Advancements
Digital infrastructure is fragmenting how pilgrimage packages are discovered, booked, and experienced, creating parallel tracks for tech-enabled convenience seekers and tradition-oriented offline customers.
Mobile-first reservation platforms are fragmenting the pilgrimage booking landscape. Tier-2 city millennials adopt app-based pilgrimage packages at accelerating rates, compressing the traditional 7-14 day advance booking window to same-day confirmations. This compression is forcing offline agents to adopt hybrid models or cede volume to digital intermediaries.
The Ministry of Tourism's PRASAD scheme and state temple development boards are mandating BIS hospitality standards near sacred sites. Accommodation quality requirements now govern licensing renewals for properties within designated radii of major religious destinations. Uttar Pradesh and Tamil Nadu temple boards are responding with accelerated certification timelines for pre-existing properties.
Spiritual travelers are unbundling package components and assembling custom itineraries through direct supplier relationships. Monastery direct bookings and local transport apps displace bundled offerings for repeat pilgrims familiar with specific sites. This disintermediation is most visible among domestic millennial travelers on secondary circuits in Gujarat and Rajasthan.
India Faith Based Tourism Market Segmentation
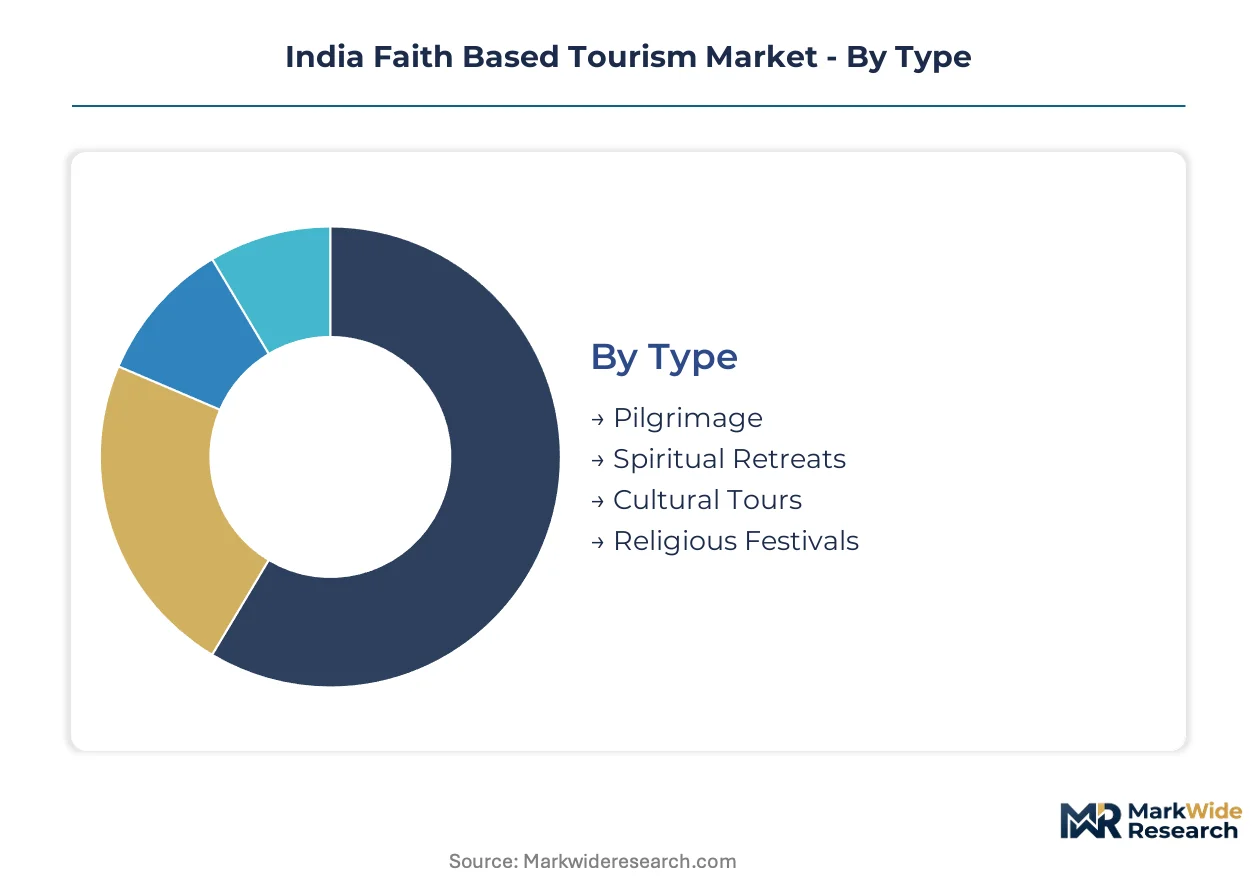
Segmentation in India's faith-based tourism market reveals how spiritual objectives, destination types, and service tiers create distinct competitive arenas with varying margin profiles and booking behaviors. Understanding these divisions enables operators to align inventory investments with actual traveler decision criteria rather than assumed homogeneity.
Type:
Pilgrimage packages face intensifying substitution pressure from spiritual retreats as wellness-oriented travelers trade ritual participation for extended contemplative stays.
- Pilgrimage:High-frequency repeat visitation patterns at Tirupati and Vaishno Devi drive volume concentration. Domestic millennial travelers in Uttar Pradesh and Maharashtra circuits now blend darshan objectives with experiential add-ons, compressing traditional booking windows.
- Spiritual Retreats:Monastery stays and meditation programs attract extended-duration bookings with higher per-traveler yields. Demand concentrates in Karnataka and Himachal Pradesh as urban professionals seek structured disconnection from digital work environments.
- Cultural Tours:Heritage circuit integration appeals to first-time sacred site visitors seeking contextual education alongside worship.
- Religious Festivals:Narrow calendar windows create acute capacity pressure at Kumbh Mela and Rath Yatra events.
Pilgrimage retains volume leadership; spiritual retreats hold the steepest expansion curve.
Destination:
Cost tier stratification separates premium-access temple zones from budget-oriented shrine circuits, with historical sites occupying a contested middle position.
- Temples:Core worship infrastructure at Varanasi and Tirupati commands highest visitor frequency. BIS hospitality standards and state temple board licensing requirements now govern accommodation quality within designated radii, filtering substandard inventory.
- Shrines:Smaller-scale worship sites in Tier-2 cities attract regional pilgrimage circuits with lower per-trip spend but higher repeat rates. Demand concentrates in Tamil Nadu and Kerala where local shrine networks interconnect through road transport.
- Historical Sites:Archaeological religious monuments appeal to cultural-spiritual hybrid travelers seeking photographic and educational content.
- Sacred Cities:Multi-site urban destinations like Ayodhya and Ujjain enable bundled itinerary construction across proximate worship points.
Temples dominate revenue concentration; sacred cities are climbing the fastest as infrastructure investments enable multi-day stays.
Travel Purpose:
Customer type differentiation separates devotion-driven repeat pilgrims from experience-seeking first-timers, with community engagement emerging as a distinct booking category.
- Religion:Ritual obligation and vow fulfillment motivate high-frequency visitation at specific deity temples. Demand concentrates among middle-aged travelers from Gujarat and Rajasthan maintaining generational worship commitments.
- Spiritual Growth:Personal transformation objectives attract younger demographics to meditation programs and guru-led retreats. This segment expands most quickly in metropolitan origin markets seeking structured wellness integration.
- Cultural Experience:Educational and photographic motivations blend with light spiritual engagement for international and domestic first-timers.
- Community Engagement:Group identity reinforcement through collective pilgrimage organizes travel club and extended family bookings.
Religion anchors repeat visitation; spiritual growth is gaining share fastest as urban millennials reinterpret sacred travel.
Tour Package:
Margin structure varies dramatically across service tiers, with luxury experiences capturing disproportionate returns through queue bypass and exclusive access arrangements.
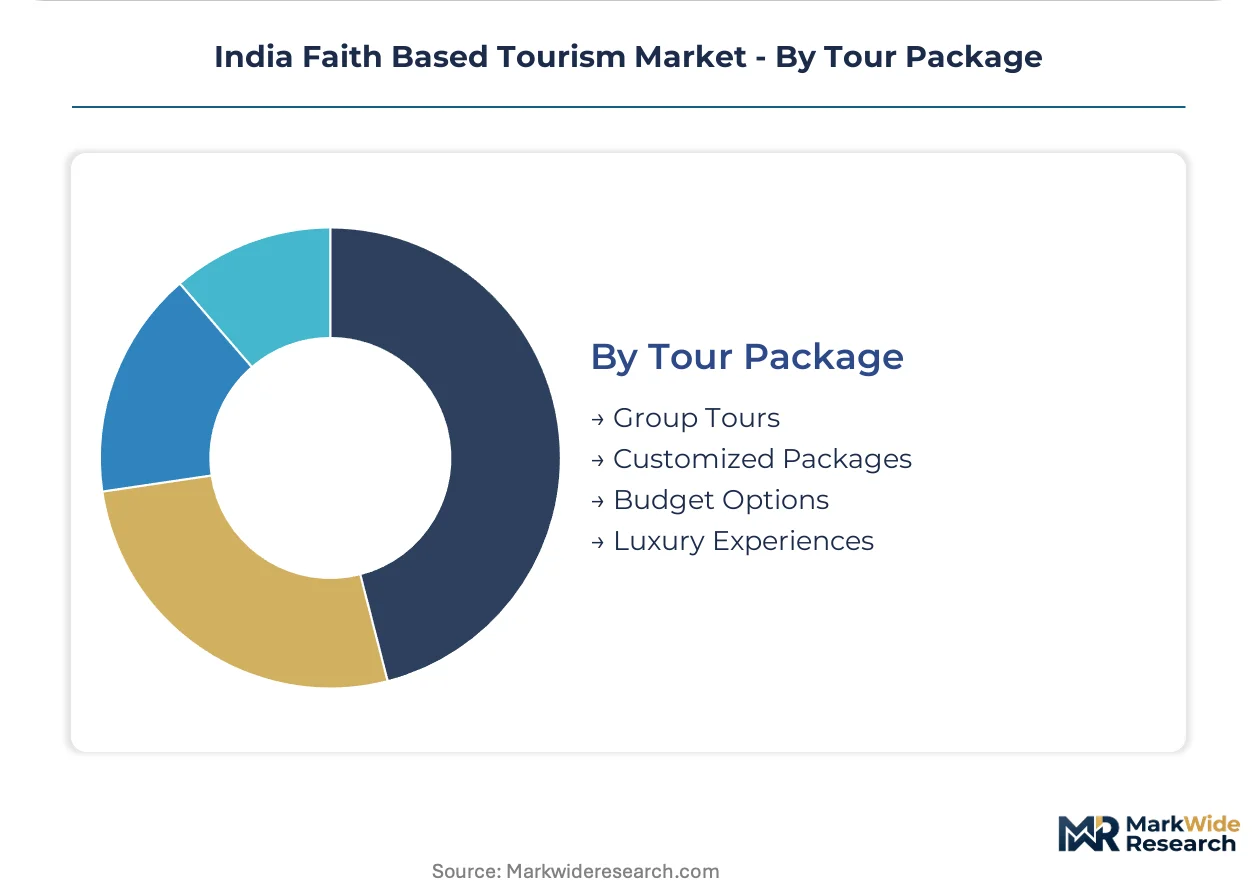
- Group Tours:Standardized itineraries with fixed departure schedules minimize per-customer acquisition costs. Demand concentrates among price-sensitive travelers from Tier-2 cities in Madhya Pradesh and Chhattisgarh.
- Luxury Experiences:Personalized darshan arrangements and premium accommodation command highest per-booking yields. High-net-worth devotees in Mumbai and Delhi seek queue bypass and private ritual participation at overcrowded legacy sites.
- Customized Packages:Flexible itinerary construction appeals to repeat pilgrims with specific site preferences and timing constraints.
- Budget Options:Minimal-service offerings with dormitory accommodation and shared transport maximize accessibility for cost-constrained travelers.
Group tours maintain volume dominance; luxury experiences are expanding most quickly as premium inventory scales at renovated sacred corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor's eastern and western arms reshape pilgrimage logistics by compressing travel times between Uttar Pradesh, Maharashtra, and Gujarat circuits. This rail backbone enables multi-state temple circuits previously impractical for domestic travelers.
Uttar Pradesh
Varanasi and Ayodhya anchor the highest pilgrimage density in India. The PRASAD scheme channels infrastructure funds into riverfront development and corridor connectivity around these sacred cities. The Kashi Vishwanath Corridor expansion concentrates premium accommodation investment within the temple radius.
Tamil Nadu
Tirupati's Venkateswara Temple sustains the country's highest single-site visitation frequency. State temple board licensing requirements under BIS hospitality standards now govern accommodation quality within designated sacred radii. The Chennai-Tirupati expressway upgrade reduces transit friction for Andhra Pradesh and Karnataka origin markets.
Maharashtra
Shirdi and Trimbakeshwar command sustained demand from Gujarat and Rajasthan feeder markets. The state's temple development board mandates guide certification protocols that operators must navigate for multi-circuit packages. Pune-Nashik road corridor improvements enable same-day return circuits previously requiring overnight stays.
Gujarat
Dwarka and Somnath form the western pilgrimage anchor with emerging circuit potential. Swadesh Darshan 2.0 fund allocations redirect infrastructure toward this underdeveloped corridor. The Ahmedabad-Rajkot highway expansion opens new itinerary construction possibilities for Rajasthan-origin travelers.
Karnataka
Udupi and Dharmasthala temple towns attract extended spiritual retreat demand from Bangalore professionals. State-level monastery registration requirements govern wellness program licensing for foreign participant inclusion. The Mysore-Coorg road network supports meditation program circuits combining sacred sites with hill station accommodation.
India Faith Based Tourism Market Competitive Landscape
Listed leaders compete with private specialists across digital platform dominance and offline agent network coverage. The market structure bifurcates between mobile-first reservation platforms capturing millennial volume and heritage circuit operators defending repeat clientele relationships. Three archetypes dominate: digital aggregators with vernacular interfaces, curated heritage specialists with guide networks, and diversified hospitality groups with captive accommodation inventory. Competitive moves center on regional language app deployment and exclusive darshan access arrangements at overcrowded legacy sites.
Within the digital platform tier, MakeMyTrip and Yatra Online occupy positions exemplifying app-based pilgrimage booking capture. Thomas Cook (India) Limited represents the curated heritage specialist archetype with guided temple visit integration. These three entities illustrate how scale-driven intermediaries and service-depth operators coexist across divergent customer acquisition strategies.
| Leading Market Players |
|---|
| MakeMyTrip |
| Thomas Cook (India) Limited |
| Cox & Kings Ltd |
| Mahindra Holidays & Resorts India Limited |
| Yatra Online Pvt Ltd |
| Cleartrip Private Limited |
| Expedia |
| SOTC Travel Limited |
| Kesari Tours |
| Others |
Supply & Pricing Matrix
App-based booking platforms replacing offline agent networks as the dominant reservation channel simultaneously redistributes supply geography toward Tier-2 departure cities and compresses pricing premiums previously captured by traditional intermediaries. This substitution dynamic fragments pricing power across digital aggregators while concentrating margin capture at the accommodation and experience layer.
Pricing Analysis
Volume-discount tiering structures dominate pilgrimage package economics, with group bookings commanding 15-30% reductions against individual reservations at identical properties. Three-tier pricing stratification across premium darshan access, standard guided circuits, and economy dormitory transport separates high-net-worth devotees from price-sensitive mass pilgrims. Pricing pressure stems from millennial travelers unbundling components and booking monastery stays directly through local apps. Tier-2 city origin markets exhibit highest price sensitivity; luxury experience seekers in Mumbai and Delhi demonstrate lowest elasticity.
Supply Chain Analysis
Rail corridor chokepoints along the Dedicated Freight Corridor's eastern and western arms underwrite multi-state circuit feasibility, compressing transit times between Uttar Pradesh, Maharashtra, and Gujarat. Accommodation inventory concentrates in Tamil Nadu, Uttar Pradesh, and Karnataka, with room supply anchored in temple board licensing zones. Raw material dependencies include construction-grade hospitality materials, food service supply chains, and licensed guide labor pools. Single-source vulnerability runs through state-level temple board permit systems that gate access to core worship zones. Distribution feeds from regional transport hubs through last-mile operator networks to sacred site perimeters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across millennial digital adoption curves and legacy offline loyalty creates niche positioning opportunities for operators targeting specific departure city tiers or worship circuit combinations.
For Market Incumbents: Compound digital platform investments with vernacular interface deployment to defend share against app-native challengers penetrating Tier-3 markets. Deepen backward integration into captive accommodation inventory near PRASAD scheme corridors to offset commission compression from booking platform intermediation. Prioritize BIS certification acceleration for pre-existing properties to maintain licensing eligibility as temple boards tighten quality gates.
For New Entrants and Emerging Players: Differentiate on spiritual retreat programming that blends monastery stays with corporate wellness contracts, targeting Bangalore and Hyderabad professional segments seeking structured disconnection. Penetrate Gujarat's Dwarka-Somnath corridor before Swadesh Darshan 2.0 infrastructure completion saturates operator presence. Deploy direct-to-monastery booking platforms that disintermediate legacy package assemblers for repeat pilgrims familiar with specific sites.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors regional specialists with temple board relationships and certified guide networks over undifferentiated digital aggregators. Long-term viability hinges on exclusive darshan access arrangements that persist through regulatory regime changes. Monitor Swadesh Darshan 2.0 fund allocation velocity as the signal indicating which sacred corridors will experience demand surges requiring capacity scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Vernacular Platform Launch | Regional language interfaces penetrate Tier-2 and Tier-3 departure cities, converting first-time digital bookers into recurring customers. |
| Monastery Direct Booking Integration | Direct supplier relationships with Karnataka and Himachal Pradesh retreat centers capture margin from disintermediated package assemblers. |
| Exclusive Darshan Access Arrangement | Queue bypass partnerships with Tirupati and Varanasi temple boards command premium pricing from high-net-worth devotees. |
| Guide Certification Investment | State tourism department training protocol compliance addresses service quality gaps damaging repeat booking rates. |
| Multi-Circuit Package Construction | Dedicated Freight Corridor connectivity enables Uttar Pradesh-Maharashtra-Gujarat bundled itineraries previously impractical for domestic travelers. |
Research Methodology
Initial hypotheses were tested against primary input from pilgrimage package operators, state tourism department officials, temple board licensing administrators, and digital platform product managers, and refined through secondary validation against Ministry of Tourism PRASAD scheme disclosures, BIS hospitality standard filings, and Swadesh Darshan 2.0 fund allocation records. Bottom-up sizing of accommodation inventory and transport capacity was triangulated with top-down expenditure estimates from domestic tourism surveys.
Variance-decomposition across traveler origin markets, worship circuit types, and service tier combinations structured the analytical framework throughout the projection horizon. Segmentation dimensions modeled include pilgrimage package type, destination category, travel purpose motivation, and tour package tier. CAGRs were derived from trend extrapolation of booking platform transaction data and infrastructure investment trajectories, incorporating seasonal compression patterns and festival calendar concentration effects as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained PRASAD scheme funding continuity and stable rail corridor freight prioritization would require recalibration. Forecasts reflect documented assumptions regarding millennial digital adoption velocity and temple board licensing enforcement intensity. Practitioners should keep alternative scenarios live as state-level regulatory fragmentation and accommodation supply bottlenecks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
Destination Wedding Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
South Africa Casino Tourism Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Culinary Tourism Market