
 Industrial Rubber Products Market | 2026-2036
Industrial Rubber Products Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Rubber Products Market Outlook
Asset-light leasing models for compounding equipment are reshaping competitive entry in industrial rubber manufacturing. Continental AG leverages captive polymer sourcing to sustain margin stability across its hose and sealing divisions. Bridgestone Corporation anchors its position through vertical integration into synthetic rubber feedstocks. Trelleborg AB specializes in precision-engineered polymer solutions for aerospace and marine sealing applications.
Industrial rubber products encompass elastomer-based components formulated from nitrile, silicone, EPDM, or neoprene, typically vulcanized under heat and pressure to achieve specified tensile strength, elongation, and compression set resistance for dynamic sealing, fluid conveyance, or vibration isolation. Hoses dominate value pools due to their critical role in hydraulic and pneumatic systems across manufacturing and construction equipment. Seals and gaskets represent the fastest-growing product category, driven by electric vehicle battery thermal management requirements and stricter leakage standards. The EPDM material segment leads volume demand for outdoor and high-temperature applications, while nitrile compounds retain pricing power in oil-resistant industrial environments.
The EPA enforces emissions and chemical content standards that restrict volatile organic compound release from rubber processing facilities, compelling manufacturers to invest in solvent-free curing technologies. REACH registration requirements in Europe mandate full substance disclosure for imported rubber compounds, directly affecting market access for non-EU suppliers. OSHA workplace exposure limits on rubber process dust and fumes shape plant capital expenditure decisions across the United States. Stakeholders must monitor evolving battery electric vehicle platform specifications, as thermal interface and sealing requirements diverge sharply from internal combustion architectures.
Market Dynamics
Electric vehicle thermal management architectures are forcing radical reformulation of elastomer specifications across powertrain sealing systems, compressing development cycles from 36 months to 18 months for qualified compounds.
Growth Catalysts
- EPA emissions standards:Tightening volatile organic compound limits from rubber processing facilities are accelerating solvent-free curing technology adoption across US manufacturing plants.
- Electric vehicle battery packs:Liquid cooling loop sealing requirements are generating specialized EPDM and silicone compound demand for thermal interface management.
- Germany:Automotive OEM procurement of advanced sealing systems is concentrating supplier qualification programs around REACH-compliant material traceability.
Market Restraints
- Synthetic rubber feedstock volatility:Butadiene and styrene price swings from Asian petrochemical complexes are compressing compounder margins unpredictably.
- Carbon black supply concentration:Three suppliers control 70% of furnace black capacity for reinforcement grades, creating single-source vulnerability.
- Fluoroelastomer technical ceiling:Perfluorinated compounds face temperature-performance tradeoffs above 300°C that limit turbine sealing applications.
Strategic Opportunities
- India:Domestic tire and hose manufacturing expansion under PLI scheme incentives is creating localized compounding equipment demand.
- Hydrogen infrastructure:High-pressure sealing for fueling stations requires novel permeation-resistant elastomer formulations absent from current product lines.
- 3D-printed tooling convergence:Additive manufacturing of mold inserts is enabling rapid prototype-to-production scaling for custom seal geometries.
Industry Challenges
- Formulation chemist scarcity:Retiring expertise in sulfur vulcanization kinetics and accelerator systems is outpacing university polymer program output.
- REACH substance disclosure timelines:Full chemical characterization for imported compounds requires 18-24 month pre-registration cycles that freeze supplier switches.
- Legacy ERP integration:Batch traceability systems from the 1990s resist connectivity with modern IoT-enabled curing press monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Rubber Products Market |
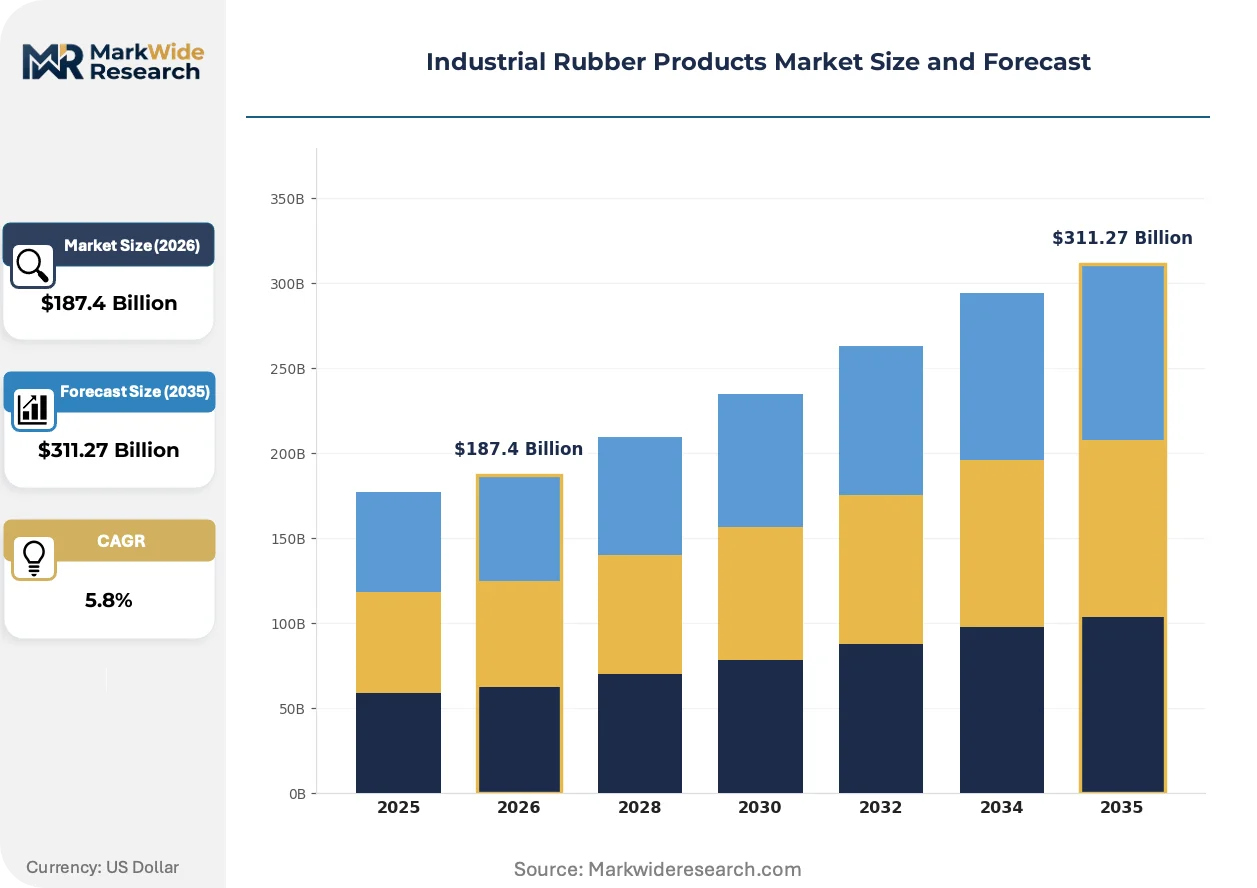
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hoses, Seals, Gaskets, Bands Application: Manufacturing, Construction, Automotive, Aerospace Material: Nitrile, Silicone, EPDM, Neoprene End User: OEMs, Tier-1 Suppliers, Distributors, Aftermarket Providers |
| Companies Covered | Bridgestone Corporation, Michelin Group, Continental AG, Goodyear Tire & Rubber Company, Sumitomo Rubber Industries, Pirelli & C. S.p.A., Yokohama Rubber Company, Hankook Tire & Technology, Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Rubber Products Market Strategic Shifts
Digital twin technology is virtualizing compound development workflows, compressing physical testing requirements while regulatory substance tracking mandates reshape material specification protocols across automotive supply chains.
Digital compound formulation platforms are virtualizing laboratory mixing and vulcanization testing through physics-based polymer network simulation. Tier-1 automotive suppliers are adopting these tools at 40% annual expansion rates to pre-qualify formulations before physical prototype commitment. This virtualization is compressing supplier development cycles from 24 months to 9 months while reducing scrap generation during scale-up trials.
REACH substance disclosure requirements are mandating full chemical fingerprinting for all rubber compounds entering EU manufacturing facilities. Industrial consequence includes forced reformulation of legacy nitrile and neoprene grades containing undisclosed process oils or secondary accelerators. Automotive sealing divisions are responding by consolidating supplier bases to three qualified partners with complete analytical documentation.
Automotive OEMs are unbundling after-sales seal and gasket inventories from original equipment contracts, creating independent replacement part procurement channels. Independent distributors and MRO platforms are capturing this volume through direct mill relationships that bypass traditional tiered supply structures. China and Germany exhibit the most visible channel fragmentation, where domestic e-procurement platforms now aggregate 15% of industrial rubber replacement demand.
Industrial Rubber Products Market Segmentation
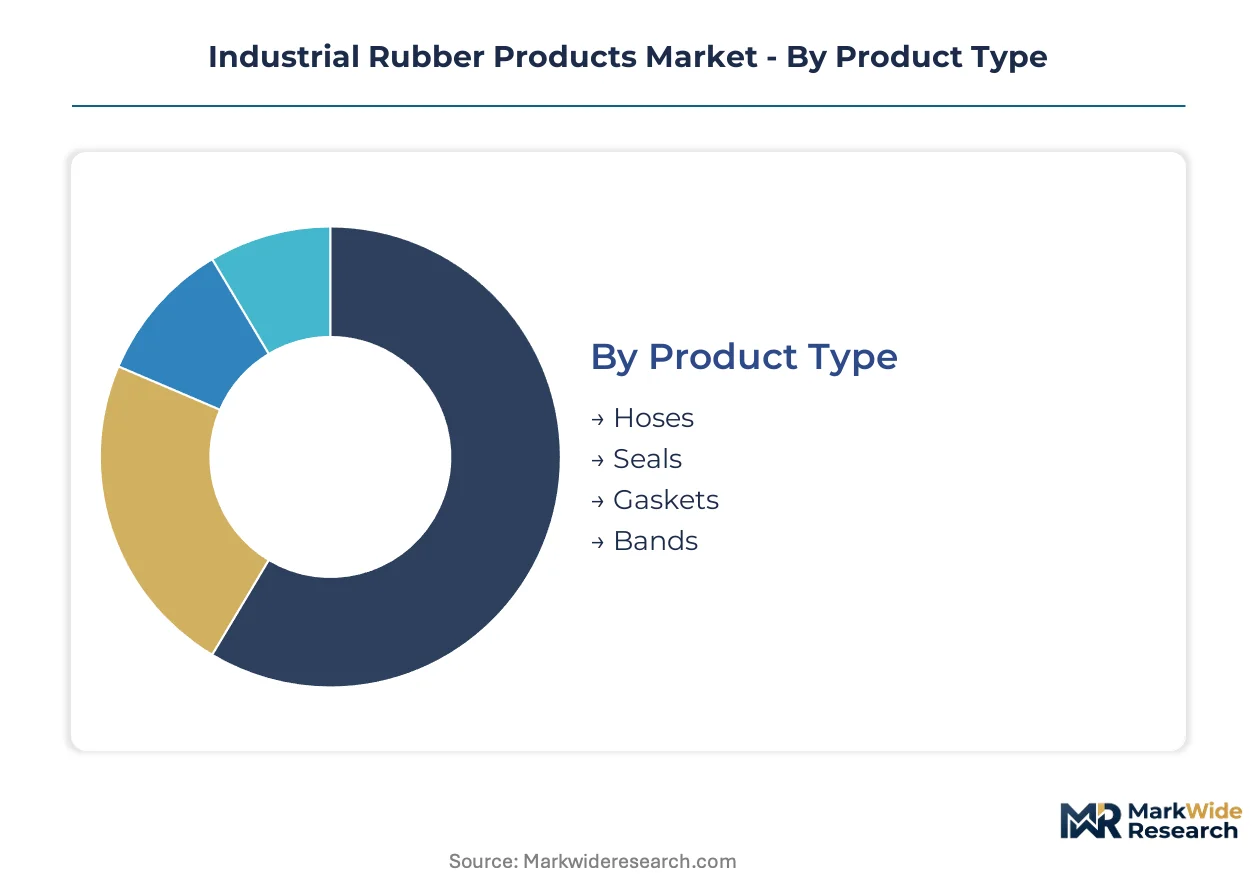
Elastomer formulation requirements diverge sharply across end-use environments, forcing suppliers to maintain parallel qualification tracks for automotive thermal management versus industrial fluid conveyance. Segmentation clarity enables compounders to align R&D spending with the specific compression set and chemical resistance profiles each application demands.
Product Type:
Use-case spectrum spans static sealing against dynamic pressure cycling to continuous flexing in hydraulic circuits, with each application imposing distinct fatigue life and permeation specifications.
- Hoses:Multi-layer constructions combining textile reinforcement with vulcanized elastomer tubes deliver rated burst pressures for hydraulic and pneumatic energy transmission. Demand concentrates in German and US manufacturing equipment fleets where OEMs specify SAE J517 or DIN 20022 performance tiers for construction and agricultural machinery.
- Seals:Precision-molded geometries from EPDM and fluoroelastomer compounds maintain seal integrity across temperature swings from -40°C to 150°C. Electric vehicle battery pack thermal interfaces in China and the United States are driving specialized low-permeation formulations for liquid cooling loop retention.
- Gaskets:Die-cut or molded sheet goods provide flange sealing with controlled compression recovery for pipeline and vessel applications.
- Bands:Extruded endless or clamp-style configurations secure hose assemblies and dampen vibration in rotating equipment.
The dominant share belongs to Hoses, while Seals is closing the gap fastest.
Application:
Cost tier separation emerges between specification-heavy automotive procurement and price-sensitive industrial maintenance budgets.
- Automotive:Powertrain and battery thermal management systems require validated compound traceability under IATF 16949 protocols. OEM qualification programs in Germany and China now mandate 18-month development cycles for new sealing formulations, compressing supplier response windows.
- Manufacturing:Hydraulic press and conveyor systems consume bulk hose and coupling assemblies with standardized SAE or ISO pressure ratings. US metal fabrication and plastics processing plants drive replacement volume through MRO procurement channels.
- Construction:Mobile equipment exposure to abrasion and UV degradation favors EPDM and chloroprene compounds for outdoor durability.
- Aerospace:FAA-certified materials for fuel system and cabin pressure sealing command premium pricing through specialized distributor networks.
Automotive commands the highest specification intensity, while Manufacturing delivers the steadiest replacement volume.
Material:
Volume concentration favors general-purpose polymers, with specialty grades capturing margin in chemically aggressive environments.
- EPDM:Ethylene-propylene-diene terpolymers deliver superior ozone and weather resistance for outdoor sealing and coolant hose applications. German automotive thermal management specifications and Chinese electric vehicle platform requirements are accelerating demand for peroxide-cured grades with enhanced compression set performance.
- Nitrile:Acrylonitrile-butadiene copolymers retain market position through oil and fuel resistance in hydraulic and powertrain sealing. US EPA emissions compliance for fuel system permeation limits sustains pricing power for high-acrylonitrile specialty grades.
- Silicone:Polysiloxane backbones enable extreme temperature service from -60°C to 230°C for aerospace and medical applications.
- Neoprene:Chloroprene polymers balance weather resistance with moderate oil compatibility for general industrial belting and hose covers.
EPDM holds the broadest application base, while Nitrile defends the most defensible pricing position.
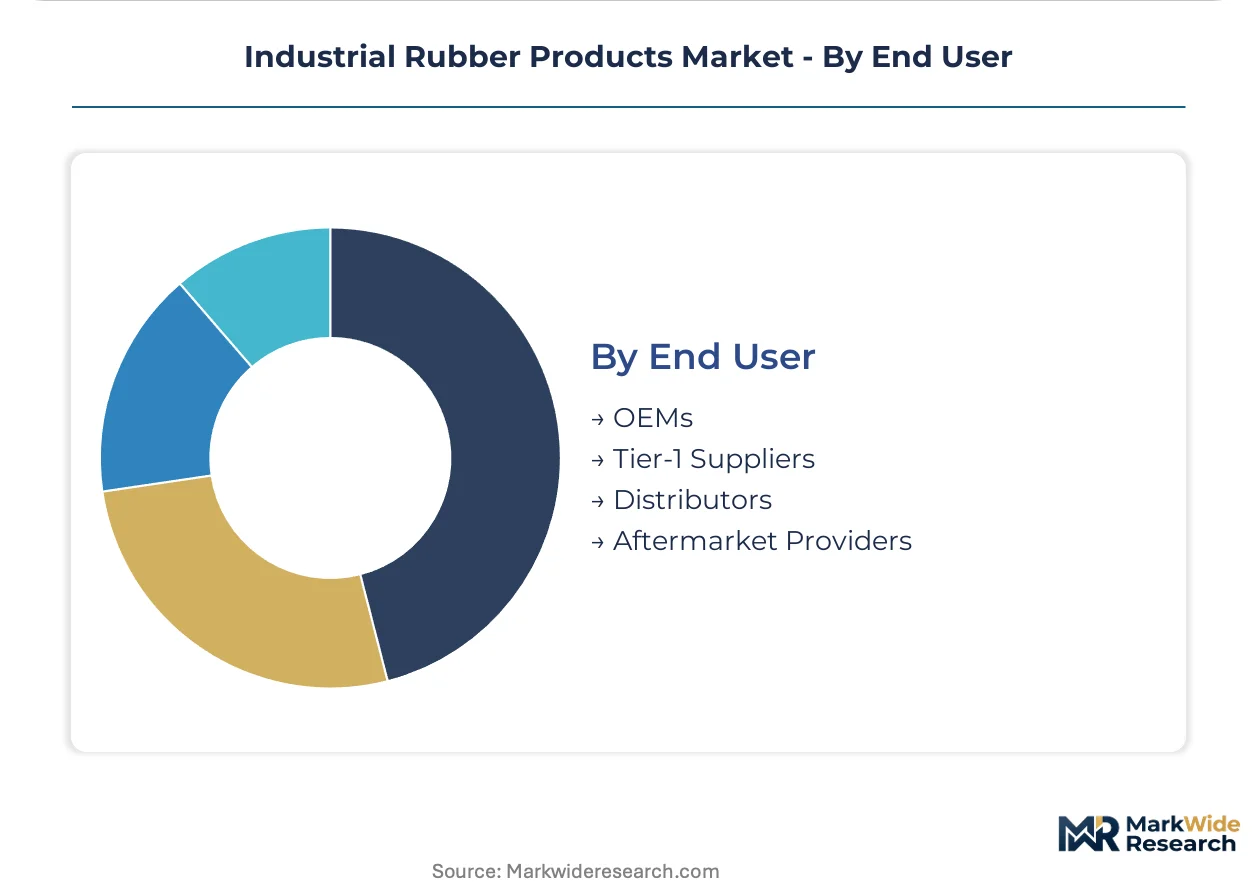
End User:
Procurement authority is fragmenting as automotive OEMs unbundle aftermarket inventories from original equipment contracts.
- OEMs:Direct automotive and equipment manufacturer specifications govern compound approval, tooling investment, and production scheduling. REACH substance disclosure mandates in Europe and EPA emissions standards in the United States force captive technical resources for regulatory navigation.
- Tier-1 Suppliers:Sealing system integrators in Germany and China consolidate qualified compound sources to three documented partners with full analytical traceability.
- Distributors:Independent hose and fitting merchants capture construction and agricultural equipment replacement demand through local inventory positioning.
- Aftermarket Providers:E-procurement platforms in China and Germany now aggregate 15% of industrial rubber replacement volume through direct mill relationships.
OEMs retain specification control, while Aftermarket Providers are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and regulatory tightening across major manufacturing economies are redrawing procurement geography for industrial rubber compounds. REACH substance disclosure mandates in Europe, EPA emissions enforcement in North America, and PLI scheme incentives in Asia are forcing suppliers to localize compounding capacity or risk market exclusion.
United States
Automotive OEM thermal management specifications and construction equipment replacement cycles drive EPDM and nitrile demand. EPA volatile organic compound limits from rubber processing facilities accelerate solvent-free curing technology adoption at Ohio and Michigan manufacturing plants. Detroit-Windsor automotive corridor suppliers consolidate qualified compound sources to meet IATF 16949 traceability requirements.
Germany
Electric vehicle battery platform sealing requirements and industrial hydraulic system specifications generate specialized elastomer demand. REACH full chemical characterization mandates for imported compounds force 18-24 month pre-registration cycles that freeze supplier switches. Stuttgart and Munich automotive clusters concentrate Tier-1 sealing system integrators consolidating to three documented partners with complete analytical documentation.
China
Domestic electric vehicle production scale and renewable energy infrastructure expansion propel coolant hose and thermal interface demand. MIIT dual carbon goals and GB standards for industrial emissions shape compounding facility investment decisions. Yangtze River Delta and Pearl River Delta manufacturing belts host localized EPDM capacity expansion serving battery OEM procurement programs.
India
Domestic tire and hose manufacturing expansion under PLI scheme incentives creates localized compounding equipment demand. BIS certification requirements for automotive rubber products tighten material specification protocols for imported compounds. Tamil Nadu and Gujarat industrial corridors attract greenfield hose extrusion capacity targeting construction and agricultural equipment OEMs.
Japan
Precision sealing for semiconductor manufacturing equipment and aerospace fuel systems sustains fluoroelastomer and silicone specialty demand. METI carbon neutrality roadmaps for industrial processes accelerate energy-efficient vulcanization technology adoption. Kansai and Chubu manufacturing regions maintain precision polymer formulation expertise for export-oriented automotive and electronics customers.
Industrial Rubber Products Market Competitive Environment
On the supply side, the industry is consolidating around three structural tiers: integrated polymer-to-component conglomerates, specialized precision seal manufacturers, and regional compounding specialists serving replacement markets. Strategic archetypes include captive feedstock players securing margin stability through upstream control, precision engineering specialists commanding premium pricing in aerospace and medical applications, and asset-light compounders leveraging leased equipment for flexible capacity. Dominant competitive moves include backward integration into synthetic rubber feedstocks and geographic expansion through qualified supplier status in automotive OEM programs.
Within the integrated conglomerate tier, Continental AG and Bridgestone Corporation exemplify upstream control strategies that buffer compound margin volatility through captive polymer sourcing. Trelleborg AB occupies a position among precision engineering specialists, representing the archetype that anchors premium positioning through aerospace and marine sealing expertise. These three entities collectively illustrate how supply chain configuration and application focus determine competitive positioning across divergent end-use specifications.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Continental AG |
| Goodyear Tire & Rubber Company |
| Sumitomo Rubber Industries |
| Pirelli & C. S.p.A. |
| Yokohama Rubber Company |
| Hankook Tire & Technology |
| Trelleborg AB |
| Others |
Value Chain & Pricing Dynamics
Carbon black supply concentration in three dominant furnace black producers anchors pricing power for reinforcement-grade compounds, concentrating margin capture upstream while compounders absorb feedstock volatility through formula adjustments.
Pricing Analysis
Certification level (IATF 16949/REACH-compliant) creates the primary spread between automotive-grade sealing compounds and general industrial grades. Three-tier pricing structure across premium, standard, and economy levels reflects qualification depth, with OEM-specified thermal management formulations commanding substantial premiums over MRO replacement hose. Cost compression in standard-grade nitrile compounds is intensifying because Asian petrochemical feedstock volatility transmits directly to compounder margins. Tier-1 automotive procurement teams exhibit the least price sensitivity due to traceability mandates, while construction equipment distributors face acute pressure from spot-market buyers.
Supply Chain Analysis
Tariff exposure between US and Asian synthetic rubber feedstock sources dominates supply chain risk assessment for North American compounders. Manufacturing gravity centers on Germany, China, and the United States for precision sealing systems, with India emerging as localized hose extrusion capacity. Butadiene, styrene, and carbon black constitute critical input dependencies with limited substitution pathways. Single-source vulnerability in furnace black reinforcement grades threatens production continuity. Distribution runs through Tier-1 automotive integrators for OEM-specified compounds, while aftermarket channels fragment toward direct mill relationships and e-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform standardization is transforming industrial rubber procurement into an ecosystem-coordination challenge, where thermal interface specification alignment across battery OEMs determines supplier viability.
For Market Incumbents: Harden qualified supplier status through captive EPDM polymer sourcing and peroxide-cured grade certification investment. Consolidate formulation documentation systems to compress REACH pre-registration cycles from 24 months to 12 months. Defend against emerging asset-light compounders by locking 5-year thermal management supply agreements with Chinese and German battery OEMs. For New Entrants and Emerging Players: Hydrogen fueling station high-pressure sealing represents the most penetrable entry point, as incumbent fluoroelastomer portfolios lack permeation-resistant formulations above 700 bar. India's PLI-subsidized tire and hose manufacturing expansion offers localized compounding equipment leasing demand with reduced qualification barriers. Pursue rapid prototype-to-production scaling through 3D-printed mold insert partnerships with German automotive Tier-1s. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light leasing models for compounding equipment, enabling flexible capacity without fixed plant investment. Five-to-ten year viability favors precision-engineered polymer specialists with aerospace and medical certification depth over commodity hose manufacturers. Monitor hydrogen infrastructure deployment rates as the primary inflection signal for novel elastomer formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber Feedstocks | Continental AG and Bridgestone Corporation buffer margin volatility through captive butadiene sourcing. |
| Digital Twin Adoption for Compound Development | Physics-based polymer network simulation compresses supplier qualification cycles from 24 months to 9 months. |
| REACH-Compliant Supplier Base Consolidation | German Tier-1 sealing integrators reduce qualified partners to three documented sources with full analytical traceability. |
| Hydrogen Infrastructure Sealing Formulation Investment | High-pressure fueling station demand requires novel permeation-resistant elastomers absent from current portfolios. |
| 3D-Printed Tooling Convergence | Additive manufacturing of mold inserts enables rapid scaling for custom EV battery thermal interface geometries. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with automotive OEM procurement directors, Tier-1 sealing system integrators, compound formulation chemists, and aftermarket distribution channel managers. Secondary validation drew from EPA emissions enforcement records, ECHA REACH registration databases, MIIT dual carbon policy filings, and customs trade data for synthetic rubber feedstock flows. Bottom-up volume modeling across hose, seal, and gasket product categories was triangulated against top-down macroeconomic indicators for manufacturing and construction equipment investment.
Calibration against historical capacity utilization rates and qualified supplier program timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-use industry intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand functions incorporating electric vehicle production ramp rates and thermal management content per vehicle. Industry-specific inputs included sulfur vulcanization kinetics expertise retirement curves and solvent-free curing technology adoption trajectories.
Practitioners should monitor synthetic rubber feedstock price volatility, REACH substance disclosure timeline extensions, and hydrogen infrastructure deployment acceleration for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Oil Saver Rubber Market
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Natural Rubber Market
Rubber
Performance Elastomers Market
Rubber
Rubber Roller Cleaner Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Tire Reinforcement Materials Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Rubber Compound Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
Rubber Ropes Market