
 Choline Market | 2026-2036
Choline Market Size, Share, and Industry Trends Forecast 2026-2036
Choline Market Analytics
REACH compliance is consolidating the cost-of-entry calculus for European choline suppliers, forcing smaller traders to upgrade testing infrastructure or exit. BASF SE leverages its Ludwigshafen integrated complex to sustain pharmaceutical-grade choline chloride output with captive ethylene oxide supply. Balchem Inc. anchors North American production through its Utah-based crystallization and microencapsulation capabilities. Kemin Industries Inc. differentiates via specialized choline forms targeting ruminant bypass protection.
Choline denotes a quaternary ammonium compound with the formula C5H14NO+, typically manufactured through ethylene oxide-trimethylamine reaction or extracted from phosphatidylcholine-rich feedstocks such as soybean lecithin; it functions as an essential methyl donor in lipid metabolism and cell membrane synthesis across human and animal nutrition. Choline chloride dominates volume flows into animal feed applications where cost-per-unit methylation drives procurement decisions, while CDP-Choline and Alpha-GPC concentrate margin pools in dietary supplements and nootropic formulations targeting cognitive health positioning. Lecithin-derived choline retains structural importance in functional foods as clean-label emulsifier systems displace synthetic alternatives.
FDA feed additive regulations and USDA organic certification standards shape product specifications for choline destined to US livestock operations, while REACH and EFSA purity mandates govern European import access and labeling claims. China's NMPA and GB standards for food-grade choline salts create parallel compliance tracks for domestic versus export-oriented manufacturers. Stakeholders must monitor evolving feed-to-food residue thresholds and regional bioavailability testing requirements as formulation science advances.
Market Dynamics
Animal feed formulators in China and the EU are expanding choline inclusion rates while REACH and F-Gas Regulation compliance costs reshape supplier economics across pharmaceutical-grade derivatives.
Growth Catalysts
- Feed-grade demand surge:Poultry and swine operations in China are scaling choline chloride inclusion to optimize methylation efficiency and reduce feed conversion ratios.
- REACH purity mandates:ECHA enforcement of impurity thresholds for imported choline salts is consolidating European supply toward certified pharmaceutical-grade channels.
- Lecithin extraction advances:Enzymatic hydrolysis of soybean phosphatidylcholine is yielding food-grade choline with clean-label positioning for functional emulsifier applications.
Market Restraints
- Ethylene oxide supply concentration:Captive production of this critical feedstock at Ludwigshafen and similar integrated sites limits independent choline chloride manufacturing expansion.
- EU F-Gas Regulation friction:Refrigerant-phaseout requirements are elevating energy costs for choline derivative crystallization and purification operations.
- Alpha-GPC substitution pressure:Nootropic formulators are pivoting toward CDP-Choline and synthetic acetylcholine precursors in premium cognitive health positioning.
Strategic Opportunities
- Ruminant bypass protection:Microencapsulated choline forms targeting dairy and beef operations remain underpenetrated relative to monogastric feed applications.
- China domestic pharmaceutical-grade expansion:NMPA pathway acceleration for choline bitartrate in parenteral nutrition is opening import substitution potential.
- Clean-label emulsifier convergence:Lecithin-derived choline is absorbing demand from synthetic phospholipids as EFSA and FDA labeling scrutiny intensifies.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel FDA, REACH, and NMPA registration tracks for pharmaceutical-grade choline salts extend commercialization cycles by 18-36 months.
- Analytical capability gaps:Smaller traders lack in-house GC-MS and HPLC infrastructure to verify choline derivative purity against evolving ECHA impurity thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Choline Market |
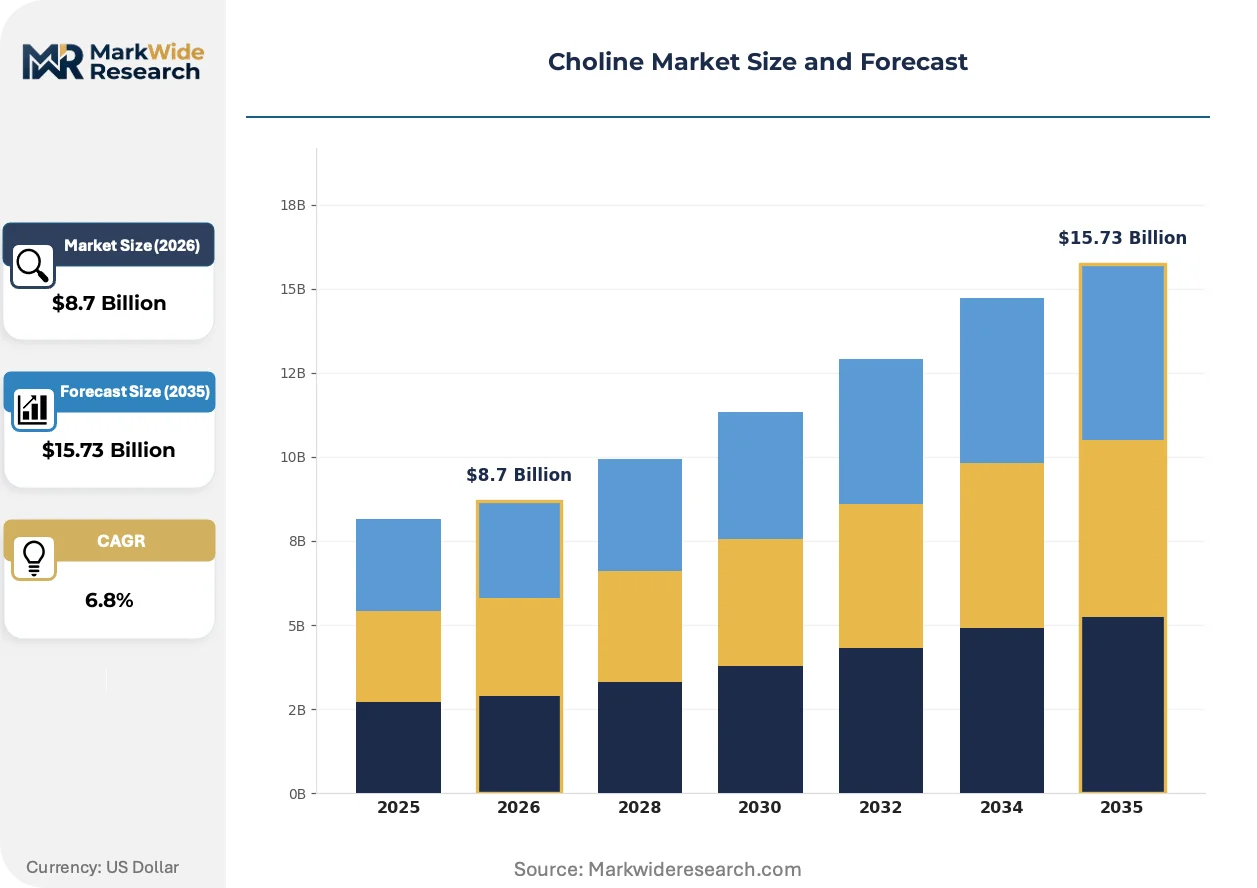
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Choline Chloride, Lecithin, CDP-Choline, Alpha-GPC Application: Dietary Supplements, Animal Feed, Pharmaceuticals, Functional Foods End User: Healthcare Professionals, Nutritionists, Farmers, Consumers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Wholesale |
| Companies Covered | BASF SE, Eastman Chemical Company, Balchem Inc., Kemin Industries Inc., Jubilant Ingrevia Limited, Merck KGaA, Tokyo Chemical Industry Co. Ltd., GHW International, Imperial Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Choline Market Evolving Landscape
Formulation science and regulatory chemistry are converging to reshape how choline derivatives are manufactured, certified, and positioned across feed, food, and pharmaceutical channels.
Microencapsulation technology is absorbing margin expansion potential in ruminant nutrition applications. Dairy operations in the US and EU are adopting lipid-coated choline chloride to protect bioavailability through rumen fermentation. This encapsulation approach is absorbing market share from unprotected feed-grade forms while commanding 40-60% price premiums.
REACH authorization requirements for ethylene oxide derivatives are compressing European import channels for non-integrated choline suppliers. ECHA's 2023-2024 substance evaluation waves have elevated documentation burdens for trimethylamine and choline chloride imports. Pharmaceutical-grade manufacturers with captive ethylene oxide supply are absorbing displaced volume from traders lacking integrated testing infrastructure.
Buyer concentration among multinational feed compounders is compressing procurement cycles and elevating specification stringency. Cargill, ADM, and similar integrators are consolidating choline sourcing toward suppliers with dual FDA-USDA organic certification. This concentration dynamic is most visible in US Midwest poultry operations where contract farming structures align feed additive procurement with processor mandates.
Choline Market Segmentation
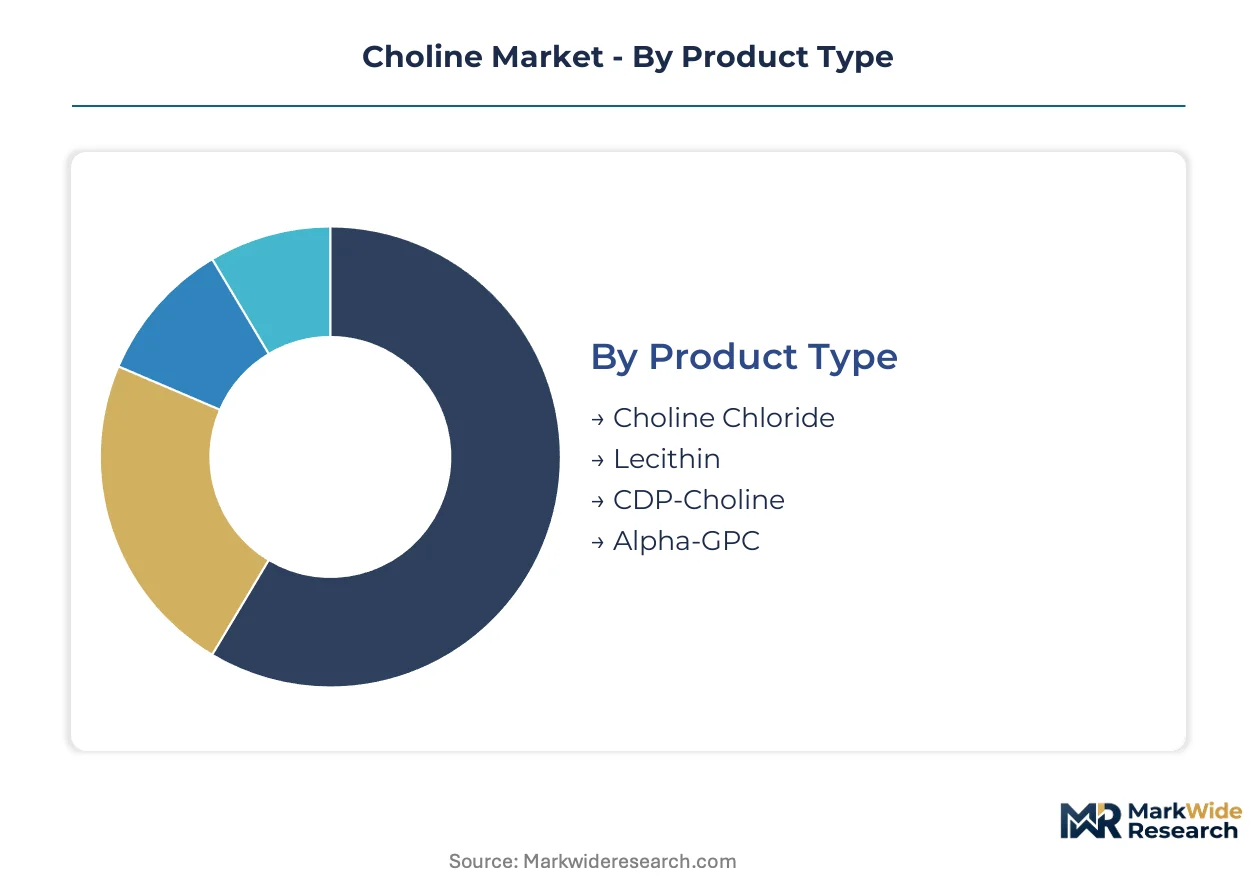
Choline derivative procurement hinges on purity certification tiers, bioavailability specifications, and end-use regulatory pathways. Buyers segment offerings across feed-grade efficiency, pharmaceutical-grade compliance, and consumer-facing cognitive positioning.
Product Type:
Cost-per-unit methylation efficiency and certification grade drive procurement decisions across derivative categories.
- Choline Chloride:Quaternary ammonium salt synthesized via ethylene oxide-trimethylamine reaction, typically standardized at 50-60% aqueous or 98% crystalline grades. Demand concentrates in Chinese and US Midwest poultry and swine operations where feed conversion ratio optimization overrides purity premiums. REACH and FDA feed additive mandates enforce heavy metal and residual solvent thresholds.
- Lecithin:Phosphatidylcholine-rich extract from soybean or sunflower processing, yielding 20-25% choline by weight. Clean-label emulsifier demand from EFSA-scrutinized European food manufacturers is displacing synthetic phospholipid alternatives.
- CDP-Choline:Cytidine diphosphate-choline salt with superior blood-brain barrier penetration. Nootropic formulators in Japan and South Korea are expanding inclusion in premium cognitive health stacks.
- Alpha-GPC:Glycerophosphate choline ester with rapid acetylcholine precursor bioavailability. Substitution pressure from CDP-Choline and synthetic alternatives is compressing margin pools in dietary supplement channels.
Volume sits with choline chloride; growth tilts toward lecithin as clean-label positioning accelerates.
Application:
Regulatory jurisdiction determines formulation specifications and commercialization timelines across end-use channels.
- Animal Feed:Methylation efficiency applications in monogastric diets dominate tonnage flows. Chinese domestic feed production scaling and EU F-Gas Regulation compliance costs are reshaping supplier economics.
- Dietary Supplements:Cognitive health and prenatal nutrition positioning drives CDP-Choline and Alpha-GPC demand. NMPA pathway acceleration in China and FDA structure-function claim enforcement in the US create divergent certification tracks.
- Pharmaceuticals:Parenteral nutrition and hepatic steatosis treatment applications require pharmaceutical-grade choline bitartrate. ECHA impurity threshold enforcement is consolidating European supply toward integrated manufacturers with captive ethylene oxide.
- Functional Foods:Lecithin-derived choline integrates into clean-label emulsifier systems for bakery and beverage applications. EFSA and FDA labeling scrutiny is absorbing demand from synthetic alternatives.
Feed applications absorb the volume base; pharmaceutical and functional food channels are climbing the fastest.
End User:
Technical sophistication and procurement authority vary sharply across buyer categories.
- Farmers:Contract poultry and swine operators in concentrated feeding operations purchase through integrator-aligned procurement. Cargill and ADM procurement mandates enforce dual FDA-USDA organic certification requirements.
- Healthcare Professionals:Hospital pharmacists and clinical nutritionists specify pharmaceutical-grade choline for parenteral and enteral applications. Multi-jurisdiction registration timelines extend commercialization cycles.
- Nutritionists:Sports and clinical nutrition practitioners influence dietary supplement formulation decisions. Bioavailability testing requirements and outcome-based positioning shape product selection.
- Consumers:Direct-to-purchaser nootropic and prenatal nutrition buyers respond to cognitive health marketing. Online retail channel concentration elevates brand visibility requirements.
Procurement authority concentrates with farmers and healthcare professionals; consumer-direct engagement is expanding most quickly.
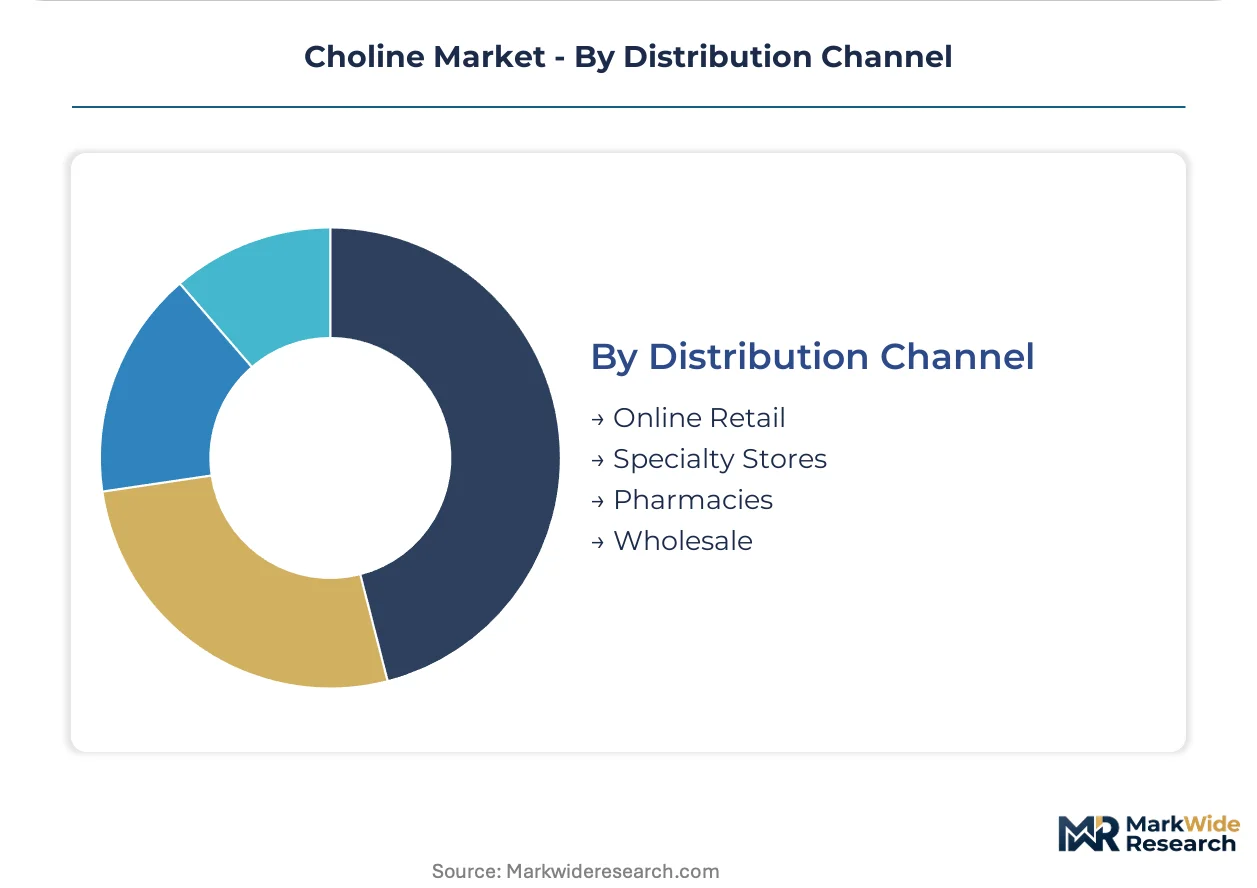
Distribution Channel:
Channel selection reflects product certification tier and buyer technical requirements.
- Wholesale:Bulk choline chloride and feed-grade lecithin flows through compounder and integrator procurement networks. Chinese domestic production scaling is compressing import dependency.
- Pharmacies:Pharmaceutical-grade choline salts for prescription and OTC distribution require national regulator registration. EMA and NMPA pathway complexity limits supplier participation.
- Online Retail:Dietary supplement and nootropic derivative sales concentrate in platform-direct and brand-owned channels. Consumer education requirements elevate content marketing investment.
- Specialty Stores:Sports nutrition and natural products retailers carry premium-positioned CDP-Choline and Alpha-GPC formulations. Staff training on bioavailability differentiation supports margin capture.
Wholesale channels handle the volume base; online retail is gaining share fastest in consumer-facing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta free-trade zones are concentrating choline chloride production capacity near Shanghai-Ningbo petrochemical corridors. German chemical parks leverage REACH compliance infrastructure to capture pharmaceutical-grade premiums. US Midwest feed compounders anchor North American demand through integrator-aligned procurement networks.
China
Poultry and swine feed production scaling in Shandong and Henan provinces absorbs two-thirds of domestic choline chloride output. NMPA pathway acceleration for pharmaceutical-grade choline bitartrate tightens purity documentation requirements for parenteral nutrition applications. The Ningbo-Zhoushan port cluster handles bulk crystalline choline exports to Southeast Asian feed mills.
Germany
REACH authorization enforcement for ethylene oxide derivatives compresses import channels for non-integrated traders. ECHA's 2023-2024 substance evaluation waves elevate testing infrastructure requirements at Ludwigshafen and Marl chemical parks. BASF's captive ethylene oxide supply sustains pharmaceutical-grade output while smaller competitors face compliance-driven exit pressure.
United States
Contract poultry operations in Arkansas and Georgia enforce dual FDA-USDA organic certification through Cargill and ADM procurement mandates. EPA feed additive residue thresholds shape specification stringency for Midwest swine operations. Balchem's Utah crystallization complex anchors North American pharmaceutical-grade production with microencapsulation capabilities.
India
Domestic feed production scaling in Punjab and Haryana drives choline chloride inclusion rate expansion for broiler operations. CDSCO import licensing for pharmaceutical-grade choline salts extends registration timelines for European suppliers. The Gujarat chemical corridor attracts lecithin extraction investments targeting clean-label emulsifier export demand.
Japan
PMDA pharmaceutical-grade certification requirements limit supplier participation in parenteral nutrition channels. CDP-Choline nootropic demand concentrates in Tokyo-Osaka metropolitan health supplement retail networks. METI industrial standards for feed-grade choline derivatives align specification protocols with export-oriented Southeast Asian markets.
Choline Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market segments. The vendor base stratifies between integrated petrochemical players with captive ethylene oxide supply and independent traders dependent on merchant feedstock markets. Three archetypes dominate: multinational chemical conglomerates with pharmaceutical-grade infrastructure, regional feed additive specialists with crystallization capabilities, and lecithin processors leveraging clean-label positioning. Capacity expansion and strategic partnerships represent the dominant competitive moves as REACH compliance costs reshape European supply economics.
Within the integrated chemical conglomerate tier, BASF SE and Merck KGaA exemplify pharmaceutical-grade positioning through captive feedstock control and multi-jurisdiction certification infrastructure. Among Asia-Pacific-based suppliers, Jubilant Ingrevia Limited occupies a position bridging Indian domestic feed demand with export-oriented pharmaceutical-grade production. Balchem Inc. anchors the North American specialist archetype through Utah-based microencapsulation capabilities serving ruminant bypass protection applications.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Balchem Inc. |
| Kemin Industries Inc. |
| Jubilant Ingrevia Limited |
| Merck KGaA |
| Tokyo Chemical Industry Co. Ltd. |
| GHW International |
| Imperial Group Limited |
| Others |
Value Network & Pricing Analysis
Petrochemical process engineers concentrated in Germany's Ludwigshafen-Marl corridor command wage premiums that compress margin spreads between pharmaceutical-grade and feed-grade choline derivatives. REACH compliance investments at these integrated sites propagate cost differentials across European import channels, forcing traders to absorb certification burdens or cede volume to captive producers.
Pricing Analysis
Short lead-time premiums dominate transactional dynamics, with pharmaceutical-grade choline salts commanding substantial markups against contract-scheduled feed-grade volumes. Three-tier pricing structure across pharmaceutical, feed-grade crystalline, and aqueous solution levels separates certification-burdened derivatives from commodity chlorides. Pricing pressure stems from ethylene oxide supply concentration at integrated Ludwigshafen complexes, compressing independent manufacturer margins. Contract poultry operations exhibit acute price sensitivity, while hospital pharmacists prioritize purity documentation over unit economics.
Supply Chain Analysis
Freight cost differentials between Ningbo-Zhoushan bulk exports and European pharmaceutical-grade air freight widen arbitrage windows for Southeast Asian feed mills. Supply concentrates in China, Germany, and the United States, with Yangtze River Delta petrochemical corridors feeding Asian demand and Utah crystallization complexes serving North American ruminant applications. Raw material dependencies center on ethylene oxide, trimethylamine, and soybean phosphatidylcholine feedstocks. Single-source vulnerability runs through Ludwigshafen's captive ethylene oxide infrastructure. Distribution runs through compounder procurement networks aligned with Cargill and ADM integrator mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene oxide capacity bottlenecks at integrated chemical parks prop pricing premiums across pharmaceutical-grade channels, sustaining margin capture for incumbent producers with captive feedstock supply.
For Market Incumbents: Anticipate REACH authorization waves compressing European import channels by accelerating ECHA impurity threshold compliance investments at Ludwigshafen and Marl sites. Backward integration into trimethylamine supply secures methylation efficiency advantages against merchant feedstock-dependent competitors. Microencapsulation capacity expansion targets ruminant bypass protection premiums before generic feed-grade substitution erodes differentiation. For New Entrants and Emerging Players: Enter via lecithin-derived choline extraction targeting EFSA-scrutinized European clean-label emulsifier demand, where enzymatic hydrolysis capabilities bypass ethylene oxide supply constraints. Gujarat chemical corridor investments absorb Indian domestic feed scaling while serving export-oriented functional food manufacturers. Pharmaceutical-grade positioning in China leverages NMPA pathway acceleration for parenteral nutrition applications. For Investors and Strategic Acquirers: Re-rating potential sits with integrated pharmaceutical-grade specialists given ECHA enforcement consolidation displacing non-compliant traders. Long-term viability across the analysis window favors producers with captive ethylene oxide and multi-jurisdiction certification infrastructure. CDSCO registration timelines for Indian pharmaceutical-grade imports signal inflection points for European supplier exit velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | BASF's Ludwigshafen complex sustains pharmaceutical-grade output against REACH-driven competitor exits. |
| Microencapsulation Capacity Expansion | Balchem's Utah facilities capture ruminant bypass protection premiums in dairy operations. |
| Clean-Label Emulsifier Repositioning | Lecithin processors absorb EFSA-scrutinized demand from synthetic phospholipid alternatives. |
| Multi-Jurisdiction Certification Investment | Dual FDA-USDA organic compliance aligns with Cargill procurement mandates in Midwest poultry. |
| NMPA Pathway Acceleration | Domestic pharmaceutical-grade producers capture import substitution in Chinese parenteral nutrition. |
Research Methodology
Document review covered ECHA substance evaluation databases, FDA feed additive guidance, and NMPA pharmaceutical-grade registration pathways, complemented by interviews with plant managers at crystallization facilities, procurement leads at multinational feed compounders, regulatory affairs directors navigating REACH authorization, and technical R&D heads developing microencapsulation formulations. Secondary validation drew from customs trade data, SEC 10-K chemical segment disclosures, and Cefic industry reports. Bottom-up capacity modeling triangulated against top-down demand aggregation across feed, pharmaceutical, and functional food channels.
Segment-level value outputs combined grade-tier differentiation, end-use regulatory pathways, and regional production hub economics across the projection horizon. CAGRs derived from ethylene oxide supply elasticity, feed conversion ratio optimization trends, and clean-label emulsifier substitution rates. Pharmaceutical-grade purity premiums and ruminant bypass protection pricing informed margin trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ethylene oxide supply disruption or accelerated ECHA impurity threshold enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
China Whey Protein Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Vitamins Gummies Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
Africa Beta Glucan Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Inositol Market
Nutritional Supplements
Bovine Collagen Peptide Market