
 Rosemary Extracts Market | 2026-2036
Rosemary Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Rosemary Extracts Market Analysis
REACH compliance is shifting the cost-of-entry calculus for European suppliers of rosemary-derived antioxidants. Kalsec Inc leverages its vertically integrated cultivation network in the United States to sustain consistent carnosic acid supply for export markets. Guangzhou Honsea Sunshine Biotech Co. Ltd anchors its competitive position through backward integration into rosemary farming across China's Yunnan province. DSM Firmenich differentiates via fermentation-adjacent extraction technologies that yield standardized rosmarinic acid concentrations.
Rosemary extracts are concentrated preparations derived from Rosmarinus officinalis leaves, typically standardized to 5-20% carnosic acid or 2.5-5% rosmarinic acid through supercritical CO2 or ethanol extraction, functioning primarily as lipid-soluble antioxidants in perishable formulations. Liquid extract formulations dominate current volume owing to their ease of incorporation into oil-based food matrices, while powder extracts command premium positioning in nutraceutical capsules where dosing precision matters. The food and beverage application segment leads absolute consumption, though cosmetic brands represent the fastest-growing demand pool as clean beauty mandates proliferate across retail channels.
EFSA guidelines on novel food safety assessments and the EU Green Deal's bio-based chemicals incentives jointly determine which rosemary extract grades achieve commercial scale in European markets. The FDA's GRAS self-affirmation pathway and China's GB standards for plant extracts create divergent compliance burdens for suppliers serving multiple jurisdictions. Stakeholders must monitor evolving maximum residue limits for extraction solvents, as regulatory tightening in major import markets could disqualify legacy processing methods without warning.
Market Dynamics
Clean-label mandates across European processed food sectors are compressing reformulation timelines for synthetic preservative replacement, forcing ingredient procurement teams to validate rosemary extract performance under accelerated shelf-life testing protocols.
Growth Catalysts
- EU Additive Bans:EFSA enforcement of prohibited artificial antioxidant lists in processed meats and baked goods redirects formulation budgets toward carnosic acid standardized extracts.
- Cosmetic Clean Beauty:Retail chain mandates for plant-derived preservative systems in skincare and haircare formulations expand addressable demand beyond traditional food applications.
- Supercritical CO2 Extraction:Adoption of solvent-free processing methods by contract manufacturers improves yield consistency and satisfies import market residue limits.
Market Restraints
- Raw Material Concentration:Mediterranean basin harvest volatility, particularly Spanish and Moroccan crop cycles, creates carnosic acid supply discontinuities.
- Extraction Solvent Regulations:REACH tightening on ethanol and hexane residue thresholds disqualifies legacy processing infrastructure without capital retrofit.
- Synthetic Antioxidant Substitution:TBHQ and BHT retain cost advantages in price-sensitive emerging market food sectors, delaying plant-extract penetration.
Strategic Opportunities
- China Functional Foods:SAMR approval pathways for novel food ingredients open nutraceutical applications in aging-population dietary supplements.
- Fermentation-Adjacent Extraction:Convergence of bioprocessing and selective solvent systems enables standardized rosmarinic acid production independent of agricultural harvests.
- Direct-to-Manufacturer Platforms:Digital procurement channels bypass traditional distributor markups for mid-scale cosmetic compounders seeking certified organic grades.
Industry Challenges
- Analytical Chemist Shortage:HPLC method expertise for carnosic acid quantification remains scarce in contract testing laboratories, extending batch release timelines.
- Multi-Jurisdiction Certification:Parallel GRAS self-affirmation, EFSA novel food dossiers, and GB standard compliance create redundant documentation burdens for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosemary Extracts Market |
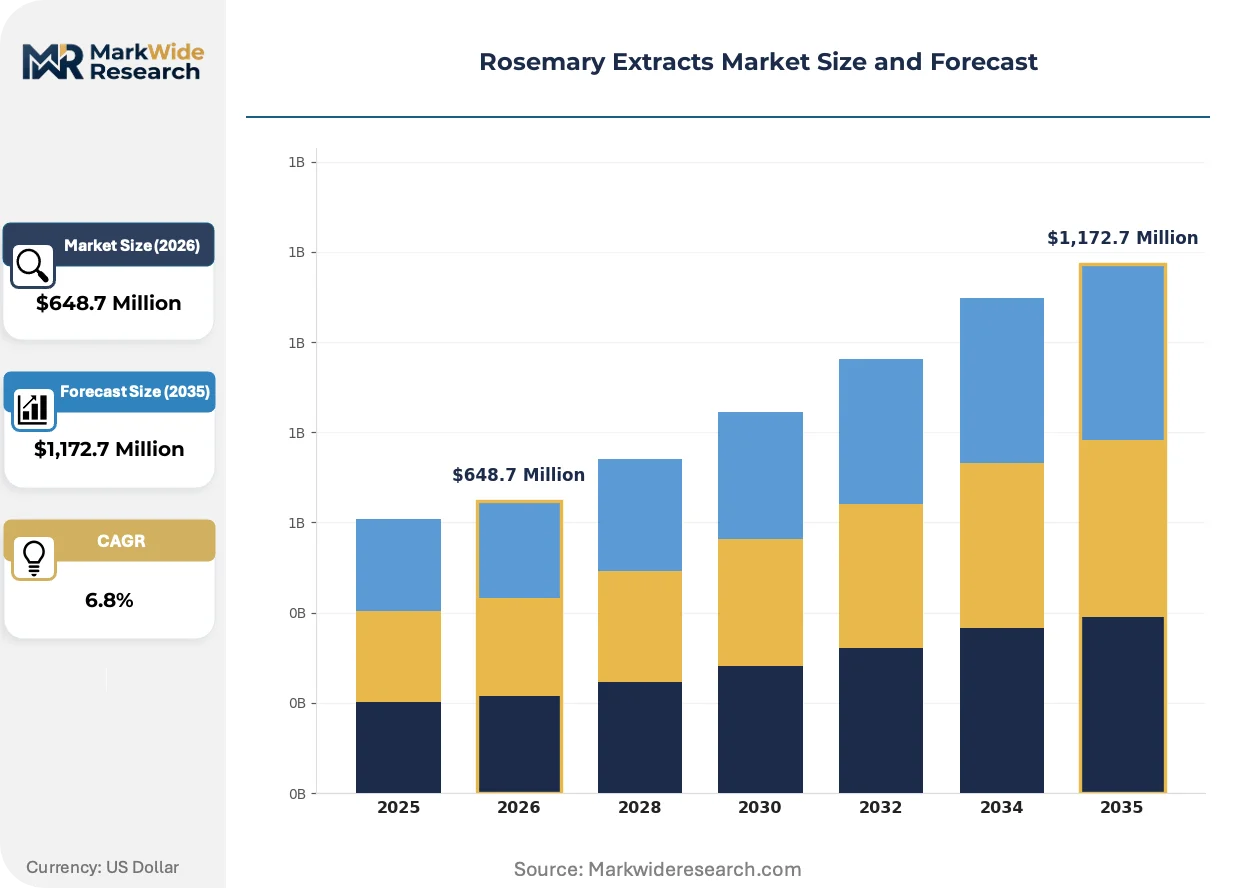
| Market Size in 2026 | $648.7 Million |
| Market Size in 2035 | $1,172.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Liquid Extract, Powder Extract, Essential Oil, Solid Extract Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Food Manufacturers, Herbal Product Companies, Cosmetic Brands, Pharmaceutical Firms |
| Companies Covered | FLAVEX Naturextrakte GmbH, Kalsec Inc, Guangzhou Honsea Sunshine Biotech Co. Ltd, DSM Firmenich, Givaudan SA, Kemin Industries, Inc., International Flavors and Fragrances Inc., Archer Daniels Midland Company, Naturalin Bio-Resources Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosemary Extracts Market Emerging Trajectories
Processing technology convergence and procurement digitization are compressing traditional supply hierarchies in rosemary extract value chains. Three developments warrant particular attention from stakeholders.
Supercritical CO2 extraction with integrated in-line spectroscopic monitoring is automating real-time carnosic acid standardization that previously required offline laboratory verification. Mid-scale cosmetic compounders in France and Italy are adopting these systems to reduce batch-to-batch variability. The technology is automating quality control labor out of per-unit production costs while enabling just-in-time contract manufacturing arrangements.
REACH authorization requirements for chemical substances in antioxidant applications are forcing solvent residue documentation to sub-ppm thresholds. European extract importers now require third-party certificates of analysis covering hexane, acetone, and methanol traces. Food-grade rosemary extract shipments into Germany face the most stringent enforcement, with customs laboratories rejecting containers exceeding 10 ppm total solvent residues.
Compound annual contracting is displacing spot purchasing for standardized carnosic acid grades among multinational meat processors. Procurement teams at German and Dutch slaughterhouse operators are locking eighteen-month supply agreements with fixed price collars. This pattern concentrates most visibly in Central European sausage and cured meat manufacturing, where reformulation investments create switching costs that favor supplier relationship stability over transactional sourcing.
Rosemary Extracts Market Segmentation
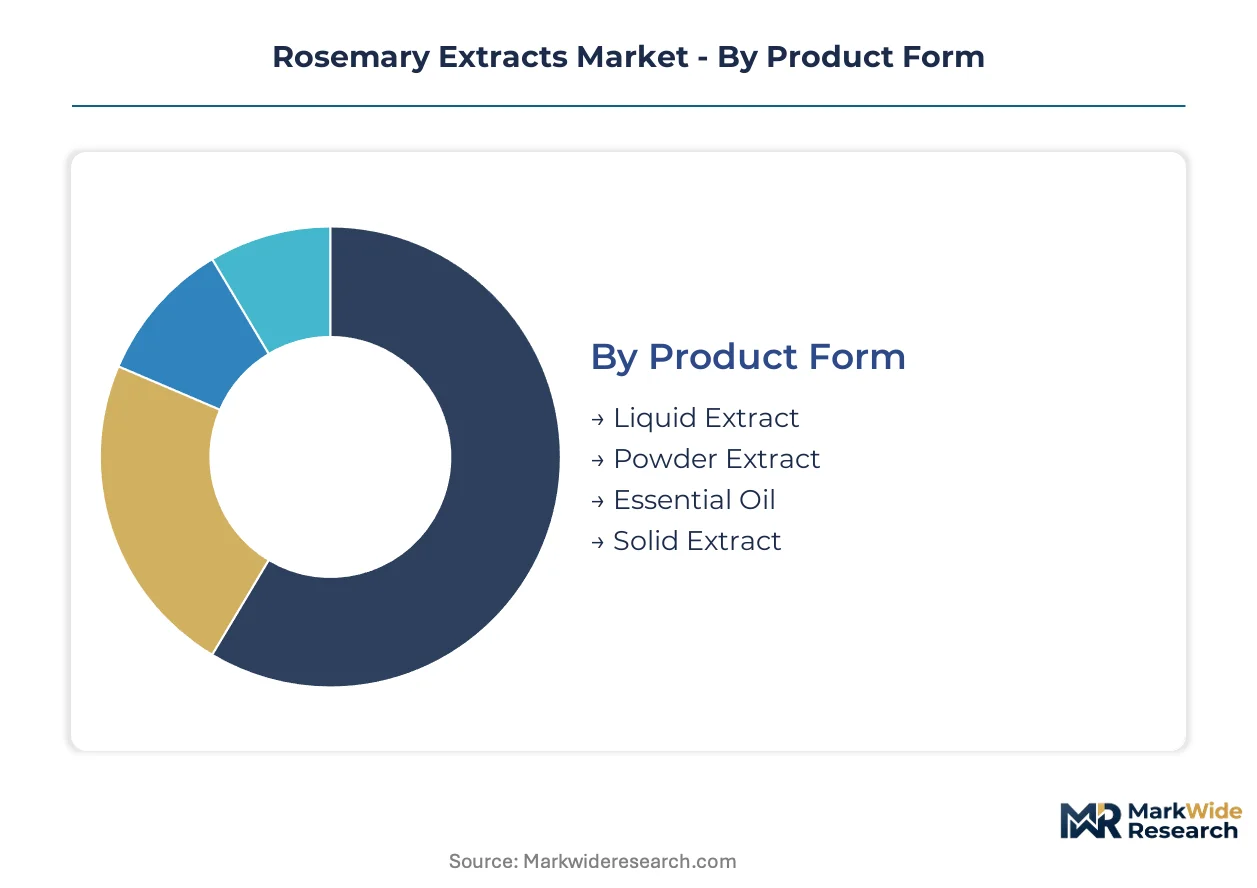
Rosemary extract procurement strategies diverge sharply across form factors and end-use specifications, with formulation requirements dicting grade selection more than price sensitivity. Manufacturers must match carnosic acid concentration, solvent residue profiles, and physical handling properties to specific application constraints.
Product Form:
Reformulation cycles in processed food and clean beauty sectors are accelerating replacement demand for standardized extract formats that integrate seamlessly into existing production lines.
- Liquid Extract:Oil-soluble preparations standardized to 5-20% carnosic acid through supercritical CO2 extraction dominate meat processing and bakery applications in Germany, where EFSA additive bans force rapid synthetic antioxidant substitution. German sausage manufacturers and Dutch cured meat operators compound these extracts directly into fat phases without additional emulsification steps.
- Powder Extract:Spray-dried or carrier-bound formulations with precise rosmarinic acid titers serve nutraceutical capsule manufacturers requiring dosing accuracy. Demand concentrates in China's aging-population supplement sector following SAMR novel food approvals, with Yunnan province extractors capturing backward integration advantages.
- Essential Oil:Steam-distilled volatile fractions rich in 1,8-cineole and camphor serve fragrance and aromatherapy applications with distinct regulatory pathways from antioxidant-grade extracts.
- Solid Extract:Semi-solid resinous preparations with elevated active compound density target cosmetic compounders in France and Italy seeking concentrated preservative systems for emulsion stability.
Liquid extract sits at the top of the volume ranking, with powder extract climbing the fastest.
Application:
End-use diversification is fragmenting procurement specifications, with each vertical imposing distinct purity, certification, and documentation requirements on suppliers.
- Food & Beverage:Lipid-soluble antioxidant grades prevent rancidity in edible oils, processed meats, and baked goods, with EU Green Deal bio-based chemical incentives accelerating plant-derived preservative adoption across Spanish and Italian olive oil bottlers.
- Cosmetics:Clean beauty mandates from French and Italian retail chains drive demand for REACH-compliant, solvent-residue-tested extracts in skincare and haircare preservative systems, expanding fastest among application verticals as plant-derived alternatives displace parabens.
- Pharmaceuticals:GMP-certified extracts with documented heavy metal and microbiological specifications target topical anti-inflammatory formulations, requiring EMA-quality documentation that excludes food-grade suppliers.
- Nutraceuticals:Standardized rosmarinic acid preparations for cognitive and circulatory health supplements face divergent approval pathways across FDA GRAS self-affirmation, EFSA novel food dossiers, and China's GB standards.
Food & Beverage maintains volume leadership, though Cosmetics is expanding most quickly.
Distribution Channel:
Procurement digitization is compressing traditional distributor hierarchies, with mid-scale compounders seeking direct certification access and price transparency.
- Online Retail:B2B platforms enable small-batch cosmetic compounders to source certified organic grades with full COA documentation, bypassing traditional three-tier markups.
- Supermarkets:Mass-market retail channels move finished consumer products rather than industrial extract volumes, with limited relevance to ingredient procurement.
- Specialty Stores:Regional distributors serving French and Italian cosmetic clusters provide technical formulation support alongside material supply.
- Direct Sales:Compound annual contracting between multinational meat processors and vertically integrated extractors locks eighteen-month supply agreements with fixed price collars, concentrating in Central European sausage manufacturing.
Direct Sales commands the largest volume flows, with Online Retail gaining share fastest among emerging compounders.
End User:
Customer scale and technical capability determine whether procurement prioritizes price stability, formulation support, or regulatory documentation depth.
- Food Manufacturers:German and Dutch slaughterhouse operators and bakery chains drive standardized carnosic acid demand, with reformulation investments creating supplier switching costs that favor relationship stability.
- Herbal Product Companies:Traditional medicine and supplement formulators in China and Europe seek multi-compound full-spectrum extracts rather than single-marker standardization.
- Cosmetic Brands:Clean beauty mandates from French retail chains force plant-derived preservative adoption, with mid-scale compounders adopting supercritical CO2 systems to reduce batch-to-batch variability.
- Pharmaceutical Firms:GMP compliance and EMA-quality documentation requirements restrict eligible suppliers to a narrow tier of certified extractors with dedicated pharmaceutical-grade production lines.
Food Manufacturers represent the largest demand pool, with Cosmetic Brands showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in Germany's meat processing belt and France's cosmetic compounding hubs, anchoring European demand for standardized carnosic acid grades. Chinese extraction engineers concentrate in Yunnan province's rosemary cultivation zones, supplying backward-integrated raw material streams.
Germany
German sausage manufacturers and Dutch cured meat operators drive liquid extract consumption for synthetic antioxidant replacement. EFSA enforcement of prohibited artificial additive lists in processed meats redirects procurement budgets toward plant-derived preservatives. The North Rhine-Westphalia slaughterhouse corridor locks eighteen-month supply agreements with fixed price collars to secure reformulation stability.
China
Yunnan province extractors capture backward integration advantages through captive rosemary farming operations serving domestic nutraceutical capsule manufacturers. SAMR novel food approval pathways for rosmarinic acid standardized extracts open aging-population dietary supplement applications. Guangzhou-based biotech clusters anchor export-oriented production for REACH-compliant European cosmetic compounders.
France
French retail chain clean beauty mandates force cosmetic brands toward plant-derived preservative systems in skincare and haircare formulations. REACH authorization requirements for chemical substances in antioxidant applications impose sub-ppm solvent residue documentation thresholds. The Provence-Alpes-Côte d'Azur fragrance cluster adapts steam-distillation infrastructure to serve dual fragrance-antioxidant extract markets.
United States
Mid-scale cosmetic compounders adopt supercritical CO2 extraction systems with integrated in-line spectroscopic monitoring to reduce batch-to-batch variability. FDA GRAS self-affirmation pathways create faster market entry for carnosic acid standardized extracts compared to EFSA novel food dossiers. Vertically integrated cultivation networks in the Pacific Northwest sustain consistent active compound supply for export markets.
Italy
Italian olive oil bottlers accelerate plant-derived preservative adoption under EU Green Deal bio-based chemical incentives. Mid-scale cosmetic compounders in Lombardy and Emilia-Romagna seek REACH-compliant, solvent-residue-tested extracts for emulsion stability applications. The Bologna-Turin industrial corridor concentrates demand for solid extract formats with elevated active compound density.
Rosemary Extracts Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive agricultural supply. Tiered supplier differentiation separates pharmaceutical-grade certifiers from food-grade volume operators. Three archetypes dominate: Mediterranean basin harvesters with seasonal raw material exposure, Chinese backward-integrated extractors with Yunnan province farming control, and fermentation-technology platforms pursuing harvest-independent production. Capacity expansion and geographic certification diversification constitute the dominant competitive moves.
Among vertically integrated specialists, Kalsec Inc and Guangzhou Honsea Sunshine Biotech Co. Ltd exemplify the captive cultivation archetype through upstream control over rosemary farming networks. DSM Firmenich occupies a position representing fermentation-adjacent extraction technology convergence. These three anchors illustrate how supply security and processing technology differentiation separate premium-tier positioning from commodity extract competition.
| Leading Market Players |
|---|
| FLAVEX Naturextrakte GmbH |
| Kalsec Inc |
| Guangzhou Honsea Sunshine Biotech Co. Ltd |
| DSM Firmenich |
| Givaudan SA |
| Kemin Industries, Inc. |
| International Flavors and Fragrances Inc. |
| Archer Daniels Midland Company |
| Naturalin Bio-Resources Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Captive cultivation networks in the Mediterranean basin and Yunnan province anchor supply positions while creating asymmetric pricing power for carnosic acid standardized extracts. German meat processors and French cosmetic compounders face divergent procurement economics based on their suppliers' upstream control over rosemary farming operations.
Pricing Analysis
Certification bundling versus unbundled analytical services splits the market into two pricing logics. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels separates EMA-quality documentation from basic COA provision. Price differentiation rests on REACH solvent residue thresholds and organic certification status. Cost compression in standard food-grade extracts is intensifying because Spanish harvest volatility forces spot purchasing. Mid-scale cosmetic compounders in France exhibit highest price sensitivity, while pharmaceutical firms accept premium positioning for GMP compliance.
Supply Chain Analysis
EU Green Deal domestic-content incentives for bio-based chemicals are redirecting procurement toward European-supercritical-CO2-processed grades. Raw material supply concentrates in Spain, Morocco, and China's Yunnan province. Extraction infrastructure draws from stainless steel reactor fabrication, analytical instrumentation, and certified organic rosemary biomass. Single-source vulnerability runs through Mediterranean climate-dependent harvest cycles. Distribution runs through direct annual contracting for multinational meat processors and B2B platforms for emerging cosmetic compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rosemary extracts market reads as a late-cycle quality story where EFSA enforcement of additive bans redirects procurement budgets toward certified carnosic acid grades with documented supply chain provenance.
For Market Incumbents: Lock in eighteen-month supply agreements with fixed price collars before Spanish harvest volatility intensifies. Deepen backward integration into Yunnan province farming networks to insulate against Mediterranean crop cycle discontinuities. Invest in supercritical CO2 capacity with in-line spectroscopic monitoring to automate batch release and reduce analytical labor costs. For New Entrants and Emerging Players: SAMR novel food approval pathways in China open a window for rosmarinic acid standardized extracts targeting aging-population dietary supplements. White-space concentrates in REACH-compliant cosmetic grades for mid-scale French and Italian compounders seeking solvent-residue-tested alternatives to parabens. Pursue direct-to-manufacturer digital procurement platforms with full COA documentation to bypass traditional distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for regional extraction specialists with captive farming assets because EFSA and FDA regulatory divergence creates compliance scale advantages for multi-jurisdiction certifiers. Five-to-ten-year viability hinges on fermentation-adjacent technology platforms achieving harvest-independent production. Monitor SAMR approval timelines for novel food ingredients as inflection indicator for Chinese nutraceutical demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Yunnan province farming control insulates Guangzhou Honsea against Mediterranean harvest volatility. |
| Supercritical CO2 Capacity Expansion | Automated in-line monitoring reduces batch-to-batch variability for French cosmetic compounders. |
| Fermentation-Adjacent Extraction Development | DSM Firmenich's bioprocessing convergence enables standardized rosmarinic acid independent of agricultural cycles. |
| Multi-Jurisdiction Certification Investment | Parallel GRAS self-affirmation and EFSA novel food dossiers unlock access to US and European food manufacturers. |
| Direct-to-Manufacturer Platform Launch | B2B procurement channels bypass distributor markups for mid-scale cosmetic compounders seeking organic grades. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build convergent validity. Primary fieldwork engaged extraction plant managers, procurement leads at German meat processors, cosmetic formulation chemists in France and Italy, regulatory affairs specialists navigating EFSA novel food pathways, and Yunnan province farming operation directors. Secondary validation drew from customs trade data on rosemary extract shipments, EFSA scientific opinions on additive safety, SAMR novel food approval registers, and REACH authorization documentation. Bottom-up volume modeling triangulated against top-down market sizing from industry association reports.
Segment-weighting approaches distributed value and volume across liquid extract, powder extract, essential oil, and solid extract form factors. Application dimensions spanned food and beverage, cosmetics, pharmaceuticals, and nutraceuticals with divergent certification requirements. Distribution channel modeling captured direct sales, online retail, and specialty store flows. CAGRs derived from regression analysis of historical pricing and volume trajectories, adjusted for EFSA regulatory enforcement timelines and EU Green Deal incentive program rollout. Forecast inputs incorporated rosemary biomass yield projections and supercritical CO2 equipment capacity expansion pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Mediterranean drought conditions or abrupt REACH solvent residue threshold tightening. Assumptions reflect continuation of current regulatory enforcement patterns and stable EU-China trade flows for extract shipments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Paprika Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Mustard Brown Extract Market