
 Middle East and Africa Vanilla Beans and Extract Market | 2026-2036
Middle East and Africa Vanilla Beans and Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Vanilla Beans and Extract Market Foresight
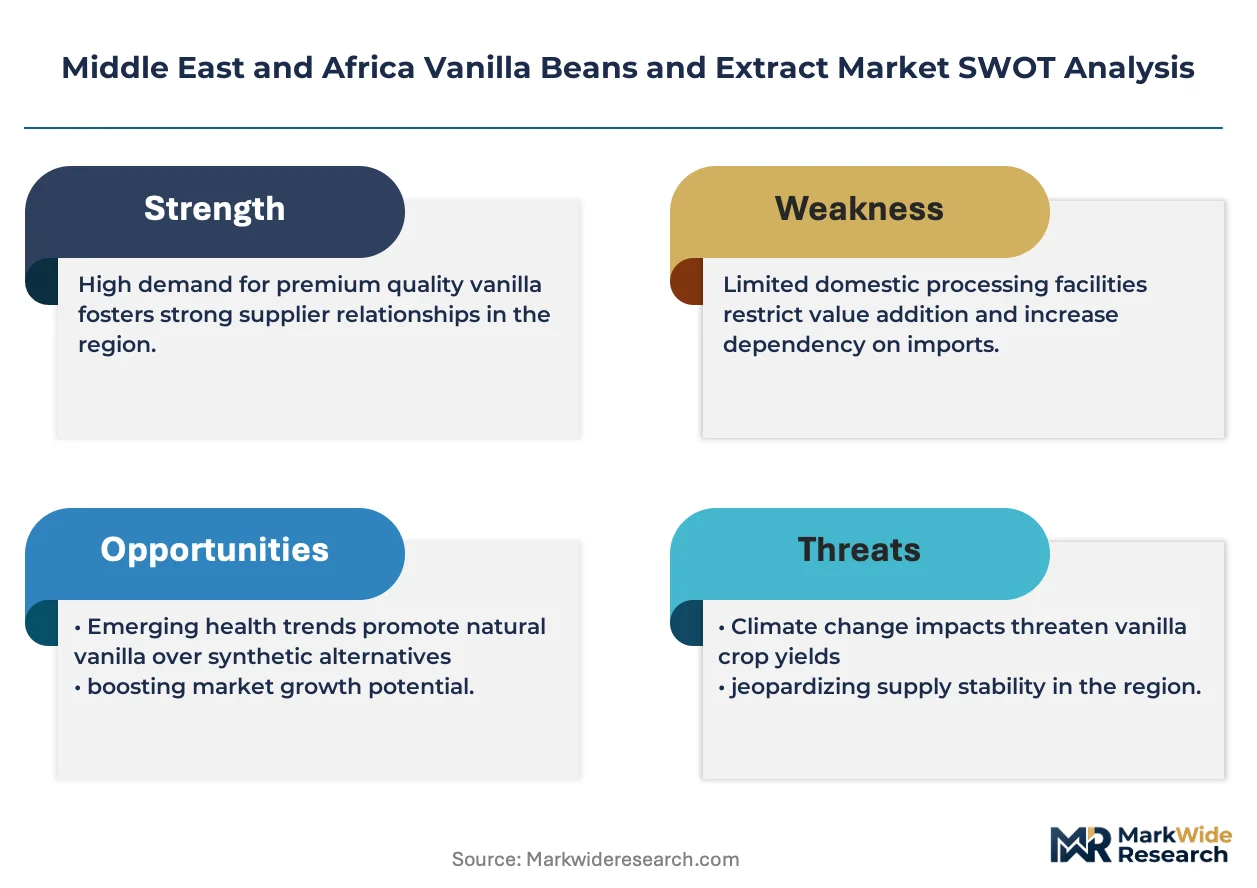
Extract-to-paste value migration is rewriting margin distribution across the Middle East and Africa vanilla supply chain. Symrise AG leverages backward integration into Madagascar-sourced bean curing to sustain cost discipline in extract production. Givaudan anchors its regional position through specialized flavor compounding services for Gulf dairy processors. Nielsen-Massey Vanillas differentiates via premium Grade A bean direct sourcing, occupying the high-end bakery segment in South Africa and the UAE.
Middle East and Africa vanilla beans and extract encompass cured vanilla planifolia and tahitensis pods plus alcohol- and glycerin-based extracts containing vanillin and related aromatic compounds, primarily functioning as natural flavoring agents in food systems requiring clean-label positioning. Extracts command the dominant value share due to formulation convenience in industrial bakery and beverage applications, while whole beans retain premium pricing in artisan chocolate and patisserie channels where visual pod presence signals quality. The quality grade dimension stratifies sharply: Premium and Organic tiers capture disproportionate margin in Gulf retail and hospitality procurement, whereas Grade B material feeds extract manufacturing for mass-market confectionery.
South Africa's Department of Health food additive regulations, Gulf Standards Organization halal certification protocols, and FSSAI-aligned import specifications across African trade corridors collectively enforce vanillin content thresholds and solvent residue limits that filter market access. These frameworks elevate compliance costs for uncertified suppliers while creating procurement preference for documented traceability from bean origin through extraction. Stakeholders must monitor evolving organic equivalence agreements between African producer nations and Gulf import authorities, as these reciprocity determinations will reshape competitive eligibility for premium segment participation.
Market Dynamics
Halal certification convergence across Gulf Cooperation Council states is tightening ingredient traceability requirements, forcing extractors to document bean origin through every curing stage while South Africa's processed food sector absorbs higher vanilla volumes for clean-label positioning.
Growth Catalysts
- Gulf Standards Organization halal protocols:Unified certification frameworks across Saudi Arabia, UAE, and Qatar reduce duplicate testing costs for extract suppliers, accelerating market access for compliant producers.
- Premium bakery segment expansion:Artisan patisserie chains in Dubai and Johannesburg absorb Grade A whole beans at premium pricing, creating pull-through demand for associated extract portfolios.
- Madagascar bean curing infrastructure:Regional processors securing backward integration into primary curing operations gain cost discipline and supply continuity advantages over spot-market dependent competitors.
Market Restraints
- Cyclone vulnerability in Madagascar:Concentrated bean sourcing from the Sava region exposes extract manufacturers to weather-driven supply shocks and price volatility every harvest cycle.
- FSSAI-aligned import specifications:African trade corridor regulations enforce vanillin content thresholds and solvent residue limits that filter uncertified suppliers from premium segment participation.
- Synthetic vanillin substitution:Petrochemical-derived alternatives from lignin and guaiacol processes capture mass-market confectionery applications, compressing natural extract pricing power at the economy tier.
Strategic Opportunities
- Organic equivalence agreements:Reciprocity determinations between African producer nations and Gulf import authorities will reshape competitive eligibility for premium segment participation.
- Specialized flavor compounding services:Technical partnerships with Gulf dairy processors enable customized vanilla profiles that differentiate beyond commodity extract offerings.
- E-commerce direct sourcing platforms:Digital procurement channels connecting South African artisan bakers to Madagascar bean curers disintermediate traditional importer-distributor networks.
Industry Challenges
- Halal certification timeline compression:Extended documentation requirements for alcohol-based extracts delay product launches as laboratories verify solvent compliance across multiple Gulf jurisdictions.
- Bean-to-extract traceability system integration:Legacy batch tracking infrastructure at African curing facilities requires capital-intensive upgrades to meet real-time chain-of-custody demands from UAE hospitality procurement hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Vanilla Beans and Extract Market |
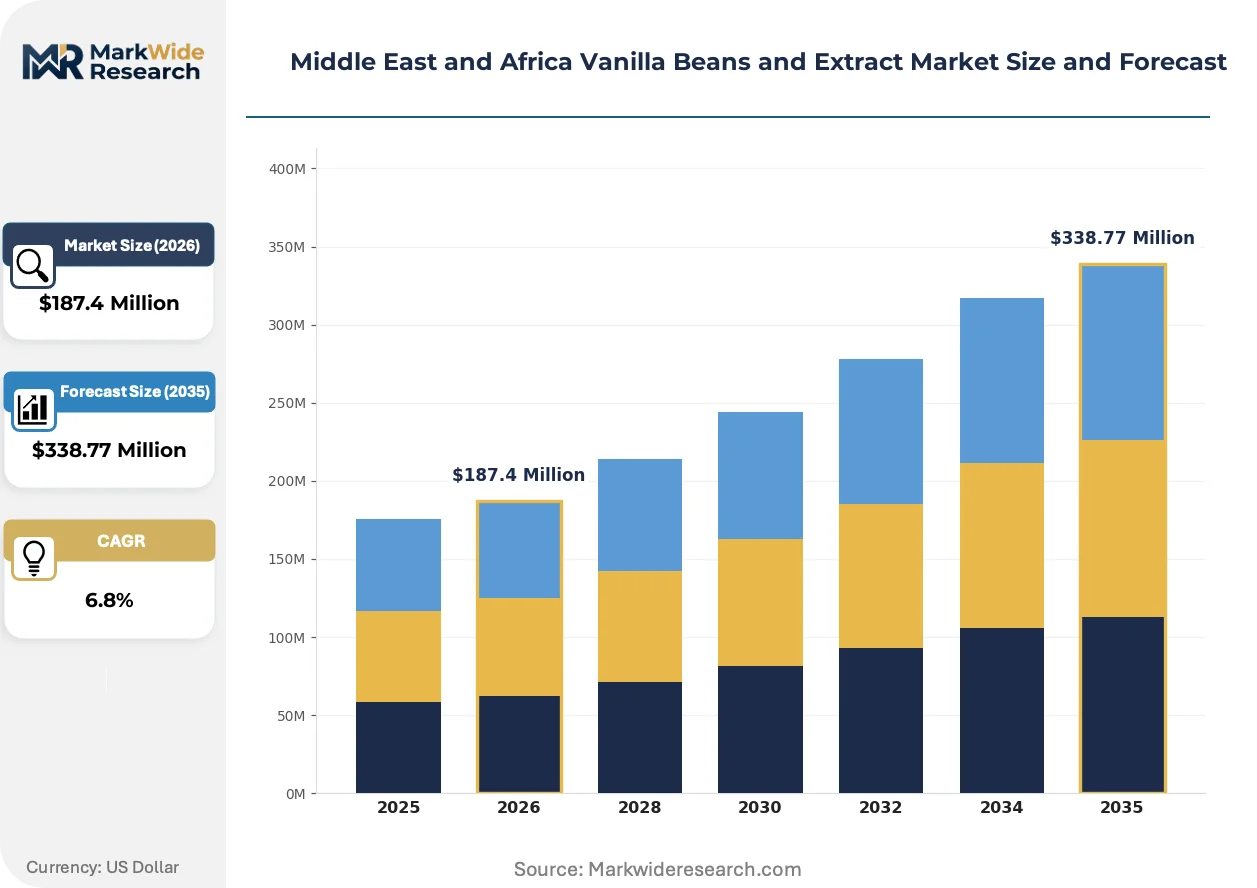
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Extracts, Powders, Paste End Use: Food & Beverage, Cosmetics, Pharmaceuticals, Baking Sales Channel: Online, Supermarkets, Specialty Stores, Wholesale Quality Grade: Premium, Grade A, Grade B, Organic |
| Companies Covered | Symrise AG, Givaudan, International Flavors & Fragrances (IFF), Kerry Group Plc, Archer-Daniels-Midland Company, Synthite Industries Ltd., Nielsen-Massey Vanillas, Heilala Vanilla, Sensient Technologies Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Vanilla Beans and Extract Market Shifts & Advancements
Glycerin-based extraction methods are displacing traditional alcohol solvents across Middle East and Africa formulation labs, driven by halal compliance requirements and clean-label positioning in Gulf retail channels.
Supercritical CO2 extraction technology is migrating from pharmaceutical flavor isolation into vanilla processing, enabling higher vanillin recovery rates without thermal degradation. Industrial bakery manufacturers in South Africa adopt this method at pilot scale for premium product lines. The technology is compressing solvent residue compliance costs while opening organic-certified extract production previously blocked by alcohol-based process limitations.
Gulf Standards Organization halal certification protocols now mandate full ingredient genealogy documentation from farm to final formulation. Extract suppliers must maintain chain-of-custody records through every curing and processing stage. Premium hospitality procurement hubs in Dubai and Riyadh enforce these standards most stringently, rejecting batches with documentation gaps even when analytical purity meets technical specifications.
Direct bean sourcing relationships are displacing traditional importer-distributor networks among South African artisan chocolate makers and UAE luxury hotel pastry programs. Buyers now contract directly with Madagascar curing cooperatives for specific harvest lots. This pattern concentrates in Cape Town's specialty food manufacturing corridor and Dubai's fine dining supply chain, where visual pod quality and origin story carry pricing power beyond commodity extract equivalents.
Middle East and Africa Vanilla Beans and Extract Market Segmentation
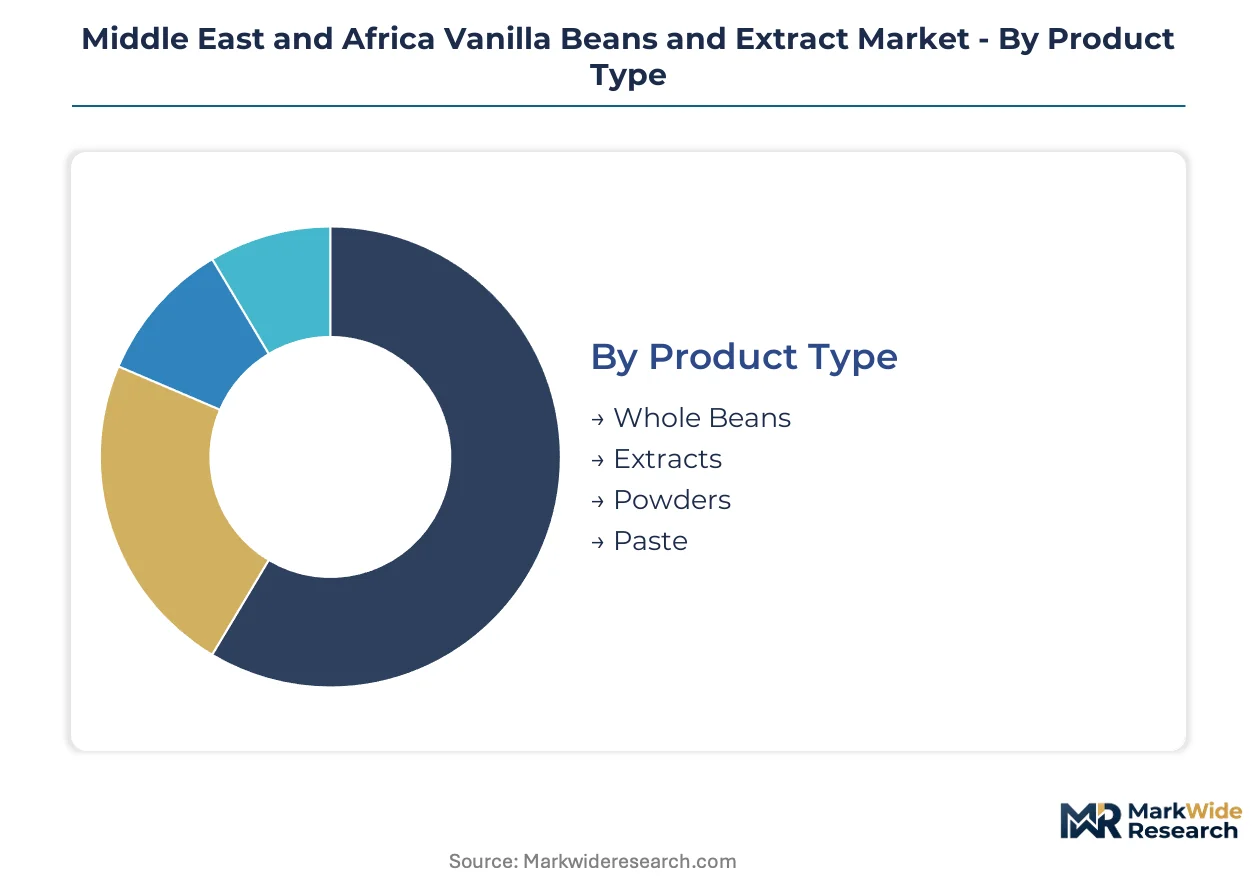
Segmentation in Middle East and Africa vanilla markets reveals how halal certification requirements and clean-label positioning reshape procurement patterns across Gulf hospitality hubs and South African manufacturing corridors. Distinct buyer behaviors emerge between artisan bakers seeking visual pod quality and industrial processors prioritizing formulation convenience.
Product Type:
Formulation convenience spans alcohol-based extraction for industrial scale to glycerin-based alternatives meeting Gulf Standards Organization halal protocols.
- Whole Beans:Cured vanilla planifolia and tahitensis pods retain visual presence signaling quality in artisan chocolate and patisserie channels. Dubai luxury hotel pastry programs and Cape Town specialty manufacturers absorb Grade A material at premium pricing where origin story carries procurement weight.
- Extracts:Alcohol- and glycerin-based solutions containing vanillin and aromatic compounds dominate industrial bakery and beverage applications for formulation precision. South Africa's processed food manufacturing corridor and UAE hospitality procurement hubs drive volume concentration as FSSAI-aligned specifications filter supplier eligibility.
- Powders:Spray-dried vanilla derivatives serve dry-mix confectionery and instant beverage applications requiring extended shelf stability without liquid solvent handling.
- Paste:Concentrated vanilla suspensions with visible seed content occupy premium bakery niches where visual authenticity differentiates finished products.
The dominant share belongs to Extracts, while Paste is closing the gap fastest among Gulf artisan bakery expansions.
End Use:
Application intensity varies sharply between mass-market volume absorption and premium positioning where ingredient genealogy commands pricing power.
- Food & Beverage:Industrial bakery, dairy, and beverage manufacturing across Saudi Arabia and South Africa consumes standard-grade extracts for clean-label positioning. FSSAI-equivalent additive standards enforce vanillin content thresholds that filter uncertified suppliers from premium segment participation.
- Baking:Artisan patisserie chains in Johannesburg and Dubai absorb Grade A whole beans and specialty pastes where visual pod quality signals craftsmanship. Direct sourcing relationships with Madagascar curing cooperatives disintermediate traditional importer networks in this channel.
- Cosmetics:Fragrance and personal care applications in UAE luxury goods manufacturing utilize vanilla extracts for natural positioning in halal-certified product lines.
- Pharmaceuticals:Excipient and flavor-masking applications require documented traceability through every curing stage to satisfy Gulf regulatory documentation demands.
Food & Beverage holds the largest volume position, though Baking demonstrates the steepest expansion trajectory as artisan chain penetration accelerates across Gulf urban centers.
Sales Channel:
Channel selection reflects buyer scale and certification documentation requirements rather than pure price sensitivity.
- Wholesale:Bulk procurement serving industrial food manufacturers across South Africa's processing corridor and Saudi dairy operations demands batch-level traceability documentation.
- Specialty Stores:Cape Town and Dubai retail outlets supply artisan bakers with origin-specific whole bean lots carrying harvest-lot pedigrees.
- Online:Digital platforms connecting Madagascar curers directly to UAE hospitality procurement hubs compress traditional distributor margins.
- Supermarkets:Mass retail distribution of standard-grade extracts and powders serves home baking segments with FSSAI-aligned labeling requirements.
Wholesale retains the deepest volume penetration, while Online channels are gaining share fastest through disintermediation of bean-to-buyer relationships.
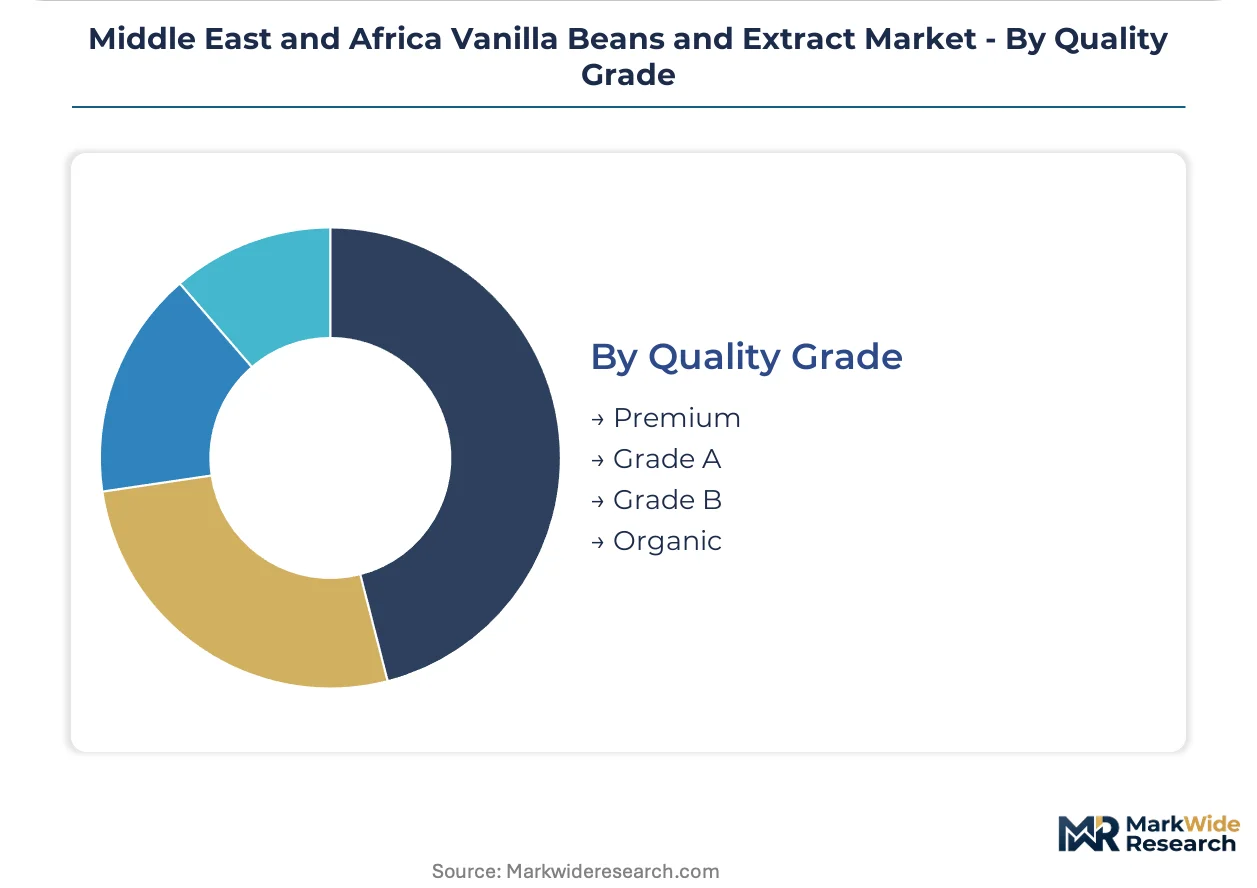
Quality Grade:
Grade stratification aligns with end-use certification requirements and buyer willingness to absorb traceability documentation costs.
- Premium:Ultra-high-vanillin content beans with complete chain-of-custody documentation serve Dubai and Riyadh hospitality procurement hubs where analytical purity alone fails without genealogy records.
- Organic:Certified material requiring reciprocity agreements between African producer nations and Gulf import authorities for market access eligibility in premium retail positioning.
- Grade A:Standard high-quality cured beans with visible oil content satisfy artisan chocolate makers and patisserie programs where visual quality signals differentiate finished products.
- Grade B:Lower moisture and aesthetic grade material feeds extract manufacturing for mass-market confectionery applications where vanillin content meets specification without premium pod presentation.
Premium grade commands the highest margin concentration, with Organic certification expanding most quickly as equivalence determinations reshape competitive eligibility across African-Gulf trade corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fractures sharply across Middle East and Africa vanilla procurement. South African industrial bakers absorb volume at standard-grade pricing while UAE hospitality buyers pay premiums for documented bean genealogy.
United Arab Emirates
Dubai's luxury hotel pastry programs and Riyadh's fine dining supply chains absorb Grade A whole beans at premium pricing. Gulf Standards Organization halal protocols mandate full ingredient genealogy documentation from farm to formulation. Procurement hubs in Dubai enforce these standards most stringently, rejecting batches with documentation gaps.
Saudi Arabia
Industrial dairy and bakery manufacturing across Riyadh and Jeddah consumes glycerin-based extracts for halal compliance. SFDA-aligned import specifications enforce vanillin content thresholds and solvent residue limits. The Eastern Province's food processing corridor concentrates mass-market extract absorption for clean-label positioning.
South Africa
Cape Town's specialty chocolate makers and Johannesburg's artisan patisserie chains drive premium bean demand. The Department of Health's food additive regulations enforce FSSAI-equivalent purity specifications. The Western Cape's specialty food manufacturing corridor concentrates direct sourcing relationships with Madagascar curing cooperatives.
Qatar
Doha's hospitality procurement sector absorbs premium extracts for luxury hotel and restaurant applications. Unified Gulf Standards Organization halal certification reduces duplicate testing costs for compliant suppliers. The Lusail development's food service infrastructure concentrates high-end vanilla procurement for international brand presence.
Madagascar
The Sava region's curing cooperatives supply raw beans to Middle East and African extract manufacturers. Cyclone vulnerability exposes supply chains to weather-driven shocks every harvest cycle. Antalaha and Sambava's primary curing operations attract backward integration investments from regional processors seeking cost discipline.
Middle East and Africa Vanilla Beans and Extract Market Competitive Landscape
Backward-integrated specialists and flavor-compounding service providers split the market along the value-added spectrum. The vendor base concentrates around three strategic archetypes: Madagascar-curing-integrated extractors, Gulf-hospitality-focused premium suppliers, and industrial-scale flavor houses. Consolidation pressure favors players with documented halal certification and bean-to-extract traceability systems. Competitive moves center on curing infrastructure acquisition and specialized technical partnerships with dairy processors.
Within the premium-tier vector, Nielsen-Massey Vanillas and Heilala Vanilla occupy positions anchored in Grade A bean direct sourcing and origin-story marketing. Symrise AG exemplifies the backward-integrated archetype through Madagascar-sourced curing operations. Givaudan sits within the flavor-compounding service tier, anchoring regional presence through technical partnerships with Gulf dairy processors.
| Leading Market Players |
|---|
| Symrise AG |
| Givaudan |
| International Flavors & Fragrances (IFF) |
| Kerry Group Plc |
| Archer-Daniels-Midland Company |
| Synthite Industries Ltd. |
| Nielsen-Massey Vanillas |
| Heilala Vanilla |
| Sensient Technologies Corporation |
| Others |
Supply & Pricing Matrix
Durban-to-Jeddah maritime corridors carry Madagascar-sourced beans through Suez Canal chokepoints, where freight cost volatility amplifies price spreads between Gulf hospitality buyers absorbing full traceability premiums and South African industrial processors negotiating standard-grade volumes. This logistics architecture concentrates pricing power with curing-integrated extractors while fragmenting margin capture across spot-market dependent distributors.
Pricing Analysis
After-sales technical service contracts and halal certification renewal fees now constitute the dominant lifetime value drivers for extract suppliers serving Gulf dairy processors. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and chain-of-custody documentation depth. Price differentiation hinges on vanillin content thresholds and solvent residue compliance verified through SFDA-aligned testing protocols. Pricing pressure stems from synthetic vanillin substitution in mass-market confectionery applications, compressing natural extract margins at the economy tier. South African industrial bakers exhibit highest price sensitivity due to FSSAI-equivalent additive cost absorption, while UAE luxury hotel pastry programs demonstrate lowest sensitivity where origin story carries procurement weight.
Supply Chain Analysis
Extended payment terms from UAE hospitality procurement hubs and supply-chain finance facilities anchored in Dubai's trade finance infrastructure are reshaping working capital dynamics for Madagascar curing cooperatives. Geographic supply concentration centers on Madagascar's Sava region, with secondary sourcing from Uganda and Tanzania emerging for organic-certified material. Raw material dependencies encompass cured vanilla planifolia pods, glycerin solvents for halal-compliant extraction, and supercritical CO2 processing equipment. Single-source vulnerability from cyclone exposure in the Sava region threatens supply continuity every harvest cycle. Distribution runs through Antalaha and Sambava curing cooperatives to regional extract manufacturers, with direct-to-buyer digital platforms disintermediating traditional importer networks in South Africa and the UAE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across halal certification tiers and clean-label positioning requirements creates specialized niche opportunities for differentiated service providers. The divergence between artisan bakery genealogy demands and industrial processor formulation convenience splinters addressable markets into distinct competitive arenas.
For Market Incumbents: Harden halal certification documentation systems against Gulf Standards Organization timeline compression by investing in real-time batch tracking infrastructure at Madagascar curing facilities. Consolidate backward integration into Sava region primary curing operations to secure cost discipline against spot-market volatility. Defend premium segment positioning through specialized flavor compounding technical partnerships with Saudi dairy processors, insulating against commodity extract price erosion.
For New Entrants and Emerging Players: Pursue glycerin-based extraction capacity expansion targeting South Africa's processed food manufacturing corridor, where FSSAI-equivalent specifications filter incumbent eligibility. Capture white-space in direct-sourcing digital platforms connecting Cape Town artisan chocolate makers to Madagascar curing cooperatives, disintermediating traditional distributor margins. Lead with organic certification reciprocity expertise as Gulf-African equivalence determinations reshape competitive eligibility.
For Investors and Strategic Acquirers: Halal-certified extract specialists with documented Madagascar curing relationships represent the priority acquisition archetype for premium segment exposure. Long-term viability hinges on regulatory reciprocity durability across African producer nations and Gulf import authorities over the five-to-ten year horizon. Monitor organic equivalence agreement announcements between specific African nations and UAE/Saudi regulators as inflection indicators for premium segment competitive reshuffling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Madagascar Curing | Symrise AG's Sava region operations demonstrate cost discipline advantages over spot-market dependent competitors. |
| Specialized Flavor Compounding Services | Givaudan's technical partnerships with Gulf dairy processors enable customized vanilla profiles beyond commodity offerings. |
| Halal Certification Documentation Systems | Real-time chain-of-custody records satisfy Dubai and Riyadh hospitality procurement hub rejection protocols for documentation gaps. |
| Direct Sourcing Digital Platforms | E-commerce channels connecting South African artisan bakers to Madagascar curers compress traditional importer-distributor margins. |
| Organic Equivalence Agreement Positioning | Reciprocity determinations between African producer nations and Gulf authorities reshape premium segment competitive eligibility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the Middle East and Africa vanilla value chain, including Madagascar curing cooperative managers, UAE hospitality procurement directors, South African industrial bakery R&D heads, Gulf dairy processor flavor technologists, and specialty chocolate makers in Cape Town. Secondary validation drew from Gulf Standards Organization halal protocol documentation, South African Department of Health food additive regulations, FSSAI-aligned import specification frameworks, customs and trade flow data, and SEC filings from publicly traded flavor houses. Bottom-up volume estimates from end-use application intensity were triangulated against top-down market sizing from trade corridor value flows.
Calibration against historical price volatility in Madagascar bean markets and documented halal certification timeline compression informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled encompass product type, quality grade tier, end-use application intensity, sales channel documentation requirements, and regional regulatory cluster alignment. CAGRs were derived from weighted average growth contributions across these segments. Industry-specific forecast inputs included cyclone frequency patterns in the Sava region and organic certification reciprocity negotiation status between African producer nations and Gulf import authorities.
Sensitivities concentrate around Madagascar weather-driven supply shocks, halal certification protocol evolution across Gulf Cooperation Council states, and synthetic vanillin substitution rates in mass-market confectionery applications. Forecasts reflect assumptions regarding regulatory reciprocity durability and clean-label positioning persistence in industrial food manufacturing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Savory Flavor Blends Market