
 Culinary Powder Market | 2026-2036
Culinary Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Culinary Powder Market Analytics
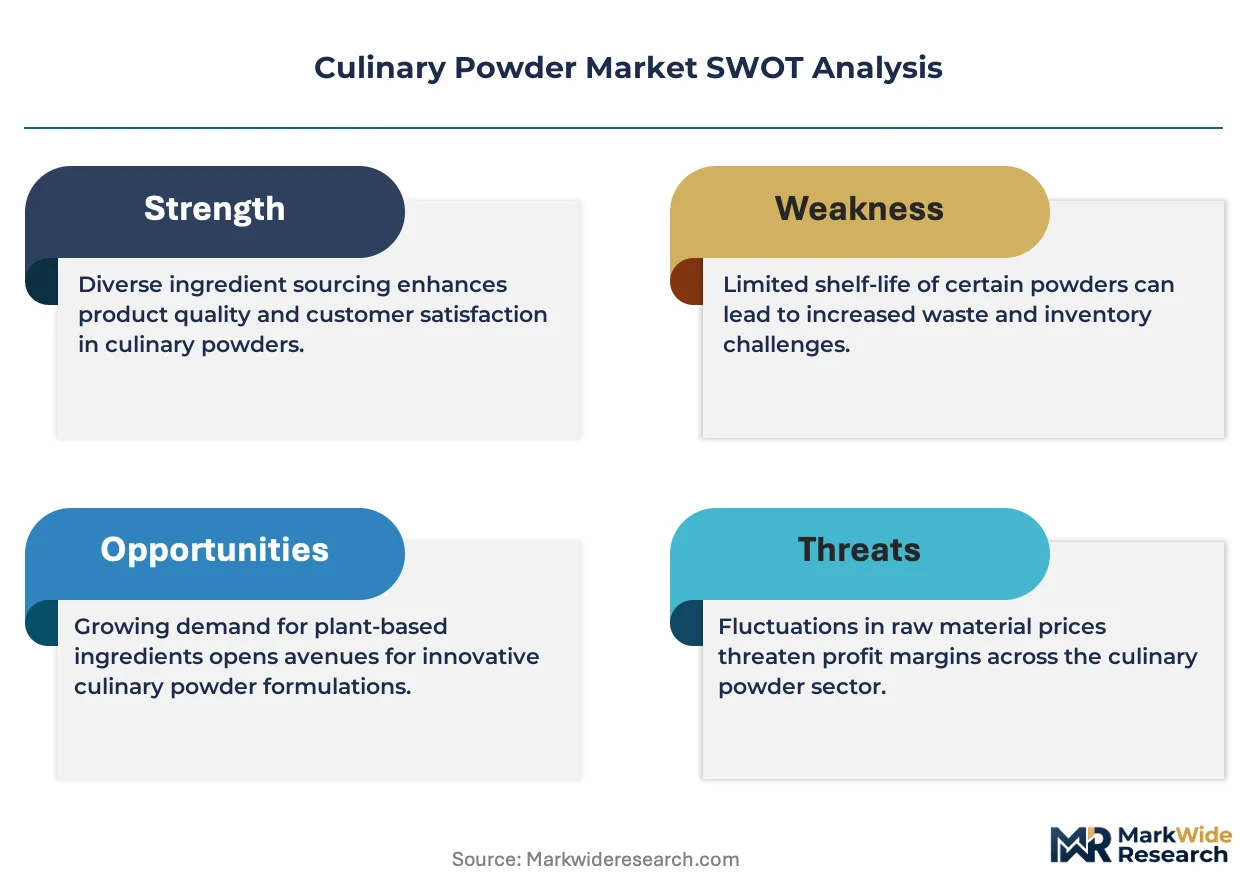
REACH compliance is rebalancing the cost-of-entry calculus for European-sourced herb powders and seasoning blends. Kerry Group plc leverages its integrated taste and nutrition platforms to sustain R&D intensity across clean-label flavoring portfolios. Fonterra Co-operative Group Limited anchors its position in dairy-derived culinary powders through backward integration into milk protein streams. Givaudan differentiates via biotechnology-driven natural flavor extraction that competes with conventional solvent-based processes.
Culinary powders comprise dehydrated, milled, and standardized food ingredients with particle sizes typically ranging from 50 to 500 microns, engineered for dispersion, solubility, and shelf-stable flavor delivery in processed foods. Spice powders retain dominant volume share due to universal applicability across cuisines, though flavoring powders command premium positioning in snack production and convenience food formulations. Granulated form factors lead industrial procurement for their flowability in automated seasoning lines, while microfine grades capture margin pools in instant beverage and soup applications where rapid dissolution determines performance.
The FDA enforces pathogen and adulteration standards for imported spice powders under FSMA, while the EFSA sets maximum residue limits for pesticide contaminants in herb powders entering European food manufacturing. India's FSSAI mandates labeling and additive disclosures that shape export readiness for domestic seasoning blend producers. Stakeholders must monitor divergence between emerging economy self-certification regimes and OECD-aligned third-party audit requirements that will determine market access tiering.
Market Dynamics
The FDA's intensified FSMA enforcement on imported spice powders is compressing supplier qualification timelines while simultaneously elevating traceability infrastructure costs across the value chain. This regulatory pressure is concentrating procurement authority among processors capable of sustaining multi-tier audit regimes.
Growth Catalysts
- Snack manufacturing expansion:Emerging economy production lines in India and Vietnam are absorbing record volumes of seasoning blends for extruded and fried snack categories. This demand pull is tightening supply for specialized flavoring powders.
- REACH compliance reconfiguration:European herb powder imports face elevated cost-of-entry thresholds that favor established processors with dedicated regulatory affairs functions. This barrier is filtering out smaller competitors.
- Clean-label biotechnology:Enzymatic extraction methods for natural flavor compounds are displacing solvent-based processes in premium applications. This shift is opening margin pools in organic and non-GMO certified segments.
Market Restraints
- Input cost volatility:Dairy protein concentrate prices fluctuate with Fonterra's auction cycles, compressing margins for culinary powder formulators dependent on milk-derived ingredients.
- Supply concentration risk:Madagascar vanilla and Indian chili powder origins dominate respective categories, creating single-origin vulnerability to climate and geopolitical disruption.
- Technical dissolution limits:Microfine grades below 50 microns exhibit agglomeration in high-humidity packaging, restricting performance claims in instant beverage applications.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya present white space for seasoning blend localization, with nascent food processing infrastructure creating first-mover advantages for technical service-intensive suppliers.
- Regulatory tailwind from EU Green Deal:Carbon footprint disclosure requirements for imported food ingredients will favor processors with renewable energy-intensive spray-drying operations.
- Direct-to-manufacturer platforms:B2B e-procurement channels are compressing distributor layers, enabling specialty powder producers to capture margin previously allocated to regional intermediaries.
Industry Challenges
- Certification timeline compression:FSSAI export-readiness audits for Indian seasoning blend producers now require 18-24 month qualification cycles, straining working capital for mid-tier processors.
- Legacy equipment retrofit costs:Automated seasoning line integration demands pneumatic conveying system upgrades that capex-constrained snack manufacturers in Southeast Asia cannot absorb without financing support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Culinary Powder Market |
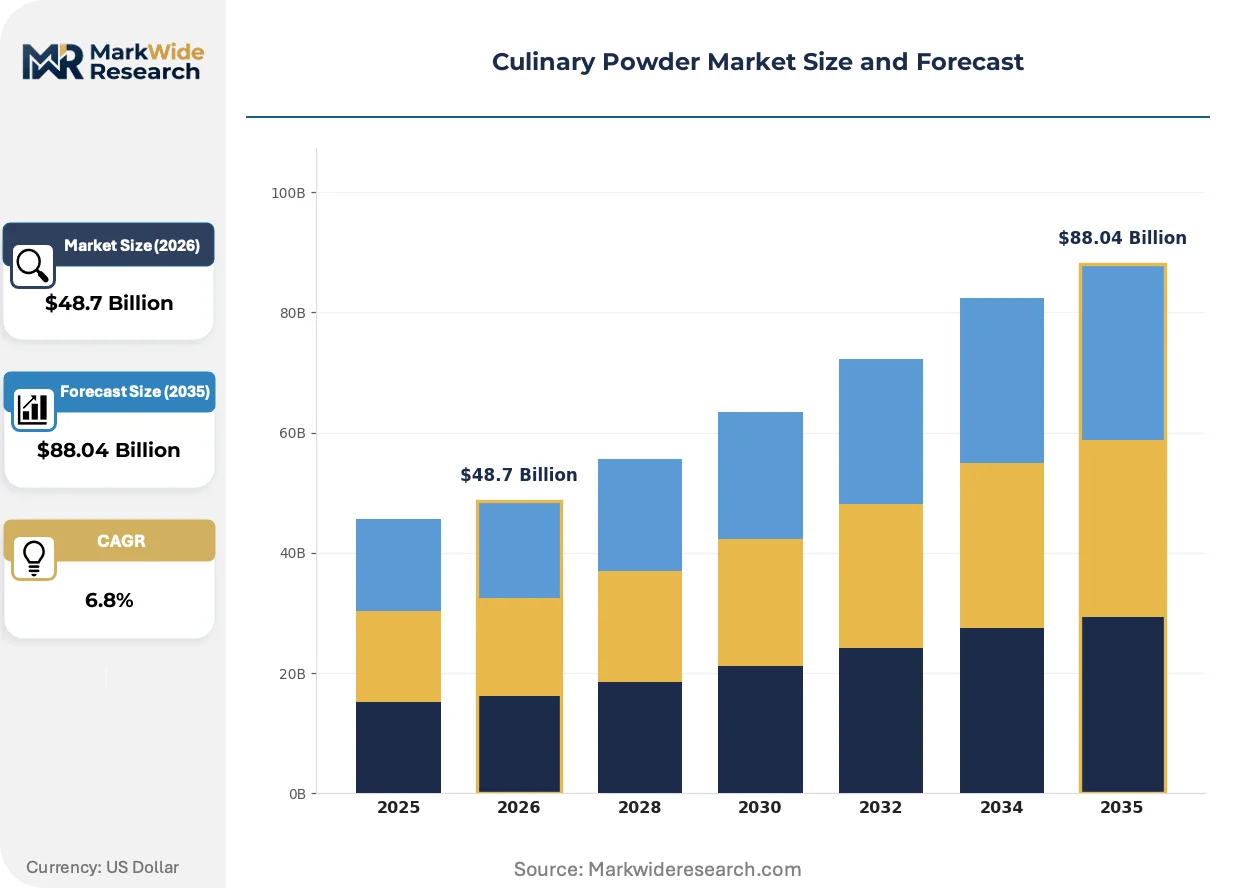
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spice Powders, Herb Powders, Flavoring Powders, Seasoning Blends Application: Food Industry, Catering Services, Home Cooking, Snack Production Form: Granulated, Fine, Coarse, Microfine Packaging Type: Bags, Jars, Pouches, Canisters |
| Companies Covered | Döhler Group SE, Arla Foods amba, Puratos NV, Fonterra Co-operative Group Limited, Lactalis Ingredients, Kerry Group plc, Givaudan, Kanegrade Ltd, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Culinary Powder Market Evolving Landscape
Biotechnology and automation are converging to reshape extraction and formulation economics, while regulatory disclosure mandates are rewriting competitive differentiation criteria across sourcing and processing tiers.
Continuous spray-drying systems equipped with real-time moisture sensors and AI-driven airflow control are automating particle size standardization that previously required batch-wise manual adjustment. Snack manufacturers in India and Mexico are adopting these systems at replacement cycle points to reduce seasoning blend variability. This automation is compressing the quality assurance headcount and skill requirements that historically differentiated tier-one from tier-two suppliers.
REACH's expanded substance restrictions on residual solvents in herb powders are forcing reformulation of extraction protocols for European-bound shipments. The regulation's industrial consequence is a bifurcation between processors investing in supercritical CO2 infrastructure and those exiting the EU market entirely. Seasoning blend manufacturers serving pan-European customers are consolidating supplier bases to reduce audit burden.
Clean-label procurement criteria now mandate disclosure of carrier agents and anti-caking additives that were previously unspecified in commercial specifications. Foodservice distributors and co-manufacturers are displacing traditional spot-buying with multi-year framework agreements that lock in additive-free formulations. This specification tightening is most visible in Nordic markets and premium private-label channels in Germany.
Culinary Powder Market Segmentation
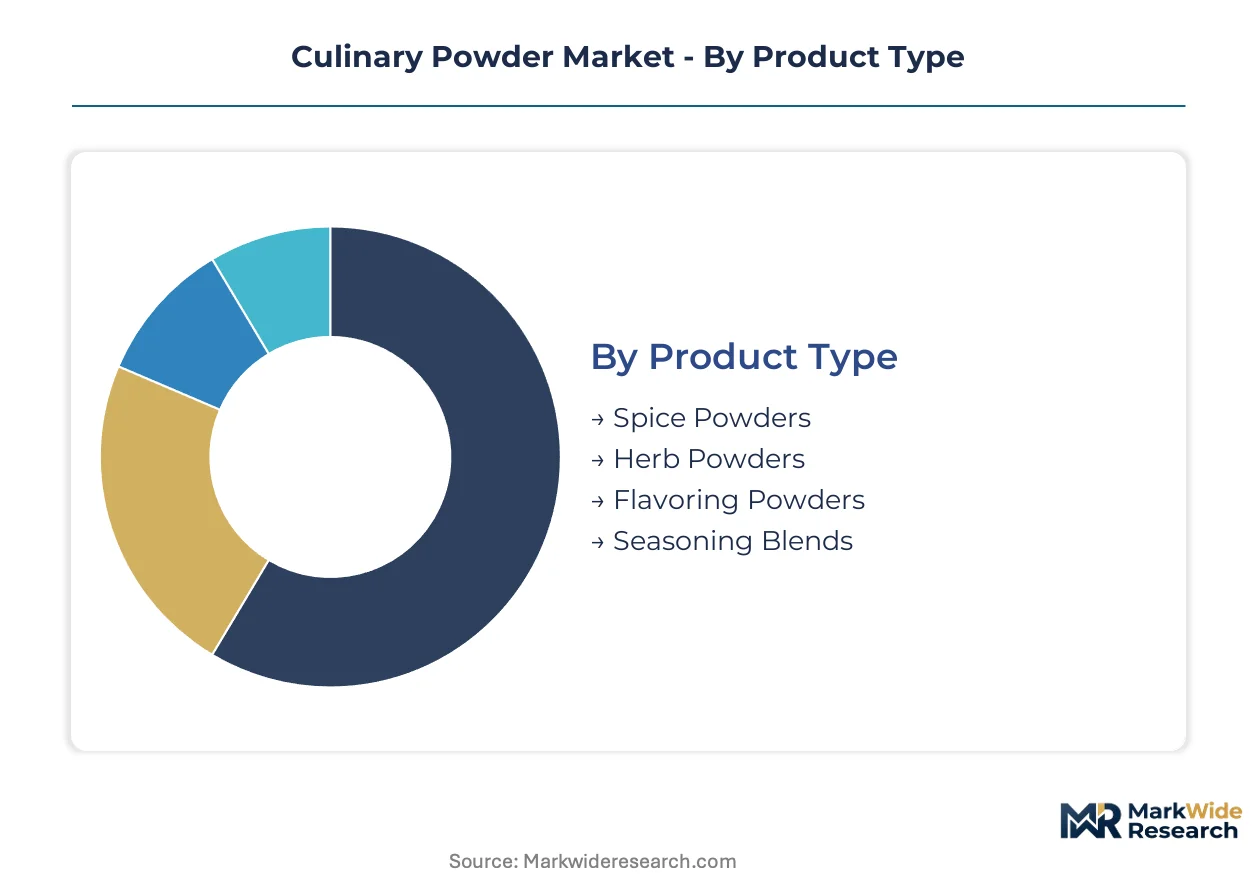
Culinary powder procurement decisions pivot on dissolution performance, shelf stability, and line integration requirements. Distinct particle engineering standards separate commodity-grade from performance-critical applications across food manufacturing tiers.
Product Type:
Integration depth varies sharply: spice and herb powders function as standalone ingredients, while flavoring powders and seasoning blends embed into complex formulations with carrier dependencies.
- Spice Powders:Dehydrated, milled seeds, fruits, or roots standardized for color, volatile oil content, and heat units. Indian chili powder and Malagasy vanilla dominate procurement volumes, though climate vulnerability concentrates supply risk in single-origin corridors.
- Herb Powders:Leaf-derived materials processed to preserve essential oil profiles through controlled temperature milling. REACH compliance costs are filtering smaller European-bound suppliers, consolidating procurement authority among processors with dedicated regulatory functions.
- Flavoring Powders:Encapsulated or plated flavor systems engineered for heat stability in extrusion and frying operations. Biotechnology-driven enzymatic extraction is displacing solvent-based methods in premium organic segments.
- Seasoning Blends:Multi-component systems combining salts, flavor carriers, and anti-caking agents for automated snack line dispensing. FSSAI export-readiness audits now require 18-24 month qualification cycles for Indian producers.
Spice powders lead volumes today; seasoning blends are gaining share fastest.
Application:
Cost tier stratification separates capital-intensive industrial users from price-sensitive consumer channels, with divergent specification tolerances and procurement rhythms.
- Food Industry:Large-scale manufacturers of sauces, soups, and ready meals demanding batch consistency certificates and allergen segregation protocols. Automated seasoning line integration requires pneumatic conveying compatibility.
- Catering Services:High-turnover institutional kitchens prioritizing portion control and rapid inventory velocity. This segment absorbs economy-grade blends in bulk formats with minimal customization.
- Home Cooking:Retail-packaged specialty and ethnic varieties sold through supermarket and e-commerce channels. Clean-label carrier disclosure mandates are tightening specifications in Nordic and German premium private-label markets.
- Snack Production:Extruded and fried product manufacturers in India and Vietnam absorbing record volumes of specialized flavoring powders. Continuous spray-drying adoption is compressing quality assurance headcount requirements.
Food industry procurement dominates absolute spend; snack production is climbing the fastest.
Form:
Particle size distribution directly determines flowability, dissolution kinetics, and packaging stability—each specification locking out incompatible equipment configurations.
- Granulated:300-500 micron particles optimized for automated seasoning line flowability. Industrial snack manufacturers prefer this grade for pneumatic conveying compatibility and reduced dust generation.
- Fine:100-300 micron materials balancing dispersion speed with handling characteristics. Soup and sauce manufacturers specify this grade for moderate shear mixing environments.
- Coarse:500+ micron visible inclusions providing texture and visual appeal in premium retail seasoning blends. Limited industrial use due to segregation risks in high-speed packaging.
- Microfine:Sub-50 micron powders engineered for instant beverage and soup applications requiring rapid dissolution. Agglomeration in high-humidity packaging restricts performance claims and shelf-life guarantees.
Granulated forms anchor industrial procurement today; microfine grades command the steepest expansion trajectory in premium instant applications.
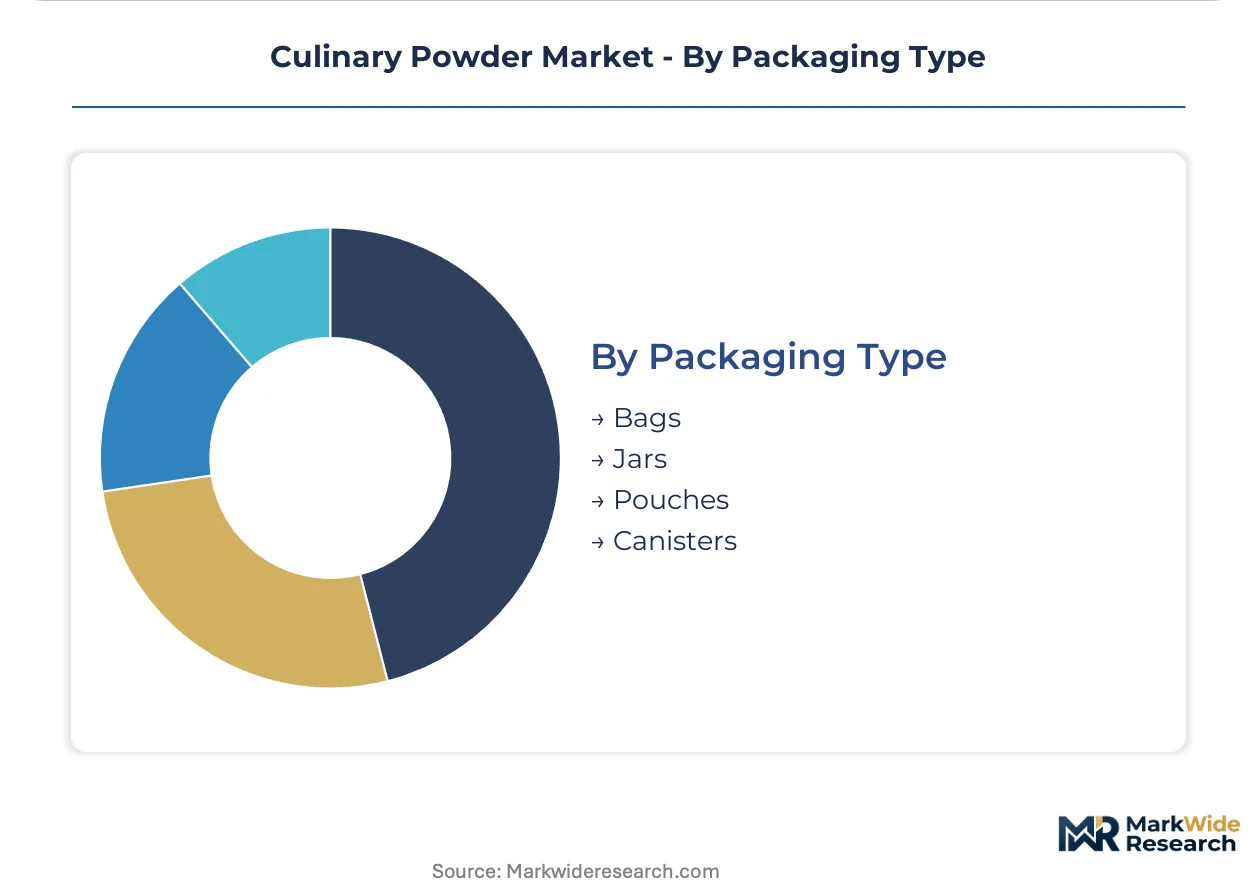
Packaging Type:
Volume scale and distribution channel economics dictate format selection, with sustainability disclosure pressures reshaping material specifications.
- Bags:Multi-wall paper or laminated structures for 5-25kg industrial quantities. EU Green Deal carbon footprint requirements favor suppliers with renewable energy-intensive operations.
- Jars:Glass containers for retail spice and herb powders emphasizing premium positioning and reuse potential. Higher unit logistics costs limit penetration in price-sensitive emerging markets.
- Pouches:Flexible films with reseal features dominating single-serve and travel-format seasoning. E-commerce channel growth is accelerating demand for ship-ready pouch configurations.
- Canisters:Rigid plastic or composite cylinders for high-frequency home cooking segments. This format faces substitution pressure from lightweight pouch alternatives in sustainability-focused markets.
Bags capture industrial volume leadership; pouches are expanding most quickly through direct-to-manufacturer platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The culinary powder industry traces its modern industrial foundations to nineteenth-century European spice milling and twentieth-century American spray-drying innovations for dairy and flavor encapsulation. Processing technology diffusion from these origins now supports diversified production networks across multiple continents.
United States
Snack manufacturing corridors in Pennsylvania and California drive concentrated demand for seasoning blends and flavoring powders. FDA intensifies FSMA enforcement on imported spice powders, compressing supplier qualification timelines to 12-18 months. Chicago-area food ingredient distributors are consolidating procurement authority among processors capable of sustaining multi-tier audit regimes.
India
Domestic consumption and export-oriented processing capacity are expanding in parallel across Gujarat and Maharashtra. FSSAI mandates labeling and additive disclosures that shape export readiness for seasoning blend producers. The Guntur chili powder belt and Kerala spice processing clusters face 18-24 month qualification cycles for FSSAI export-readiness audits.
Germany
Clean-label procurement criteria from Nordic and domestic premium private-label channels tighten specifications for carrier-free formulations. REACH compliance costs filter smaller European-bound herb powder suppliers, consolidating procurement authority among processors with dedicated regulatory affairs functions. Hamburg and Frankfurt serve as consolidation points for pan-European seasoning blend distribution.
Vietnam
Emerging economy production lines for extruded and fried snacks absorb record volumes of specialized flavoring powders. The country's national food safety regulator aligns with ASEAN harmonization protocols while maintaining distinct additive disclosure requirements. Ho Chi Minh City processing zones attract technical service-intensive suppliers establishing Southeast Asian manufacturing footholds.
Brazil
White space for seasoning blend localization exists in nascent food processing infrastructure across São Paulo and Minas Gerais states. ANVISA enforces pathogen and adulteration standards for imported spice powders that diverge from OECD-aligned third-party audit requirements. Campinas industrial corridors present first-mover advantages for suppliers offering pneumatic conveying system integration support.
Culinary Powder Market Competitive Landscape
The competitive structure tilts toward diversified ingredient conglomerates with integrated taste and nutrition platforms. Tier-one processors sustain R&D intensity across clean-label portfolios while mid-tier specialists concentrate on single-origin spice sourcing and regional seasoning formulations. Two dominant competitive moves define current positioning: biotechnology licensing for enzymatic extraction methods, and backward integration into captive milk protein streams for dairy-derived culinary powders.
Among European-based diversified ingredient groups, Döhler Group SE, Kerry Group plc, and Givaudan occupy positions spanning flavor extraction, encapsulation technology, and pan-regional distribution infrastructure. Döhler Group SE exemplifies the integrated taste platform archetype. Kerry Group plc represents biotechnology-driven natural flavor extraction capabilities. Givaudan anchors premium positioning in enzymatic extraction methods competing with conventional solvent-based processes.
| Leading Market Players |
|---|
| Döhler Group SE |
| Arla Foods amba |
| Puratos NV |
| Fonterra Co-operative Group Limited |
| Lactalis Ingredients |
| Kerry Group plc |
| Givaudan |
| Kanegrade Ltd |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FSSAI-export-ready and domestic-only seasoning blend producers manifests in both pricing power and supply chain configuration. Indian processors absorbing 18-24 month qualification cycles command contract premiums from pan-European buyers, while uncertified competitors remain trapped in spot-market commodity sales with compressed margins.
Pricing Analysis
Service-bundled technical support versus unbundled commodity supply separates pricing architectures across the culinary powder value chain. Three-tier pricing structure across premium, standard, and economy levels tracks certification status, with FSSAI-export-ready and REACH-compliant tiers capturing 15-25% uplifts over domestic-grade equivalents. Cost compression in economy-grade spice powders intensifies as Fonterra's auction volatility transmits through dairy-protein-dependent flavoring formulations. Snack manufacturers in Vietnam and India exhibit highest price sensitivity due to capex-constrained pneumatic conveying retrofits, while Nordic clean-label buyers prioritize carrier-free specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Hamburg, Mumbai, and Ho Chi Minh City anchor hub-and-spoke patterns for European, Middle Eastern, and Southeast Asian fulfillment. Raw material sourcing concentrates in India for chili powder and spice extracts, Madagascar for vanilla, and New Zealand for dairy protein streams. Single-origin vulnerability to climate disruption in Madagascar and the Guntur belt constitutes the dominant structural risk. Distribution runs through technical service-intensive suppliers for automated seasoning line integration, with direct-to-manufacturer platforms compressing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FSMA intensification and REACH expansion continuously revalue certification assets. The FDA's compressed supplier qualification timelines have transformed audit-ready infrastructure into a demand-generating mechanism rather than mere compliance cost.
For Market Incumbents: Deepen backward integration into captive milk protein streams to insulate margin from Fonterra auction volatility. Fortify FSSAI-export-ready capacity in Gujarat and Maharashtra clusters to capture procurement authority concentration among pan-European seasoning blend buyers. Biotechnology licensing for enzymatic extraction methods offers defensive positioning against solvent-based process displacement.
For New Entrants and Emerging Players: Launch via direct-to-manufacturer B2B e-procurement platforms to bypass entrenched distributor layers in underpenetrated African markets. Nigeria and Kenya present accessible white space where nascent food processing infrastructure rewards technical service-intensive entry. Target seasoning blend localization for extruded snack production lines where pneumatic conveying integration support creates switching costs.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier Indian processors face working capital strain from 18-24 month FSSAI qualification cycles. Long-term viability favors diversified ingredient conglomerates with integrated taste platforms spanning extraction, encapsulation, and pan-regional distribution. Acquisition target archetype: REACH-compliant herb powder processors with dedicated regulatory affairs functions. Signal to watch: divergence between emerging economy self-certification regimes and OECD-aligned third-party audit requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Infrastructure Investment | REACH compliance for European herb powder shipments filters solvent-dependent competitors from EU market access. |
| Continuous Spray-Drying System Deployment | AI-driven particle standardization reduces quality assurance headcount requirements for Indian snack manufacturers. |
| Backward Integration into Milk Protein Streams | Fonterra auction cycle insulation secures margin stability for dairy-derived culinary powder formulators. |
| Direct-to-Manufacturer Platform Launch | B2B e-procurement channels capture margin previously allocated to regional intermediaries in fragmented markets. |
| Clean-Label Carrier-Free Formulation Lock-in | Multi-year framework agreements with Nordic and German premium private-label channels reduce spot-buying volatility. |
Research Methodology
Bottom-up snack production line and food industry procurement modeling reconciled against top-down spice powder and seasoning blend supply tracking forms the analytical core. Primary interviews with plant managers at extruded snack facilities, procurement leads at seasoning blend distributors, FSSAI regulatory consultants, and technical R&D directors at flavor extraction operations combined with secondary validation from FDA FSMA guidance documents, EFSA maximum residue limit databases, FSSAI labeling directives, customs trade data for chili powder and vanilla imports, and SEC filings from diversified ingredient conglomerates.
Input-output matrix framing connects raw material availability in Madagascar, India, and New Zealand through processing capacity utilization rates to end-use absorption across food industry, snack production, catering services, and home cooking segments. Segmentation dimensions span product type, application, particle size form factor, and packaging format across the projection horizon. CAGRs derive from regression against historical volume trajectories and elasticity estimates for clean-label premiumization and automated line adoption.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate disruption in single-origin supply corridors and divergent regulatory recognition between emerging economy self-certification and OECD-aligned audit regimes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Asia-Pacific Prepared Mustard Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Mustard Brown Extract Market