
 Paprika Market | 2026-2036
Paprika Market Size, Share, and Industry Trends Forecast 2026-2036
Paprika Market Intelligence
EU Green Deal agricultural standards are restructuring demand toward sustainably cultivated paprika varieties across European food manufacturing. Kalsec Inc. leverages its vertical integration from seed to extract to secure consistent oleoresin supply chains. Synthite Industries Ltd. anchors South Asian production capacity with specialized solvent extraction infrastructure. Chr. Hansen Holding A/S differentiates through fermentation-derived color stabilization technologies that reduce thermal degradation in processed foods.
Paprika comprises dried and ground fruit of Capsicum annuum cultivars, typically exhibiting 100–240 ASTA color units for commercial grading and 30–100 Scoville heat units depending on cultivar selection. The powder functions primarily as a natural colorant and flavoring agent in processed proteins, snack coatings, and emulsified sauces. Sweet paprika dominates bulk commodity trade while smoked paprika captures expanding margin pools in premium retail and foodservice channels. Meat processing applications sustain the largest volume absorption among end-use segments, though snack flavoring exhibits the fastest structural growth as extruded and coated products proliferate in emerging markets. Sachet packaging for food manufacturers is displacing bulk bags in mid-scale processing operations seeking inventory flexibility and reduced contamination risk.
FDA color additive regulations govern paprika oleoresin deployment in US food products, while EFSA purity specifications and CE marking requirements shape import access into European Union markets. India's FSSAI labeling mandates for natural versus synthetic colorants are tightening disclosure standards for spice traders and flavoring companies. Stakeholders must monitor evolving maximum residue limits for aflatoxin and pesticide metabolites across multiple jurisdictions to sustain market access and avoid supply disruption.
Market Dynamics
Clean-label mandates across North American and European retail channels are restructuring procurement specifications for paprika suppliers, forcing processors to document cultivar origin and extraction methods while certifying aflatoxin compliance under tightening residue limits.
Growth Catalysts
- EU Green Deal agricultural standards:The framework's sustainable farming incentives are redirecting cultivation subsidies toward integrated pest management and soil health protocols in paprika-producing regions.
- Extruded snack manufacturing:Rapid expansion of coated and puffed product lines across emerging markets is absorbing oleoresin volumes for uniform color dispersion in high-temperature processing.
- Smoked paprika premiumization:Controlled-designation origin products from Spain's Extremadura region command sustained price premiums as foodservice operators differentiate menu offerings through provenance marketing.
Market Restraints
- Capsicum input volatility:Weather-driven yield fluctuations in major growing belts create raw material cost instability that compresses processor margins during contract renewal cycles.
- EFSA purity specifications:Stringent maximum residue limits for pesticide metabolites and aflatoxin B1 create non-tariff barriers that delay import clearance and increase testing expenditure.
- Annatto and turmeric substitution:Lower-cost natural colorants with comparable heat stability are displacing paprika oleoresin in price-sensitive sauce and dairy applications.
Strategic Opportunities
- India's FSSAI disclosure mandates:Tightening natural versus synthetic colorant labeling requirements create first-mover advantage for suppliers with certified traceability systems.
- Fermentation-derived stabilization:Convergence of precision fermentation with traditional oleoresin extraction is opening pathways to thermal degradation resistance in UHT-processed foods.
- Sachet packaging for mid-scale processors:Inventory-flexible unit formats are capturing share from bulk bags among regional meat processors seeking contamination risk reduction.
Industry Challenges
- ASTA color unit calibration expertise:Scarcity of technicians proficient in standardized color measurement protocols creates quality control bottlenecks at regional processing facilities.
- Dual certification timelines:Simultaneous pursuit of FDA color additive compliance and CE marking for EU market access extends product launch cycles by 8-14 months.
- Legacy solvent extraction infrastructure:Capital-intensive retooling for supercritical CO2 systems strains mid-tier processors lacking access to green financing instruments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paprika Market |
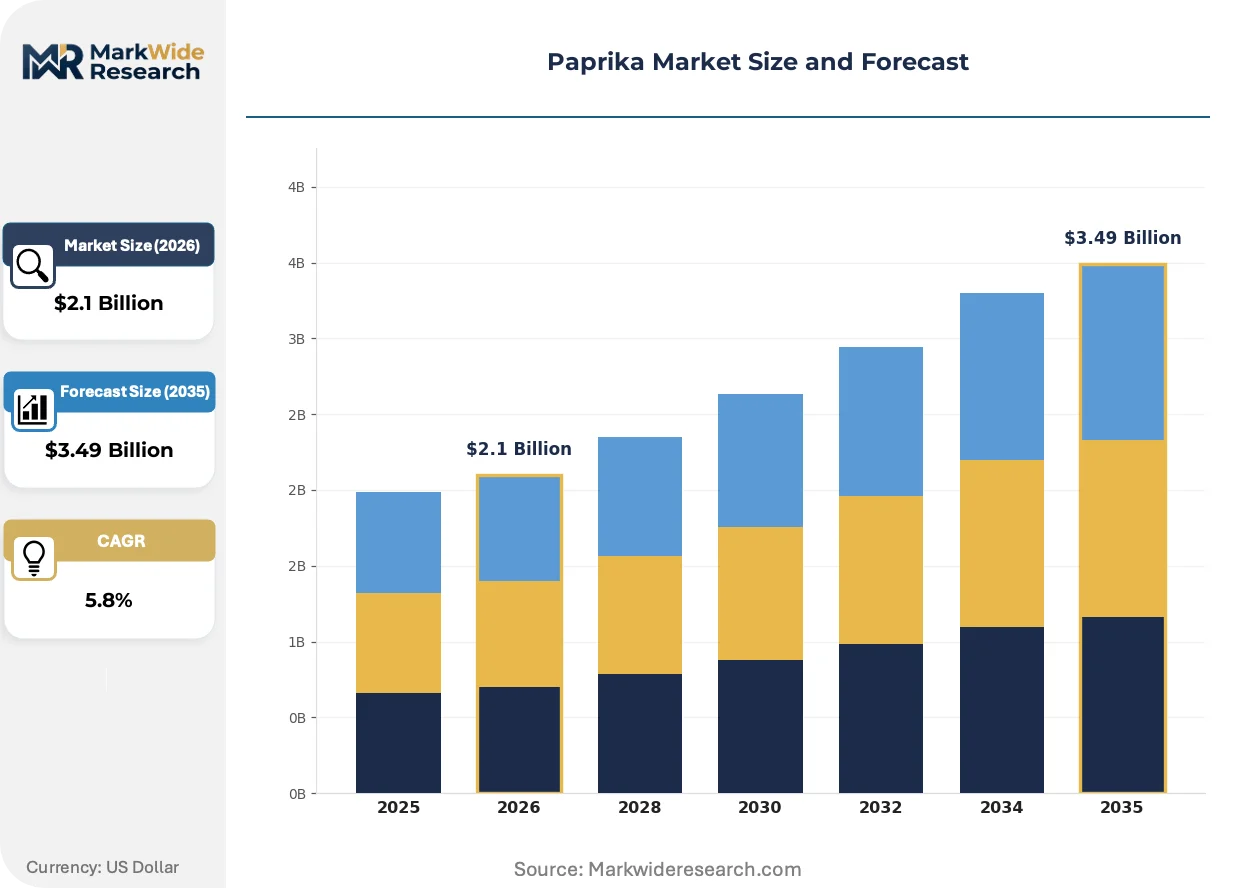
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Paprika, Hot Paprika, Smoked Paprika, Hungarian Paprika, Spanish Paprika Application: Food Seasoning, Meat Processing, Snack Flavoring, Sauce Ingredient, Beverage Additive Packaging Type: Bulk Bags, Sachets, Glass Jars, Plastic Containers, Cardboard Boxes End User: Food Manufacturers, Spice Traders, Catering Services, Specialty Retailers, Flavoring Companies |
| Companies Covered | Kalsec Inc., Naturex S.A., Chr. Hansen Holding A/S, Extractos Vegetales SA (EVESA), Universal Oleoresins, Synthite Industries Ltd., DDW The Color House, Givaudan, Plant Lipids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paprika Market Strategic Shifts & Innovations
Processing technology and procurement specifications are advancing in parallel as buyers demand verified provenance and functional performance beyond basic color units. Suppliers are repositioning around extraction method transparency and application-specific formulation capabilities.
Supercritical CO2 extraction technology is converging with traditional solvent-based oleoresin production as premium food manufacturers seek residual-solvent-free certifications for clean-label positioning. Organic and natural-product processors in Germany and the Netherlands are adopting these systems at accelerated replacement cycles. The technology is compressing acceptable purity thresholds across the supplier base as certification bodies harmonize testing protocols.
CE marking requirements under evolving EU food contact material regulations are reshaping import documentation burdens for non-European oleoresin suppliers. The industrial consequence is consolidation of customs brokerage relationships around specialized agricultural trade expertise. Spanish and Hungarian processors with established EU regulatory affairs capabilities are capturing expanded toll-processing contracts from Asian-origin raw material suppliers.
Food manufacturers are unbundling colorant procurement from bundled spice blends to secure direct supplier relationships with documented cultivar traceability. Mid-scale meat processors in Poland and Romania are displacing traditional trader intermediaries with contracted oleoresin supply agreements. The shift is most visible in sausage and cured meat verticals where retail private-label specifications now mandate single-origin paprika documentation.
Paprika Market Segmentation
Paprika procurement specifications diverge sharply across end-use applications, with thermal stability requirements and color unit thresholds driving distinct product selections. Understanding segment boundaries enables suppliers to align extraction methods and cultivar sourcing with buyer technical mandates.
Product Type:
Upgrade cycles in paprika procurement center on color unit consistency and provenance documentation as clean-label mandates intensify across retail channels.
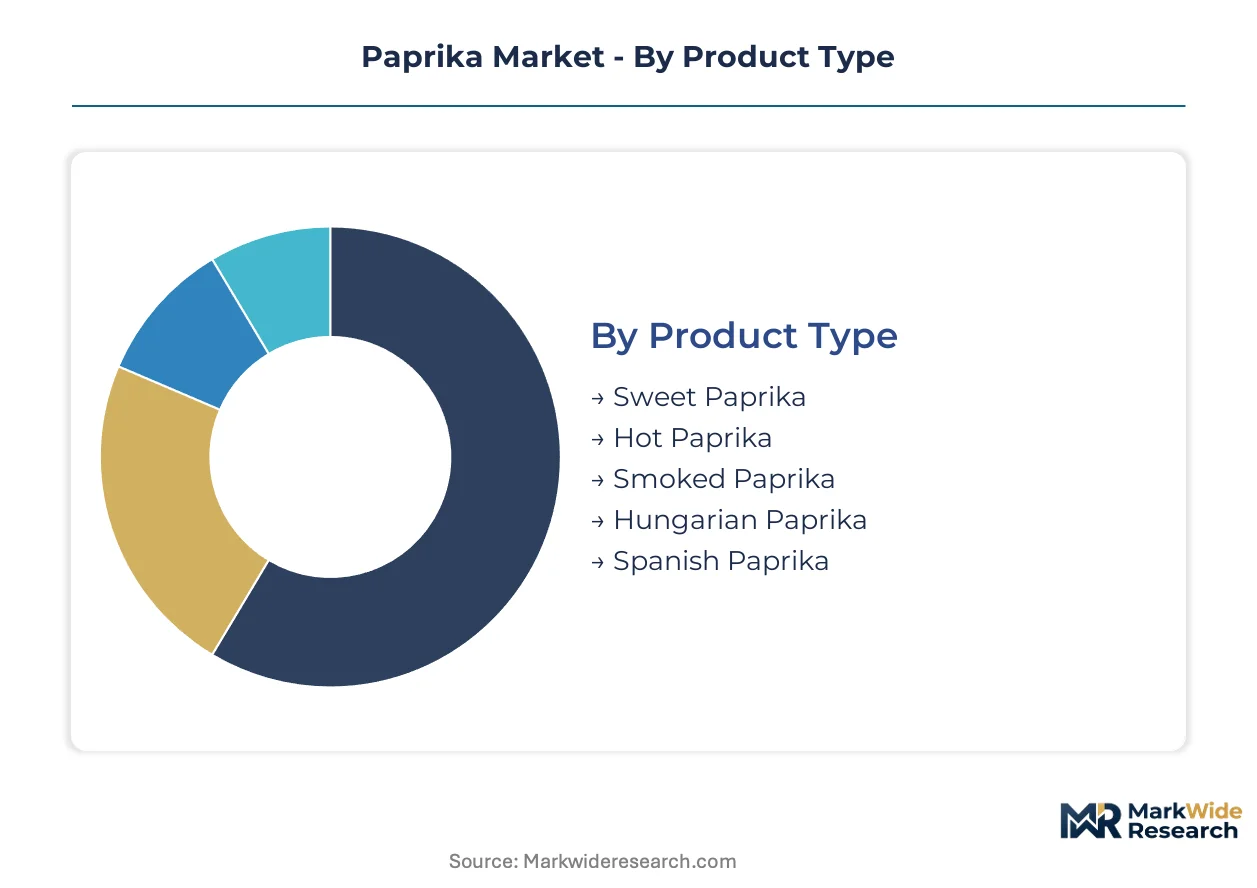
- Sweet Paprika:Exhibits 100–140 ASTA color units with negligible Scoville heat, making it the default choice for dairy applications and mild sauce formulations where color dominates flavor. Bulk commodity absorption concentrates in German and Dutch meat processing facilities seeking cost-efficient colorant coverage for emulsified products.
- Smoked Paprika:Oak-fired drying in Spain's Extremadura region imparts distinctive phenolic compounds that command sustained price premiums. Foodservice operators in Madrid and Barcelona leverage controlled-designation origin documentation to differentiate menu offerings through provenance storytelling.
- Hot Paprika:500–1,000 Scoville heat units suit ethnic cuisine formulations and heat-forward snack coatings.
- Hungarian Paprika:Protected geographical indication status restricts cultivar sourcing to Szeged and Kalocsa growing belts.
- Spanish Paprika:Murcia region production dominates export volumes through established EU regulatory compliance infrastructure.
Sweet Paprika sits at the top of the volume ranking, with Smoked Paprika climbing the fastest.
Application:
Application selection maps directly to processing temperature exposure and shelf-life requirements, with high-heat segments demanding oleoresin forms over ground powder.
- Meat Processing:Sausage and cured meat applications sustain the largest volume absorption, with Poland and Romania processors displacing trader intermediaries through direct oleoresin contracts. Retail private-label specifications now mandate single-origin paprika documentation for premium product lines.
- Snack Flavoring:Extruded and coated product proliferation across emerging markets absorbs oleoresin volumes for uniform color dispersion in high-temperature processing. India and Brazil snack manufacturers exhibit steepest expansion trajectory as puffed product categories penetrate lower-tier cities.
- Food Seasoning:Blend manufacturers prioritize ASTA consistency over provenance for commodity positioning.
- Sauce Ingredient:Tomato-based formulations in Italy and Portugal specify paprika for depth enhancement.
- Beverage Additive:Limited deployment in fermented drink coloration, primarily Eastern European traditional products.
Meat Processing commands current volume leadership, while Snack Flavoring gains share fastest.
Packaging Type:
Packaging selection reflects inventory velocity and contamination risk tolerance, with mid-scale processors accelerating format transitions.
- Sachets:Unit-dose formats capture share from bulk bags among regional meat processors seeking inventory flexibility and reduced cross-contamination exposure. Polish mid-tier sausage manufacturers lead adoption, citing lot traceability improvements under FSSC 22000 certification requirements.
- Bulk Bags:25kg woven polypropylene remains standard for high-volume spice traders and industrial flavoring companies with dedicated silo infrastructure.
- Glass Jars:Retail premium positioning in specialty channels favors this format for Hungarian and Spanish origin products.
- Plastic Containers:Foodservice portion-control applications in catering verticals specify resealable formats.
- Cardboard Boxes:E-commerce direct-to-consumer shipments increasingly specify this format for sustainability signaling.
Bulk Bags retain volume dominance, with Sachets expanding most quickly among mid-scale processors.
End User:
End-user procurement sophistication varies sharply, with integrated manufacturers demanding cultivar traceability that trader intermediaries cannot provide.
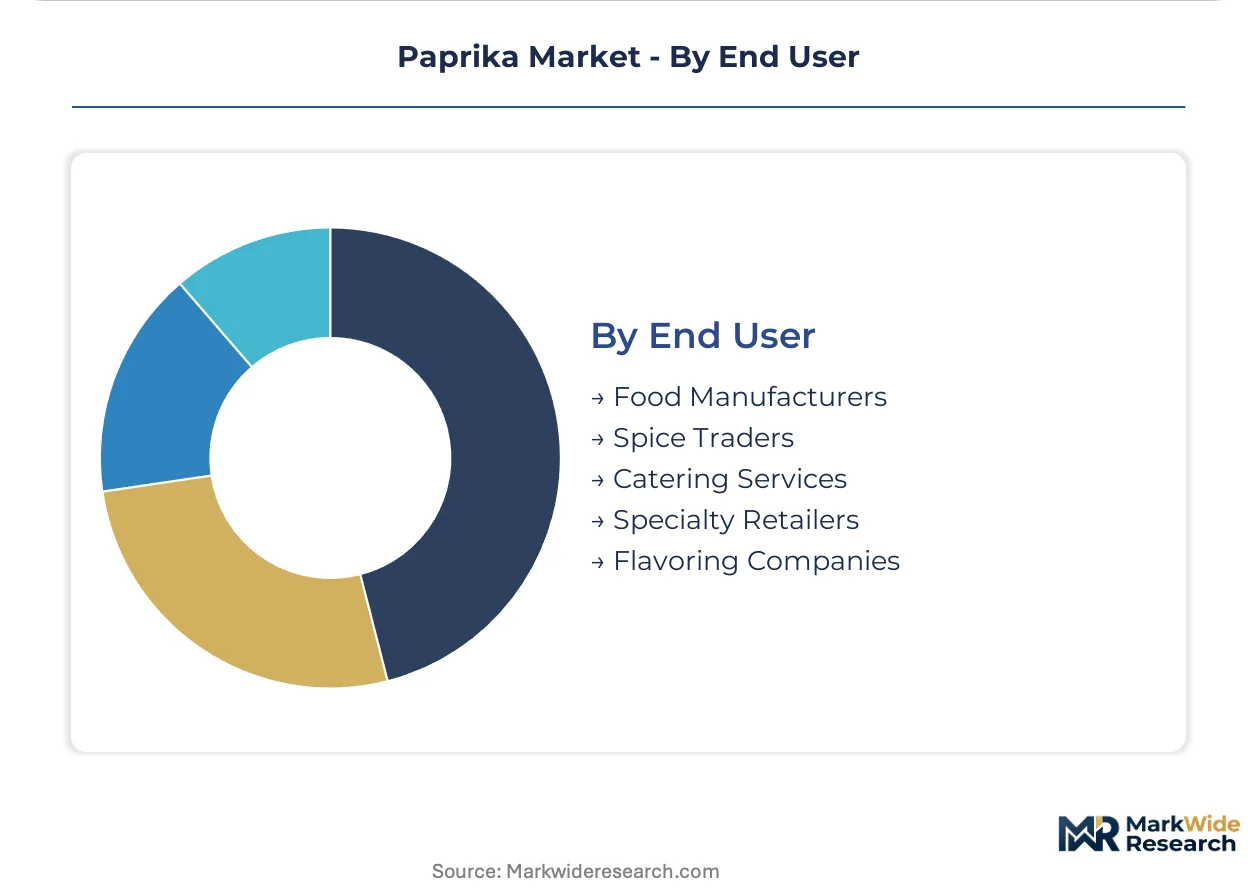
- Food Manufacturers:Unbundling colorant procurement from bundled spice blends to secure direct supplier relationships with documented extraction method transparency. German organic processors specify supercritical CO2 oleoresin for residual-solvent-free certifications.
- Spice Traders:Traditional intermediary role compressing as mid-scale processors establish direct oleoresin contracts, particularly in Romanian and Bulgarian markets.
- Catering Services:Smoked paprika premiumization drives menu differentiation in Madrid and Barcelona foodservice clusters.
- Specialty Retailers:Controlled-designation origin products command shelf space in premium urban outlets.
- Flavoring Companies:Solvent extraction infrastructure investments concentrate in South Asian production hubs.
Food Manufacturers represent the largest procurement volume, with Catering Services showing steepest growth in premium segment absorption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paprika cultivation and processing trace their industrial lineage to sixteenth-century Spanish monastic gardens, where Capsicum annuum varieties from the New World were first systematically dried and ground for European trade. This Iberian foundation established quality protocols that persist in modern controlled-designation origin frameworks.
Spain
Extremadura's De la Vera and Murcia region production anchors European premium supply, with oak-fired drying infrastructure concentrated around Cáceres and Jaraíz de la Vera. EU Green Deal agricultural standards redirect cultivation subsidies toward integrated pest management protocols in these traditional growing belts. Murcia-based processors leverage established CE marking compliance infrastructure to capture toll-processing contracts from Asian-origin raw material suppliers.
India
Guntur and Warangal districts in Andhra Pradesh concentrate solvent extraction capacity for oleoresin production, supplying volume to emerging market snack manufacturers. FSSAI labeling mandates for natural versus synthetic colorant disclosure tighten compliance burdens for spice traders operating through Mumbai and Chennai port corridors. Synthite Industries Ltd. anchors South Asian production with specialized extraction infrastructure in Kerala's Kochi industrial cluster.
United States
California's Central Valley and New Mexico's Hatch Valley sustain domestic cultivation for food manufacturing applications, though processors rely heavily on imported oleoresin for cost-competitive positioning. FDA color additive regulations govern deployment specifications in meat processing facilities concentrated around Chicago and Kansas City. Kalsec Inc. leverages Michigan-based vertical integration from seed breeding to extract refining for consistent supply chain security.
Hungary
Szeged and Kalocsa growing belts operate under protected geographical indication status that restricts cultivar sourcing to traditional Capsicum annuum landraces. EFSA purity specifications for aflatoxin B1 maximum residue limits create testing expenditure burdens for processors exporting into German and Dutch retail channels. Budapest-based traders increasingly displace traditional intermediaries as Polish and Romanian meat processors establish direct oleoresin procurement relationships.
Germany
Organic and natural-product processors in Hamburg and Cologne accelerate adoption cycles for supercritical CO2 extraction systems to secure residual-solvent-free certifications. German meat processing facilities in Lower Saxony absorb bulk commodity volumes of sweet paprika for emulsified product coloration. REACH compliance infrastructure and ECHA registration protocols shape import documentation requirements for non-European oleoresin suppliers seeking northern European market access.
Paprika Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the paprika value chain, with integrated cultivator-processors maintaining captive raw material access while specialized extractors focus on application-specific formulation capabilities. The supplier base fragments across three functional tiers: seed-to-extract integrated operators, toll-processing specialists with regulatory compliance infrastructure, and regional traders facing margin compression from direct procurement trends. Dominant competitive moves center on backward integration into controlled-designation origin cultivation zones and supercritical CO2 capacity expansion for clean-label certification positioning.
Within the integrated extraction tier, Kalsec Inc. and Synthite Industries Ltd. exemplify contrasting geographic anchoring strategies, with the former representing North American vertical integration and the latter exemplifying South Asian volume-scale infrastructure. Chr. Hansen Holding A/S occupies a distinct position bridging fermentation-derived stabilization technology with traditional oleoresin applications. Among European toll-processing specialists, Extractos Vegetales SA anchors Iberian regulatory compliance capabilities for non-EU raw material suppliers.
| Leading Market Players |
|---|
| Kalsec Inc. |
| Naturex S.A. |
| Chr. Hansen Holding A/S |
| Extractos Vegetales SA (EVESA) |
| Universal Oleoresins |
| Synthite Industries Ltd. |
| DDW The Color House |
| Givaudan |
| Plant Lipids |
| Others |
Cost & Logistics Intelligence
Capsicum annuum spot prices in Guntur and Murcia trading corridors cascade through three distinct pricing tiers as extraction method and provenance documentation stratify buyer willingness-to-pay. Clean-label certification premiums for supercritical CO2 oleoresin now command spreads over solvent-extracted alternatives that compress mid-tier processor margins during contract renegotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates controlled-designation origin Spanish paprika from commodity-grade Indian oleoresin and unbranded bulk powder. Price differentiation rests on extraction method transparency and ASTA color unit consistency, with EFSA aflatoxin certification adding measurable premiums. Cost compression in the standard tier is intensifying because annatto and turmeric substitution erodes paprika's cost-position in sauce applications. Regional meat processors in Poland exhibit highest price sensitivity, while German organic food manufacturers show lowest elasticity for residual-solvent-free certifications.
Supply Chain Analysis
Freight cost volatility between Andhra Pradesh and European port corridors is reshaping procurement geography as toll-processing contracts migrate toward Spanish and Hungarian regulatory compliance hubs. Raw material supply concentrates in India, Spain, and Hungary, with oleoresin extraction capacity drawing from Guntur, Murcia, and Szeged cultivation belts. Supply chain risk centers on single-source vulnerability for oak-fired drying infrastructure in Extremadura's De la Vera region. Distribution runs through specialized agricultural trade brokers with CE marking expertise, though direct contracting between processors and food manufacturers is accelerating disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paprika procurement is becoming a margin-expansion story as supercritical CO2 extraction premiums widen and sachet packaging reduces working capital intensity for mid-scale processors.
For Market Incumbents: Extend backward integration into controlled-designation origin cultivation zones in Extremadura and Szeged to secure captive raw material access against emerging South Asian volume competitors. Invest in dual FDA-EFSA certification infrastructure to compress product launch cycles by 6-10 months. Prioritize fermentation-derived stabilization R&D partnerships to differentiate against annatto substitution in UHT dairy applications. For New Entrants and Emerging Players: Enter via India's FSSAI disclosure mandate compliance as a white-space anchor, positioning certified traceability systems for first-mover advantage among Mumbai and Chennai spice traders. Target mid-scale Polish and Romanian meat processors seeking sachet-format inventory flexibility. Pursue toll-processing contracts with Asian-origin raw material suppliers lacking EU regulatory affairs capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with supercritical CO2 extraction specialists with established organic certification pathways and captive cultivar relationships. Long-term viability favors operators with demonstrated EFSA aflatoxin compliance infrastructure and direct food manufacturer contracting relationships. Watch for inflection when CE marking documentation burdens trigger consolidation of customs brokerage relationships around Iberian toll-processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Designation Origin Zones | Secures cultivar traceability for EU Green Deal compliance and premium positioning. |
| Supercritical CO2 Capacity Expansion | Captures clean-label premiums from German and Dutch organic food manufacturers. |
| Fermentation-Derived Stabilization Partnership | Opens thermal degradation resistance pathways in UHT-processed food segments. |
| Sachet Packaging Format Adoption | Reduces contamination risk and improves lot traceability for FSSC 22000-certified processors. |
| Dual FDA-EFSA Certification Investment | Compresses product launch timelines and expands addressable market access. |
Research Approach
Multiple input streams — primary interviews with extraction plant managers, spice procurement leads at meat processors, and regulatory affairs directors at flavoring companies; secondary validation through FSSAI disclosure filings, EFSA purity specification updates, and customs trade data — were reconciled through bottom-up volume modeling and top-down value triangulation. Conversations with Hungarian and Spanish toll-processing operators, Indian solvent extraction infrastructure owners, and German organic food manufacturer technical buyers informed cultivation-to-extraction cost structure assumptions.
Data-stream reconciliation across product type, application, packaging format, and end-user segmentation dimensions shaped analytical framework construction throughout the projection horizon. CAGRs were derived from normalized historical absorption patterns and forward-looking procurement specification shifts, with particular weighting assigned to EU Green Deal subsidy restructuring and extruded snack manufacturing expansion trajectories in emerging markets.
Inputs from EFSA maximum residue limit databases and FDA color additive guidance documents were available through the study window; gaps in real-time aflatoxin testing cost structures and supercritical CO2 equipment replacement cycle data introduce uncertainty bands around processor margin forecasts. Stakeholders should weight assumptions against their own operating context and regional regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Asia-Pacific Prepared Mustard Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Frangipani Extract Market