
 Savory Flavor Blends Market | 2026-2036
Savory Flavor Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Savory Flavor Blends Market Analytics
The gap between premium artisanal blends and mass-market commodity formulations is shifting from a price distinction to a supply-chain capability divide. Symrise AG leverages its integrated taste-modulation platform to command premium positioning in European food manufacturing. Kerry Group plc anchors its volume leadership through captive savory extraction facilities across multiple continents. Givaudan differentiates via biotechnology-derived flavor precursors that reduce reliance on agricultural commodity volatility.
Savory flavor blends comprise complex mixtures of hydrolyzed proteins, yeast extracts, vegetable powders, and reaction flavors engineered to deliver umami depth, roasted notes, and mouthfeel enhancement in finished foods. These formulations typically undergo Maillard reaction processing or controlled enzymatic hydrolysis to achieve thermal stability and flavor specificity for industrial applications. Seasoning mixes occupy the largest revenue pool due to their ubiquity across snack foods and ready-meal applications, though marinades represent the fastest-expanding category as marinated protein demand accelerates in retail and foodservice channels. Meal kits within the application dimension concentrate margin capture because subscription-format buyers accept per-unit premiums that offset formulation complexity costs.
FDA oversight of Generally Recognized As Safe determinations and USDA labeling requirements shape permissible ingredient declarations and clean-label positioning for US-market blends, while EFSA and EU Flavouring Regulation 1334/2008 govern maximum usage levels and labeling transparency across European formulations. The EU Green Deal's farm-to-fork sustainability targets are additionally pressuring suppliers to document supply-chain carbon intensity and botanical sourcing ethics. Stakeholders must monitor regulatory divergence between jurisdictions while building formulation flexibility that accommodates both permissive and restrictive additive frameworks without duplicative product lines.
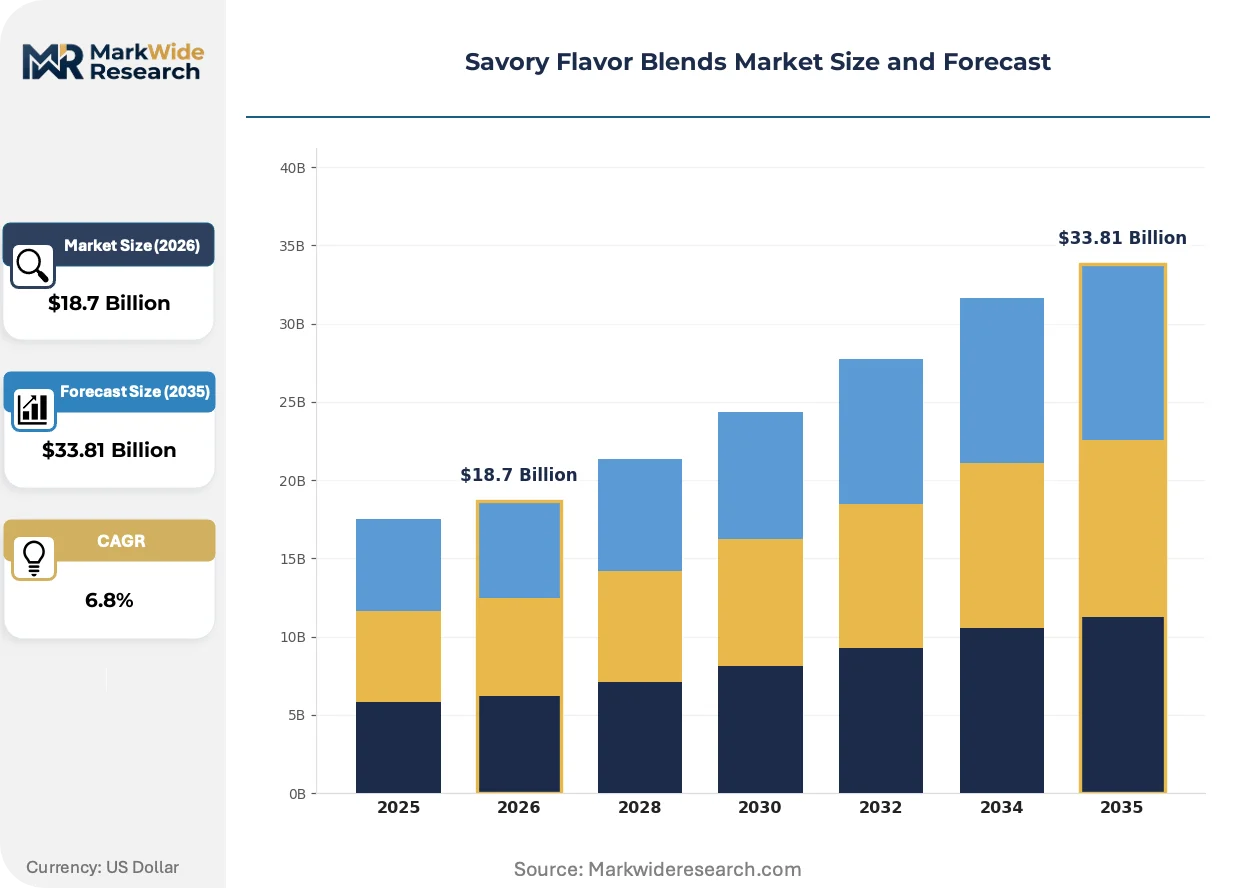
Market Dynamics
Clean-label mandates from EFSA and FDA are forcing savory blend suppliers to eliminate artificial enhancers while preserving umami intensity through natural precursors and fermentation-derived alternatives.
Growth Catalysts
- EU Flavouring Regulation 1334/2008:Maximum usage level caps for synthetic additives are accelerating investment in yeast extract and hydrolyzed vegetable protein platforms that deliver equivalent taste performance.
- Plant-based protein manufacturers:Meat alternative formulators in Germany and the Netherlands are expanding procurement of savory masking systems to neutralize off-notes from pea and soy isolates.
- Maillard reaction engineering:Advanced thermal processing control systems are enabling precise roasted note replication without caramel color additives, satisfying clean-label requirements in premium snack applications.
Market Restraints
- Vanilla and spice commodity volatility:Climate-driven supply disruptions in Madagascar and Indonesia are compressing margins for blenders dependent on natural botanical extracts as flavor carriers.
- Enzymatic hydrolysis capacity concentration:Captive extraction facilities controlled by three integrated multinationals limit tolling access for mid-tier compounders seeking reaction flavor production.
- Reaction flavor thermal stability ceiling:Current Maillard-derived formulations degrade above 180°C, restricting deployment in high-temperature extruded snack applications where synthetic alternatives still dominate.
Strategic Opportunities
- India convenience food penetration:Frozen ready-meal and instant noodle manufacturers in Maharashtra and Karnataka are under-supplied with localized savory profiles adapted to regional masala preferences.
- EU Green Deal farm-to-fork traceability:Carbon intensity documentation requirements are creating premium positioning for suppliers with verified sustainable botanical sourcing and regenerative agriculture partnerships.
- Biotechnology-fermentation convergence:Precision-fermented savory peptides combined with AI-guided flavor optimization are enabling novel umami precursors that bypass agricultural commodity exposure entirely.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in reaction kinetics and natural extract standardization is concentrating at established firms, constraining formulation capabilities at emerging regional blenders.
- GRAS self-determination timeline:FDA notification pathways for novel fermentation-derived ingredients are extending 18-24 months, delaying product launches and freezing R&D capital in regulatory limbo.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savory Flavor Blends Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seasoning Mixes, Marinades, Sauces, Gravy Application: Food Processing, Snack Foods, Condiments, Meal Kits Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors Customer Type: Food Manufacturers, Restaurants, Catering Services, Home Chefs |
| Companies Covered | Symega, Synergy Flavors, Symrise AG, Kanegrade, Givaudan, AngelYeast Co. Ltd., Kerry Group plc, Takasago International Corporation, Firmenich SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savory Flavor Blends Market Evolving Landscape
Biotechnology-derived savory platforms are compressing the traditional agricultural supply chain, while regulatory transparency mandates and shifting procurement authority are restructuring how flavor value is captured and distributed.
Precision fermentation of savory peptides is rewriting competitive boundaries between natural extract suppliers and synthetic compounders. Snack food manufacturers in the United States are piloting these bio-identical umami molecules at commercial scale. The technology is compressing cost structures for premium clean-label positioning while displacing volume-dependent agricultural sourcing strategies.
EU Green Deal carbon accounting requirements are mandating supply-chain documentation from farm to finished flavor. EFSA enforcement of botanical sourcing ethics is compelling blenders to audit extraction partners across multiple continents. Seasoning mix suppliers serving European retail channels are restructuring supplier qualification protocols to satisfy emerging due diligence obligations.
Direct procurement relationships between protein processors and flavor houses are disintermediating traditional distribution channels. Marinated meat and plant-alternative manufacturers are consolidating specification authority in-house, bypassing ingredient distributors for complex custom blend development. This concentration is most visible in the United States, where Tyson Foods and Beyond Meat have established captive flavor innovation partnerships.
Savory Flavor Blends Market Segmentation
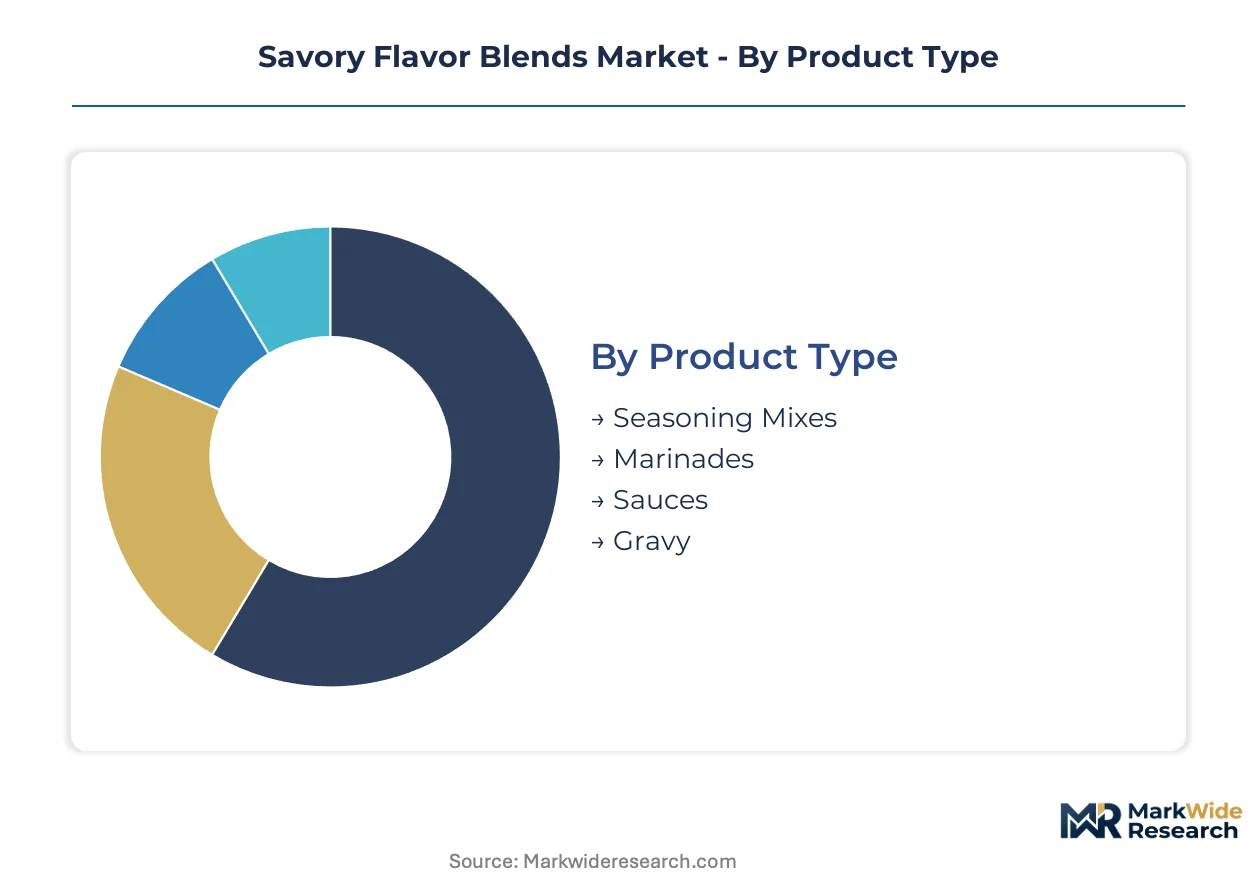
Savory flavor blend procurement patterns diverge sharply across customer scale and application complexity. Mass-market manufacturers prioritize thermal stability and cost predictability, while premium channels demand traceable botanical provenance and fermentation-derived clean-label credentials.
Product Type:
Supply concentration among integrated multinationals favors high-volume seasoning platforms over specialized reaction flavor systems.
- Seasoning Mixes:Complex blends of hydrolyzed proteins, yeast extracts, and vegetable powders engineered for umami depth across snack and ready-meal applications. Demand concentrates in United States and China where convenience food penetration drives bulk procurement contracts with thermal stability specifications.
- Marinades:Liquid or paste formulations combining acidulants, savory reaction flavors, and masking systems for protein applications. Retail and foodservice channels in Germany and the Netherlands are expanding marinated protein offerings, accelerating procurement of clean-label alternatives to synthetic tenderizers.
- Sauces:Viscous savory preparations requiring emulsion stability and pasteurization tolerance for industrial and foodservice deployment.
- Gravy:Starch-thickened savory systems optimized for reconstitution performance in institutional and retail channels.
Seasoning mixes absorb the bulk of installed capacity; marinades are expanding most quickly.
Application:
Cost tier stratification separates commodity flavor procurement from premium formulation partnerships.
- Food Processing:Large-scale savory blend integration into processed meat, plant-based alternatives, and prepared meals requiring batch-to-batch consistency and regulatory documentation. Manufacturers in Maharashtra and Karnataka are under-supplied with localized profiles, creating procurement gaps for regional masala adaptations.
- Meal Kits:Subscription-format savory components with per-unit premiums offsetting complex formulation costs. Direct partnerships between kit providers and flavor houses are disintermediating traditional distribution in United States and United Kingdom markets.
- Snack Foods:Thermal-stability-critical applications including extruded and baked savory coatings.
- Condiments:Table-ready savory preparations with extended shelf-life requirements for retail placement.
Food processing commands the largest procurement volumes; meal kits are gaining share fastest.
Distribution Channel:
Volume flows through distributor networks while premium positioning shifts toward direct manufacturer relationships.
- Distributors:Traditional intermediaries consolidating fragmented demand from mid-tier food manufacturers and regional processors. Procurement authority is concentrating as Tyson Foods and Beyond Meat establish captive flavor innovation partnerships, bypassing these channels for complex custom development.
- Online Retail:Direct-to-channel fulfillment enabling specialty and clean-label blend access for smaller manufacturers and foodservice operators. Growth concentrates in United States and United Kingdom where procurement digitization accelerates.
- Supermarkets:Mass-market retail placement for standardized seasoning and sauce formulations.
- Specialty Stores:Curated channels for artisanal and provenance-verified savory blends.
Distributors retain the deepest penetration; online retail is climbing the fastest.
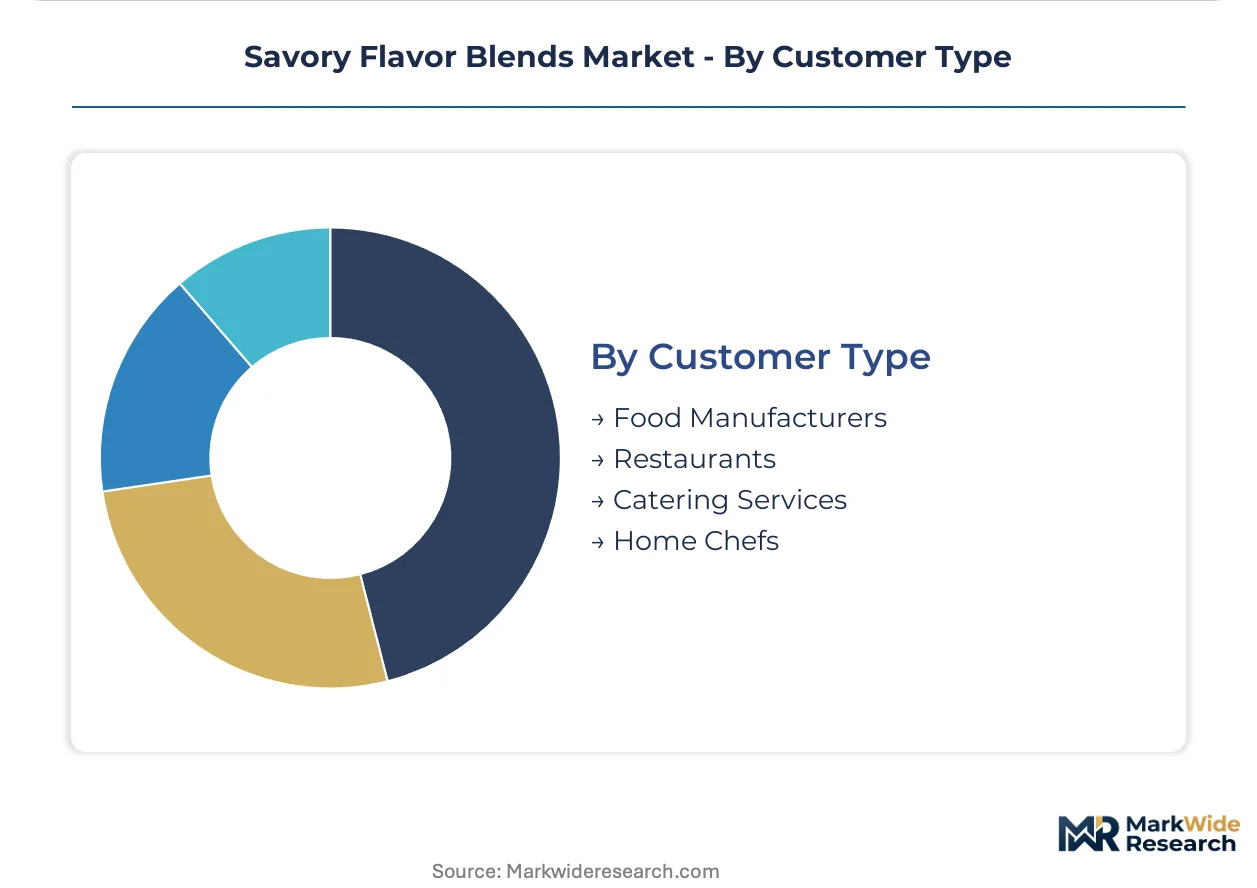
Customer Type:
Application maturity separates specification-heavy manufacturing partnerships from transactional foodservice supply.
- Food Manufacturers:Integrated savory blend development spanning reaction flavor engineering, regulatory compliance, and supply-chain documentation. EFSA and FDA clean-label mandates are forcing elimination of artificial enhancers while preserving umami intensity through natural precursors.
- Restaurants:Foodservice operators consolidating procurement of customized savory systems for menu differentiation. Chains in United States and Germany are building direct flavor house relationships to secure proprietary profiles.
- Catering Services:Volume-driven procurement prioritizing cost efficiency and preparation simplicity.
- Home Chefs:Retail-oriented demand for convenience-oriented seasoning and sauce solutions.
Food manufacturers represent the most sophisticated demand; restaurants are deepening flavor partnerships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American savory blend procurement through its concentration of protein processors and flavor innovation partnerships. The metropolitan corridor hosts direct manufacturer relationships that bypass traditional distribution channels for marinated meat and plant-alternative applications.
United States
Frozen ready-meal and instant noodle manufacturers drive procurement volumes across the Midwest and Southeast. FDA GRAS determinations and USDA labeling requirements shape permissible ingredient declarations for clean-label positioning. Chicago and Dallas-Fort Worth concentrate captive flavor innovation partnerships with Tyson Foods and Beyond Meat establishing direct specifications.
Germany
Meat alternative formulators in Berlin and Hamburg expand procurement of savory masking systems for pea and soy protein applications. EFSA enforcement of EU Flavouring Regulation 1334/2008 governs maximum usage levels for synthetic additives. The Bavarian industrial corridor hosts yeast extract and hydrolyzed vegetable protein platform investments delivering equivalent taste performance.
China
Convenience food penetration accelerates demand for localized savory profiles adapted to regional umami preferences. SAMR oversight of food additive standards and dual carbon goals pressure suppliers to document supply-chain sustainability. Shanghai and Guangzhou concentrate seasoning mix manufacturing for snack food and ready-meal bulk procurement contracts.
India
Frozen ready-meal and instant noodle manufacturers in Maharashtra and Karnataka face under-supply of regional masala-adapted savory profiles. FSSAI clean-label mandates force elimination of artificial enhancers while preserving intensity through natural precursors. Mumbai and Bangalore concentrate procurement digitization accelerating online retail channel growth for specialty blend access.
Netherlands
Plant-based protein manufacturers in Rotterdam and Eindhoven expand marinated protein offerings accelerating clean-label marinade procurement. EU Green Deal farm-to-fork traceability requirements create premium positioning for carbon-documented botanical sourcing. The Randstad region hosts regenerative agriculture partnerships satisfying emerging due diligence obligations.
Savory Flavor Blends Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the savory flavor blend market. Integrated multinationals with captive extraction facilities command volume leadership through thermal stability specifications and regulatory documentation capabilities. Three strategic archetypes dominate: biotechnology-fermentation specialists, integrated taste-modulation platforms, and regional compounders dependent on tolling access. Competitive moves concentrate on direct procurement relationships disintermediating distribution and precision-fermented umami peptide development bypassing agricultural commodity exposure.
Within the integrated multinational tier, Symrise AG, Kerry Group plc, and Givaudan exemplify divergent capability positioning. Symrise AG occupies a position emphasizing integrated taste-modulation platforms for European food manufacturing. Kerry Group plc anchors volume leadership through captive savory extraction facilities across multiple continents. Givaudan sits within biotechnology-derived flavor precursor development reducing reliance on agricultural commodity volatility.
| Leading Market Players |
|---|
| Symega |
| Synergy Flavors |
| Symrise AG |
| Kanegrade |
| Givaudan |
| AngelYeast Co. Ltd. |
| Kerry Group plc |
| Takasago International Corporation |
| Firmenich SA |
| Others |
Value Network & Pricing Analysis
Premium-commodity divergence in savory flavor blends separates fermentation-derived clean-label credentials from mass-market thermal stability specifications, with EU Flavouring Regulation 1334/2008 compliance costs concentrating pricing power among integrated multinationals while mid-tier compounders absorb margin compression from tolling access constraints.
Pricing Analysis
Yield-guaranteed performance anchors value-based pricing for precision-fermented savory peptides, with three-tier pricing structure across premium, standard, and economy levels differentiating by clean-label certification intensity and botanical traceability documentation. Price differentiation stems from EFSA audit compliance costs and volume scale commitments, with cost compression in commodity seasoning mixes intensifying due to captive extraction facility concentration. Small food manufacturers exhibit highest price sensitivity; meal kit subscription providers accept per-unit premiums for formulation complexity.
Supply Chain Analysis
Regional distribution centers in Germany, China, and India anchor hub-and-spoke fulfillment patterns for savory blend logistics, with raw material dependencies on Madagascar vanilla, Indonesian spice extracts, and yeast biomass from dedicated fermentation facilities. Single-source vulnerability concentrates in enzymatic hydrolysis capacity controlled by three integrated multinationals. Distribution runs through distributor networks for mid-tier manufacturers while direct procurement relationships disintermediate traditional channels for Tyson Foods and Beyond Meat scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal farm-to-fork traceability operates as a cost-of-compliance moat, with carbon intensity documentation requirements erecting barrier-to-entry walls that favor incumbent suppliers with verified sustainable botanical sourcing infrastructure over capital-constrained regional blenders.
For Market Incumbents: Deepen captive fermentation capacity in Bavaria and Maharashtra to secure enzymatic hydrolysis autonomy against tolling access bottlenecks. Expand direct procurement partnerships with plant-based protein manufacturers in Rotterdam and Eindhoven to lock in marinated protein flavor specifications before channel disintermediation accelerates. For New Entrants and Emerging Players: Direct-to-manufacturer digital platforms in Karnataka and Maharashtra offer lowest competitive density for regional masala-adapted savory profiles. Target frozen ready-meal manufacturers with localized umami formulations, leveraging FSSAI clean-label transition windows to establish formulation credibility before incumbent certification investments mature. For Investors and Strategic Acquirers: Re-rating potential sits with biotechnology-fermentation specialists given precision-fermented savory peptide commercialization timelines compressing agricultural commodity exposure. Long-term viability favors asset-light designers with AI-guided flavor optimization capabilities over volume-dependent extract suppliers. Monitor FDA GRAS notification pathway acceleration as inflection signal for fermentation-derived ingredient market access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Commercializes bio-identical umami peptides displacing Madagascar vanilla dependency for clean-label positioning. |
| Captive Extraction Facility Investment | Secures enzymatic hydrolysis autonomy in Bavaria reducing tolling vulnerability to Kerry Group and Symrise gatekeeping. |
| Direct Procurement Partnership | Disintermediates distributor channels for Tyson Foods and Beyond Meat marinated protein specification authority. |
| Carbon Documentation Compliance | Satisfies EU Green Deal farm-to-fork traceability mandating regenerative agriculture partnership verification. |
| Regional Masala Localization | Addresses under-supply in Maharashtra and Karnataka with FSSAI-compliant natural precursor formulations. |
Research Methodology
Multi-period observation of FDA GRAS notification timelines, EFSA enforcement patterns, and procurement digitization rates anchored the trend analysis, supplemented by interviews with flavor chemists, regulatory affairs directors at savory blend suppliers, procurement leads at protein processors, and sustainability officers at fermentation technology developers. Secondary validation drew from FDA GRAS filings, EFSA scientific opinions on flavoring substances, EU customs trade data for yeast extract imports, and SEC 10-K disclosures from integrated multinationals. Bottom-up segment sizing triangulated against top-down market value estimates.
Input-output matrix modeling connected Maillard reaction engineering capacity, precision fermentation yield curves, and clean-label certification penetration across product type, application, and customer type dimensions throughout the forecast period. CAGRs derived from regression analysis of historical procurement volume patterns and elasticity-adjusted price trajectories. Industry-specific inputs included enzymatic hydrolysis facility utilization rates and EU Flavouring Regulation 1334/2008 maximum usage level compliance cost curves.
The model holds under stable regulatory enforcement intensity and commodity supply continuity; deviation in Madagascar vanilla crop yields or FDA notification pathway delays would shift growth trajectories. Forecasts reflect documented assumption sets regarding biotechnology-fermentation convergence timelines and carbon accounting mandate implementation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Paprika Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Garlic Extract Market